
 Carbomer Market | 2026-2036
Carbomer Market Size, Share, and Industry Trends Forecast 2026-2036
Carbomer Market Analysis
Specialty chemical distribution networks serving personal care formulators is reconfiguring as regional distributors consolidate inventory positions around high-viscosity carbomer grades. The Lubrizol Corporation leverages its North American manufacturing footprint to sustain supply continuity for pharmaceutical-grade material. Evonik Industries AG anchors European demand through specialized emulsion-compatible carbomer lines. Sumitomo Seika Chemicals Co. Ltd. competes on technical service depth across Asia-Pacific cosmetic laboratories.
Carbomers constitute a family of high-molecular-weight cross-linked polyacrylic acid polymers neutralized with bases to form hydrophilic gels, typically exhibiting viscosity from 0.5 to 80 Pa·s depending on grade concentration and pH. These polymers function primarily as rheology modifiers, suspension agents, and controlled-release matrices across topical, oral, and industrial formulations. Carbomer 940 dominates personal care gel applications where optical clarity and stiff flow behavior command premium positioning. Carbomer 980 leads pharmaceutical tablet binding and transdermal systems due to broader compendial acceptance. Powder form generates the highest volume throughput, though gel and emulsion forms capture disproportionate margin in finished-dose pharmaceutical contracts.
FDA excipient guidelines and USP-NF monographs govern carbomer identity and purity thresholds for drug applications, while REACH registration and the EU Cosmetics Regulation impose full supply-chain disclosure on European-sourced material. China's NMPA and GB standards for pharmaceutical excipients are tightening import inspection protocols for carbomer viscosity and residual solvent content. Stakeholders must monitor divergent pharmacopeial harmonization timelines to avoid formulation requalification costs.
Market Dynamics
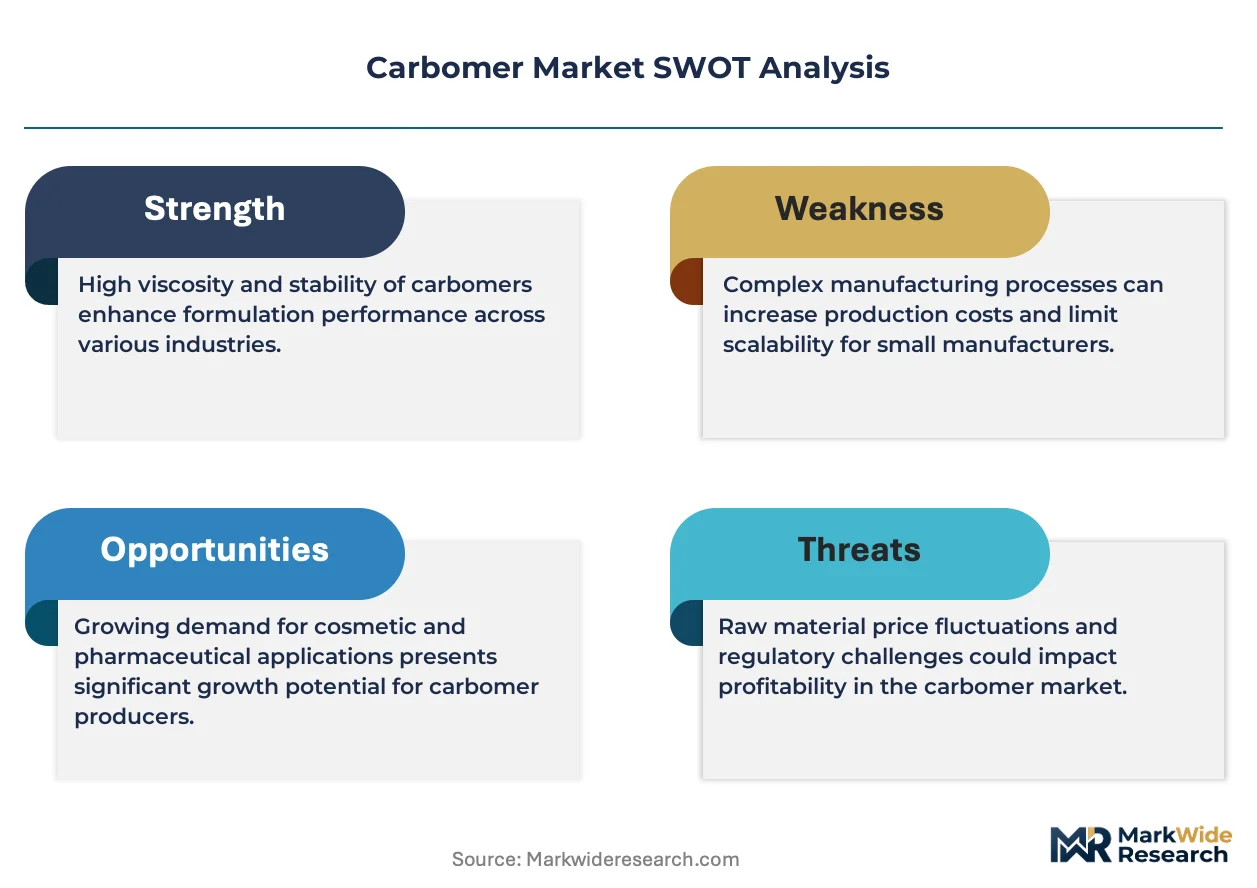
Pharmaceutical-grade carbomer supply is tightening as FDA and NMPA inspection protocols force reformulators to requalify excipient sources, compressing approved supplier lists and amplifying price premiums for compendial-certified material.
Growth Catalysts
- Controlled-release tablet demand:Oral solid dosage manufacturers are expanding carbomer matrices for modified-release formulations. USP-NF monograph compliance now serves as a gatekeeper for supplier selection.
- REACH substance registration:ECHA disclosure requirements for cross-linked polyacrylic acid polymers are filtering out non-compliant imports, consolidating volume with registered European producers.
- China's pharmaceutical localization:Domestic formulators are substituting imported carbomer with GB-standard certified local production to satisfy NMPA traceability mandates.
Market Restraints
- Acrylic acid feedstock volatility:Carbomer production costs fluctuate with propylene derivative pricing, squeezing margin on standard-grade material.
- Supplier concentration in North America:Pharmaceutical-grade capacity clusters with limited qualified manufacturers, creating single-source risk for validated formulations.
- Cellulosic substitute encroachment:Hydroxypropyl methylcellulose and ethylcellulose alternatives are capturing oral dosage share where viscosity tolerance permits.
Strategic Opportunities
- India's excipient import substitution:CDSCO tightening of pharmaceutical raw material sourcing rules creates opening for local carbomer manufacturing partnerships.
- Topical cannabis formulations:Transdermal gel applications for cannabinoid delivery are expanding addressable demand beyond traditional pharmaceutical and cosmetic segments.
- ISO 16128 natural origin certification:Carbomer derivatives meeting natural content thresholds command premium positioning in clean-label personal care lines.
Industry Challenges
- Residual solvent analytical capability:Formulators lack in-house testing infrastructure for benzene and other cross-linker quantification at pharmacopeial thresholds.
- Multi-compendial harmonization lag:Divergent USP-NF, Ph.Eur., and JP monograph update timelines force redundant qualification batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbomer Market |
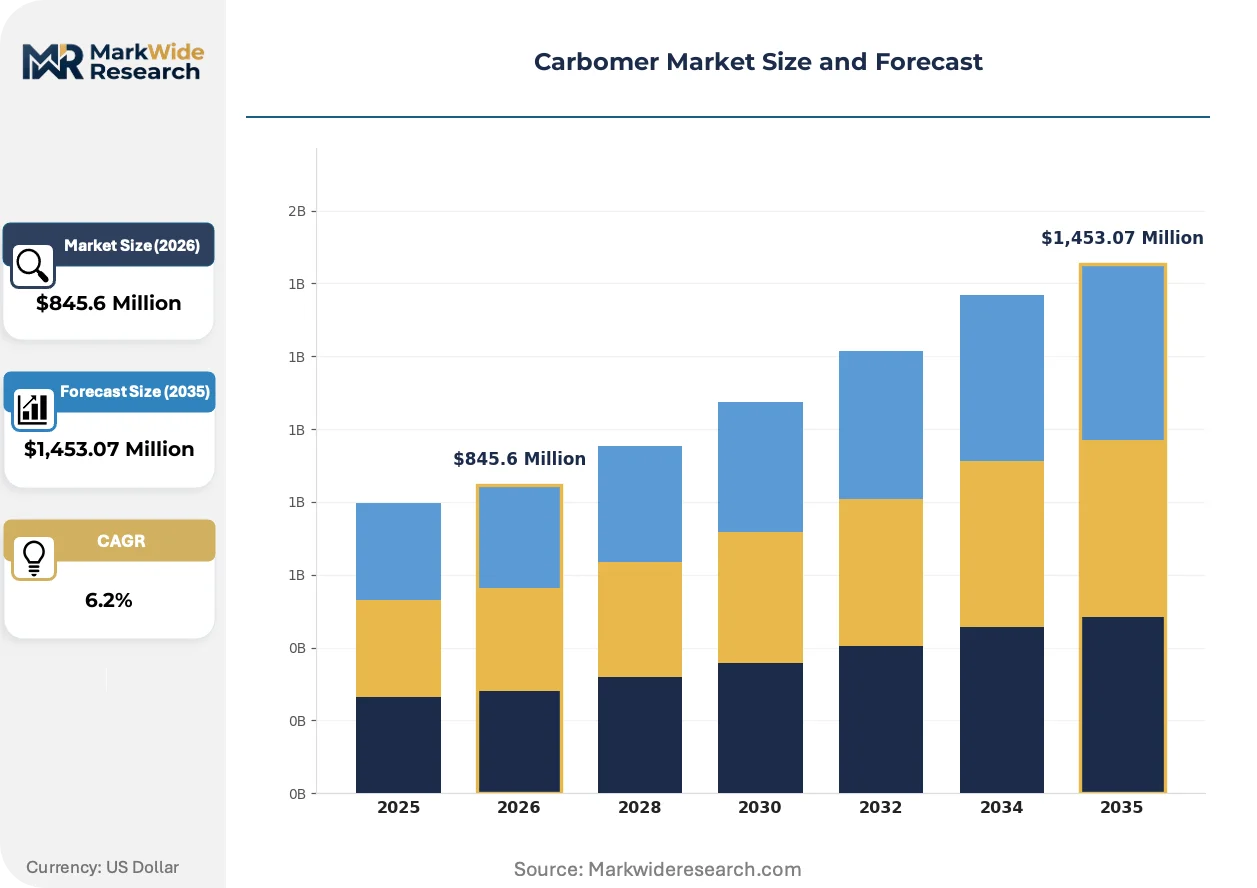
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,453.07 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbomer 940, Carbomer 980, Carbomer 1342, Carbomer 203 Application: Personal Care, Pharmaceuticals, Paints, Adhesives End User: Cosmetic Manufacturers, Pharmaceutical Companies, Industrial Coatings, Household Products Form: Powder, Gel, Emulsion, Solution |
| Companies Covered | Anhui Newman Fine Chemicals Co. Ltd., Sumitomo Seika Chemicals Co. Ltd., The Lubrizol Corporation, Maruti Chemicals, Tinci Materials, Evonik Industries AG, Ashland, Corel Pharma Chem, SNF Floerger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbomer Market Emerging Trajectories
Carbomer functionality is fragmenting into application-optimized grades as formulators reject one-size-fits-all rheology modifiers. Specialty polymer houses are engineering surface-treated and co-processed variants that collapse traditional viscosity-performance tradeoffs.
Self-wetting carbomer grades are collapsing hydration time requirements for high-throughput cosmetic manufacturing. Personal care compounders in South Korea and Japan are adopting these modified polymers to eliminate dusting and tank-fouling losses. The technology is compressing batch cycle times and reducing clean-in-place chemical consumption.
REACH Annex XIV authorization candidate listing for acrylic acid derivatives is forcing supply-chain re-documentation across European cosmetic and pharmaceutical formulators. ECHA's 2024-2026 substance evaluation work program prioritizes cross-linked polymer impurity profiles. German and French distributors are demanding extended safety data sheets from Asian carbomer exporters to preempt import blockages.
Direct procurement contracts between finished-dose manufacturers and carbomer producers are displacing traditional specialty chemical distribution in high-volume pharmaceutical applications. Multinational generic drug firms in India and China are negotiating multi-year supply agreements with polymer houses to lock viscosity specifications and residual solvent certificates. The shift concentrates volume with vertically integrated suppliers capable of batch-specific documentation.
Carbomer Market Segmentation
Carbomer specifications fragment across viscosity grades, compendial certifications, and hydration kinetics. Formulators select polymer architectures based on optical clarity requirements, ionic tolerance, and regulatory filing constraints rather than generic rheology performance.
Product Type:
Each carbomer grade occupies distinct positions across the formulation spectrum from stiff cosmetic gels to pharmaceutical controlled-release matrices.
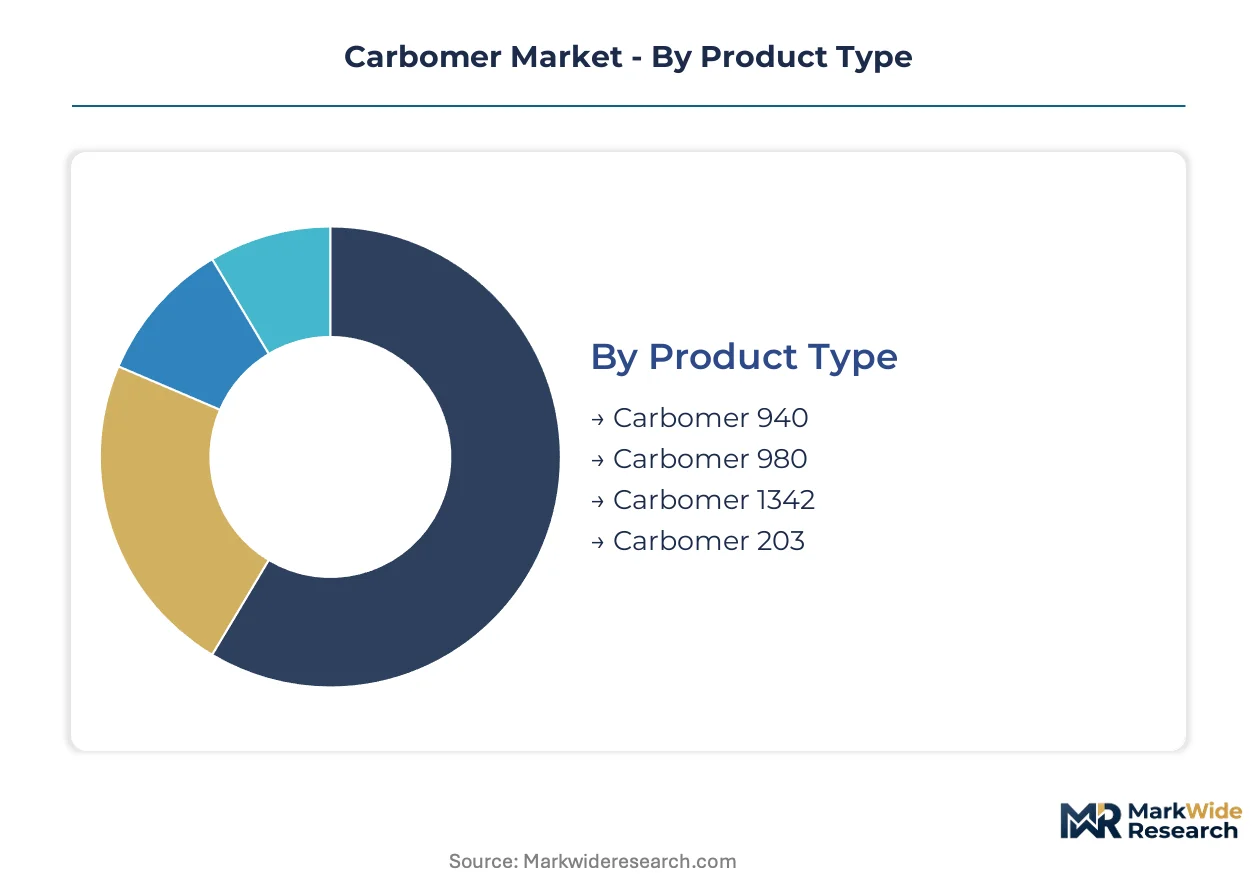
- Carbomer 940:Short-chain cross-linked polyacrylic acid polymer delivering the highest viscosity yield per unit concentration. Cosmetic gel manufacturers in South Korea specify this grade for transparent skincare formulations where stiff flow behavior and optical clarity command premium shelf positioning.
- Carbomer 980:Benzene-polymerized variant with broader pharmacopeial acceptance across USP-NF, Ph.Eur., and JP monographs. Oral solid dosage manufacturers in India are expanding procurement of this grade for tablet binding and transdermal patch matrices to satisfy CDSCO traceability mandates.
- Carbomer 1342:Acrylates/C10-30 alkyl acrylate cross-polymer engineered for electrolyte tolerance in surfactant-rich systems. Personal care compounders specify this grade for shampoo and body wash formulations where standard carbomers collapse.
- Carbomer 203:Lower viscosity polymer optimized for sprayable applications and industrial coatings requiring atomization without stringing.
The dominant share belongs to Carbomer 980, while Carbomer 1342 is closing the gap fastest.
Application:
End-use diversification reflects divergent purity thresholds and documentation requirements across consumer and regulated industries.
- Personal Care:Facial gels, moisturizers, and sunscreen formulations leverage carbomer suspending power and sensory modification. Chinese domestic cosmetic manufacturers are scaling local procurement to reduce import dependency.
- Pharmaceuticals:Controlled-release matrices, tablet binders, and transdermal delivery systems. FDA excipient guidelines and NMPA inspection protocols are compressing approved supplier lists for compendial-certified material.
- Paints:Rheology modification for waterborne architectural coatings. Industrial formulators prioritize sag resistance and spatter reduction over optical clarity.
- Adhesives:Pressure-sensitive and construction adhesive applications where tack and open time require precise viscosity control.
Personal Care retains volume leadership, though Pharmaceuticals generates the steepest margin expansion trajectory.
End User:
Customer archetypes separate by qualification burden, batch documentation requirements, and specification negotiation leverage.
- Cosmetic Manufacturers:High-volume compounders demanding rapid hydration kinetics and color consistency. South Korean and Japanese laboratories are adopting self-wetting grades to eliminate dusting losses.
- Pharmaceutical Companies:Finished-dose manufacturers requiring residual solvent certificates and multi-compendial compliance. Direct procurement contracts are displacing traditional distribution channels.
- Industrial Coatings:Paint and coating producers prioritizing cost efficiency over pharmacopeial certification.
- Household Products:Cleaners and disinfectants utilizing carbomer thickening for cling and vertical hold.
Cosmetic Manufacturers move the highest tonnage, while Pharmaceutical Companies are consolidating supply relationships fastest.
Form:
Physical presentation determines handling infrastructure, dust exposure, and batch cycle economics.
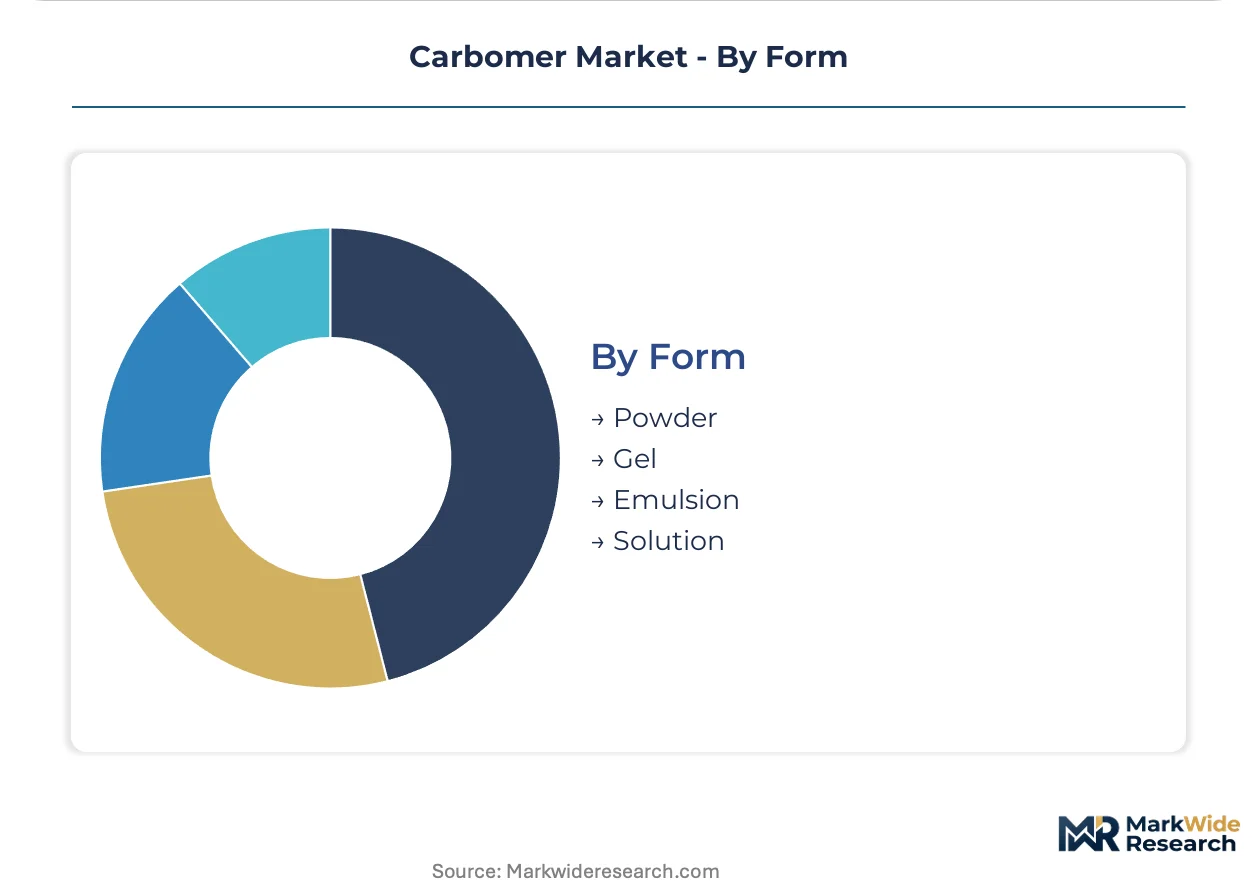
- Powder:Standard anhydrous polymer requiring high-shear dispersion and controlled dust management. Generates highest volume throughput across all end-use segments.
- Gel:Pre-neutralized aqueous dispersion eliminating hydration time. Captures disproportionate margin in finished-dose pharmaceutical contracts where batch consistency is paramount.
- Emulsion:Liquid dispersion form for high-throughput manufacturing lines with limited powder handling capability.
- Solution:Ready-to-use concentrate for small-batch formulators lacking dispersion equipment.
Powder dominates absolute volume, while Gel is expanding most quickly in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration requirements and NMPA traceability mandates are redrawing procurement patterns across pharmaceutical and cosmetic formulators. Domestic production incentives in China and India are accelerating localized carbomer manufacturing.
United States
FDA excipient guidelines are compressing approved supplier lists for pharmaceutical-grade material. USP-NF monograph compliance serves as a gatekeeper for oral solid dosage manufacturers. The New Jersey and Ohio pharmaceutical corridors are consolidating direct procurement contracts with polymer houses to lock viscosity specifications.
Germany
ECHA's 2024-2026 substance evaluation work program prioritizes cross-linked polymer impurity profiles. REACH Annex XIV authorization candidate listing is forcing supply-chain re-documentation across cosmetic formulators. The Rhine-Ruhr industrial cluster anchors European demand through specialized emulsion-compatible carbomer lines.
China
Domestic cosmetic manufacturers and pharmaceutical firms are scaling local carbomer procurement to reduce import dependency. NMPA inspection protocols for pharmaceutical excipients are tightening import inspection protocols for viscosity and residual solvent content. The Yangtze River Delta pharmaceutical manufacturing base is substituting imported material with GB-standard certified local production.
India
CDSCO tightening of pharmaceutical raw material sourcing rules is creating openings for local carbomer manufacturing partnerships. Oral solid dosage manufacturers are expanding procurement of compendial-certified grades for tablet binding. The Mumbai-Pune pharmaceutical belt is negotiating multi-year supply agreements to satisfy traceability mandates.
Japan
Personal care compounders are adopting self-wetting carbomer grades to eliminate dusting and tank-fouling losses. METI standards govern industrial chemical purity thresholds for cosmetic applications. Osaka-based cosmetic laboratories are compressing batch cycle times through modified polymer adoption.
Carbomer Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated polymer houses capable of batch-specific documentation. Three archetypes dominate: North American pharmaceutical-grade specialists, European REACH-registered producers, and Asia-Pacific technical service providers. Competitive moves concentrate on direct procurement contract capture and multi-compendial qualification acceleration.
Within the pharmaceutical-grade tier, The Lubrizol Corporation and Evonik Industries AG exemplify supply continuity strategies through regional manufacturing footprints. Among Asia-Pacific technical service providers, Sumitomo Seika Chemicals Co. Ltd. occupies a position emphasizing laboratory support depth across cosmetic formulators. These three anchors represent divergent geographic and service-model specializations.
| Leading Market Players |
|---|
| Anhui Newman Fine Chemicals Co. Ltd. |
| Sumitomo Seika Chemicals Co. Ltd. |
| The Lubrizol Corporation |
| Maruti Chemicals |
| Tinci Materials |
| Evonik Industries AG |
| Ashland |
| Corel Pharma Chem |
| SNF Floerger |
| Others |
Supply Flow & Price Mechanics
North American pharmaceutical-grade carbomer manufacturing concentration anchors margin capture downstream, with compendial-certified material commanding substantial premiums over standard cosmetic grades as FDA and NMPA inspection protocols compress approved supplier lists.
Pricing Analysis
Volume-discount tiering separates pharmaceutical contracts from personal care procurement, with multi-year direct agreements locking viscosity specifications and residual solvent certificates at rates substantially above spot-market cosmetic grades. Price differentiation hinges on USP-NF monograph compliance and REACH registration status, with non-certified imports facing exclusion from validated formulations. Cost compression in standard-grade material is intensifying as acrylic acid feedstock volatility squeezes producer margins. Industrial coatings buyers exhibit highest price sensitivity, while finished-dose pharmaceutical manufacturers prioritize supply continuity over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for pharmaceutical formulators requalifying excipient sources under tightened traceability mandates. Manufacturing gravity centers on United States, Germany, and China, with production drawing from propylene derivative feedstocks and specialized cross-linking agent chemistries. Single-source vulnerability concentrates in pharmaceutical-grade capacity, where qualified manufacturers remain limited. Distribution runs through direct procurement contracts displacing traditional specialty chemical channels in high-volume pharmaceutical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where compendial certification interoperability determines supplier viability, with ECHA, FDA, and NMPA disclosure requirements creating network effects that consolidate volume with documentation-capable polymer houses.
For Market Incumbents: Harden supply continuity through captive production of pharmaceutical-grade material in multiple regulatory jurisdictions, insulating against NMPA import inspection protocol disruptions. Deepen backward integration into acrylic acid feedstocks to buffer propylene derivative volatility. Prioritize multi-compendial qualification acceleration to outpace cellulosic substitute encroachment in oral solid dosage applications. For New Entrants and Emerging Players: Pursue India's excipient import substitution opportunity as CDSCO sourcing rules tighten, partnering with domestic pharmaceutical manufacturers to establish GB-standard and USP-NF certified production. Target topical cannabis formulation laboratories seeking transdermal gel rheology modifiers beyond traditional supplier relationships. Lead with technical service depth and rapid hydration kinetics to differentiate from established commodity suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated polymer houses with batch-specific documentation capabilities spanning REACH, USP-NF, and NMPA compliance. Long-term viability hinges on regulatory filing momentum rather than volume scale alone. Watch for direct procurement contract announcements from multinational generic drug firms as the primary inflection signal for supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid Feedstocks | Captive supply of propylene derivatives buffers margin compression from commodity volatility. |
| Multi-Compendial Qualification Acceleration | USP-NF, Ph.Eur., and JP monograph compliance opens access to validated pharmaceutical formulations. |
| Self-Wetting Grade Manufacturing Scale-Up | Modified polymer hydration kinetics compress batch cycle times for South Korean cosmetic compounders. |
| Direct Procurement Contract Capture | Multi-year agreements with Indian and Chinese generic drug firms lock viscosity specifications. |
| Residual Solvent Testing Infrastructure Investment | In-house benzene quantification capability satisfies pharmacopeial thresholds without third-party dependency. |
Methodological Framework
The analysis maps carbomer grade specifications, application segments, and regional procurement patterns, each validated through formulation chemists at cosmetic laboratories, pharmaceutical excipient procurement managers, and specialty chemical distribution channel partners. Primary interview intelligence triangulates against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from polymer houses, and USP-NF monograph update records. Bottom-up volume modeling from end-use consumption and top-down supply-side capacity assessment converge on segment-level estimates.
Assumptions hold regulatory inspection protocol stringency and excipient traceability mandate timelines fixed across the projection horizon, while acrylic acid feedstock pricing and cellulosic substitute penetration rates vary as sensitivity inputs. Segmentation dimensions include viscosity grade tier, compendial certification status, physical form, and end-use industry concentration. CAGRs derive from fitted growth curves against historical volume trajectories, with pharmaceutical controlled-release matrix adoption and personal care clean-label certification demand as primary forecast drivers.
Sensitivities concentrate around NMPA import inspection protocol enforcement intensity, ECHA substance evaluation timeline acceleration, and pharmaceutical customer consolidation into direct procurement relationships. Forecasts reflect these documented assumptions and risk factor weightings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Thiamine Market
Functional Chemicals
Sodium Methylate Market