
 Tartrazine Market | 2026-2036
Tartrazine Market Size, Share, and Industry Trends Forecast 2026-2036
Tartrazine Market Analysis
Beverage industry uptake is expanding faster than traditional food coloring channels as carbonated and functional drink portfolios diversify across Asia-Pacific and Latin American markets. Sensient Colors LLC leverages its North American technical service infrastructure to anchor premium beverage contracts. Dynemic Products Ltd. specializes in pharmaceutical-grade tartrazine output for tablet coating applications. Shanghai Dyestuffs Research Institute Co. Ltd. dominates domestic powder-grade supply through captive intermediates production.
Tartrazine, also designated FD&C Yellow No. 5 or E102, is a synthetic azo dye produced through diazotization of 4-aminobenzenesulfonic acid coupled with pyrazolone derivatives, yielding a lemon-yellow hue with maximum absorbance near 425 nm. The compound serves primarily as a water-soluble colorant imparting visual uniformity to processed foods, oral medications, and personal care formulations. Powder-grade tartrazine sustains the largest volume share due to shelf stability and freight efficiency, though liquid dispersions are gaining ground in high-throughput beverage bottling lines where dosing precision reduces batch variation. Pharmaceutical-grade certifications command margin premiums over industrial-grade material because residual aromatic amine thresholds sit orders of magnitude lower.
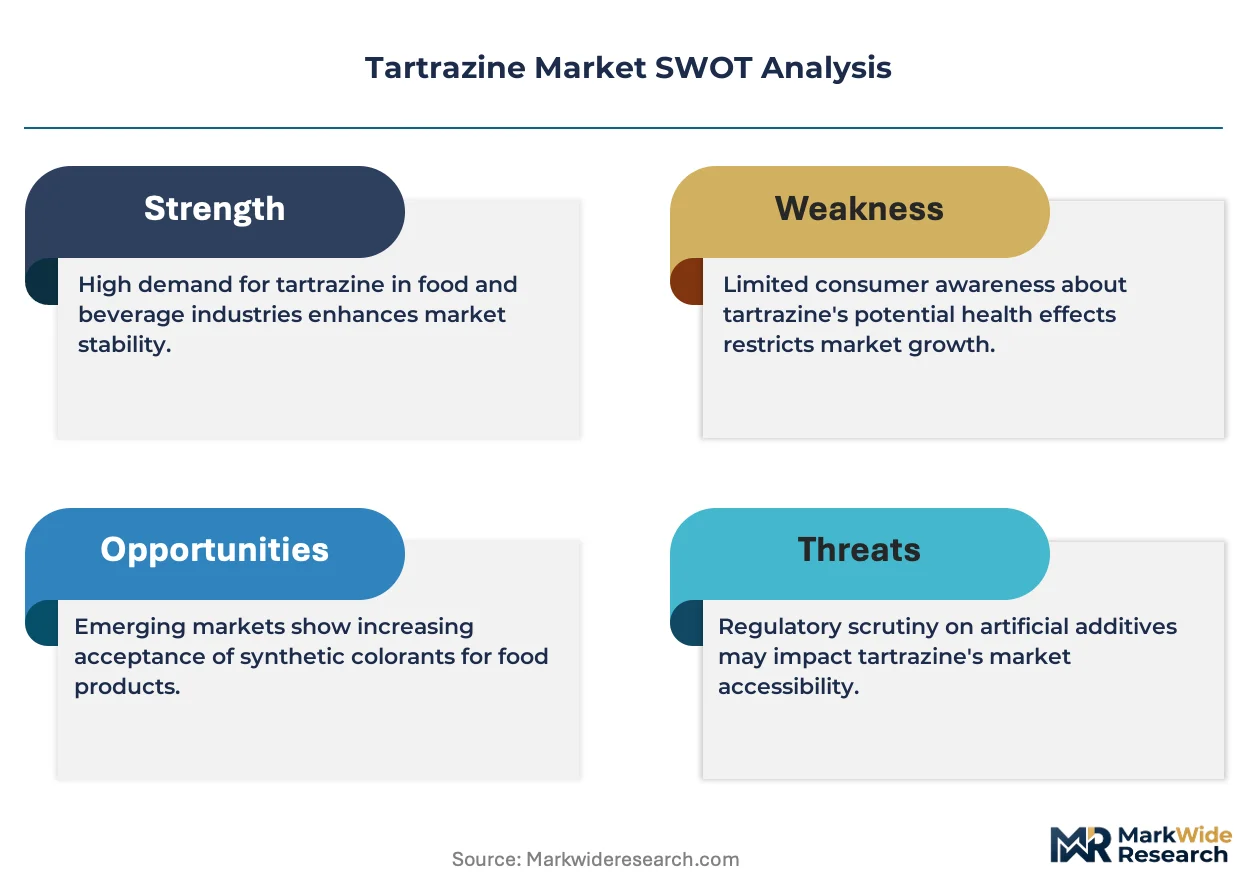
EFSA maintains maximum permitted levels for tartrazine in specific food categories under Regulation (EC) No 1333/2008, while the FDA enforces batch certification requirements for FD&C Yellow No. 5 through its Color Certification Program. India's FSSAI aligns with Codex Alimentarius standards yet enforces additional labeling mandates for products containing azo dyes. These layered compliance obligations compel manufacturers to maintain parallel certification portfolios and region-specific purity dossiers. Stakeholders must monitor pending EFSA re-evaluations of acceptable daily intake thresholds and anticipate corresponding reformulation cycles across European export destinations.
Market Dynamics
EFSA's pending re-evaluation of acceptable daily intake thresholds for azo dyes is compressing formulation timelines across European export destinations, forcing manufacturers to pre-validate alternative supply chains before regulatory finalization.
Growth Catalysts
- India's FSSAI labeling mandates:Domestic processed food output expansion and pharmaceutical export growth are synchronizing demand for certified colorant grades.
- Liquid dispersion technology:High-throughput beverage bottling lines are adopting precision dosing systems that reduce batch variation and waste.
- Carbonated drink portfolios:Functional beverage diversification across Latin American markets is intensifying procurement of water-soluble colorants.
Market Restraints
- 4-aminobenzenesulfonic acid feedstock volatility:Diazotization precursor costs fluctuate with petrochemical derivative pricing.
- Residual aromatic amine thresholds:Pharmaceutical-grade certification requires purity levels orders of magnitude stricter than industrial grades, constraining supplier pools.
- Natural colorant substitution:Turmeric and beta-carotene extracts are displacing synthetic azo dyes in clean-label product lines.
Strategic Opportunities
- Tablet coating applications:Pharmaceutical-grade tartrazine for oral medications remains underpenetrated relative to food coloring saturation.
- Codex Alimentarius alignment:India's FSSAI harmonization creates export passporting advantages for compliant domestic manufacturers.
- Captive intermediates production:Backward integration into pyrazolone derivative synthesis insulates margin compression from merchant market volatility.
Industry Challenges
- Parallel certification portfolios:Maintaining region-specific purity dossiers for FDA, EFSA, and FSSAI compliance strains quality assurance bandwidth.
- Laboratory analytical capacity:Residual aromatic amine testing at pharmaceutical-grade thresholds requires specialized chromatography infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tartrazine Market |
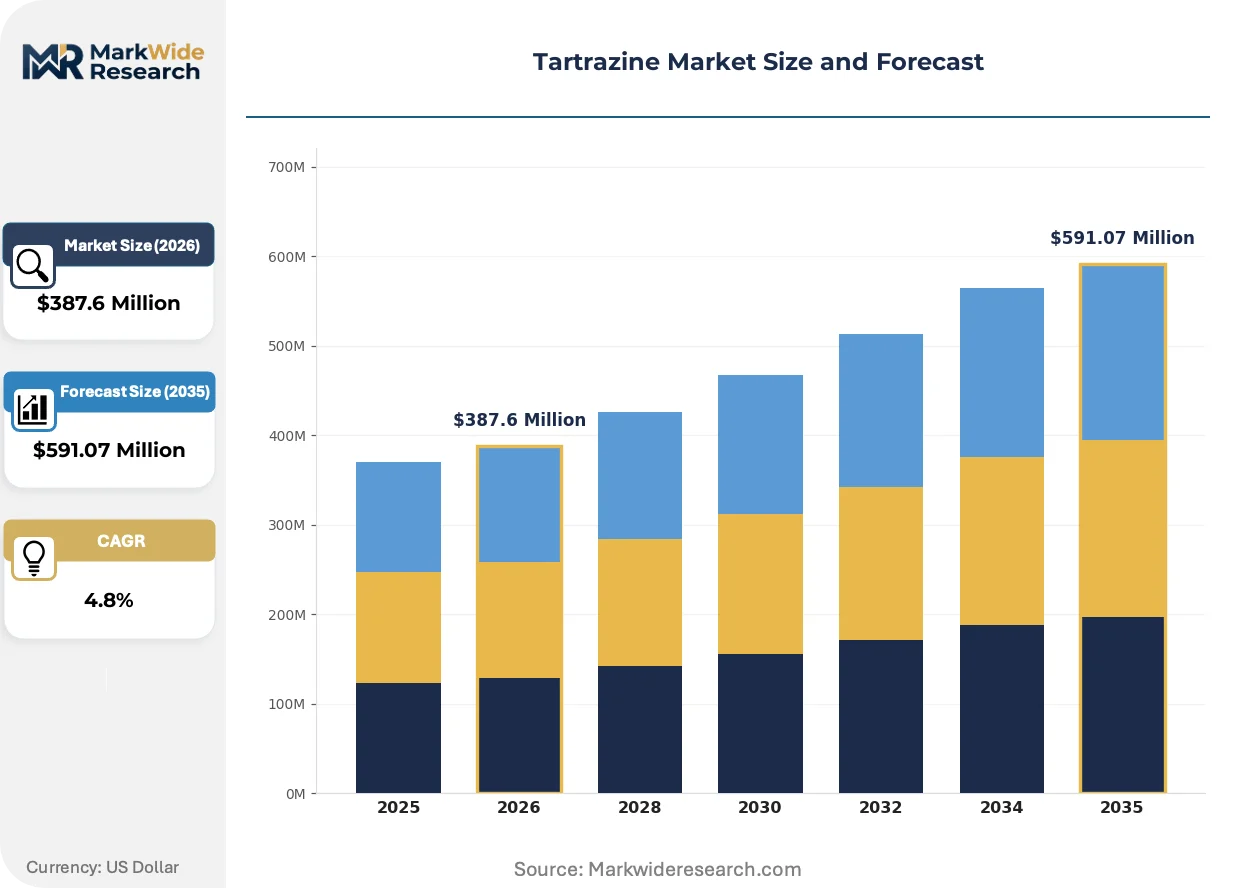
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Paste Application: Food Coloring, Pharmaceutical Products, Cosmetics, Beverage Industry Grade: Food Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Producers, Beverage Manufacturers |
| Companies Covered | Cathay Industries, GFS Chemicals Inc., Sensient Colors LLC, Shanghai Dyestuffs Research Institute Co. Ltd., Sigma-Aldrich Co. LLC, Dynemic Products Ltd., Sunfoodtech, TNC Chemicals Philippines Inc., Neelikon Food Dyes & Chemicals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tartrazine Market Emerging Trajectories
Micro-dispersion technologies and regulatory pre-certification protocols are compressing traditional batch manufacturing cycles while fragmenting procurement authority across regional quality teams.
Encapsulated tartrazine microspheres is decentralizing colorant delivery from centralized powder processing to point-of-use liquid systems. Beverage manufacturers in Brazil and Mexico are adopting these systems at pilot scale. The shift is compressing inventory carrying costs while elevating technical service requirements for equipment calibration.
REACH authorization timelines for aromatic amine derivatives are extending pre-market notification periods for new tartrazine formulations. Industrial consequence includes accelerated investment in analytical method validation. Powder-grade suppliers serving German and French export markets are pre-positioning third-party toxicity dossiers.
Buyer concentration among multinational beverage conglomerates is consolidating specification authority at regional technical centers, displacing plant-level procurement autonomy. Direct contracting with certified manufacturers is replacing distributor intermediation. This pattern is most visible in India's western and southern states where bottling capacity clusters.
Tartrazine Market Segmentation
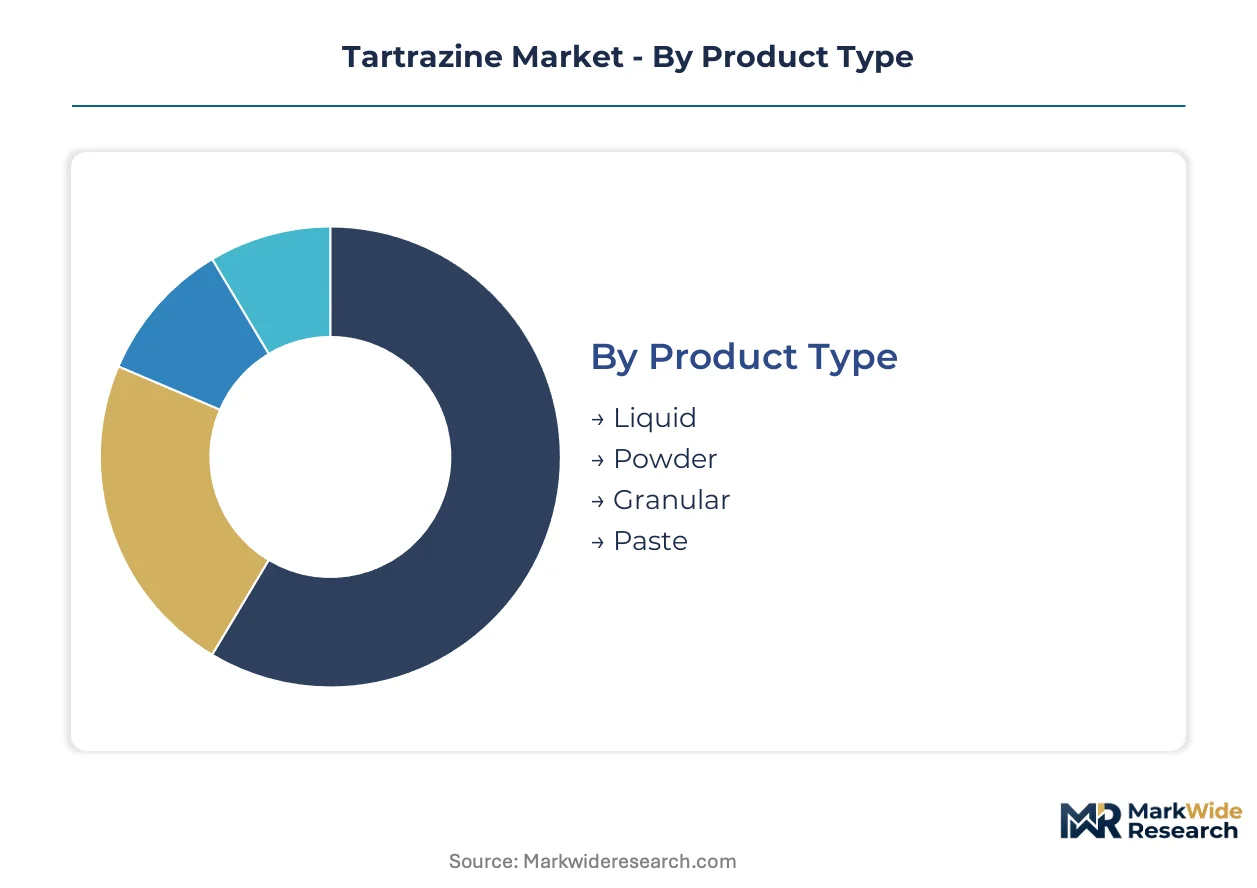
Tartrazine procurement patterns diverge sharply across physical forms, regulatory grades, and end-use specifications. Buyers prioritize shelf stability, dosing precision, or certification tiers depending on their production economics and export obligations.
Product Type:
Physical form selection hinges on handling infrastructure, moisture sensitivity, and batch-to-batch consistency requirements.
- Powder:Anhydrous crystalline form with extended shelf stability and minimal freight cost per color unit. Beverage bottlers in Brazil and Mexico favor powder for inventory carrying efficiency, though dust containment systems add capital overhead.
- Liquid:Pre-dispersed aqueous solutions enabling precision dosing in high-throughput bottling lines. Carbonated drink manufacturers across Latin America are converting to liquid systems to reduce batch variation and waste.
- Granular:Free-flowing agglomerated particles with reduced dusting versus powder grades. Food manufacturers with pneumatic conveying systems specify granular for operator safety compliance.
- Paste:High-viscosity concentrated dispersion for small-batch cosmetic and pharmaceutical compounding. Specialty tablet coaters in India source paste for direct incorporation into coating pans without pre-dissolution.
Powder leads volumes today; liquid is gaining share fastest.
Application:
End-use differentiation centers on regulatory stringency, color stability requirements, and consumer exposure assumptions.
- Beverage Industry:Water-soluble colorant for carbonated drinks, sports beverages, and functional waters where visual uniformity drives shelf appeal. EFSA's pending ADI re-evaluation is compressing formulation timelines for European export portfolios.
- Food Coloring:Broad deployment across processed snacks, confectionery, and dairy analogs. India's FSSAI labeling mandates for azo dyes are redirecting domestic procurement toward certified suppliers with parallel FDA dossiers.
- Pharmaceutical Products:Tablet coating and oral liquid formulations requiring residual aromatic amine thresholds orders of magnitude below industrial grades. CDSCO certification requirements for export-oriented Indian manufacturers constrain supplier pools.
- Cosmetics:Personal care colorant for shampoos, lotions, and decorative products with lower purity thresholds than ingestible applications. REACH authorization timelines for aromatic amine derivatives extend pre-market notification periods for new formulations.
Beverage applications anchor current volumes; pharmaceutical coloring is climbing the fastest.
Grade:
Certification tier determines permissible end-uses, analytical burden, and margin structure.
- Food Grade:Codex Alimentarius-aligned purity specifications for direct human consumption. FSSAI-harmonized Indian manufacturers leverage this grade for export passporting advantages into Middle Eastern and African markets.
- Pharmaceutical Grade:USP/EP-compliant material with comprehensive residual solvent and heavy metal documentation. Oral medication coaters pay substantial premiums for batch-certified material with third-party toxicity dossiers.
- Cosmetic Grade:Intermediate purity tier for topical applications without ingestion exposure assumptions. Personal care formulators in Southeast Asia source this grade for cost-sensitive mass-market lines.
- Industrial Grade:Technical specification for inks, textiles, and non-food applications with minimal regulatory oversight. Price-sensitive buyers in packaging printing accept higher impurity profiles.
Food grade dominates procurement volumes today; pharmaceutical grade commands the steepest expansion trajectory.
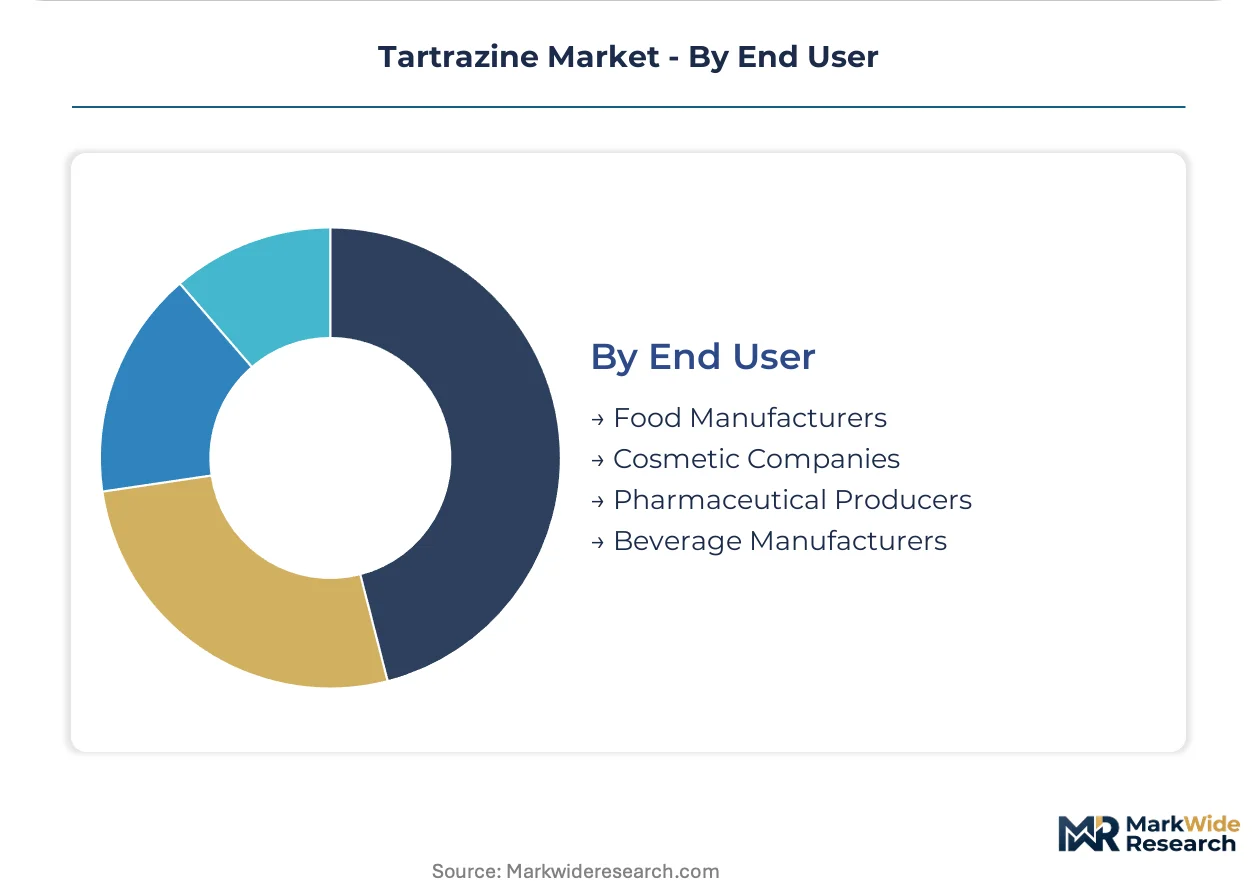
End User:
Customer scale and technical sophistication fragment procurement authority across plant-level buyers and centralized specification teams.
- Beverage Manufacturers:Multinational bottlers with regional technical centers consolidating direct contracts with certified producers. Western and southern Indian states exhibit concentrated bottling capacity with displaced distributor intermediation.
- Food Manufacturers:Processed snack and confectionery producers with formulation flexibility constrained by retailer clean-label pressures. Natural colorant substitution with turmeric and beta-carotene extracts is displacing synthetic azo dyes in premium lines.
- Pharmaceutical Producers:Tablet and capsule manufacturers requiring validated supply chains for regulatory inspections. Specialized chromatography infrastructure for residual aromatic amine testing strains quality assurance bandwidth.
- Cosmetic Companies:Personal care brands with regional formulation hubs adapting to divergent color additive regulations. Brazilian and Mexican pilot-scale operations are testing encapsulated tartrazine microspheres for point-of-use liquid delivery.
Beverage manufacturers lead current offtake; pharmaceutical producers are expanding procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting tartrazine production toward jurisdictions with streamlined certification pathways and lower cost-of-compliance structures, particularly as EFSA tightens purity thresholds across European export destinations.
India
FSSAI labeling mandates for azo dyes and pharmaceutical export growth are synchronizing demand for certified colorant grades. CDSCO certification requirements for tablet coating applications constrain supplier pools to validated manufacturers. Western and southern states—Maharashtra, Gujarat, Karnataka, and Tamil Nadu—host concentrated bottling and pharmaceutical compounding clusters where direct producer contracts are displacing distributor intermediation.
United States
FDA batch certification requirements for FD&C Yellow No. 5 sustain premium pricing for pharmaceutical-grade material with comprehensive documentation. Beverage manufacturers consolidate specification authority at regional technical centers. The New Jersey-Pennsylvania chemical corridor and California's personal care formulation hubs anchor domestic powder-grade and liquid dispersion supply chains.
Germany
REACH authorization timelines for aromatic amine derivatives extend pre-market notification periods, accelerating investment in analytical method validation. EFSA's pending ADI re-evaluation compresses formulation timelines for food and beverage exporters. The Rhine-Ruhr industrial region and Bavarian chemical clusters pre-position third-party toxicity dossiers for compliant tartrazine formulations.
Brazil
Carbonated and functional beverage diversification intensifies procurement of water-soluble colorants for high-throughput bottling lines. ANVISA pharmaceutical regulations align with USP standards for oral medication applications. São Paulo state and the Rio de Janeiro industrial belt pilot encapsulated tartrazine microspheres for point-of-use liquid delivery systems.
China
Domestic processed food output expansion and captive intermediates production insulate margin compression from merchant market volatility. NMPA pharmaceutical-grade standards and export-oriented FSSC 22000 certifications create dual-track compliance obligations. The Yangtze River Delta and Shandong Peninsula concentrate powder-grade manufacturing with backward integration into pyrazolone derivative synthesis.
Tartrazine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification requirements concentrating procurement among validated producers while food-grade volumes fragment across regional suppliers. The market exhibits tiered structure: multinational colorant houses with parallel FDA-EFSA-FSSAI dossiers anchor premium contracts, mid-scale regional manufacturers serve domestic beverage and food channels, and industrial-grade producers compete on price for non-food applications. Two dominant competitive moves are reshaping positioning: direct contracting with certified manufacturers replacing distributor intermediation, and backward integration into diazotization precursors to capture margin from feedstock volatility.
Among North American technical service providers, Sensient Colors LLC exemplifies the multinational premium-tier archetype with beverage-focused infrastructure. Indian pharmaceutical-grade specialists occupy a distinct position—Dynemic Products Ltd. represents the validated-supplier archetype for tablet coating applications, while Neelikon Food Dyes & Chemicals Ltd. sits within the export-oriented certification-heavy tier. Chinese captive-production players anchor the intermediates-integrated segment, with Shanghai Dyestuffs Research Institute Co. Ltd. exemplifying domestic powder-grade dominance through in-house pyrazolone synthesis.
| Leading Market Players |
|---|
| Cathay Industries |
| GFS Chemicals Inc. |
| Sensient Colors LLC |
| Shanghai Dyestuffs Research Institute Co. Ltd. |
| Sigma-Aldrich Co. LLC |
| Dynemic Products Ltd. |
| Sunfoodtech |
| TNC Chemicals Philippines Inc. |
| Neelikon Food Dyes & Chemicals Ltd. |
| Others |
Supply Flow & Price Mechanics
Specialized chromatography technicians in India and China anchor labor-cost differentials that widen pricing-tier spreads between pharmaceutical-grade and industrial-grade tartrazine output.
Pricing Analysis
Distributor margins on pharmaceutical-grade material compress direct-to-OEM discounts that beverage manufacturers negotiate at volume. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates certification-burdened premiums from commodity spot levels. Cost compression in food-grade powder stems from natural colorant substitution with turmeric extracts. Industrial-grade buyers exhibit highest price sensitivity; pharmaceutical coaters accept substantial premiums for USP-compliant batch certification.
Supply Chain Analysis
Freight cost advantages favor powder-grade shipments from India and China to Latin American beverage bottlers over liquid dispersion imports from European suppliers. Pyrazolone derivative synthesis and 4-aminobenzenesulfonic acid diazotization feedstock sourcing rest on petrochemical derivative pricing volatility. Single-source vulnerability concentrates in pyrazolone intermediate supply from Yangtze River Delta manufacturers. Distribution runs through direct producer contracts with multinational beverage technical centers, displacing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tartrazine demand compounds through layered regulatory certification requirements, with EFSA's pending ADI re-evaluation for azo dyes forcing pre-validation of alternative supply chains ahead of finalization.
For Market Incumbents: Anchor pharmaceutical-grade certification portfolios against natural colorant substitution threats by deepening analytical method validation capacity. Defend margin position through backward integration into pyrazolone derivative synthesis that captures feedstock volatility premiums. Prioritize FSSAI-FDA parallel dossier maintenance for Indian export passporting advantages.
For New Entrants and Emerging Players: Enter via pharmaceutical-grade tablet coating applications where residual aromatic amine testing requirements constrain validated supplier pools. Target India's western and southern state clusters where CDSCO certification gaps create white-space opportunities. Pursue direct contracting relationships with regional beverage technical centers as the primary go-to-market pathway.
For Investors and Strategic Acquirers: Beverage conglomerate procurement teams are the most active acquirer in this space, consolidating specification authority at regional technical centers. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Target validated manufacturers with captive intermediates production and parallel FDA-EFSA-FSSAI dossiers. Monitor EFSA re-evaluation timelines as the critical inflection signal for reformulation-driven demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive pyrazolone synthesis insulates margin compression from merchant feedstock volatility in India and China. |
| Pharmaceutical Grade Certification | USP-compliant batch documentation commands substantial premiums from oral medication coaters over food-grade material. |
| Liquid Dispersion Technology | Precision dosing systems reduce batch variation for carbonated beverage manufacturers across Latin American markets. |
| Direct Producer Contracting | Eliminating distributor intermediation captures margin for certified manufacturers serving concentrated Indian bottling clusters. |
| Regulatory Pre-Certification | Third-party toxicity dossiers position suppliers ahead of REACH authorization timelines for aromatic amine derivatives. |
Methodological Framework
Multiple input streams — technical discussions with pharmaceutical quality assurance directors, beverage procurement leads at regional technical centers, and specialty chemical distribution channel partners — were reconciled against customs trade data, FSSAI regulatory filings, and SEC disclosures from listed colorant manufacturers. Bottom-up volume estimates from grade-specific production capacities were cross-validated against top-down demand calculations from end-use industry consumption patterns.
Historical shipment volumes were cross-referenced against panel input from plant managers and R&D directors to establish baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation across physical form, certification grade, and end-use application plus regional regulatory cluster alignment. CAGRs were derived from slope-consistency checks against processed food output indices and pharmaceutical export growth rates.
The model holds under stable regulatory certification timelines; deviation in EFSA re-evaluation schedules or REACH authorization accelerations would shift demand timing assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Propylparaben Market