
 Anti-Corrosion Nanocoatings Market | 2026-2036
Anti-Corrosion Nanocoatings Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Corrosion Nanocoatings Market Outlook
A shortage of specialized nanomaterials chemists and surface engineering technicians is redrawing competitive boundaries across the anti-corrosion nanocoatings sector. PPG Industries leverages its integrated resin and additive supply chain to secure formulation consistency at volume. AkzoNobel anchors its position through marine-focused R&D centers in Northern Europe. BASF SE competes on the strength of its polymer science platform, extending proprietary binders into next-generation barrier coatings.
Anti-corrosion nanocoatings constitute ultra-thin functional films, typically 50–500 nanometers in thickness, engineered with ceramic, metallic, or polymeric nanoparticles to create dense, impermeable barriers against electrochemical degradation on metal substrates. Their primary industrial purpose centers on extending service intervals for steel and aluminum structures exposed to saltwater, chemical effluent, or atmospheric oxidation. Water-based formulations now lead volume shipments across most regulated jurisdictions, while hybrid coatings represent the fastest-expanding category as formulators blend bio-based carriers with inorganic nanoparticle loadings to satisfy dual performance and sustainability targets. Marine applications command premium pricing due to certification complexity and performance guarantees, whereas construction sector uptake remains more price-sensitive and specification-driven.
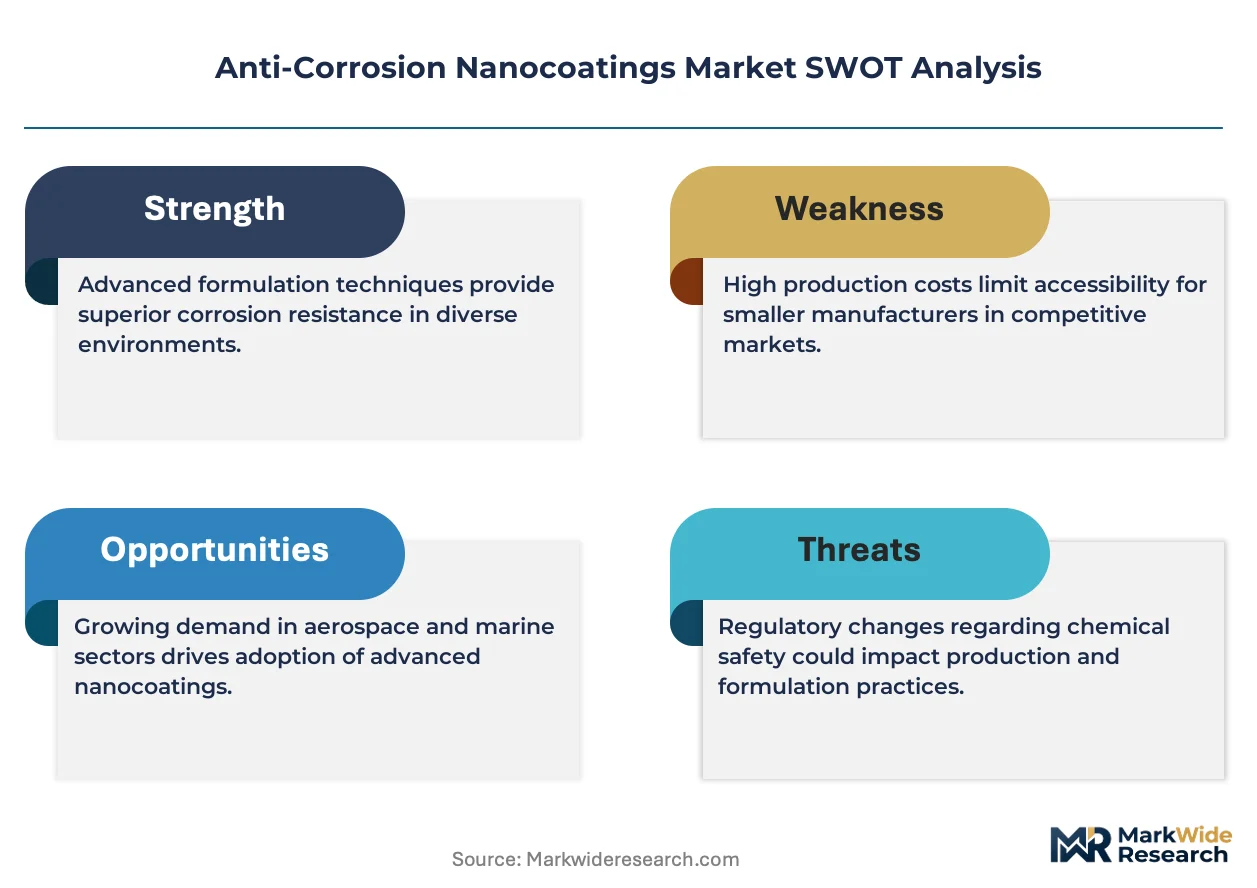
REACH registration requirements in Europe, EPA VOC emission rules in the United States, and China's GB standards for industrial coating emissions collectively determine which formulations achieve market access and which face reformulation costs. Japan's METI-administered JIS corrosion testing protocols further segment export opportunities by creating differentiated compliance tiers. Stakeholders must monitor evolving substance restriction lists and pre-qualification testing timelines to avoid supply discontinuities as regulatory thresholds tighten.
Market Dynamics
REACH substance restriction timelines and EPA VOC emission thresholds are forcing simultaneous reformulation across three continents, compressing R&D cycles while opening first-mover advantages for compliant water-based systems.
Growth Catalysts
- Marine infrastructure renewal:Offshore platform operators in the North Sea and Gulf of Mexico are specifying nanocoating systems for subsea pipelines and risers to extend inspection intervals beyond conventional epoxy limits.
- REACH Annex XVII expansions:Chromium VI compound restrictions in Europe are eliminating legacy pretreatment options, redirecting specification authority toward compliant nanoparticle-based conversion coatings.
- Hybrid formulation breakthroughs:Bio-based carrier systems incorporating silica and alumina nanoparticles are achieving salt-spray performance parity with solvent-borne alternatives, unlocking construction sector volume.
Market Restraints
- Specialized silica nanoparticle supply:Fumed silica production concentrates among three German and Japanese chemical conglomerates, creating input bottlenecks during marine coating seasonality peaks.
- Application equipment capex:Plasma-spray and electrophoretic deposition systems for uniform nanofilm application require capital commitments that exclude smaller job-shop applicators from certification pipelines.
- Epoxy-polyurethane substitution:Mature high-build epoxy systems continue dominating above-water marine maintenance where certification grandfathering protects incumbent specifications.
Strategic Opportunities
- Wind turbine tower protection:China's offshore wind installation targets are creating specification windows for ice-phobic nanocoatings on turbine foundations in Bohai Bay and Yangtze River Delta clusters.
- ISO 12944-9 compliance services:Third-party certification of nanocoating performance against the new offshore wind-specific corrosion standard opens recurring revenue streams for testing laboratories and coating integrators.
- Carbon nanotube-polymer convergence:Multi-walled carbon nanotube loadings in fluoropolymer matrices are demonstrating self-healing barrier properties for chemical storage tank interiors, penetrating petrochemical maintenance budgets.
Industry Challenges
- Surface engineering technician scarcity:Plasma electrolytic oxidation and atomic layer deposition operations require operators trained in vacuum technology and thin-film metrology, skills concentrated in aerospace and semiconductor labor markets.
- Multi-jurisdiction certification timelines:Simultaneous NORSOK M-501, ISO 20340, and NACE SP0108 qualification testing extends product launch cycles by 18-24 months for marine system suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Corrosion Nanocoatings Market |
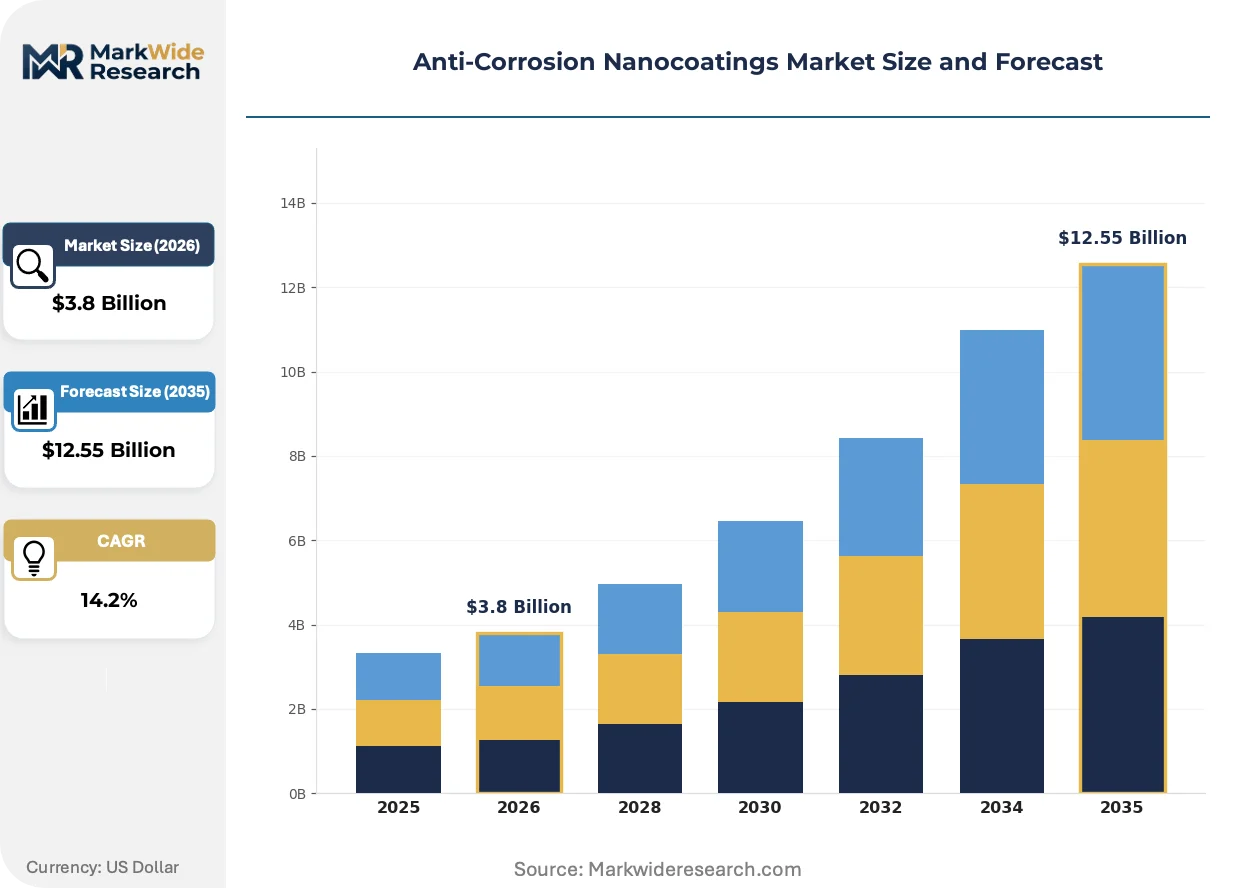
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Powder Coatings, Hybrid Coatings Application: Aerospace, Automotive, Marine, Construction End User: Manufacturers, Maintenance Providers, OEMs, Distributors Technology: Electrostatic Spraying, Aerosol Deposition, Dip Coating, Roll Coating |
| Companies Covered | PPG Industries, Axalta Coating Systems, AkzoNobel, Chugoku Marine Paints, Nippon Paint, Jotun, BASF SE, Nanophase Technologies, Hempel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Corrosion Nanocoatings Market Strategic Shifts
Formulation chemistry and application methodology are converging to produce functional films below 100 nanometers, collapsing the performance gap between laboratory demonstrations and production-scale reliability.
Self-assembling monolayer systems incorporating organosilane and phosphonic acid head groups are miniaturizing barrier film thicknesses while maintaining hydrophobic contact angles above 150 degrees. Shipyards in South Korea and Japan are piloting these systems for ballast tank applications where space constraints limit conventional coating build. The technology is miniaturizing equipment footprints and reducing curing energy requirements by two-thirds compared to thermal-spray alternatives.
EPA Method 24 VOC testing protocol revisions are reclassifying certain water-borne nanodispersions as compliant coatings, triggering reformulation investments among US industrial maintenance suppliers. The rule change compresses permissible solvent content thresholds for Category II industrial coatings, affecting approximately 40 percent of existing marine product registrations. Gulf Coast petrochemical facilities are responding by pre-qualifying zero-VOC ceramic nanoparticle primers for tank farm refurbishment programs.
Asset owner engineering departments are consolidating coating specification authority away from maintenance contractors and toward centralized materials engineering teams with direct nanocoating vendor relationships. This concentration shifts procurement from spot purchasing toward multi-year performance contracts with guaranteed corrosion protection intervals. The pattern is most visible in Norwegian and UK offshore operator procurement frameworks, where total cost of ownership models now dominate initial price evaluation.
Anti-Corrosion Nanocoatings Market Segmentation
Anti-corrosion nanocoatings exhibit sharply divergent margin profiles across formulation chemistries and application methods. Understanding these segment-level economics reveals where specification power concentrates and which technology transitions will reshape competitive returns.
Product Type:
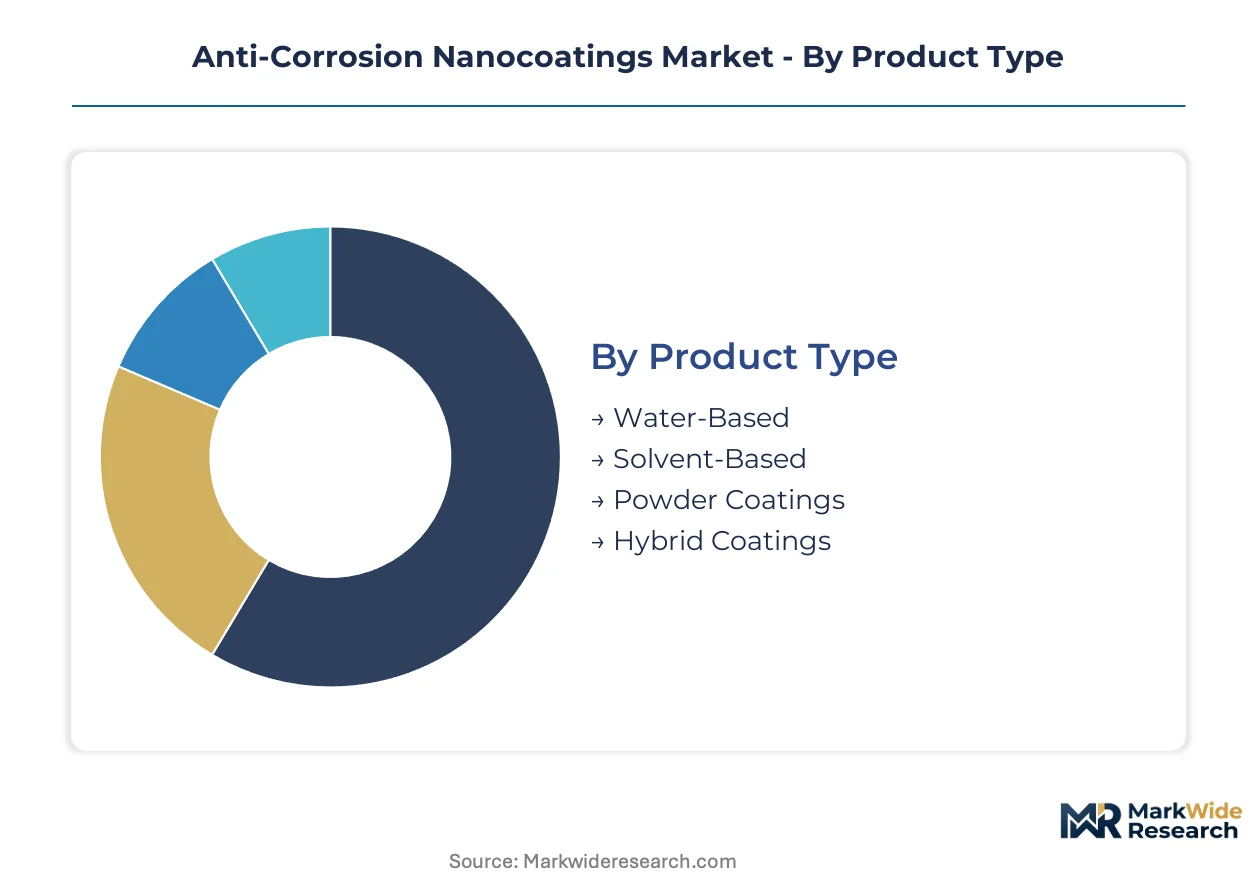
Water-based formulations command premium pricing in regulated jurisdictions, while hybrid systems are capturing the steepest volume expansion as sustainability mandates tighten.
- Water-Based:These systems disperse ceramic and metallic nanoparticles in aqueous carriers, achieving sub-100g/L VOC content that satisfies EPA Method 24 thresholds and REACH Annex XVII limits. Demand clusters in European marine maintenance and US Gulf Coast petrochemical tank refurbishment, where zero-VOC primers are pre-qualified for asset owner engineering specifications. The dominant share belongs to Water-Based, while Hybrid Coatings is closing the gap fastest.
- Hybrid Coatings:Bio-based carriers blended with inorganic silica and alumina nanoparticles are achieving salt-spray parity with solvent-borne alternatives at reduced regulatory compliance cost. Construction sector volume in China's coastal manufacturing belt is accelerating adoption as GB standards for industrial emissions tighten.
- Solvent-Based:Legacy formulations retain above-water marine maintenance share where certification grandfathering protects incumbent specifications.
- Powder Coatings:Thermoset polymer matrices with embedded nanoparticles serve automotive underbody and infrastructure applications requiring thick-film durability.
Water-Based retains the dominant position, though Hybrid Coatings is expanding most quickly as dual performance-sustainability targets harden across jurisdictions.
Application:
Marine certification complexity sustains premium pricing, while construction sector uptake remains specification-driven and price-sensitive.
- Marine:Subsea pipelines, risers, and ballast tank applications require NORSOK M-501 and ISO 20340 qualification, creating 18-24 month certification barriers that protect qualified suppliers. North Sea and Gulf of Mexico offshore operators are specifying nanocoating systems to extend inspection intervals beyond conventional epoxy limits.
- Construction:Steel infrastructure and aluminum facade applications in China's Yangtze River Delta clusters are absorbing water-based and hybrid volumes as GB standards phase out chromium VI pretreatments.
- Aerospace:Plasma electrolytic oxidation and atomic layer deposition operations serve turbine components and airframe sections where vacuum technology expertise concentrates in semiconductor and aerospace labor markets.
- Automotive:Underbody chassis coatings and battery enclosure protection utilize powder and water-based systems with embedded silica nanoparticles for stone-chip resistance.
Marine commands the highest margin pool, yet Construction is gaining share fastest as infrastructure investment scales in coastal China.
End User:
Procurement authority is consolidating toward centralized materials engineering teams with direct vendor relationships, displacing spot purchasing through maintenance contractors.
- Manufacturers:Shipyards in South Korea and Japan pilot self-assembling monolayer systems for ballast tank applications where space constraints limit conventional coating build.
- OEMs:Wind turbine tower producers in Bohai Bay specify ice-phobic nanocoatings for foundation protection against offshore corrosion and icing.
- Maintenance Providers:Norwegian and UK offshore operators now require multi-year performance contracts with guaranteed corrosion protection intervals rather than initial price-based awards.
- Distributors:Regional coating integrators serve smaller job-shop applicators excluded from certification pipelines by plasma-spray and electrophoretic deposition capital requirements.
Manufacturers hold the largest procurement volume, though OEMs are climbing fastest as offshore wind installation targets create specification windows.
Technology:
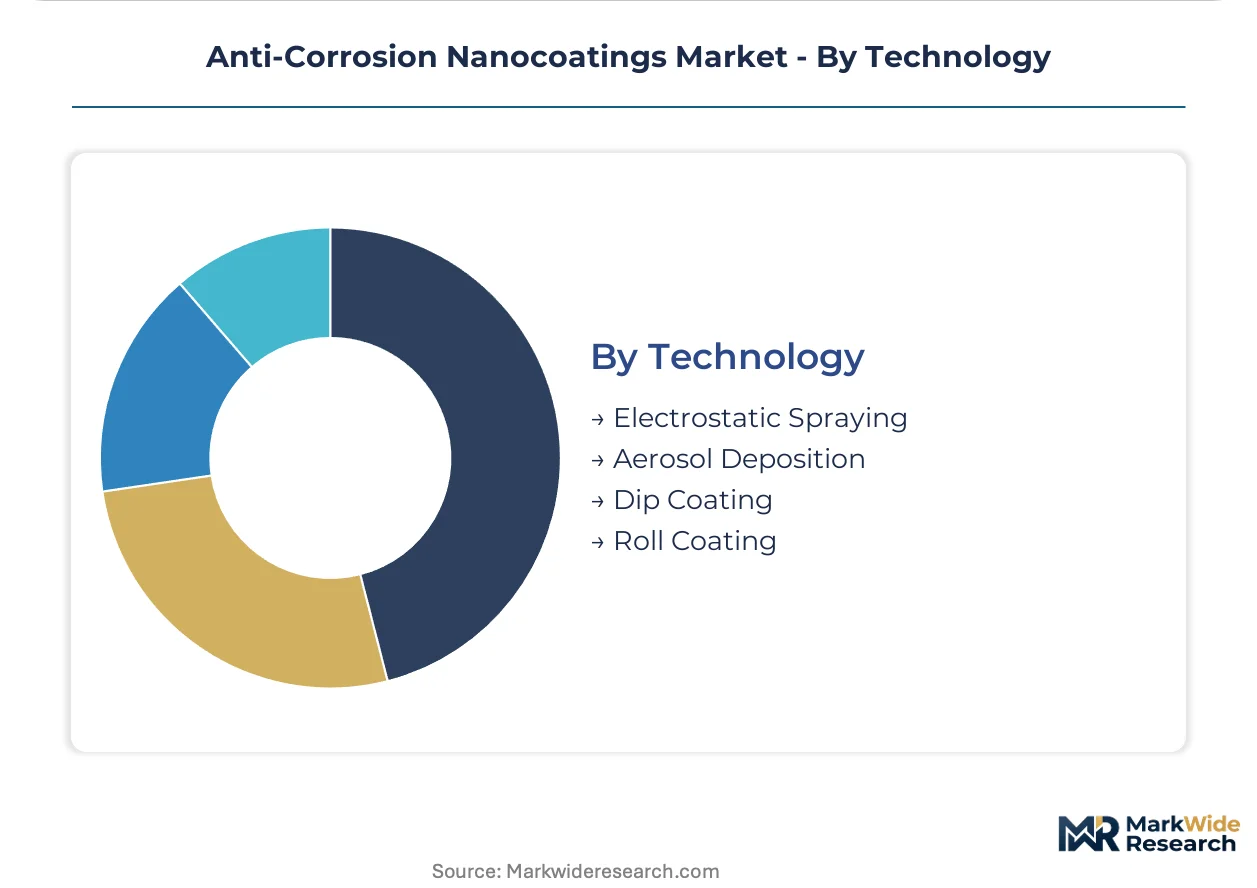
Application equipment capex requirements fragment the vendor base, with electrostatic spraying dominating volume and aerosol deposition advancing thin-film capabilities.
- Electrostatic Spraying:Charged particle deposition achieves uniform nanofilm coverage on complex geometries, serving high-volume automotive and industrial maintenance applications with established equipment supply chains.
- Aerosol Deposition:Room-temperature impact consolidation of nanoparticles enables ceramic film formation on temperature-sensitive substrates, penetrating semiconductor-adjacent aerospace applications.
- Dip Coating:Immersion-based application suits uniform coverage of small components and fasteners in marine hardware.
- Roll Coating:Continuous web processing serves coil-coated steel for construction and appliance applications.
Electrostatic Spraying retains the dominant installation base, while Aerosol Deposition is gaining traction fastest for sub-100 nanometer functional films.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for industrial coating emissions are reshaping procurement patterns across the dominant geography for nanocoating consumption. The report traces how regulatory divergence between jurisdictions is fragmenting formulation strategies while concentrating supply relationships.
United States
Gulf Coast petrochemical facilities drive specification authority for zero-VOC ceramic nanoparticle primers in tank farm refurbishment programs. EPA Method 24 protocol revisions reclassify water-borne nanodispersions as compliant coatings, compressing permissible solvent content thresholds. Houston-area engineering teams consolidate coating procurement away from maintenance contractors toward centralized materials engineering functions.
Germany
Fumed silica production concentrates among chemical conglomerates serving marine coating formulators across Northern Europe. REACH Annex XVII chromium VI compound restrictions eliminate legacy pretreatment options, redirecting specification authority toward compliant nanoparticle-based conversion coatings. Hamburg and Bremen port infrastructure operators specify nanocoating systems for inspection interval extension.
China
Shipbuilding and port infrastructure investment concentrates in the Yangtze River Delta and Bohai Bay manufacturing belts. GB standards for industrial emissions phase out chromium VI pretreatments in steel infrastructure applications. Offshore wind installation targets in Jiangsu and Shandong provinces create specification windows for ice-phobic nanocoatings on turbine foundations.
Japan
METI-administered JIS corrosion testing protocols segment export opportunities through differentiated compliance tiers. Shipyards in Nagasaki and Kure pilot self-assembling monolayer systems for ballast tank applications where space constraints limit conventional coating build. Surface engineering technician scarcity concentrates plasma electrolytic oxidation operations in semiconductor-adjacent labor markets.
Norway
North Sea offshore platform operators specify nanocoating systems for subsea pipelines and risers to extend inspection intervals beyond conventional epoxy limits. NORSOK M-501 qualification requirements protect certified suppliers through 18-24 month certification barriers. Stavanger and Bergen engineering departments now require multi-year performance contracts with guaranteed corrosion protection intervals.
Anti-Corrosion Nanocoatings Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the anti-corrosion nanocoatings sector. Integrated resin and additive suppliers occupy positions of formulation consistency at volume, while marine-focused specialists anchor premium-tier positioning through certification complexity. The market structure fragments across three strategic archetypes: diversified chemical conglomerates with polymer science platforms, regional coating specialists with marine certification depth, and nanoparticle technology developers with materials science IP. Dominant competitive moves include strategic partnerships between formulation houses and nanoparticle suppliers, plus geographic expansion through qualification testing investments in high-growth jurisdictions.
Among diversified chemical conglomerates, PPG Industries and BASF SE exemplify the integrated supply chain archetype, leveraging captive resin and polymer science capabilities to secure formulation consistency. AkzoNobel anchors the marine-specialist tier through Northern European R&D center positioning and certification depth. Nanophase Technologies represents the materials-science-driven archetype, occupying a position focused on specialized nanoparticle development rather than end-formulation supply. These three player types collectively illustrate how competitive returns concentrate at different points in the value chain.
| Leading Market Players |
|---|
| PPG Industries |
| Axalta Coating Systems |
| AkzoNobel |
| Chugoku Marine Paints |
| Nippon Paint |
| Jotun |
| BASF SE |
| Nanophase Technologies |
| Hempel |
| Others |
Value Chain & Pricing Dynamics
Ninety-day fumed silica order backlogs concentrate pricing power among German and Japanese chemical conglomerates, compressing formulation margins for second-tier nanocoating suppliers while amplifying returns for integrated resin producers with captive nanoparticle sourcing.
Pricing Analysis
Marine-grade nanocoatings in Norway command price spreads exceeding construction-sector equivalents by certification depth rather than raw material cost. Three-tier pricing structure across NORSOK-qualified premium, ISO-standard mid-tier, and economy water-based formulations segments buyer archetypes by liability tolerance. Pricing pressure stems from hybrid formulation parity achievements in salt-spray testing, eroding solvent-borne premiums. Maintenance providers exhibit highest price sensitivity, whereas asset owner engineering departments prioritize guaranteed protection intervals over unit cost.
Supply Chain Analysis
Ruhr Valley fumed silica production chokepoints tether global marine coating output to German chemical conglomerate scheduling. Raw material flows draw from Japanese precipitated silica specialists, Chinese rare-earth nanoparticle refiners, and BASF's Ludwigshafen polymer science platform. Single-source vulnerability concentrates in plasma-spray equipment supply, where three vendors control electrophoretic deposition system availability. Distribution runs through regional coating integrators serving certified applicators, excluding capital-constrained job shops from specification pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating toward centralized materials engineering teams at Norwegian and UK offshore operators, displacing fragmented maintenance contractor procurement and forcing vendors toward multi-year performance contracting.
For Market Incumbents: Fortify certification moats through simultaneous NORSOK M-501, ISO 20340, and GB standard pre-qualification investments in China's Yangtze River Delta. Hybrid formulation R&D spending must accelerate before bio-based carriers achieve full performance parity. Backward integration into fumed silica sourcing through offtake agreements with German chemical conglomerates secures input priority during marine coating seasonality peaks. For New Entrants and Emerging Players: Differentiate on aerosol deposition equipment miniaturization for sub-100 nanometer film applications in semiconductor-adjacent aerospace maintenance. China's offshore wind installation targets in Jiangsu and Shandong provinces present the most penetrable geography, with ice-phobic nanocoating specifications still forming. Partner with Stavanger-based engineering consultancies to bypass 18-24 month direct certification barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates' non-core coating divisions, where polymer science platforms await nanocoating-specific application focus. Long-term viability hinges on regulatory compliance service bundling rather than commodity formulation supply. Watch EPA Method 24 threshold compression as the inflection signal triggering zero-VOC ceramic primer pre-qualification waves across Gulf Coast petrochemical facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanoparticle Supply | Captive fumed silica sourcing insulates PPG Industries from German conglomerate allocation decisions during marine seasonality peaks. |
| Multi-Jurisdiction Certification Investment | Simultaneous REACH, EPA, and GB standard qualification unlocks specification access across North Sea, Gulf Coast, and Chinese coastal manufacturing belts. |
| Hybrid Formulation Scale-Up | Bio-based carrier systems with silica nanoparticle loadings capture construction sector volume as China's industrial emission standards tighten. |
| Performance Contracting Transition | Guaranteed corrosion protection intervals displace spot purchasing among Norwegian offshore operators consolidating procurement authority. |
| Aerosol Deposition Equipment Partnership | Room-temperature ceramic film formation enables penetration of temperature-sensitive aerospace substrate applications. |
Study Parameters
The analysis maps water-based, hybrid, solvent-based, and powder formulation sub-sectors, each validated through technical R&D directors at marine coating formulators, procurement leads at offshore platform operators, plant managers at fumed silica production facilities, and distribution channel partners serving certified applicators. Secondary validation draws from REACH Annex XVII substance restriction filings, EPA Method 24 protocol documentation, Chinese GB standard emission databases, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume estimates triangulate against top-down addressable market calculations.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions model formulation chemistry, application method, end-use industry, and regional regulatory cluster. CAGRs derive from regression analysis of historical adoption curves applied to regulatory enforcement timelines. Forecast inputs incorporate REACH substance restriction phase-out schedules and Chinese offshore wind installation capacity targets.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, EPA threshold compression, or Chinese GB standard implementation would require recalibration. Forecasts reflect assumptions regarding certification timeline stability and nanoparticle supply concentration persistence. Practitioners should keep alternative scenarios live as hybrid formulation performance parity and aerosol deposition equipment cost trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Marking Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
Trim Coatings Market
Coatings
Architectural Metal Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
BPA-Free Coatings Market
Coatings
Non-Stick Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Wire Enamels Market
Coatings
Coatings Raw Materials Market
Coatings
Packaging Coatings Market
Coatings
Carbon Fiber Coatings Market
Coatings
Textile Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Acrylic Coating Market