
 Phthalimide Market | 2026-2036
Phthalimide Market Size, Share, and Industry Trends Forecast 2026-2036
Phthalimide Market Analytics
Specialized phthalimide chemist availability is unwinding capacity expansion plans at several producers. Lanxess leverages its European manufacturing base to sustain pharmaceutical-grade supply chains. Nanjing Ningkang Chemical dominates regional production in East China through backward integration into phthalic anhydride feedstocks. Tokyo Chemical Industry positions itself in high-purity research-grade segments for laboratory end users.
Phthalimide comprises a bicyclic organic compound with the formula C8H5NO2, synthesized via condensation of phthalic anhydride with ammonia or urea at temperatures between 150°C and 300°C, serving primarily as a chemical intermediate for pharmaceuticals, agrochemicals, and specialty dyes. Pharmaceutical-grade phthalimide commands premium pricing due to stringent purity thresholds and regulatory documentation burdens, while industrial-grade supply competes on volume scale for dye and polymer applications. The agrochemicals application segment is gaining traction as phthalimide derivatives find expanded use in fungicide and herbicide formulations.
REACH registration requirements in Europe, China's GB standards administered by SAMR, and India's BIS certification collectively elevate compliance costs for cross-border phthalimide trade. EPA oversight in the United States further constrains emission profiles from phthalic anhydride-based production routes. Stakeholders must monitor evolving purity mandates and feedstock volatility to align capacity investments with shifting regional demand patterns.
Market Dynamics
Phthalimide production capacity clusters around East China's chemical corridor, creating supply-side concentration that amplifies price volatility when feedstock phthalic anhydride fluctuates. This geographic lock-in forces buyers to navigate multi-layered compliance regimes spanning REACH in Europe, GB standards in China, and BIS certification in India.
Growth Catalysts
- Active pharmaceutical ingredient synthesis:Pharmaceutical manufacturers in India are scaling phthalimide procurement for intermediate production, with CDSCO oversight driving documentation-heavy supply relationships.
- REACH registration tiering:The European Chemicals Agency's substance evaluation protocols create competitive moats for compliant suppliers, filtering out lower-grade competitors from pharmaceutical-grade segments.
- Agrochemical derivative expansion:Fungicide and herbicide formulations incorporating phthalimide backbones are gaining formulation share as resistance management drives molecular diversification.
Market Restraints
- Phthalic anhydride feedstock volatility:Crude oil-linked aromatics pricing transmits directly to phthalimide production economics, compressing margin predictability for non-integrated producers.
- Specialized chemist scarcity:The limited pool of phthalimide synthesis specialists constrains capacity expansion timelines at multiple producers across the supply base.
- Regulatory documentation burden:Pharmaceutical-grade supply requires extensive purity certification and audit trails, elevating fixed costs that industrial-grade competitors avoid.
Strategic Opportunities
- High-purity research-grade segments:Laboratory end users in Japan and South Korea present underserved demand for ultra-pure phthalimide with MFDS-aligned documentation.
- Green chemistry process innovation:Catalytic ammonia condensation methods reducing energy intensity below 150°C threshold operations align with China's dual carbon goals and MEE emission guidelines.
- Backward integration pathways:Captive phthalic anhydride production within East China chemical parks insulates margin structures from feedstock spot market swings.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous BIS, REACH, and GB standard compliance creates sequential approval bottlenecks stretching 18-24 months for new production facilities.
- Legacy equipment retrofit costs:Existing condensation reactors require capital-intensive upgrades to meet tightening EPA emission profiles for ammonia handling and thermal oxidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phthalimide Market |
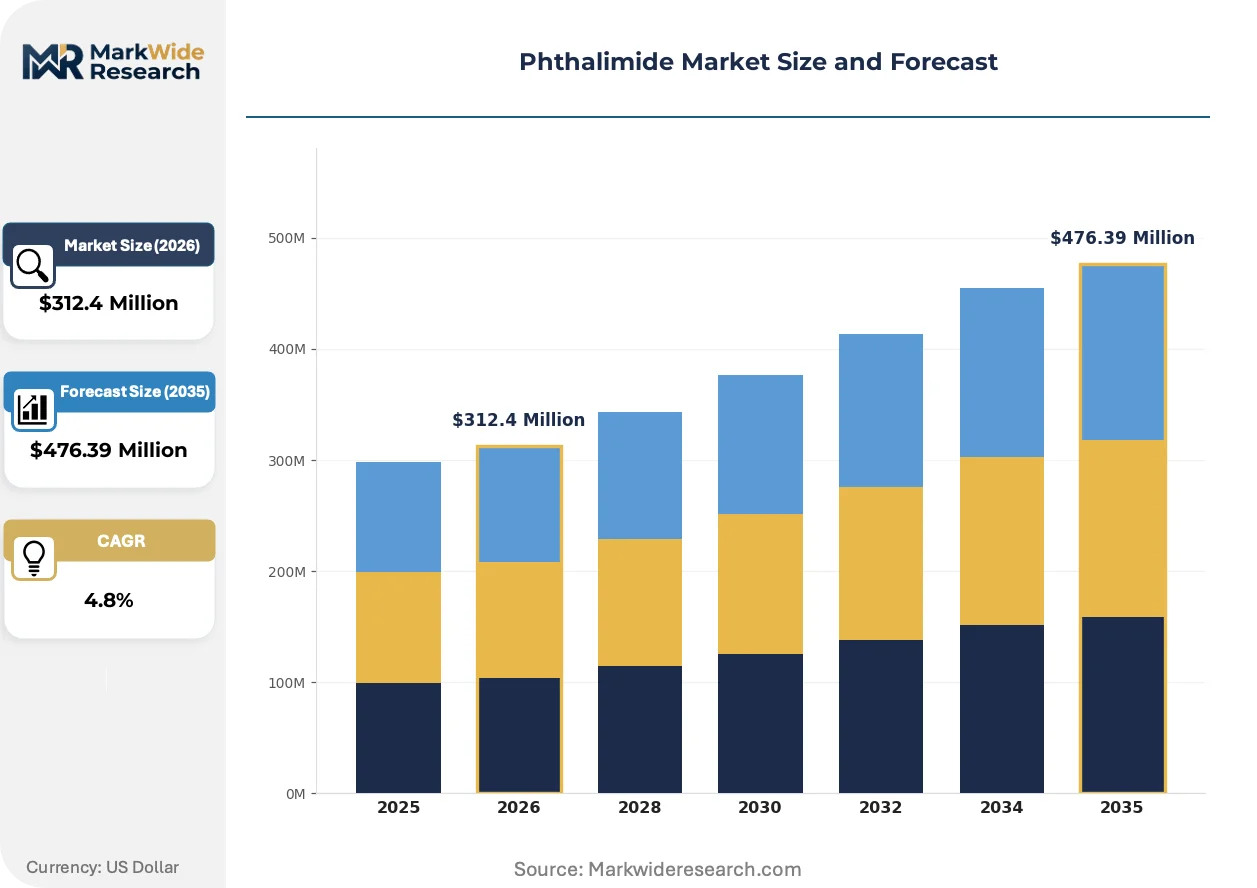
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Agricultural Grade, Specialty Grade Application: Pharmaceuticals, Agrochemicals, Dyes, Specialty Polymers End User: Pharmaceutical Manufacturers, Agrochemical Companies, Research Laboratories, Chemical Industries Sales Channel: Direct Sales, Distributors, Online Platforms, Retailers |
| Companies Covered | Lanxess, Triveni Chemicals, Brahma Scientific, Neuchatel Chemie Specialities, SLN Pharmachem, Ishita Industries Limited, Nanjing Ningkang Chemical Co., Ltd., Tokyo Chemical Industry Co., Ltd., HuBei XianLong Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phthalimide Market Evolving Landscape
Process intensification and purity segmentation are restructuring competitive boundaries in phthalimide supply. Technology diffusion is compressing the gap between pharmaceutical-grade and industrial-grade production capabilities.
Continuous flow reactor technology for phthalic anhydride-ammonia condensation is fragmenting traditional batch production economics. Specialty chemical producers in Germany and Japan are adopting modular flow systems for sub-tonne pharmaceutical-grade output. This scale-down capability is fragmenting volume-based competitive moats that historically protected large-batch producers.
REACH substance evaluation under ECHA's 2023-2025 work program is tightening impurity thresholds for phthalimide imported into European pharmaceutical supply chains. Downward revisions on allowable heavy metal content and residual solvent levels are forcing reformulation of established synthesis protocols. Contract manufacturers in India are responding by investing in dedicated pharmaceutical-grade production lines with segregated quality systems.
Buyer consolidation among Indian API producers is compressing supplier negotiation cycles from annual to quarterly frameworks. Long-term offtake agreements with backward-integrated Chinese producers are displacing spot market purchasing for volume phthalimide consumers. This contract densification is most visible in the Mumbai-Pune pharmaceutical manufacturing cluster where procurement teams centralize chemical intermediate sourcing.
Phthalimide Market Segmentation
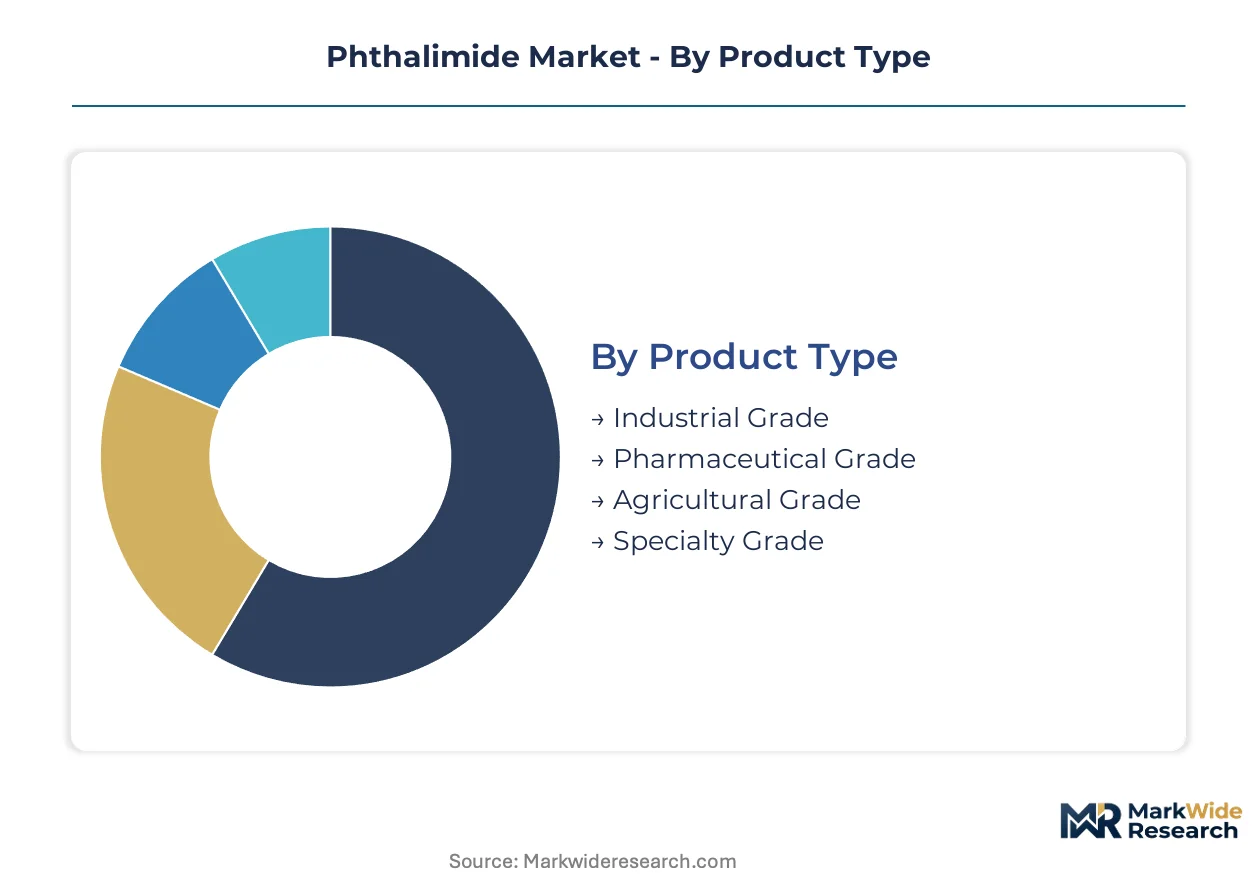
Phthalimide purity grades and application pathways fragment procurement patterns across pharmaceutical, agrochemical, and industrial dye supply chains. Segment boundaries align with regulatory certification burdens rather than simple chemical specifications, forcing buyers to navigate tiered compliance requirements.
Product Type:
Domestic consumption clusters around industrial-grade supply chains serving dye manufacturers in East China, while pharmaceutical-grade volumes flow disproportionately toward export markets governed by REACH and FDA documentation protocols.
- Industrial Grade:Standard purity specifications (95-98%) serve bulk dye intermediates and polymer additive applications. Demand concentrates in Ningbo and Shandong chemical parks where phthalic anhydride feedstock costs determine margin structures.
- Pharmaceutical Grade:Ultra-high purity (≥99.5%) with full impurity profiling and COA documentation for active pharmaceutical ingredient synthesis. Indian API manufacturers in Hyderabad and Ahmedabad drive procurement volumes under CDSCO oversight.
- Agricultural Grade:Intermediate purity tier (97-99%) for fungicide and herbicide backbone synthesis. Agrochemical formulators in Jiangsu province represent the primary domestic uptake.
- Specialty Grade:Custom-specification batches for research-scale applications requiring NMR and MS characterization data. Tokyo Chemical Industry and similar suppliers dominate this thin-volume segment.
Industrial Grade commands the established base. The steepest expansion runs through Pharmaceutical Grade.
Application:
Cost tier separation distinguishes pharmaceutical synthesis—where purity premiums absorb documentation costs—from commodity dye applications competing on kilogram economics.
- Pharmaceuticals:Intermediate for thalidomide derivatives, antimicrobial agents, and heterocyclic building blocks. Indian contract manufacturers scale procurement under long-term offtake agreements with Chinese producers.
- Agrochemicals:Fungicide and herbicide molecular backbones incorporating phthalimide scaffolds for resistance management. Formulation demand is climbing fastest as agrochemical patent cliffs accelerate molecular diversification.
- Dyes:Phthalocyanine pigment precursors and disperse dye intermediates. Volume scale competes on phthalic anhydride integration economics in Shandong and Zhejiang production clusters.
- Specialty Polymers:Heat-resistant polyimide monomers and electronic-grade resin components. Semiconductor packaging applications in South Korea and Japan drive specification tightening.
Dyes command the established base. The steepest expansion runs through Agrochemicals.
End User:
Customer type determines contract structure—pharmaceutical manufacturers negotiate quarterly frameworks while chemical industries transact on spot markets.
- Pharmaceutical Manufacturers:Integrated API producers and contract development organizations requiring audit-ready supply chains. Mumbai-Pune cluster procurement teams centralize intermediate sourcing under BIS-aligned quality systems.
- Agrochemical Companies:Multinational formulators and domestic Chinese producers sourcing backbone intermediates for fungicide synthesis. Procurement cycles align with Northern Hemisphere growing seasons.
- Research Laboratories:Academic and corporate R&D facilities demanding gram-to-kilogram quantities with full analytical characterization. MFDS-aligned documentation requirements shape supplier selection in South Korea.
- Chemical Industries:Dye manufacturers, polymer compounders, and specialty chemical blenders purchasing on volume contracts. Price sensitivity forces backward integration where feedstock access permits.
Chemical Industries command the established base. The steepest expansion runs through Pharmaceutical Manufacturers.
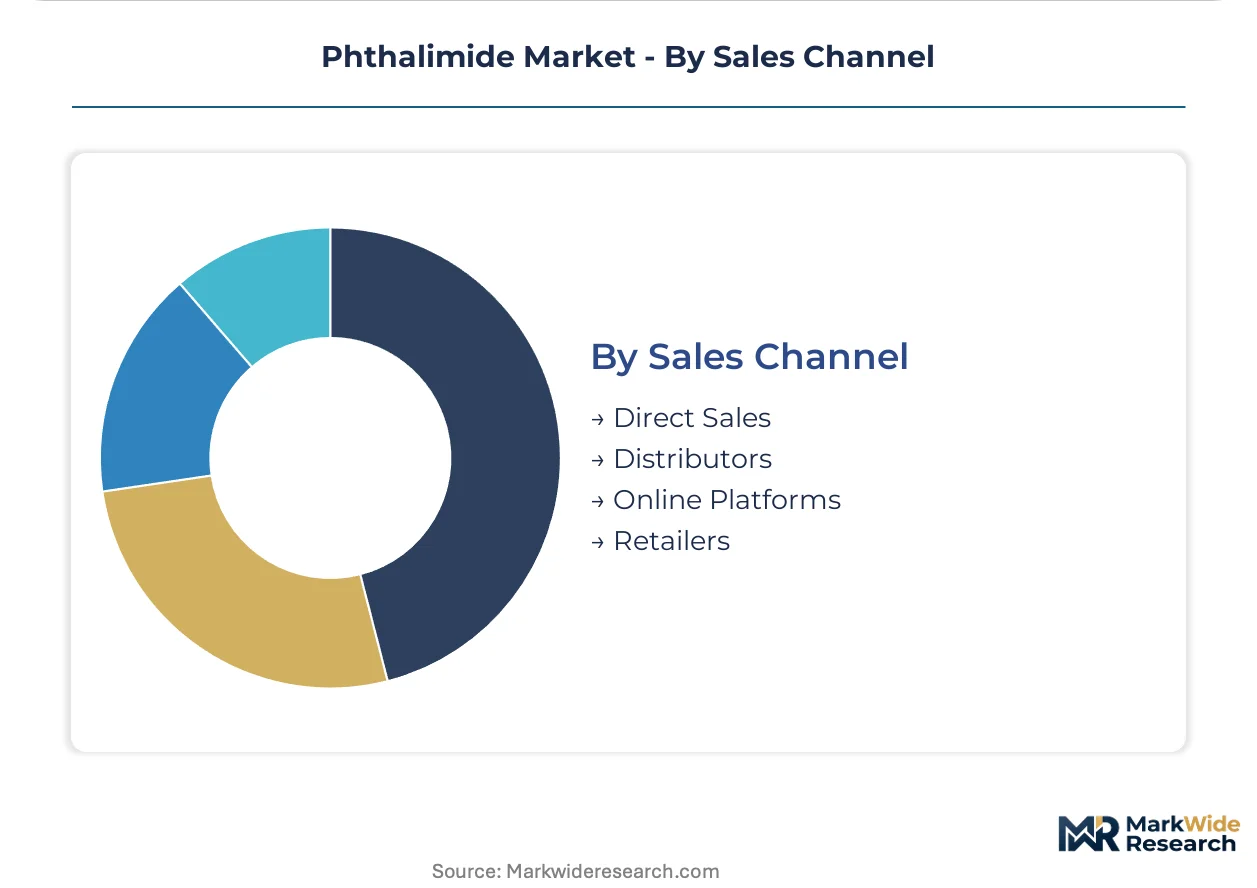
Sales Channel:
Supply concentration in East China chemical corridors shapes channel economics—direct relationships dominate volume trade while distributors fragment smaller-lot procurement.
- Direct Sales:Long-term supply agreements between phthalimide producers and pharmaceutical or agrochemical end users. Contract densification is most visible in Indian API procurement shifting from spot to annual frameworks.
- Distributors:Regional chemical distributors stocking industrial-grade material for dye and polymer customers. Inventory positions in Shanghai and Guangzhou warehouses buffer feedstock price volatility.
- Online Platforms:E-procurement portals for research-grade and specialty-grade material with credit-card transactions and rapid fulfillment. Alibaba and specialty chemical marketplaces serve laboratory-scale buyers.
- Retailers:Limited presence—small-scale chemical traders serving local dye houses and artisanal manufacturers in secondary Chinese cities.
Direct Sales command the established base. The steepest expansion runs through Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes phthalimide predominantly for industrial dye intermediates, while India and Europe channel higher-grade material into pharmaceutical synthesis. This consumption-mix differential shapes regulatory investment priorities and supplier certification requirements across major demand centers.
China
East China's chemical corridor around Nanjing and Ningbo concentrates domestic production capacity for both industrial-grade and pharmaceutical-grade material. GB standards administered by SAMR enforce tightening purity specifications for export-bound pharmaceutical shipments. The Yangtze River Delta cluster leverages backward integration into phthalic anhydride feedstocks to insulate margin structures from crude oil-linked aromatics volatility.
India
API manufacturers in Hyderabad and Ahmedabad scale phthalimide procurement for thalidomide derivatives and heterocyclic building blocks under CDSCO oversight. BIS certification requirements elevate compliance costs for cross-border supply relationships. The Mumbai-Pune pharmaceutical manufacturing cluster centralizes intermediate sourcing through quarterly procurement frameworks replacing spot market purchasing.
Germany
Specialty chemical producers adopt modular continuous flow systems for sub-tonne pharmaceutical-grade output serving European formulation demand. REACH registration tiering under ECHA substance evaluation protocols creates competitive moats filtering lower-grade competitors from high-purity segments. The Rhine-Ruhr industrial region maintains legacy condensation reactor capacity requiring capital-intensive upgrades to meet tightening emission profiles.
United States
Pharmaceutical contract manufacturers source phthalimide for antimicrobial agent synthesis under FDA current good manufacturing practice standards. EPA oversight constrains emission profiles from phthalic anhydride-based production routes, elevating fixed costs for domestic producers. The Gulf Coast petrochemical corridor provides feedstock access for non-integrated buyers navigating volatile aromatics pricing.
Japan
Research-grade end users in Tokyo and Osaka drive demand for ultra-pure phthalimide with full NMR and MS characterization data. MFDS-aligned documentation requirements from South Korean laboratory buyers shape supplier selection criteria for Japanese distributors. METI industrial policy supports catalytic process innovation reducing energy intensity below traditional 150°C threshold operations.
Phthalimide Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the phthalimide supply base. Three structural archetypes define competitive positioning: backward-integrated Chinese producers controlling phthalic anhydride feedstocks, European pharmaceutical-grade specialists leveraging REACH compliance as competitive moat, and research-grade distributors serving laboratory-scale demand with analytical documentation. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as specialized chemist scarcity constrains organic growth timelines.
Among Asia-Pacific-based producers, Nanjing Ningkang Chemical Co., Ltd. exemplifies the backward-integrated archetype through its East China manufacturing position, while Tokyo Chemical Industry Co., Ltd. occupies a specialist position in high-purity research-grade segments. Lanxess represents the European integrated model, sustaining pharmaceutical-grade supply chains from its regional manufacturing base. These three companies anchor the tiered structure, with their respective geographic and grade specializations defining competitive boundaries.
| Leading Market Players |
|---|
| Lanxess |
| Triveni Chemicals |
| Brahma Scientific |
| Neuchatel Chemie Specialities |
| SLN Pharmachem |
| Ishita Industries Limited |
| Nanjing Ningkang Chemical Co., Ltd. |
| Tokyo Chemical Industry Co., Ltd. |
| HuBei XianLong Chemical Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
East China's 300,000-tonne phthalic anhydride capacity base creates scale economies that simultaneously depress industrial-grade phthalimide price floors and concentrate pharmaceutical-grade pricing power among backward-integrated producers. This dual structure forces non-integrated buyers to absorb feedstock volatility while integrated players capture margin stability through captive aromatics supply.
Pricing Analysis
Long-term offtake agreements between Indian API manufacturers and East Chinese producers now dominate pharmaceutical-grade procurement, displacing quarterly spot purchasing that previously governed Mumbai-Pune cluster sourcing. Three-tier pricing structure across pharmaceutical, agricultural, and industrial grades separates documentation-heavy supply chains from commodity dye intermediates. Cost compression in industrial-grade tiers is intensifying because Shandong dye manufacturers negotiate volume rebates against phthalic anhydride spot indices. Chemical industries purchasing polymer additives exhibit highest price sensitivity, while research laboratories accepting NMR-certified batches show lowest elasticity.
Supply Chain Analysis
Strategic stockpile preferences among Indian pharmaceutical manufacturers reflect 18-24 month BIS-REACH-GB certification timelines that buffer against supply interruption risks. Manufacturing concentrates in China, India, and Germany, with feedstock sourcing anchored in East China chemical parks. Raw material dependencies draw from phthalic anhydride, ammonia, and catalytic hydrogenation reagents. Single-source vulnerability runs through Nanjing-Ningbo production corridor concentration. Distribution runs through direct sales channels for pharmaceutical volumes and regional distributors for industrial-grade dye applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialized phthalimide synthesis chemist shortage constrains capacity expansion timelines across multiple producers, making technical talent retention and process automation investments critical differentiators for sustainable positioning.
For Market Incumbents: Compound REACH registration tiering advantages by investing in segregated pharmaceutical-grade production lines with dedicated quality systems, defending against Indian contract manufacturers backward-integrating into captive synthesis. Prioritize catalytic process innovation below 150°C energy thresholds to align with China's MEE emission guidelines and capture dual carbon policy incentives. For New Entrants and Emerging Players: Research-grade service-layer gaps in Japanese and South Korean laboratory markets present white-space entry points where Tokyo Chemical Industry's premium positioning leaves volume underserved. Target ultra-pure segments requiring MFDS-aligned documentation through e-procurement platforms with rapid fulfillment capabilities, bypassing established distributor relationships. For Investors and Strategic Acquirers: Backward-integrated Chinese producers with captive phthalic anhydride supply represent the acquisition archetype offering margin insulation from aromatics volatility. Long-term viability hinges on regulatory compliance moats widening under tightening ECHA impurity thresholds. Watch for CDSCO audit enforcement intensity crossing thresholds that disqualify non-segregated production facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phthalic anhydride production insulates Nanjing Ningkang from crude-linked feedstock volatility. |
| Green Manufacturing Transition | Catalytic ammonia condensation below 150°C aligns with China's MEE emission reduction mandates. |
| Long-term Supply Agreement | Annual frameworks between Indian API producers and East Chinese suppliers displace spot market purchasing. |
| Capacity Expansion | Segregated pharmaceutical-grade lines respond to REACH downward revisions on heavy metal thresholds. |
| Joint Venture | Technology partnerships for continuous flow reactor adoption fragment traditional batch economics. |
Research Methodology
Cross-validation between primary interviews with phthalimide plant managers, procurement leads at Indian API manufacturers, and distribution channel partners anchors the qualitative findings against customs trade data, ACC industry reports, and SEC chemical company filings. Bottom-up capacity modeling triangulates with top-down consumption estimates across pharmaceutical, agrochemical, and dye end-use segments.
Sensitivity analysis on feedstock price volatility and regulatory compliance cost trajectories shapes the analytical framework across the analysis window. Segmentation dimensions include purity grade tier, end-use industry application, and regional production hub clustering. CAGRs derive from installed capacity utilization rates and downstream demand elasticity coefficients, with phthalic anhydride spot price correlation and certification timeline lag effects as key forecast inputs.
Underlying assumptions cover sustained REACH-GB-BIS convergence on impurity thresholds, with deviation risk concentrated in sudden phthalic anhydride supply disruptions or accelerated ECHA substance evaluation timelines. Revision becomes warranted when Indian API procurement centralization crosses thresholds that fundamentally restructure supplier negotiation dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global Adiponitrile Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Citrate Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Functional Polymer Market