
 Traumatic Brain Injuries (TBI) Treatment Market | 2026-2036
Traumatic Brain Injuries (TBI) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Traumatic Brain Injuries (TBI) Treatment Market Analytics
Aftermarket service revenue for implantable neurostimulation systems is narrowing as manufacturers bundle long-term monitoring into initial device contracts. Medtronic leverages its integrated care pathway platforms to sustain recurring revenue streams across acute and chronic TBI management settings. Stryker Corporation anchors its position through specialized cranioplasty and neurosurgical navigation hardware that dominates high-volume trauma centers. Baxter International competes in fluid management and drug delivery systems for intracranial pressure control, a niche where technical specification requirements create defensive moats.
Traumatic Brain Injuries (TBI) Treatment encompasses pharmacological interventions, neurosurgical procedures, rehabilitation protocols, and long-term monitoring systems designed to mitigate primary and secondary neurological damage following cranial trauma. Functional parameters include intracranial pressure thresholds below 22 mmHg, cerebral perfusion pressure maintenance above 60 mmHg, and Glasgow Coma Scale scoring for severity stratification. Medications command the largest current revenue pool given immediate administration protocols in emergency departments, while Monitoring Equipment represents the fastest-expanding segment as continuous intracranial pressure and brain tissue oxygen monitoring become standard of care in level I trauma centers. Rehabilitation Devices concentrate margin pools in post-acute settings where reimbursement for cognitive and motor recovery programs has expanded under bundled payment models.
The FDA regulates neurosurgical devices and neuromodulation systems through premarket notification and premarket approval pathways that shape product development timelines and clinical evidence requirements. The Centers for Medicare & Medicaid Services (CMS) determines reimbursement eligibility for TBI-specific procedure codes, directly influencing hospital capital allocation toward monitoring infrastructure and rehabilitation capacity. Stakeholders must monitor evolving CMS neuroplasticity coverage determinations and FDA guidance on adaptive trial designs for regenerative therapies, as these will determine which therapeutic modalities achieve scalable market access.
Market Dynamics
The FDA's breakthrough device designation pathway is compressing clinical trial timelines for neuromodulation systems while CMS bundled payment models are redistributing capital flows across acute and post-acute care settings.
Growth Catalysts
- Military Healthcare Modernization:Veterans Affairs medical centers are mandating advanced neurorehabilitation protocols for polytrauma patients, creating institutional pull for integrated monitoring-to-recovery platforms.
- CMS Neuroplasticity Coverage Expansion:Medicare reimbursement determinations for cognitive rehabilitation are extending bundled payment eligibility to post-acute TBI recovery programs.
- Intracranial Pressure Monitoring Standardization:Level I trauma centers across Texas, California, and New York are installing continuous brain tissue oxygen monitoring as default protocol for severe TBI admissions.
Market Restraints
- Implantable Device Supply Concentration:Neurostimulation pulse generator manufacturing clusters in Minnesota and Massachusetts create geographic vulnerability to component shortages.
- Specialized Neurosurgeon Scarcity:Fellowship-trained trauma neurosurgeons concentrate in fifteen metropolitan hospital systems, limiting procedural capacity expansion.
- Silicon Wafer Input Volatility:Microelectrode array fabrication depends on semiconductor-grade substrate pricing subject to foundry allocation constraints.
Strategic Opportunities
- Telehealth-Enabled Rural Access:Federally Qualified Health Centers in Appalachian and Southwestern states lack TBI-specialized rehabilitation capacity, creating demand for remote cognitive therapy platforms.
- FDA Breakthrough Designation Tailwinds:Expedited review pathways for closed-loop neuromodulation are reducing time-to-reimbursement for novel intracranial pressure management devices.
- Acute-to-Post-Acute Data Integration:Cloud-based electronic health record interoperability between trauma centers and skilled nursing facilities is collapsing information silos that fragment patient handoffs.
Industry Challenges
- Biocompatibility Certification Timelines:ISO 10993 testing for chronically implanted neural interfaces extends product development cycles by eighteen to thirty-six months.
- Legacy Device Interoperability:Proprietary data formats from existing intracranial pressure monitors resist integration with newer cloud-analytics platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traumatic Brain Injuries (TBI) Treatment Market |
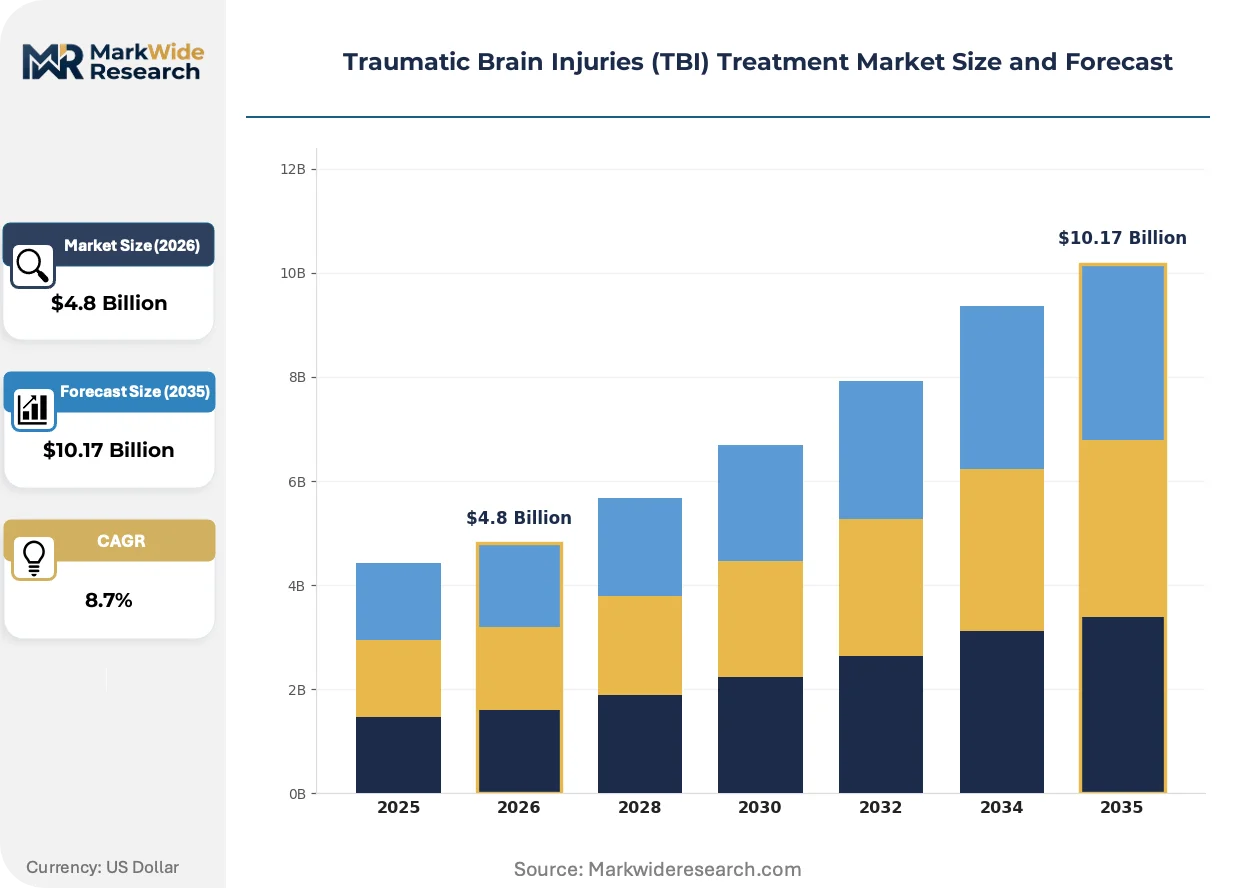
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Rehabilitation Devices, Surgical Instruments, Monitoring Equipment Therapy Type: Pharmacological, Physical Therapy, Cognitive Therapy, Occupational Therapy Delivery Mode: Oral, Intravenous, Inhalation, Transdermal End User: Hospitals, Rehabilitation Centers, Home Care, Long-Term Care Facilities |
| Companies Covered | Johnson & Johnson, Medtronic, Stryker Corporation, Baxter International, Boston Scientific, Abbott Laboratories, Integra LifeSciences, Teva Pharmaceutical Industries Ltd., SanBio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traumatic Brain Injuries (TBI) Treatment Market Evolving Landscape
Neuromodulation hardware and algorithmic patient stratification are converging to compress the gap between acute intervention and functional recovery measurement.
Closed-loop intracranial pressure management systems are collapsing the traditional separation between monitoring and therapeutic response. These devices autonomously adjust cerebrospinal fluid drainage or targeted drug delivery based on real-time biometric thresholds. Academic medical centers in Boston, Houston, and Baltimore are piloting these platforms in surgical intensive care units. The technology is collapsing the need for manual nursing intervention in pressure crisis events, reducing response latency from minutes to milliseconds.
CMS is finalizing coverage determinations for remote patient monitoring codes specific to post-discharge TBI surveillance. This regulatory shift is compelling hospital systems to invest in wearable accelerometry and cognitive assessment apps for home-based recovery tracking. Rehabilitation networks in Florida and Arizona are responding fastest, integrating these tools into value-based care contracts with commercial payers.
Hospital procurement committees are consolidating vendor relationships for acute neurocritical care into single-source monitoring ecosystem contracts. This behavioral shift displaces the previous pattern of point-solution purchasing for individual device categories. The concentration is most visible in California and Illinois, where integrated delivery networks are negotiating five-year agreements bundling intracranial hardware, software licenses, and clinical decision support subscriptions.
Traumatic Brain Injuries (TBI) Treatment Market Segmentation
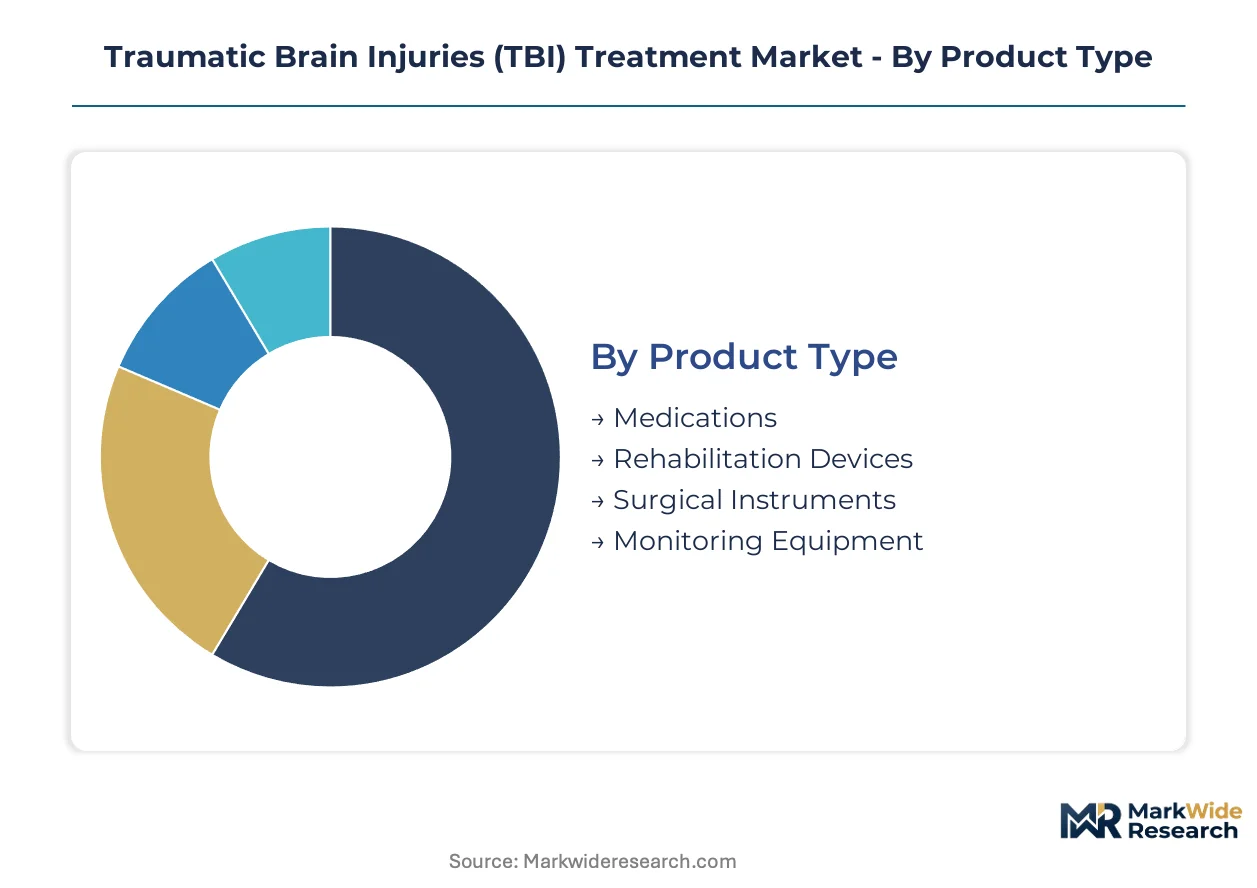
Treatment modality selection in TBI care hinges on injury severity stratification, reimbursement pathway alignment, and institutional infrastructure capacity. Segmentation reveals where capital allocation concentrates and which therapeutic categories command premium pricing power.
Product Type:
After-sales service intensity varies sharply across product categories, with implantable systems requiring multi-year technical support contracts while consumable medications generate minimal recurring revenue attachment.
- Medications:Acute-phase pharmaceutical protocols encompass osmotic diuretics, anticonvulsants, and sedative-analgesic combinations administered in emergency departments. Demand clusters at level I trauma centers in Texas, California, and New York where severe TBI admission volumes justify dedicated neurocritical care pharmacy infrastructure. Formulary placement decisions by hospital pharmacy committees determine manufacturer access.
- Monitoring Equipment:Continuous intracranial pressure and brain tissue oxygen monitoring systems integrate proprietary catheter hardware with cloud-based analytics platforms. Level I trauma centers across the United States are installing these as default protocol for severe TBI admissions, driven by emerging evidence linking early pressure normalization to improved functional outcomes. FDA breakthrough device designations are compressing procurement evaluation cycles for novel closed-loop systems.
- Rehabilitation Devices:Robotic-assisted gait trainers and virtual reality cognitive training systems target motor and neuroplastic recovery in post-acute settings. CMS bundled payment expansion for cognitive rehabilitation is extending reimbursement eligibility to skilled nursing facilities.
- Surgical Instruments:Craniotomy kits, decompressive craniectomy systems, and neurosurgical navigation hardware support emergent operative intervention. High-volume trauma centers in metropolitan hospital systems concentrate procedural demand.
Medications holds the largest share; momentum sits with Monitoring Equipment.
Therapy Type:
Cost tier stratification separates acute intervention from extended recovery protocols, with pharmacological and physical therapy commanding distinct reimbursement schedules and facility capital requirements.
- Pharmacological:Drug protocols target intracranial pressure reduction, seizure prophylaxis, and metabolic stabilization in acute neurocritical care. Veterans Affairs medical centers mandate standardized pharmacological algorithms for polytrauma patients.
- Physical Therapy:Motor rehabilitation protocols address spasticity, balance dysfunction, and gait impairment through task-specific training regimens. Rehabilitation networks in Florida and Arizona are integrating wearable accelerometry into value-based care contracts.
- Cognitive Therapy:Structured interventions target attention, memory, and executive function deficits following moderate-to-severe TBI. Federally Qualified Health Centers in Appalachian states lack specialized capacity, creating demand for telehealth-enabled remote delivery.
- Occupational Therapy:Functional retraining focuses on activities of daily living and vocational reintegration for community re-entry. Post-acute settings under bundled payment models concentrate margin pools.
Pharmacological therapy captures the largest share; cognitive therapy is expanding most quickly.
Delivery Mode:
Application context determines route selection, with acute neurocritical care favoring intravenous administration while post-discharge maintenance shifts toward patient-managed oral and transdermal options.
- Intravenous:Osmotic agents and sedative infusions achieve rapid therapeutic thresholds in intensive care settings. Emergency department protocols mandate immediate intravenous access for severe TBI presentations.
- Oral:Extended-release formulations support outpatient seizure prophylaxis and neuropsychiatric symptom management. Home care settings rely on oral regimens for medication adherence sustainability.
- Inhalation:Aerosolized drug delivery targets pulmonary complications and sedation requirements in ventilated patients. Limited penetration outside surgical intensive care units.
- Transdermal:Patch-based delivery systems address spasticity and pain management with reduced dosing frequency. Long-term care facilities favor transdermal options for nursing efficiency.
Intravenous dominates acute-phase volume; transdermal delivery is climbing the fastest.
End User:
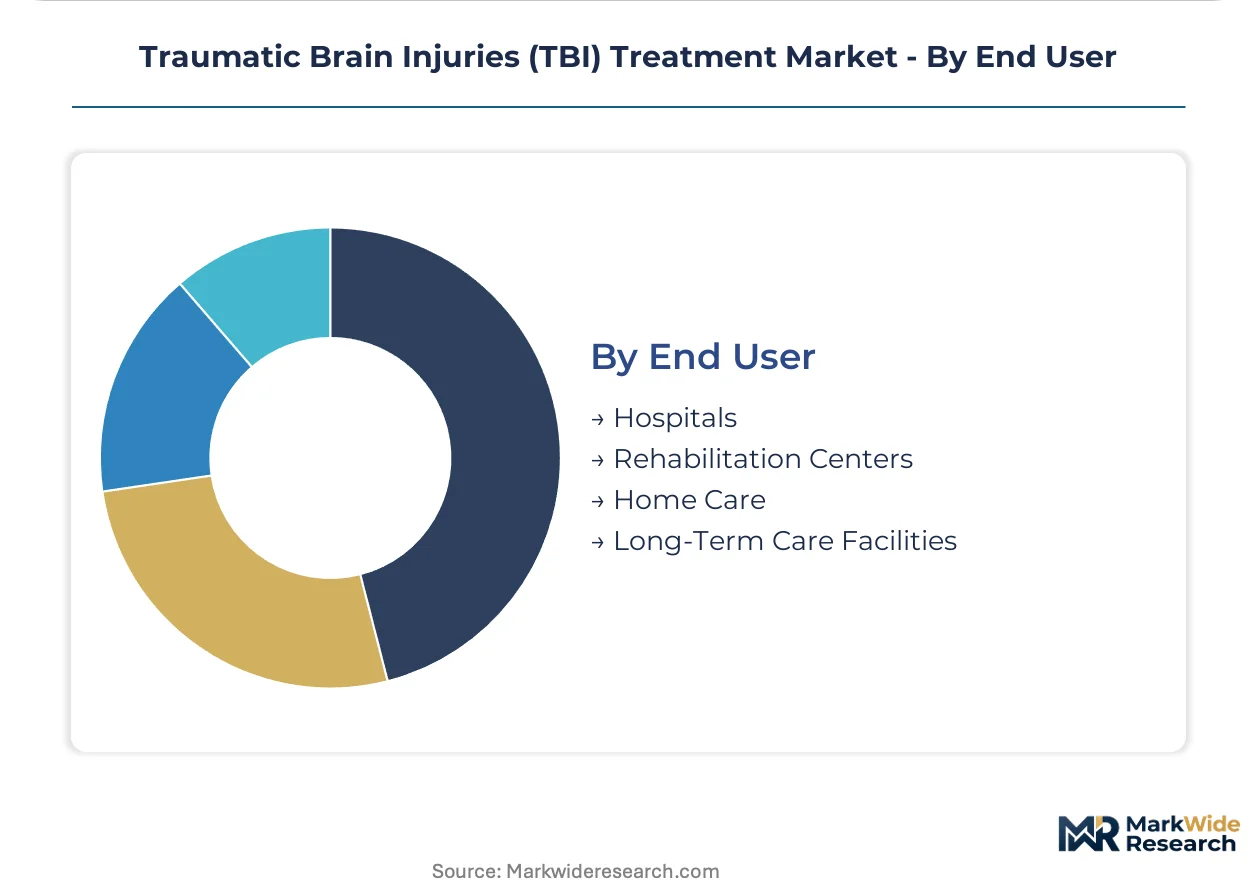
Customer type segmentation maps to reimbursement pathway complexity, with hospitals capturing acute-phase revenue and post-acute settings gaining share under CMS bundled payment redistribution.
- Hospitals:Level I trauma centers and academic medical centers anchor acute surgical and neurocritical care capacity. Hospital procurement committees are consolidating vendor relationships into single-source monitoring ecosystem contracts.
- Rehabilitation Centers:Inpatient rehabilitation facilities and outpatient therapy networks target functional recovery optimization. Specialized TBI care networks cluster around major metropolitan medical centers.
- Home Care:Remote patient monitoring and telehealth-enabled cognitive therapy extend care continuity post-discharge. CMS finalization of remote monitoring codes specific to TBI surveillance is compelling hospital system investment.
- Long-Term Care Facilities:Skilled nursing facilities manage persistent vegetative state and minimally conscious patients requiring chronic care. Bundled payment eligibility expansion is redistributing capital flows toward this segment.
Hospitals retain the largest share; home care settings are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity for implantable neurostimulation systems, while procurement committees in India and Brazil enforce aggressive cost ceilings on monitoring hardware. The United States sits in the middle tier, where bundled payment models compress capital budgets even as clinical specifications tighten.
United States
Veterans Affairs medical centers and level I trauma centers in Texas, California, and New York drive procurement volume for closed-loop intracranial pressure management systems. The FDA's breakthrough device designation pathway accelerates market access for novel neuromodulation technologies. Academic medical centers in Boston, Houston, and Baltimore pilot autonomous cerebrospinal fluid drainage platforms in surgical intensive care units.
Germany
University hospitals in Bavaria and North Rhine-Westphalia anchor European demand for neurosurgical navigation hardware and cranioplasty systems. The EMA's medical device regulation framework shapes clinical evidence requirements for implantable neural interfaces. Industrial clusters around Munich and Düsseldorf concentrate precision manufacturing capacity for microelectrode arrays.
Switzerland
Swissmedic's streamlined approval processes attract developers of chronically implanted neural interfaces seeking faster European market entry. Research institutions in Basel and Zurich coordinate multicenter trials for regenerative TBI therapies. The country's precision engineering heritage supports biocompatibility certification capabilities that shorten ISO 10993 testing timelines.
Japan
PMDA reimbursement determinations for cognitive rehabilitation devices influence procurement patterns across Asia-Pacific. Metropolitan hospital systems in Tokyo and Osaka install continuous brain tissue oxygen monitoring as standard protocol for severe TBI admissions. METI funding programs accelerate domestic development of robotic-assisted gait trainers for post-acute settings.
India
CDSCO regulatory harmonization with IMDRF standards reduces technical barriers for imported monitoring equipment. Federally Qualified Health Centers in Maharashtra and Karnataka lack specialized TBI rehabilitation capacity, creating demand for telehealth-enabled remote cognitive therapy platforms. Hospital procurement in Delhi-NCR and Chennai prioritizes cost-optimized intracranial pressure monitor configurations.
Traumatic Brain Injuries (TBI) Treatment Market Competitive Landscape
Capability concentration sits with mid-tier specialists mastering biocompatibility certification and chronic implant design; scale advantage sits with diversified medtech conglomerates leveraging integrated care pathway platforms. The market structures around three archetypes: neuromodulation system integrators, neurosurgical hardware specialists, and fluid management niche players. Dominant competitive moves include vendor consolidation into single-source monitoring ecosystem contracts and backward integration into semiconductor-grade microelectrode fabrication.
Among the diversified medtech conglomerates, Medtronic and Stryker Corporation exemplify contrasting scale strategies. Medtronic occupies a position as the neuromodulation system integrator archetype, while Stryker Corporation anchors the neurosurgical hardware specialist tier. Baxter International sits within the fluid management niche, representing defensive positioning where technical specification requirements create procurement stickiness. Johnson & Johnson's broad surgical portfolio exemplifies the diversified platform approach that competes across multiple intervention points in the TBI care continuum.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Stryker Corporation |
| Baxter International |
| Boston Scientific |
| Abbott Laboratories |
| Integra LifeSciences |
| Teva Pharmaceutical Industries Ltd. |
| SanBio |
| Others |
Value Network & Pricing Analysis
Minnesota and Massachusetts manufacturing clusters for neurostimulation pulse generators concentrate component supply, granting incumbent device manufacturers leverage over procurement committees negotiating bundled monitoring ecosystem contracts. This geographic concentration feeds directly into pricing power for closed-loop intracranial pressure management systems, where technical specification requirements create defensive moats against cost-optimized alternatives.
Pricing Analysis
Extended technical support contracts and multi-year monitoring service agreements drive lifetime value for implantable neurostimulation systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated closed-loop platforms from conventional catheter-based monitors and cost-optimized configurations for emerging markets. Price differentiation rests on ISO 10993 biocompatibility certification tier and after-sales service bundling intensity. Cost compression in standard-tier hardware is intensifying because hospital procurement committees are consolidating vendor relationships into single-source contracts. Federally Qualified Health Centers in Appalachian states exhibit highest price sensitivity; Veterans Affairs medical centers demonstrate lowest elasticity due to mandated protocol standardization.
Supply Chain Analysis
Flex, Jabil, and Benchmark Electronics hold contract manufacturing capacity for neurocritical care device assembly. Component sourcing concentrates in the United States, Germany, and Switzerland for microelectrode arrays and biocompatible implant materials. Raw material dependencies include semiconductor-grade silicon wafers, platinum-iridium alloys for electrode contacts, and medical-grade polymers for catheter housings. Single-source vulnerability runs through foundry allocation constraints for semiconductor-grade substrate fabrication. Distribution runs through integrated delivery network procurement committees in California and Illinois, with direct-to-hospital contracting displacing traditional distributor intermediaries for high-value monitoring ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across post-acute rehabilitation settings creates niche opportunities as CMS bundled payment expansion redistributes capital toward skilled nursing facilities and home care platforms lacking specialized TBI capacity.
For Market Incumbents: Insulate position by deepening backward integration into semiconductor-grade microelectrode fabrication, capturing supply security as foundry allocation constraints tighten. Secure multi-year sole-source monitoring ecosystem contracts with level I trauma centers in Texas, California, and New York before procurement committee consolidation completes. The threat of telehealth-enabled remote cognitive therapy platforms displacing inpatient rehabilitation revenue makes channel control through integrated care pathway software the priority defensive lever. For New Entrants and Emerging Players: Federally Qualified Health Centers in Appalachian and Southwestern states present the most penetrable white-space target, with specialized TBI rehabilitation capacity gaps creating demand for remote cognitive therapy platforms. Target skilled nursing facilities gaining bundled payment eligibility under CMS neuroplasticity coverage expansion, where incumbent presence remains thin. A go-to-market angle anchored in FDA breakthrough designation pursuit for closed-loop neuromodulation can compress time-to-reimbursement against established hardware vendors. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because hospital procurement behavior is shifting from point-solution purchasing toward single-source monitoring ecosystem contracts that favor integrated vendors. Acquisition target archetype: mid-tier specialists with ISO 10993 certification capabilities and chronic implant design expertise that fill gaps in neuromodulation hardware portfolios. The signal to watch is CMS finalization of remote patient monitoring codes specific to TBI surveillance, which would validate home care infrastructure investments and trigger hospital system capital reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Expedited review compresses time-to-reimbursement for novel intracranial pressure management systems. |
| Hospital System Partnership | Five-year sole-source monitoring ecosystem contracts with California integrated delivery networks lock out competitors. |
| Software Companion Development | Cloud-based electronic health record interoperability collapses information silos between trauma centers and skilled nursing facilities. |
| Backward Integration into Microelectrode Fabrication | Captive supply of semiconductor-grade substrates insulates against foundry allocation constraints. |
| Reimbursement Strategy | Coverage determination alignment with CMS neuroplasticity bundled payment models unlocks skilled nursing facility capital. |
Research Methodology
Cross-validation between primary interviews with neurocritical care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and clinical trial registries. Bottom-up demand modeling for intracranial pressure monitor installations and top-down market sizing through manufacturer revenue analysis were reconciled to produce segmentation outputs.
Calibration against historical adoption curves for neuromodulation technologies and neurosurgical navigation hardware informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, therapy type, delivery mode, and end user, with injury severity stratification and reimbursement pathway alignment as cross-cutting variables. CAGRs were derived from installed base growth rates and replacement cycle analysis, incorporating Veterans Affairs procurement forecasts and level I trauma center expansion pipelines as TBI-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medtech conglomerates into telehealth-enabled rehabilitation platforms would shift outcomes beyond modeled ranges. Competitive dynamics around FDA breakthrough designation pursuit, CMS coverage determination timing, and foundry capacity allocation for semiconductor-grade substrates represent specific risk factors requiring monitoring. Quarterly review of hospital procurement committee vendor consolidation announcements and remote patient monitoring code finalization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Cerebral Aneurysm Management Market
Neurology
CNS Treatment and Therapy Market
Neurology
Nerve Repair Market
Neurology
Neurological Biomarkers Market
Neurology
Optic Neuritis Treatment Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Spain Neurology Devices Market
Neurology
Spinal Cord Trauma Treatment Market
Neurology
Intracranial Aneurysm Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Narcolepsy Treatment Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Netherlands Neurology Devices Market
Neurology
Global Neuromarketing Market
Neurology
Spinal Laminoplasty Market
Neurology
Chronic Brain Damage Management Market