
 United States Neurology Devices Market | 2026-2036
United States Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Neurology Devices Market Analytics
Buyer consolidation among integrated delivery networks is realigning purchasing power toward fewer, larger hospital systems. Medtronic leverages its full-stack neurostimulation portfolio to anchor long-term supply agreements with these consolidated buyers. Boston Scientific competes through specialized interventional neurology catheters that address acute ischemic stroke workflows. Stryker sustains manufacturing scale in cranial stabilization and navigation platforms that dominate neurosurgical suites.
Neurology devices encompass instruments, implants, and electronic systems engineered for the diagnosis, surgical intervention, monitoring, or therapeutic modulation of central and peripheral nervous system disorders, typically requiring biocompatibility certifications and precision tolerances measured in micrometers. Their primary purpose is to restore neural function, manage chronic neurological conditions, or enable minimally invasive access to anatomically complex structures. Neurostimulation technology leads in margin contribution due to recurring implantable pulse generator replacement cycles and proprietary programming ecosystems. Interventional neurology applications represent the fastest-expanding segment as mechanical thrombectomy becomes standard of care for large-vessel occlusions. Diagnostic devices remain mature with stable replacement demand tied to EEG and EMG hardware refresh cycles in hospital electrophysiology departments.
FDA premarket approval pathways and CMS national coverage determinations jointly shape market access timelines and reimbursement eligibility for novel neurology devices. The FDA breakthrough devices program compresses review timelines for technologies addressing irreversibly debilitating conditions, while state-level certificate-of-need regulations constrain capital equipment deployment in concentrated markets. Stakeholders must monitor evolving CMS evidence requirements for neurostimulation indications and preemptive FDA engagement on software-as-a-medical-device classifications for AI-enabled diagnostic platforms.
Market Dynamics
Hospital system consolidation is compressing neurology device procurement into fewer integrated delivery networks, concentrating purchasing power and forcing vendors to restructure pricing and service models around multi-year enterprise agreements rather than transactional sales.
Growth Catalysts
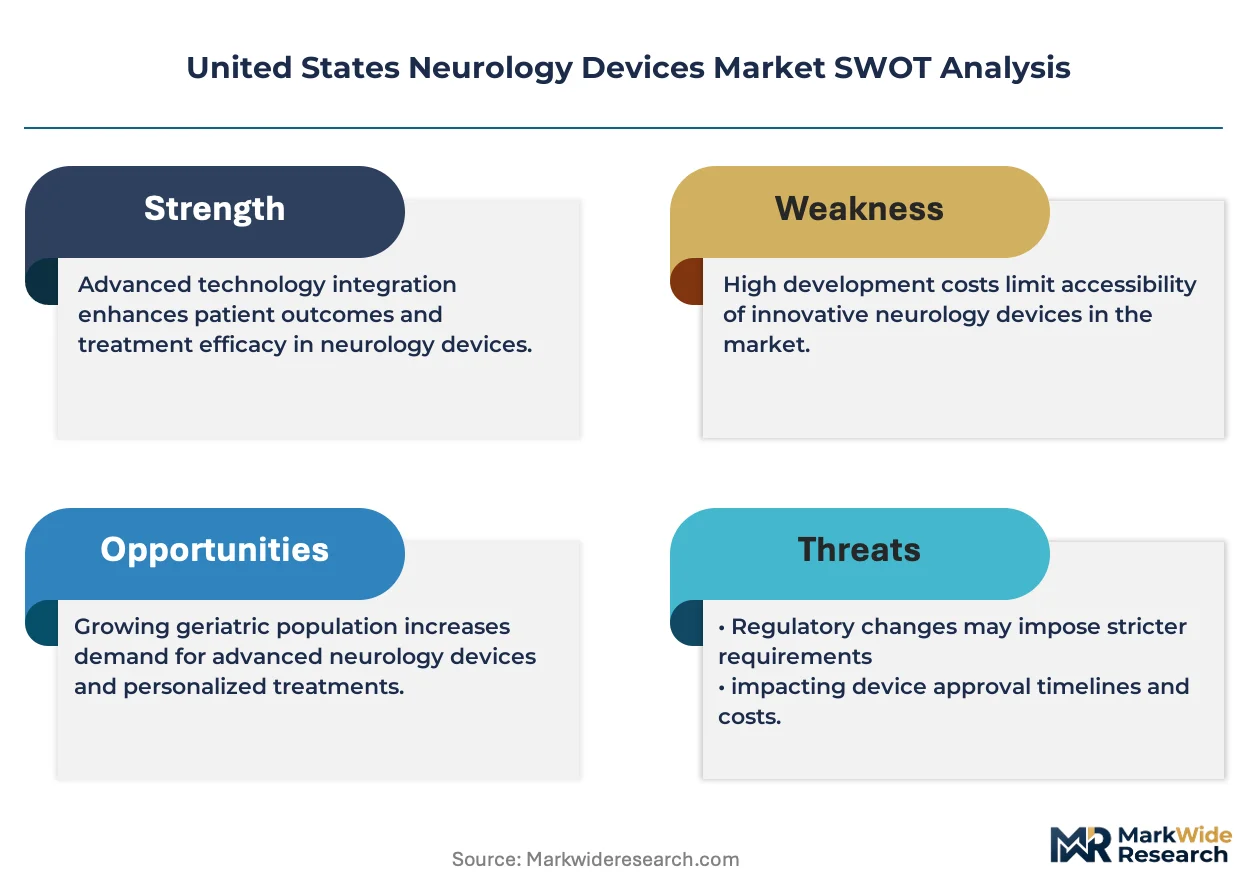
- Mechanical thrombectomy:Large-vessel occlusion treatment protocols now mandate endovascular intervention, expanding catheter demand across stroke centers in Texas, Florida, and New York.
- FDA breakthrough device designation:Expedited review pathways compress commercialization timelines for neuromodulation therapies addressing treatment-resistant depression and epilepsy.
- Academic medical center clustering:NIH-funded neurosurgical research hubs in Massachusetts, California, and Pennsylvania generate sustained demand for navigation platforms and intraoperative monitoring systems.
Market Restraints
- Implantable pulse generator battery costs:Lithium-ion cell price volatility and rare earth supply constraints squeeze margins on neurostimulator hardware.
- Certificate-of-need regulations:State-level CON laws in New York, Illinois, and Washington restrict capital equipment deployment for MRI-guided focused ultrasound systems.
- Biocompatibility certification timelines:ISO 10993 testing protocols for novel polymer coatings extend product development cycles by 18-24 months.
Strategic Opportunities
- Community hospital stroke certification:Joint Commission thrombectomy-ready designations in underserved Midwest and Mountain West markets expand addressable catheter volumes.
- Remote programming ecosystems:Bluetooth-enabled neurostimulator adjustments reduce clinic visit burden for patients in rural Montana, Wyoming, and Alaska.
- AI-enabled EEG interpretation:FDA software-as-a-medical-device pathways for seizure detection algorithms open diagnostic software revenue streams independent of hardware sales.
Industry Challenges
- Neurointerventionalist training pipelines:Fellowship program capacity constraints limit operator availability to deploy new thrombectomy devices at scale.
- Legacy EMG system integration:Proprietary data formats from incumbent diagnostic equipment vendors obstruct seamless connectivity with cloud-based analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Neurology Devices Market |
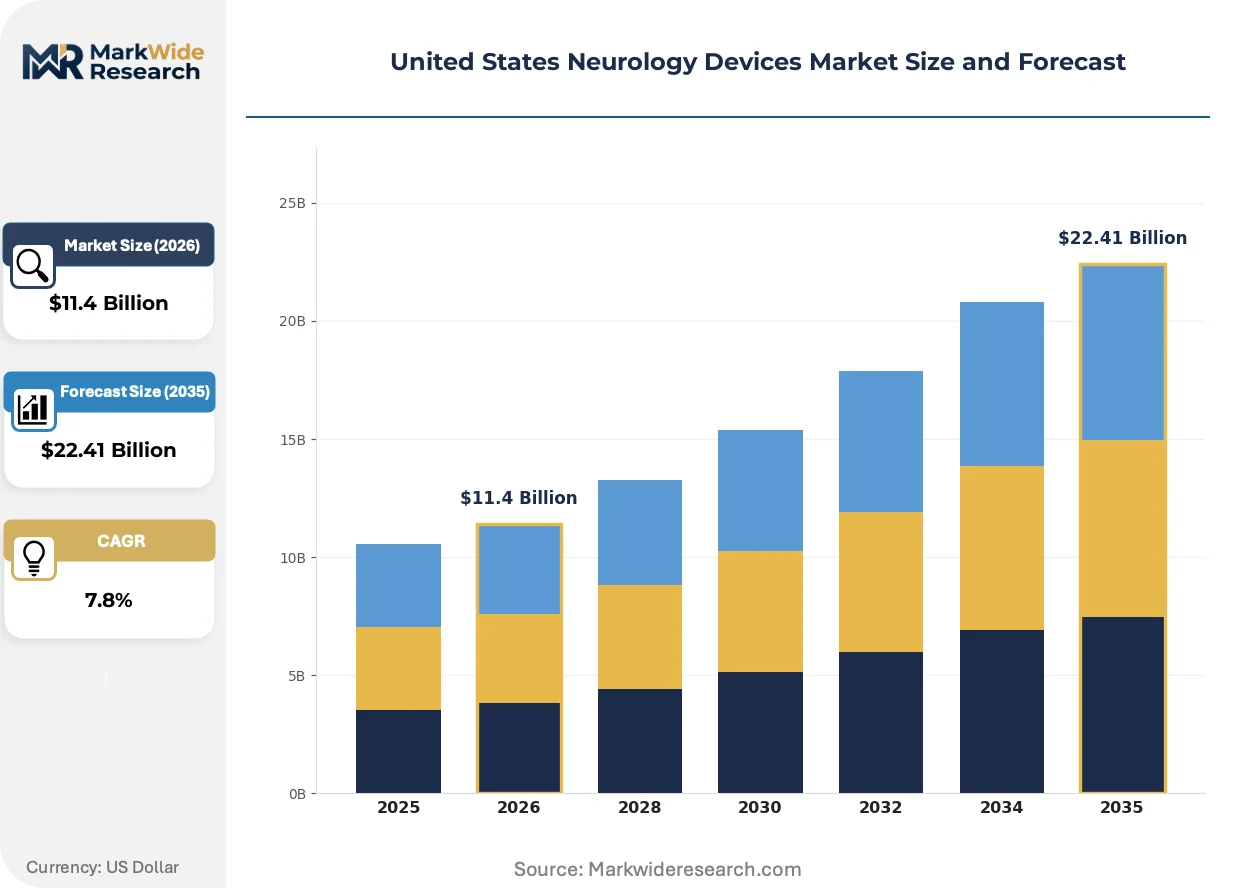
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.41 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Diagnostic Devices, Surgical Instruments, Monitoring Equipment, Therapeutic Devices Application: Electroencephalography, Interventional Neurology, Neurosurgery, Pain Management End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Technology: Neurostimulation, Imaging Technologies, Biomarkers, Robotics |
| Companies Covered | Medtronic, Boston Scientific, Stryker, Abbott Laboratories, B. Braun, Johnson and Johnson, Penumbra, Smith & Nephew, MicroPort Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Neurology Devices Market Evolving Landscape
Neurology device development is pivoting toward closed-loop therapeutic systems and software-defined functionality, blurring hardware-software boundaries and reshaping how manufacturers capture recurring revenue.
Closed-loop responsive neurostimulation is decentralizing seizure management from epilepsy monitoring units to ambulatory settings. Implantable systems with cortical sensing and algorithmic stimulus adjustment are gaining traction among level 3 and 4 epilepsy centers. This capability compression is eliminating the need for continuous inpatient video-EEG correlation and shifting reimbursement toward remote management codes.
CMS national coverage determinations for spinal cord stimulation now mandate specific pain reduction metrics and psychological screening protocols prior to permanent implantation. Device manufacturers must embed patient-reported outcome collection into their programming workflows to maintain reimbursement eligibility. Chronic pain practices in Florida, Texas, and Arizona are restructuring care pathways to meet these evidentiary requirements.
Integrated delivery networks are consolidating neurosurgical device procurement under value-analysis committees with standardized evaluation scorecards. Independent community hospitals are losing direct purchasing autonomy as regional systems centralize vendor negotiations and capital allocation decisions. This concentration is most visible in the Northeast, where Catholic health systems and academic alliances control the majority of cranial and spinal implant volumes.
United States Neurology Devices Market Segmentation
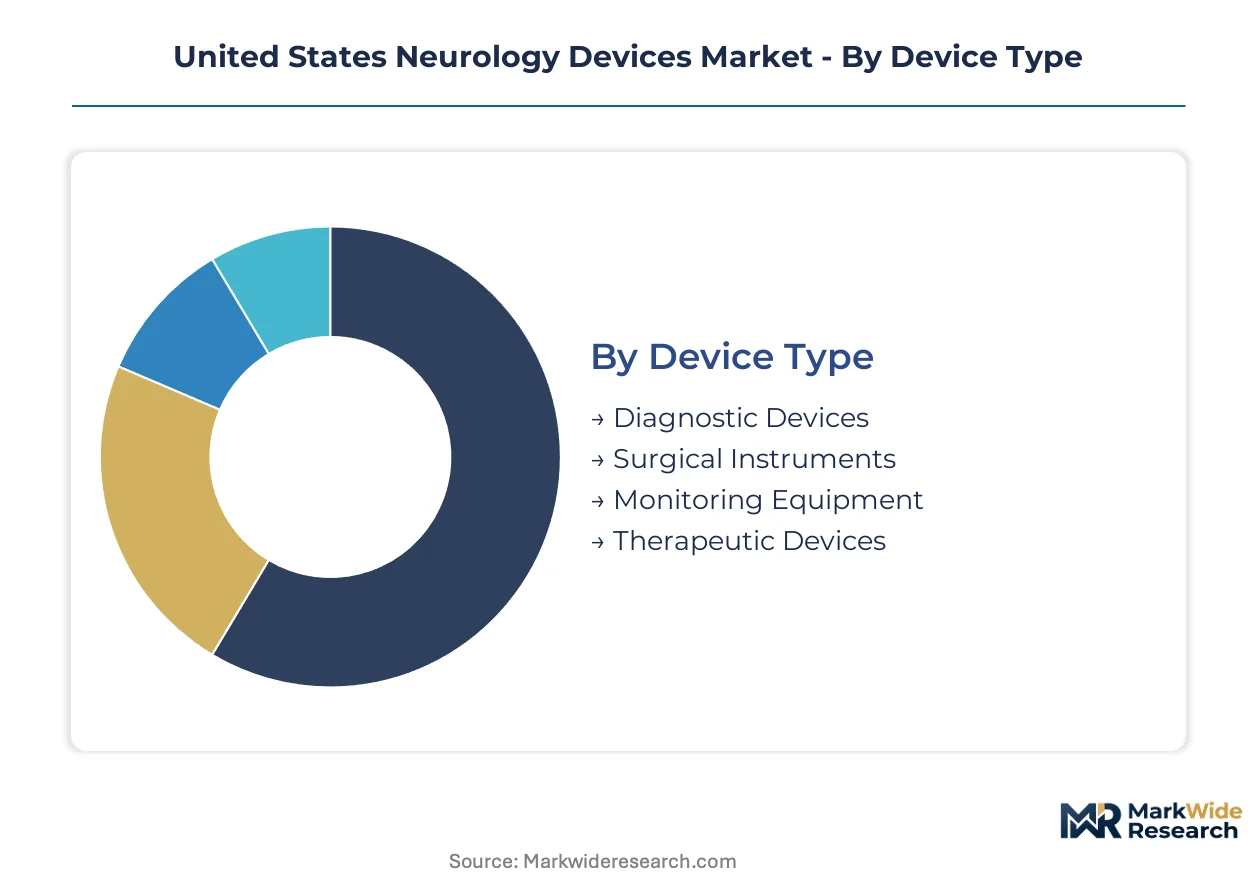
Segmentation in the United States neurology devices market reveals how purchasing power, clinical workflows, and reimbursement pathways concentrate demand across distinct technology and customer categories. Understanding these splits enables vendors to align R&D investment with where volume and margin actually accumulate.
Device Type:
Volume concentrates in surgical instruments and monitoring equipment purchased through consolidated hospital contracts, while premium pricing attaches to implantable therapeutic systems with recurring revenue streams.
- Diagnostic Devices:EEG amplifiers, EMG systems, and intraoperative monitoring hardware with proprietary data formats. Demand clusters in academic medical centers across Massachusetts and Pennsylvania where NIH-funded electrophysiology research drives replacement cycles.
- Surgical Instruments:Cranial fixation systems, navigation platforms, and microdissection tools engineered to micrometer tolerances. Neurosurgical suites in California and Texas account for disproportionate procurement volume as stroke center certification expands.
- Monitoring Equipment:Continuous EEG and intracranial pressure systems.
- Therapeutic Devices:Implantable pulse generators and drug delivery pumps.
Today's leader: Surgical Instruments. Tomorrow's challenger: Therapeutic Devices.
Application:
Interventional neurology applications command the steepest expansion trajectory as mechanical thrombectomy protocols displace intravenous tPA across stroke centers, while electroencephalography maintains stable replacement demand tied to hardware refresh cycles.
- Electroencephalography:Scalp and intracranial electrode arrays with amplifier systems for seizure localization and sleep disorder diagnosis. Hospital electrophysiology departments in the Northeast and Midwest generate consistent demand for 256-channel and higher-density configurations.
- Interventional Neurology:Aspiration catheters, stent retrievers, and distal access platforms for large-vessel occlusion treatment. Florida, Texas, and New York stroke centers drive catheter volumes as Joint Commission thrombectomy-ready certifications proliferate.
- Neurosurgery:Cranial and spinal access systems.
- Pain Management:Spinal cord and peripheral nerve stimulation systems.
Interventional neurology is expanding most quickly. Pain management faces CMS evidentiary hurdles.
End User:
Hospital procurement consolidation is squeezing out independent purchasing autonomy, while homecare settings emerge as a nascent channel for remote neurostimulator programming and ambulatory EEG monitoring.
- Hospitals:Integrated delivery networks and academic medical centers with value-analysis committees standardizing vendor scorecards. Catholic health systems in the Northeast and regional alliances in California centralize cranial and spinal implant negotiations.
- Clinics:Private neurology practices and ambulatory surgery centers.
- Research Laboratories:NIH-funded institutions and device development partnerships.
- Homecare Settings:Remote patient monitoring and therapy management platforms.
Hospitals retain procurement dominance. Homecare settings are climbing the fastest as reimbursement shifts toward remote management codes.
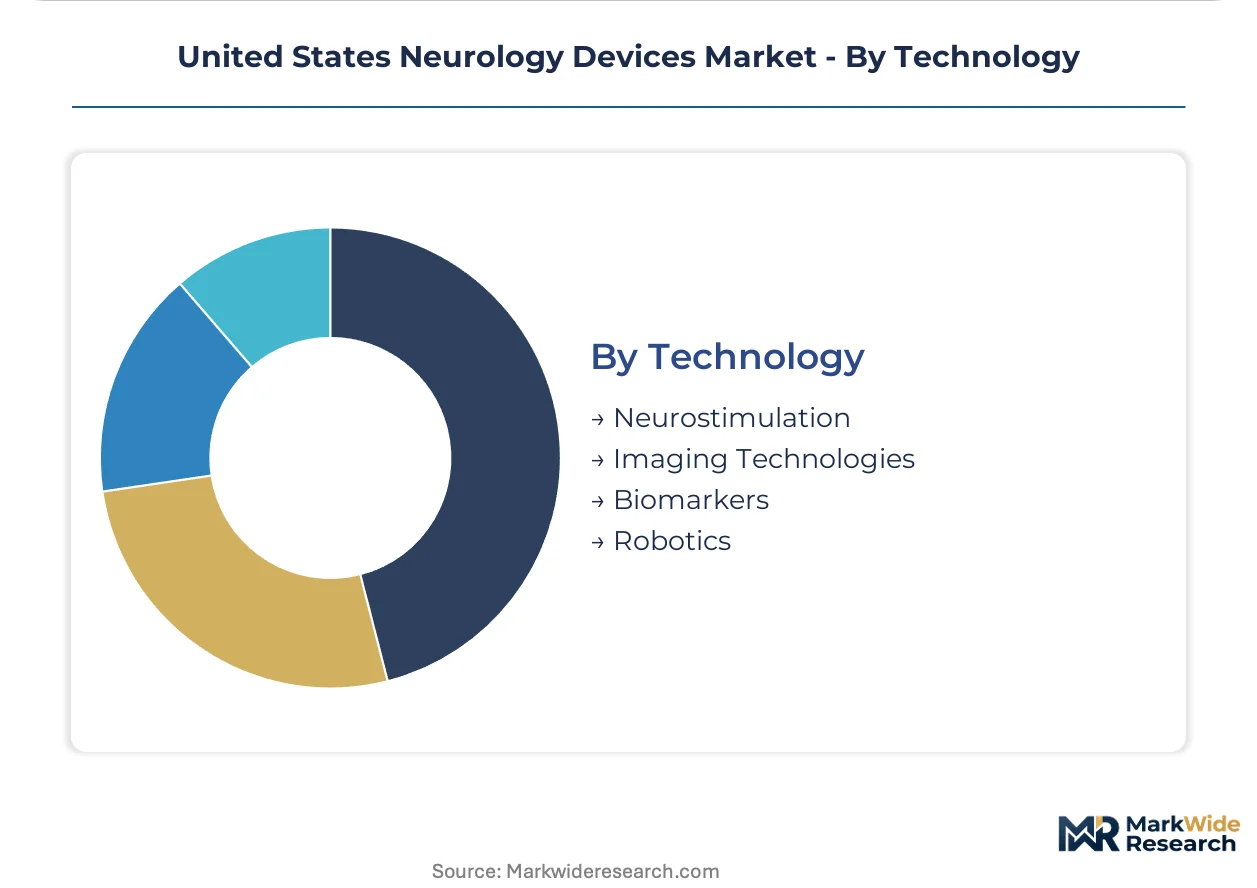
Technology:
Neurostimulation technology anchors margin contribution through proprietary programming ecosystems and replacement cycles, while robotics and biomarkers remain development-stage with longer commercialization timelines.
- Neurostimulation:Implantable pulse generators with cortical sensing and closed-loop algorithms for epilepsy and movement disorders. Level 3 and 4 epilepsy centers in Pennsylvania and Ohio adopt responsive neurostimulation as inpatient monitoring requirements compress.
- Imaging Technologies:MRI-guided focused ultrasound and intraoperative navigation systems. Certificate-of-need regulations in New York and Illinois constrain capital deployment despite clinical efficacy data.
- Biomarkers:Cerebrospinal fluid assays and blood-based neurological markers.
- Robotics:Stereotactic guidance and surgical assistance platforms.
Neurostimulation captures current margin leadership. Imaging technologies face regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in neurology device procurement intensity, with German hospital networks emphasizing MRI-guided focused ultrasound adoption while American integrated delivery networks concentrate purchasing power for neurostimulation systems.
Northeast Corridor
Academic medical centers in Massachusetts and Pennsylvania drive demand for intraoperative navigation platforms and responsive neurostimulation systems. NIH-funded electrophysiology research at Boston Children's Hospital and the University of Pennsylvania generates consistent hardware replacement cycles. FDA breakthrough device designations for closed-loop epilepsy therapies accelerate commercialization timelines for manufacturers targeting level 3 and 4 epilepsy centers clustered in Greater Boston and Philadelphia.
California
Stroke center certification expansion across Los Angeles and San Francisco Bay Area metro regions elevates catheter demand for mechanical thrombectomy workflows. University of California medical centers anchor neurosurgical research funding that sustains procurement of cranial stabilization and navigation platforms. State-level environmental regulations under the California Air Resources Board influence manufacturing facility siting decisions for implantable pulse generator production.
Texas
Joint Commission thrombectomy-ready certifications proliferate across Houston and Dallas-Fort Worth hospital systems, expanding addressable volumes for aspiration catheters and stent retrievers. Texas Medical Center concentration creates dense operator training pipelines for neurointerventionalists. Certificate-of-need regulations remain absent, permitting rapid capital equipment deployment for MRI-guided focused ultrasound systems in private health systems.
Florida
Chronic pain practices in Miami and Tampa restructure care pathways to meet CMS national coverage determination requirements for spinal cord stimulation. Patient-reported outcome collection workflows embed into programming systems to maintain reimbursement eligibility. Medicare Advantage penetration rates exceed national averages, creating pricing pressure on neurostimulator hardware while expanding remote programming adoption.
Midwest
Community hospital stroke certification in Illinois and Ohio expands catheter addressable markets beyond academic centers. Cleveland Clinic and Northwestern Medicine anchor demand for intraoperative monitoring systems. State-level certificate-of-need laws in Illinois restrict capital deployment for high-end imaging systems, channeling investment toward therapeutic device categories with clearer reimbursement pathways.
United States Neurology Devices Market Competitive Landscape
Irish-domiciled producers anchor one tier of the neurology devices market; American and Swiss specialists hold differentiated positions in neurostimulation and interventional segments. Market structure tilts toward consolidation among integrated delivery network suppliers, with three to four enterprise-scale vendors capturing majority procurement volume. Two strategic archetypes dominate: full-stack neurostimulation portfolio providers and focused interventional catheter specialists. Competitive moves concentrate on multi-year enterprise supply agreements and FDA premarket approval pathway navigation for breakthrough device designations.
Among American-domiciled enterprises, Medtronic exemplifies the full-stack neurostimulation archetype through its implantable pulse generator and proprietary programming ecosystem positioning. Boston Scientific occupies a specialist tier in interventional neurology, with its catheter portfolio aligned to mechanical thrombectomy workflow standardization. Stryker represents the surgical instrumentation scale tier, anchoring cranial stabilization and navigation platform presence in consolidated hospital procurement. These three enterprises collectively illustrate how vendor structure maps to buyer consolidation patterns across academic medical centers and integrated delivery networks.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Stryker |
| Abbott Laboratories |
| B. Braun |
| Johnson and Johnson |
| Penumbra |
| Smith & Nephew |
| MicroPort Scientific Corporation |
| Others |
Value Network & Pricing Analysis
California Air Resources Board emissions mandates for lithium-ion cell manufacturing gate qualified supply for implantable pulse generator producers and anchor premium-tier pricing access for neurostimulator vendors with compliant production footprints. FDA breakthrough device designation pathways further stratify pricing power between certified and non-certified therapeutic categories.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for lithium-ion cells used in implantable pulse generators, compressing hardware margins for neurostimulator manufacturers. Pricing stratifies across FDA breakthrough-designated, PMA-approved, and 510(k)-cleared tiers, with reimbursement eligibility and battery chemistry grade as primary differentiation drivers. Cost compression in standard-tier catheter categories is intensifying because of GPO-negotiated enterprise contracts at consolidated hospital systems. Community hospital stroke centers exhibit highest price sensitivity; academic medical centers with NIH funding demonstrate lowest sensitivity to capital equipment premiums.
Supply Chain Analysis
Refurbishment flows for explanted neurostimulators and trade-in programs for EEG amplifiers create reverse-logistics revenue streams that subsidize new device pricing. Component sourcing concentrates in China for rare earth magnets, South Korea for lithium-ion cells, and Germany for precision micromachined surgical instruments. Raw material dependencies include neodymium for pulse generator housings, platinum-iridium for electrode contacts, and medical-grade silicone for lead insulation. Single-source vulnerability for rare earth processing in China presents structural supply risk. Distribution runs through integrated delivery network value-analysis committees and specialized neurology GPOs rather than direct hospital contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA breakthrough device designations and CMS national coverage determinations jointly accelerate demand cycles for qualifying technologies.
For Market Incumbents: Extend proprietary programming ecosystem lock-in through Bluetooth-enabled remote adjustment capabilities that reduce clinic visit burden and embed patient-reported outcome collection workflows. Defend against interventional neurology catheter specialists by anchoring multi-year enterprise supply agreements with consolidated hospital systems. Capacity addition in Texas for MRI-guided focused ultrasound manufacturing represents a critical lever for markets without certificate-of-need constraints. For New Entrants and Emerging Players: Direct-to-clinician digital education platforms bypass incumbent GPO relationships and enable targeted penetration of community hospital stroke certification programs in the Mountain West and Midwest. The most penetrable segment lies in AI-enabled EEG interpretation software under FDA software-as-a-medical-device pathways, where diagnostic revenue decouples from hardware sales. Remote neurostimulator programming for rural Medicare Advantage populations offers a second white-space target with favorable reimbursement tailwinds. For Investors and Strategic Acquirers: Valuations sit cheapest among interventional neurology catheter specialists without integrated delivery network enterprise agreements, presenting consolidation opportunities as hospital procurement concentration accelerates. Long-term viability across the projection horizon hinges on regulatory pathway execution rather than manufacturing scale alone. The signal to watch is Joint Commission thrombectomy-ready certification velocity in underserved states as an indicator of addressable market expansion for catheter volumes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited review compresses commercialization timelines for closed-loop epilepsy therapies at level 3 and 4 centers. |
| Hospital System Partnership | Multi-year enterprise agreements with Catholic health systems in the Northeast anchor cranial implant procurement volume. |
| Software Companion Development | AI-enabled seizure detection algorithms open diagnostic revenue streams independent of EEG hardware replacement cycles. |
| Reimbursement Strategy | CMS national coverage determination alignment for spinal cord stimulation embeds patient-reported outcome workflows into programming systems. |
| CE Marking Pathway | European market access for responsive neurostimulation systems diversifies revenue beyond FDA-regulated United States demand. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down neurostimulator shipment tracking forms the analytical core of this study. Primary interviews with neurointerventionalists, hospital value-analysis committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) and PMA filings, CMS national coverage determination records, hospital procurement databases, and NIH research funding disclosures. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrices map implantable pulse generator replacement cycles, catheter consumption per thrombectomy procedure, and navigation platform refresh rates to derive volume and value outputs across the projection horizon. Segmentation dimensions include device type, application workflow, end-user procurement channel, and technology maturity tier. CAGRs were derived from procedure volume growth, reimbursement pathway expansion, and replacement cycle compression. Forecast inputs incorporate Joint Commission certification velocity, FDA breakthrough designation flow, and CMS evidence requirement evolution.
The model assumes a particular technology adoption path for closed-loop responsive neurostimulation; alternative pathways for open-loop systems or non-invasive neuromodulation would alter the outlook. Forecasts reflect assumptions regarding reimbursement stability, training pipeline capacity, and rare earth supply continuity. Practitioners should monitor state-level certificate-of-need regulatory shifts and lithium-ion cell price volatility for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Brain Ischemia Market
Neurology
Chile Neurology Devices Market
Neurology
Mexico Neurology Devices Market
Neurology
Movement Disorder Market
Neurology
Italy Neurology Devices Market
Neurology
Acute Repetitive Seizures Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
Intracranial Aneurysm Market
Neurology
Neurocutaneous Disorders Market
Neurology
Spain Neurology Devices Market
Neurology
Global Neuromarketing Market
Neurology
India Neurology Devices Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Neurology Digital Therapeutics Market