
 Chile Neurology Devices Market | 2026-2036
Chile Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Neurology Devices Market Outlook
CE marking alignment under the EU Medical Device Regulation is repositioning import compliance costs for Chilean distributors sourcing European neurology equipment. Medtronic PLC leverages its neurostimulation portfolio to anchor premium segment positioning across Santiago's private hospital chains. Stryker Corporation competes through specialized cranial access and neurovascular platforms tailored to Latin American surgical workflows. Boston Scientific Corporation differentiates via deep brain stimulation systems calibrated for movement disorder protocols in Chilean neurology departments.
Neurology devices encompass instruments engineered for diagnosis, intervention, and monitoring of central and peripheral nervous system pathologies, typically operating within precision tolerances of 0.1 millimeters for invasive neurosurgical applications and utilizing biocompatible polymers or titanium alloys for prolonged intracranial residence. These systems serve stroke triage, epilepsy localization, chronic pain modulation, and neurodegenerative disease tracking across hospital and ambulatory settings. Neurostimulation devices command disproportionate margin pools due to programmable pulse generator replacement cycles and specialized programming services. Imaging techniques including MRI and CT scanners absorb the largest capital allocation share, though monitoring systems register the fastest adoption velocity as remote neurology expands beyond tertiary centers.
Chile's national pharmaceutical regulator, the Instituto de Salud Pública, enforces medical device conformity assessment parallel to ANMAT harmonization, while ISO 13485 certification governs quality management systems for manufacturers supplying the Chilean market. These frameworks elevate documentation burdens for new entrants but simultaneously reduce post-market surveillance risk for established suppliers. Stakeholders must weigh reimbursement pathway clarity against procurement decentralization as regional health services gain autonomous purchasing authority.
Market Dynamics
Public-private partnerships in Santiago's tertiary hospital network are accelerating neurodiagnostic infrastructure modernization, creating concentrated procurement windows that favor suppliers with established service networks over pure equipment vendors.
Growth Catalysts
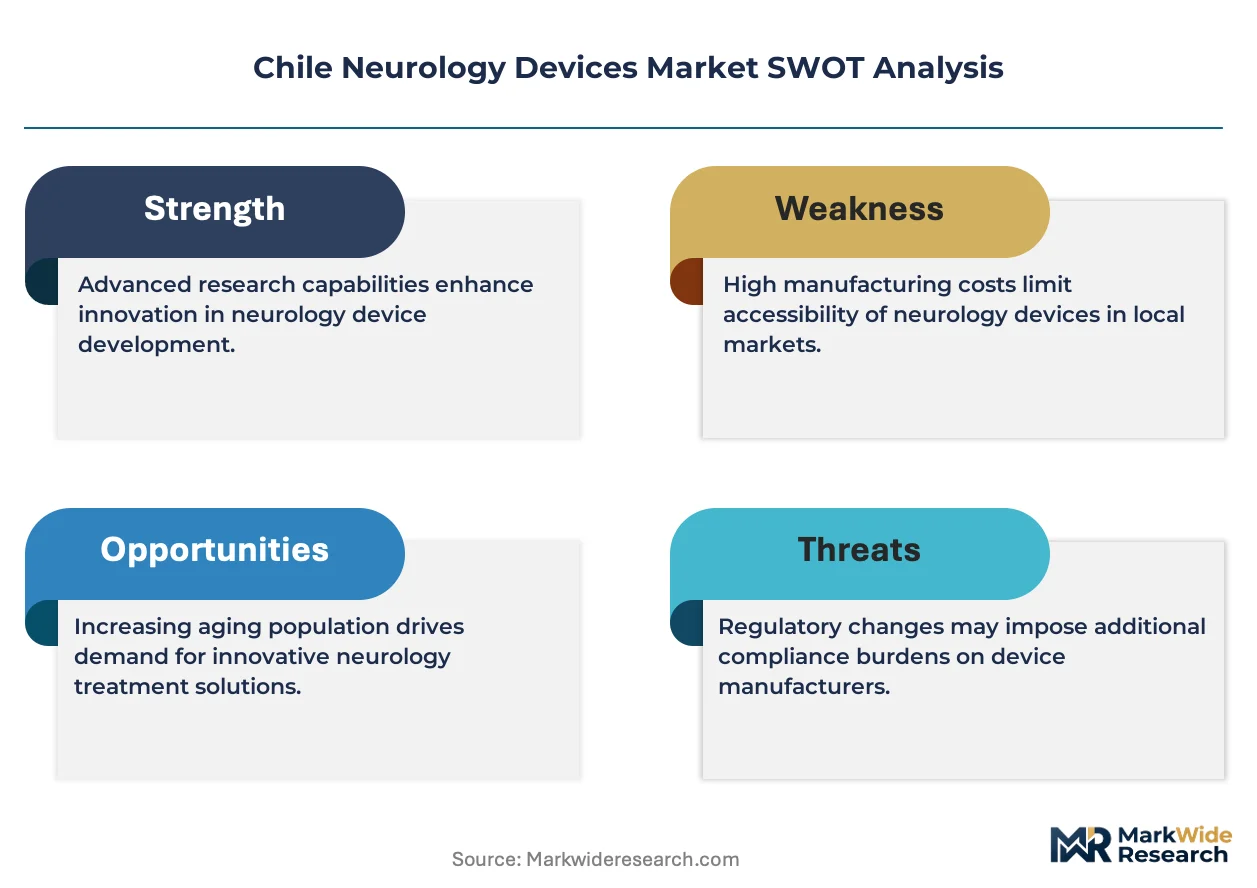
- Aging Demographics:Chile's expanding elderly population drives stroke incidence and neurodegenerative disease burden, expanding the addressable patient base for interventional neurology across metropolitan health networks.
- ISP Registration Reforms:The Instituto de Salud Pública has streamlined medical device conformity assessment timelines, reducing market entry delays for advanced neurostimulation and neurovascular platforms.
- Neuroimaging Capacity:MRI and CT scanner deployment in regional health services is accelerating triage protocols and surgical planning precision beyond Santiago's core hospitals.
Market Restraints
- Capital Equipment Intensity:Precision neurosurgical systems require titanium alloy components and biocompatible polymer sourcing, exposing distributors to raw material cost volatility and extended procurement cycles.
- Geographic Supply Concentration:Advanced neurology device manufacturing concentrates in European and North American production clusters, creating import dependency and currency exposure for Chilean procurement authorities.
- Technical Specialization Barriers:Deep brain stimulation programming and neurostimulator calibration demand specialized biomedical engineering expertise that remains scarce outside Santiago's academic medical centers.
Strategic Opportunities
- Regional Health Service Autonomy:Decentralized purchasing authority in Valparaíso, Biobío, and Antofagasta regions creates first-mover advantages for suppliers establishing regional technical service presence.
- Remote Neurology Expansion:Telemedicine-enabled EEG monitoring and cloud-based neurophysiology interpretation is converging with ambulatory care networks, extending device utilization beyond tertiary hospital boundaries.
- ANMAT Harmonization:Regulatory alignment with Argentina's pharmaceutical regulator creates pathway efficiencies for cross-border product registration and regional scale economies.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Neurostimulator programming, intraoperative neuromonitoring, and complex cranial access system operation require specialized training pipelines that Chilean technical institutes have not scaled to match equipment deployment rates.
- ISO 13485 Documentation Burden:Quality management system certification demands extensive technical file preparation that extends supplier onboarding timelines and elevates compliance costs for emerging manufacturers.
- Legacy System Integration Friction:New neurodiagnostic platforms must interface with existing hospital information systems and PACS infrastructure, complicating deployment and elevating total cost of ownership calculations in procurement evaluations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Neurology Devices Market |
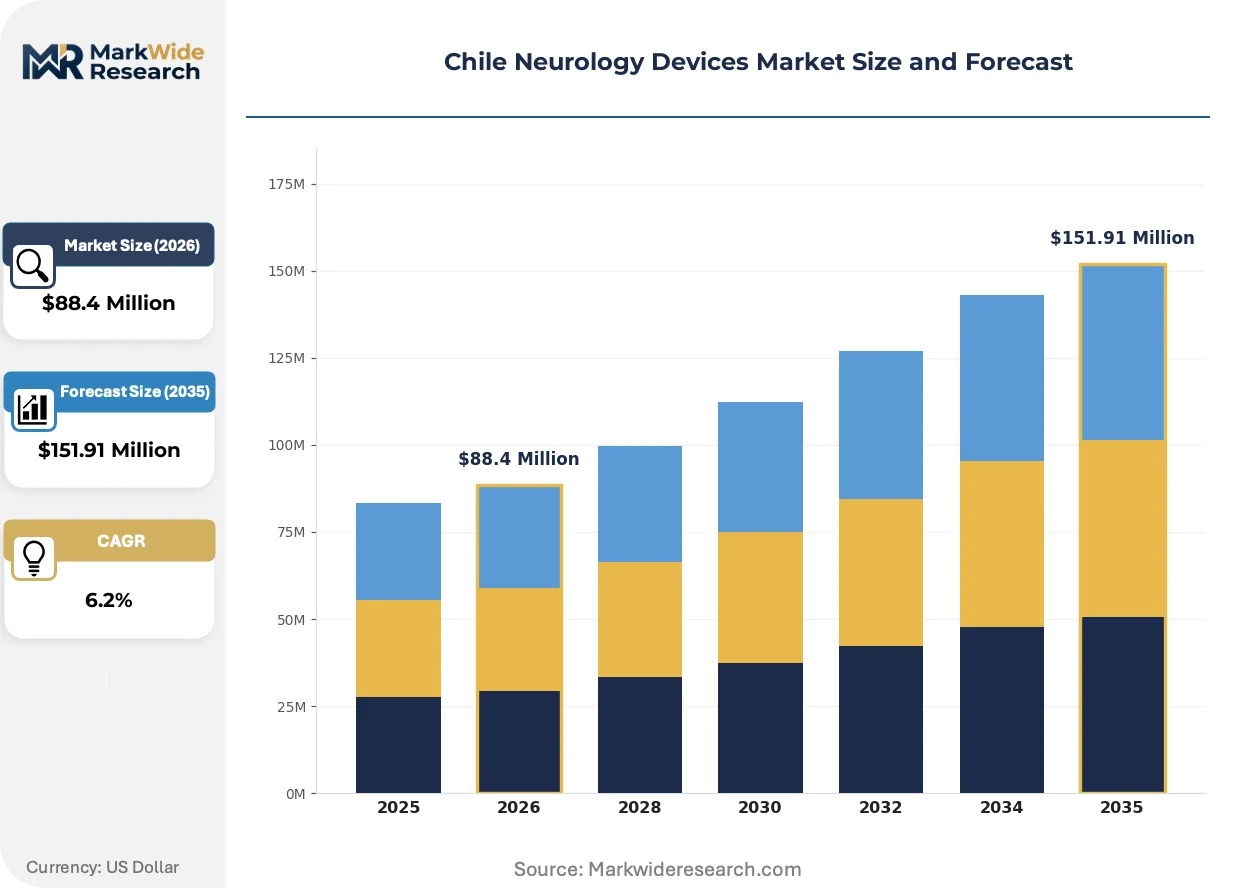
| Market Size in 2026 | $88.4 Million |
| Market Size in 2035 | $151.91 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalography Devices, Neurostimulation Devices, MRI Machines, CT Scanners End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers Technology: Invasive, Non-invasive, Imaging Techniques, Monitoring Systems Application: Stroke Management, Pain Relief, Neurorehabilitation, Diagnostics |
| Companies Covered | B Braun SE, Stryker Corporation, Medtronic PLC, Abbott Laboratories, Johnson & Johnson, Nihon Kohden Corporation, Smith & Nephew, Elekta AB, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Neurology Devices Market Strategic Shifts
Neurology device innovation in Chile centers on precision miniaturization, regulatory pathway optimization, and service model restructuring that shifts value capture from capital sales toward recurring revenue streams.
Robotic-assisted cranial access platforms is converging with intraoperative imaging navigation to enable sub-millimeter precision in deep brain stimulation electrode placement. Santiago's private hospital chains are adopting these integrated systems at accelerated cadence compared to public institutions. This convergence is compressing surgical learning curves and expanding treatable patient populations for movement disorder interventions.
CE marking alignment under the EU Medical Device Regulation is repositioning import compliance frameworks for Chilean distributors sourcing European neurology equipment. The MDR's enhanced clinical evidence requirements are filtering supplier portfolios toward established manufacturers with robust post-market surveillance infrastructure. Neurostimulation device categories face the steepest documentation elevation, advantaging incumbents with legacy technical files.
Service unbundling from equipment procurement is restructuring competitive dynamics across Chile's hospital procurement landscape. Private hospital chains are separating device acquisition from programming, maintenance, and training contracts, creating specialized service provider niches. This pattern is most visible in Santiago's premium neurology departments, where neurostimulator programming services now command discrete budget lines and specialized vendor relationships.
Chile Neurology Devices Market Segmentation
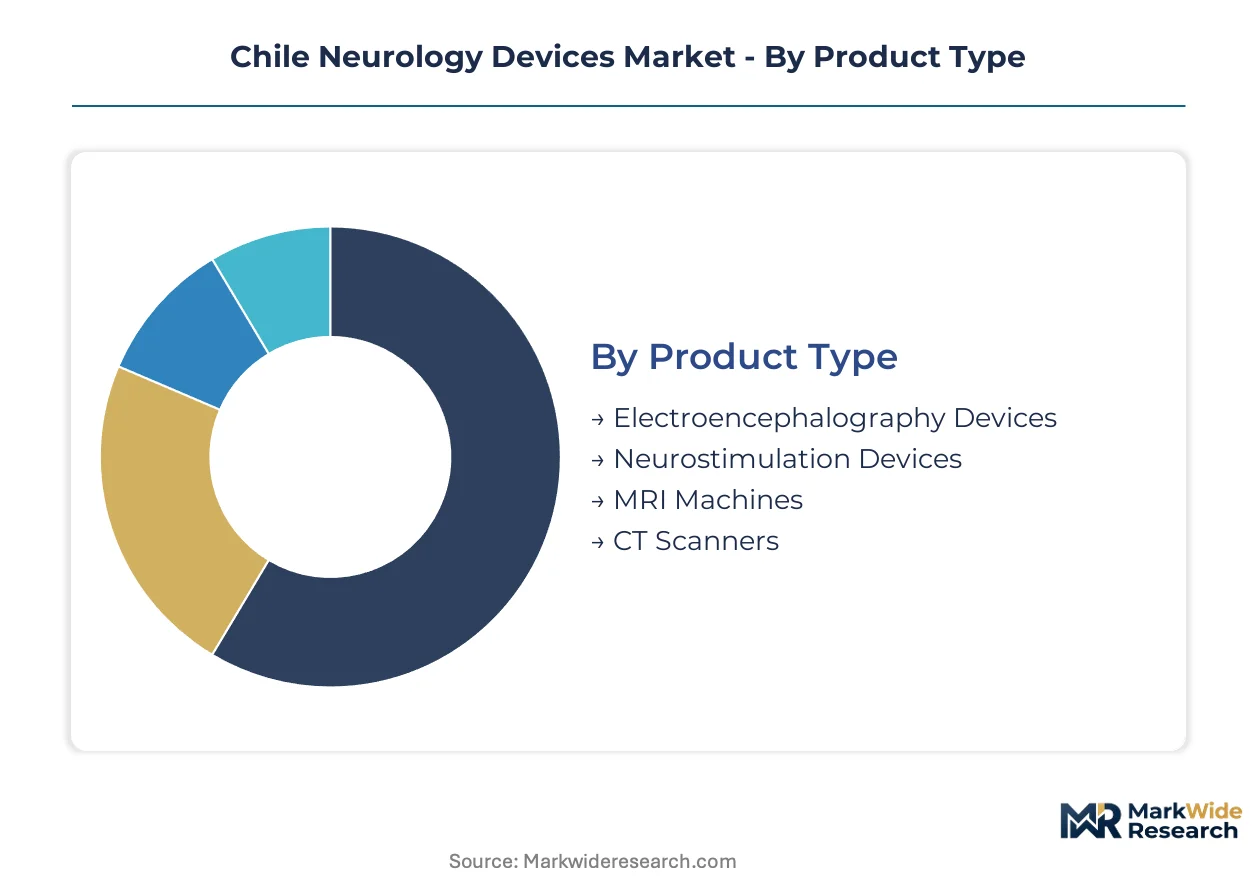
Segmentation in Chile's neurology devices market reveals how procurement priorities diverge across care settings and clinical applications. Understanding these divisions exposes where capital concentrates and where service models must adapt to distinct technical requirements.
Product Type:
Cost tier differentiation separates high-capital imaging platforms from programmable therapeutic systems and portable diagnostic tools.
- Neurostimulation Devices:Implantable pulse generators and electrode arrays utilizing biocompatible polymers for prolonged intracranial residence. Santiago's private hospital chains concentrate demand for deep brain stimulation systems, driven by movement disorder patient volumes and specialized programming service availability.
- MRI Machines:Superconducting magnet systems operating at 1.5T and 3T field strengths with dedicated neurological coil configurations. Deployment concentrates in Santiago's tertiary hospital network, where public-private partnerships are modernizing neurodiagnostic infrastructure and expanding surgical planning capabilities.
- Electroencephalography Devices:Multi-channel amplifiers with sub-microvolt resolution for epilepsy localization and sleep disorder assessment.
- CT Scanners:Helical acquisition systems with sub-millimeter slice thickness for acute stroke triage protocols.
Volume sits with MRI Machines; growth tilts toward Neurostimulation Devices.
End User:
Application maturity and reimbursement pathway clarity determine where device utilization expands most aggressively.
- Hospitals:Tertiary centers with neurosurgical suites, angiography capabilities, and 24-hour stroke response protocols. Santiago's metropolitan centers anchor procurement, with regional health services in Valparaíso and Biobío gaining autonomous purchasing authority.
- Clinics:Ambulatory neurology practices with diagnostic focus and limited interventional capacity. Concentration in Santiago's urban core reflects patient density and specialist availability constraints.
- Research Institutions:Academic medical centers with clinical trial infrastructure and neuroimaging research protocols.
- Rehabilitation Centers:Post-acute facilities with neuroplasticity-focused therapeutic device requirements.
Procurement authority concentrates in Hospitals; Clinics are expanding most quickly as remote neurology extends beyond tertiary boundaries.
Technology:
Margin structure and regulatory burden intensity separate implantable therapeutic systems from external diagnostic platforms.
- Imaging Techniques:MRI and CT modalities absorbing the largest capital allocation share across Chilean health networks. Santiago's private hospital chains deploy these systems at accelerated cadence compared to public institutions, compressing surgical planning timelines.
- Monitoring Systems:Continuous EEG and intracranial pressure monitoring platforms with cloud-based data transmission. Regional health services outside Santiago drive adoption velocity as telemedicine-enabled neurology expands infrastructure requirements.
- Invasive:Cranial access systems, neurovascular catheters, and implantable pulse generators requiring sterile surgical deployment.
- Non-invasive:Transcranial magnetic stimulation and external neuromodulation platforms with ambulatory application protocols.
Capital deployment favors Imaging Techniques; Monitoring Systems gain share fastest through remote care expansion.
Application:
Patient volume scale and procedure reimbursement rates determine where device manufacturers prioritize service network investments.
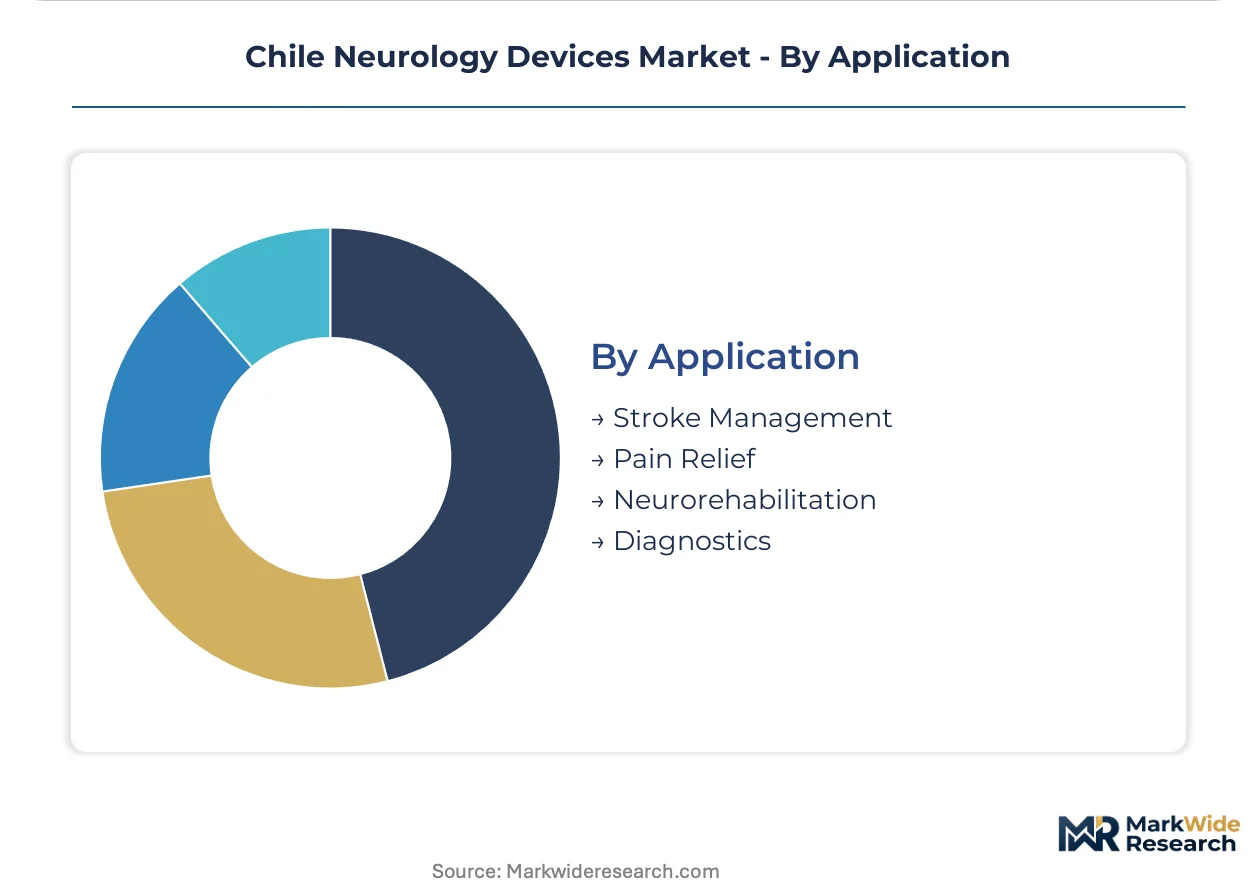
- Stroke Management:Acute triage protocols combining CT angiography, mechanical thrombectomy systems, and neurocritical care monitoring. Chile's aging demographics expand addressable patient base across metropolitan health networks, with regional services accelerating neuroimaging capacity deployment.
- Pain Relief:Spinal cord stimulation and peripheral nerve modulation systems with programmable parameter adjustment. Demand concentrates in Santiago's private hospital chains where specialized programming services command discrete budget allocations.
- Neurorehabilitation:Functional electrical stimulation and robotic-assisted motor recovery platforms for post-stroke and traumatic injury populations.
- Diagnostics:Epilepsy localization, sleep disorder assessment, and neurodegenerative disease tracking across hospital and ambulatory settings.
Procedure volume anchors Stroke Management; Pain Relief climbs the fastest as service unbundling creates specialized provider niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Zona Franca de Iquique tax-exempt zone concentrates import logistics for northern Chile's medical device distributors, creating a staging hub for neurology equipment entering the Andean corridor.
Metropolitan Santiago
Santiago's tertiary hospital network anchors national neurodiagnostic capacity, with Clínica Alemana and Hospital Clínico Universidad de Chile expanding robotic-assisted surgical suites. The Ministry of Health's public-private partnership framework accelerates MRI and CT scanner deployment across the metropolitan region's seven major health complexes. Private hospital chains in Las Condes and Providencia concentrate demand for deep brain stimulation systems.
Valparaíso Region
Valparaíso's regional health service autonomy creates independent procurement authority for Hospital Carlos Van Buren and the University of Valparaíso medical complex. ISP registration harmonization reduces approval timelines for neurostimulation platforms entering this coastal metropolitan area. The port city's logistics infrastructure supports faster customs clearance for European-manufactured neurology equipment.
Biobío Region
Concepción's Hospital Guillermo Grant Benavente drives neuroimaging demand in Chile's second-largest metropolitan area, serving stroke triage protocols across the southern agricultural belt. Regional health service decentralization enables direct contracting for EEG monitoring systems and neurorehabilitation platforms. The Universidad de Concepción medical school trains biomedical engineering specialists for device programming.
Antofagasta Region
Antofagasta's mining economy generates occupational neurology demand for peripheral nerve monitoring and traumatic injury assessment at Hospital Regional Dr. Leonardo Guzmán. Remote neurology expansion via telemedicine connects this isolated northern center to Santiago's specialist networks. Zona Franca benefits reduce landed costs for imported neurodiagnostic equipment serving the Atacama mining corridor.
Araucanía Region
Temuco's Hospital Hernán Henríquez Aravena represents the southern frontier of advanced neurology device deployment, with ISO 13485-certified distributors establishing technical service presence. Mapuche population health initiatives expand epilepsy monitoring and neurorehabilitation access across rural communes. The regional health service's autonomous purchasing authority creates opportunities for portable diagnostic platforms.
Chile Neurology Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Chile's neurology devices market, creating a tiered structure where full-line suppliers anchor premium hospital contracts while niche players capture specialized service segments. The vendor base stratifies between established multinationals with ISP-registered technical infrastructure and emerging distributors leveraging ANMAT harmonization for cross-border scale. Three archetypes dominate: integrated surgical platform providers, neurostimulation programming specialists, and regional imaging equipment distributors. Competitive moves center on service unbundling from equipment sales and regional technical presence expansion beyond Santiago.
Among diversified healthcare conglomerates, Medtronic PLC and Stryker Corporation exemplify the integrated surgical platform archetype, leveraging established ISP registration portfolios and nationwide service networks to defend premium positioning. Boston Scientific Corporation occupies the neurostimulation specialist tier, where programming service capabilities determine contract renewal rates. These three anchors demonstrate how technical service density, not equipment pricing alone, structures competitive outcomes in Chile's concentrated metropolitan hospital market.
| Leading Market Players |
|---|
| B Braun SE |
| Stryker Corporation |
| Medtronic PLC |
| Abbott Laboratories |
| Johnson & Johnson |
| Nihon Kohden Corporation |
| Smith & Nephew |
| Elekta AB |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Backward integration into titanium alloy component manufacturing anchors both supply security and pricing power for established neurology device suppliers serving Chile's metropolitan hospital networks. European and North American production clusters dominate precision neurosurgical system fabrication, creating import dependency that amplifies currency exposure for Chilean procurement authorities negotiating service-unbundled contracts.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations for implantable pulse generators and robotic-assisted cranial access platforms, while spot inventory discounts attract budget-constrained regional health services. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European systems from ANMAT-harmonized regional alternatives and unbranded Asian components. Cost compression in the economy tier intensifies because raw material volatility in biocompatible polymers squeezes distributor margins. Public hospital procurement committees demonstrate highest price sensitivity, whereas Santiago's private hospital chains prioritize programming service availability over unit cost.
Supply Chain Analysis
Refurbishment flows for explanted neurostimulators and remanufactured electrode arrays create secondary supply channels that compete with new equipment in price-sensitive regional markets. Manufacturing concentrates in Germany, Ireland, and the United States for precision-machined titanium components and biocompatible polymer housings. Supply chains draw from rare earth magnet suppliers for MRI superconducting coils and specialized semiconductor foundries for implantable pulse generator circuitry. Single-source vulnerability in programmable pulse generator firmware creates procurement risk for Chilean distributors. Distribution runs through the Zona Franca de Iquique tax-exempt zone for northern regional health services, while metropolitan Santiago receives direct European air freight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's neurology devices market is consolidating around suppliers with integrated service networks, as ISP registration reforms and ISO 13485 documentation burdens force smaller distributors toward acquisition or exit.
For Market Incumbents: Anchor defensive positioning by expanding biomedical engineering training partnerships with Universidad de Concepción and Universidad de Chile to lock in programming service capabilities. Acquire regional distributors in Valparaíso and Biobío before decentralized purchasing authority matures, securing first-mover advantage in autonomous health service contracting.
For New Entrants and Emerging Players: Capture the remote neurology monitoring segment where telemedicine-enabled EEG platforms face limited incumbent service infrastructure. Target Antofagasta's mining corridor occupational neurology demand through portable diagnostic platforms with Zona Franca logistics advantages. Lead with outcome-based contracting models that separate device acquisition from cloud-based interpretation services.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap distributors with established ISP technical files and regional service presence outside Santiago. Long-term viability hinges on recurring revenue from neurostimulator programming and maintenance contracts rather than capital equipment sales. Watch ANMAT harmonization implementation velocity as the signal for cross-border scale economies and acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISP Registration Acceleration | Streamlined conformity assessment reduces market entry delays for neurostimulation platforms entering Chilean metropolitan networks. |
| Regional Service Network Expansion | Technical presence in Valparaíso and Biobío captures autonomous procurement authority before competitor infrastructure deployment. |
| CE Marking Alignment Investment | MDR-compliant clinical evidence portfolios filter supplier competition toward established manufacturers with robust surveillance infrastructure. |
| Biomedical Engineering Training Pipeline | University partnerships address talent scarcity constraining neurostimulator programming and intraoperative neuromonitoring capacity scaling. |
| Remote Neurology Platform Development | Cloud-based EEG interpretation extends device utilization beyond tertiary hospital boundaries into ambulatory and regional networks. |
Study Parameters
Multi-period observation of ISP registration timelines, neuroimaging deployment patterns, and neurostimulator replacement cycles anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and ISP regulatory affairs specialists. Secondary validation drew from ANMAT harmonization documentation, EU MDR technical file databases, Chilean Ministry of Health procurement disclosures, and regional health service budget allocations. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to equipment replacement cycles and expansion capital deployment patterns. Forecast inputs incorporated aging demographic stroke incidence projections, public-private partnership neurodiagnostic infrastructure commitments, and remote neurology reimbursement pathway developments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ISP regulatory enforcement consistency, ANMAT harmonization implementation velocity, and biomedical engineering talent pipeline scaling. Practitioners should monitor ISP registration backlog clearance rates and regional health service budget autonomy expansion for early signals of competitive structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Tourette Syndrome Market
Neurology
Intracranial Aneurysm Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
US Optic Neuritis Market
Neurology
Arachnoiditis Market
Neurology
CNS Therapeutics Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
CNS Treatment and Therapy Market
Neurology
Brazil Neurology Devices Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
China Neurology Devices Market
Neurology
Chiari Malformation Treatment Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Acute Repetitive Seizures Market
Neurology
Global Narcolepsy Therapeutics Market