
 Optic Neuropathy Management Market | 2026-2036
Optic Neuropathy Management Market Size, Share, and Industry Trends Forecast 2026-2036
Optic Neuropathy Management Market Analytics
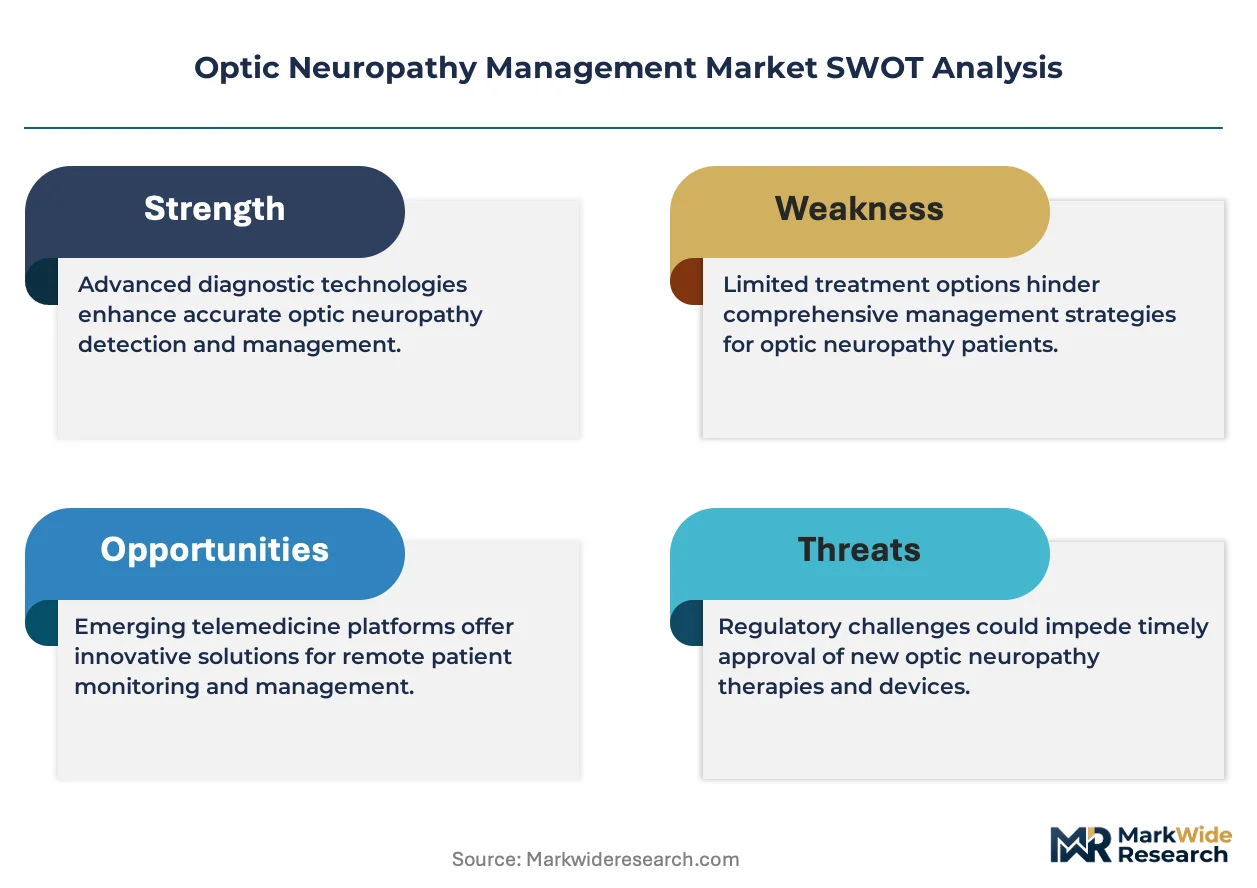
CE marking under the EU MDR is reorganizing competitive access for device-drug combination therapies in optic neuropathy. Novartis leverages its ophthalmology franchise to sustain leadership in neuroprotective compounds across European and North American markets. GenSight Biologics anchors its position through gene therapy specialization for Leber hereditary optic neuropathy, while Santen Pharmaceutical competes on manufacturing scale in topical and intravitreal delivery formats.
Optic neuropathy management encompasses pharmacological, surgical, and rehabilitative interventions targeting retinal ganglion cell preservation and axonal integrity, with intravitreal anti-VEGF injections and neuroprotective agents representing core therapeutic modalities. The primary purpose is halting or reversing vision loss from ischemic, compressive, hereditary, or toxic etiologies. Medications command the largest current revenue pool given established reimbursement for anti-VEGF and corticosteroid protocols, while gene therapies within the Therapies segment represent the fastest-expanding margin pool due to orphan pricing potential. Intravitreal Injection dominates delivery mode selection for posterior segment conditions, though Oral Administration is gaining traction for chronic neuroprotection in neurology-ophthalmology crossover care.
FDA orphan drug designation and EMA PRIME eligibility are accelerating development timelines for hereditary optic neuropathy therapies, while HIPAA frameworks in the United States shape real-world evidence collection protocols that underpin payer negotiations. Japan's PMDA Sakigake designation creates a parallel fast-track pathway for novel mechanisms targeting Leber hereditary optic neuropathy. Stakeholders must monitor regulatory divergence between FDA gene therapy guidance and EMA advanced therapy medicinal products standards to anticipate market access timelines.
Market Dynamics
Gene therapy commercialization is compressing development timelines and reshaping reimbursement negotiations across ophthalmology departments, forcing traditional pharmaceutical manufacturers to accelerate neuroprotective pipeline investments.
Growth Catalysts
- FDA Orphan Drug Designation:The FDA's expedited review pathway for hereditary optic neuropathy therapies reduces clinical trial duration and unlocks priority voucher monetization for developers targeting Leber hereditary optic neuropathy mutations.
- Intravitreal injection protocols:Hospital ophthalmology departments in the United States and Germany are standardizing anti-VEGF administration workflows, expanding addressable patient pools for chronic glaucomatous progression management.
- EMA PRIME eligibility:The European Medicines Agency's accelerated assessment mechanism for advanced therapy medicinal products compresses regulatory timelines for gene therapy submissions targeting mitochondrial optic neuropathies.
Market Restraints
- Viral vector manufacturing scarcity:AAV production capacity concentrates among contract manufacturers in the United States and Switzerland, creating bottlenecks for gene therapy developers requiring GMP-grade material.
- Reimbursement complexity:Germany's G-BA benefit assessment procedures impose 12-18 month delays between EMA approval and statutory health insurance coverage for novel ophthalmologic therapies.
- Retinal ganglion cell biomarker immaturity:The absence of validated surrogate endpoints forces reliance on visual field testing, extending pivotal trial durations and inflating development costs.
Strategic Opportunities
- Japan's PMDA Sakigake designation:Japan's regenerative medicine fast-track creates first-mover advantages for gene therapy developers willing to conduct parallel development with domestic clinical sites.
- Neuro-ophthalmology crossover care:Academic medical centers in the United States are integrating neurology and ophthalmology departments, creating demand for oral neuroprotective agents that bridge specialty prescribing.
- Real-world evidence frameworks:HIPAA-compliant data infrastructure investments enable outcomes-based contracting models that align manufacturer and payer incentives for high-cost gene therapies.
Industry Challenges
- Gene therapy manufacturing scale-up:Translating academic viral vector production to commercial GMP standards requires $200-400 million facility investments with 3-5 year construction timelines.
- Retinal specialist training gaps:Intravitreal injection competency for novel neuroprotective formulations lags behind anti-VEGF standardization, limiting protocol adoption in community ophthalmology practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optic Neuropathy Management Market |
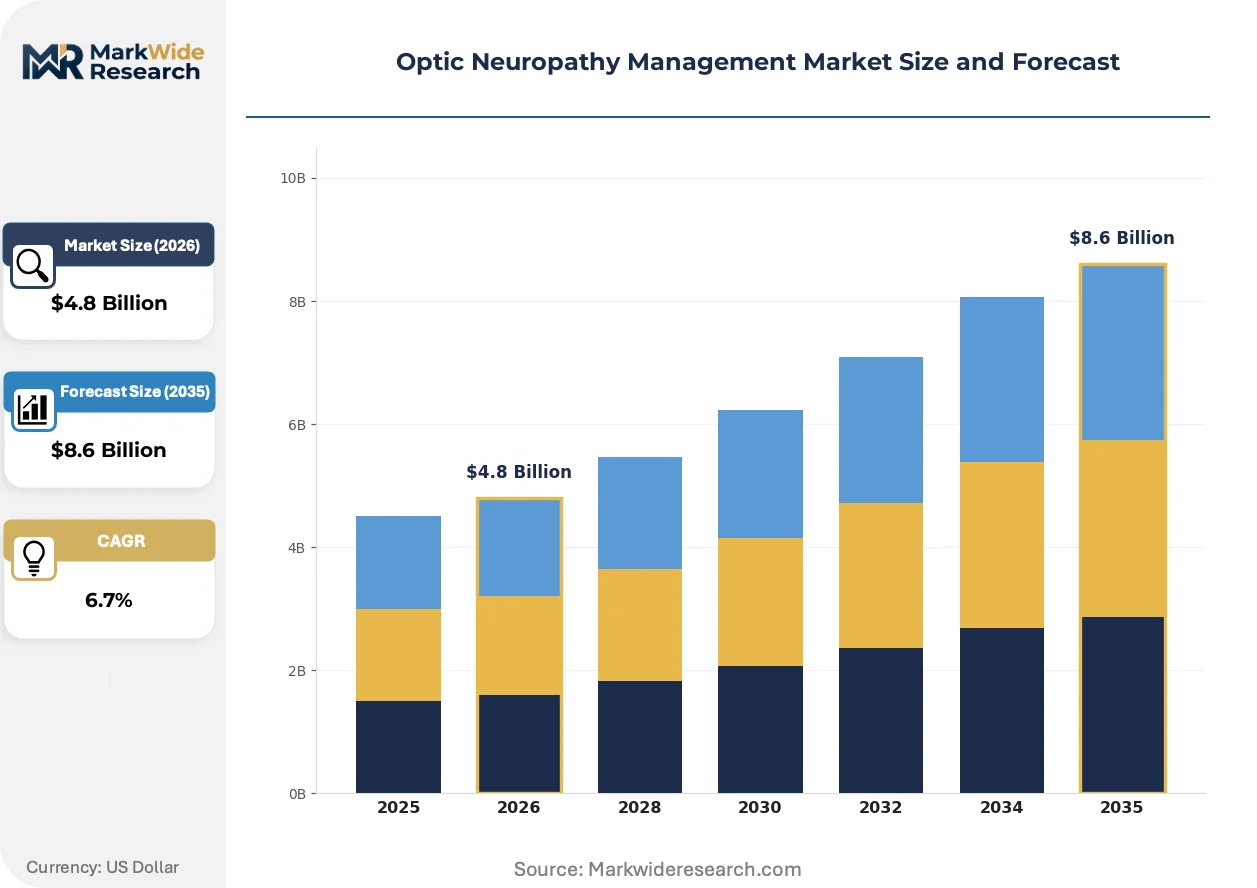
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Surgery, Supplements End User: Ophthalmologists, Neurologists, Hospitals, Clinics Delivery Mode: Intravitreal Injection, Oral Administration, Topical Application, Infusion Application: Treatment, Diagnosis, Research, Rehabilitation |
| Companies Covered | Novartis, Santen Pharmaceutical, GenSight Biologics, Stealth BioTherapeutics, Chiesi Farmaceutici, Santhera Pharmaceuticals, Roche Holding AG, Bausch Health Companies, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optic Neuropathy Management Market Evolving Landscape
Biomarker-guided patient stratification is displacing empirical treatment selection in optic neuropathy management, with molecular diagnostics enabling precision matching of therapeutic mechanisms to underlying etiologies.
AAV-based gene delivery is fragmenting the hereditary optic neuropathy treatment landscape. The technology enables single-disease targeting for mitochondrial DNA mutations. Academic medical centers in Boston and Paris are establishing dedicated gene therapy infusion suites. Novartis and GenSight Biologics are compressing traditional small-molecule development timelines through platform manufacturing approaches.
EU MDR CE marking requirements are reorganizing device-drug combination therapy access. The regulation imposes enhanced clinical evidence standards for intravitreal delivery systems. European notified bodies in Germany and the Netherlands are experiencing 18-24 month backlog for ophthalmologic device certifications. Manufacturers are responding by pre-submission engagement with BSI and TÜV SÜD to accelerate technical file preparation.
Hospital procurement committees are consolidating ophthalmology vendor relationships to reduce formulary complexity. Integrated delivery networks in the United States are negotiating multi-year anti-VEGF contracts that bundle neuroprotective agent access. This concentration is most visible in the Medicare Advantage population, where UnitedHealthcare and CVS Aetna are implementing step-therapy protocols that prioritize established intravitreal regimens over novel mechanisms.
Optic Neuropathy Management Market Segmentation
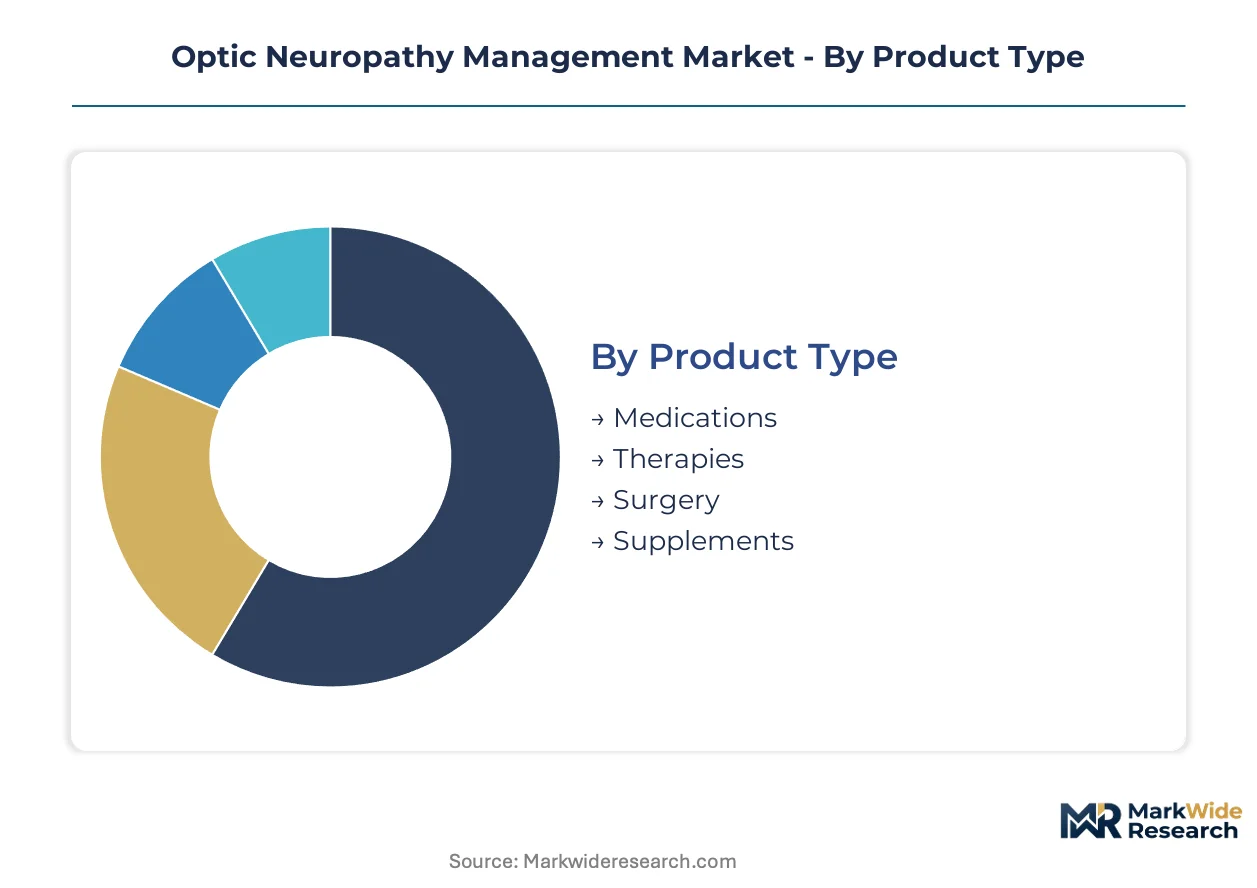
Optic neuropathy management segments reveal divergent geographic footprints. Medications and intravitreal protocols concentrate in United States and German hospital systems, while gene therapies and surgical interventions show export-led patterns from Swiss and Japanese manufacturing clusters.
Product Type:
Medications and therapies flow predominantly through domestic channels in established markets, whereas surgical devices and supplements exhibit stronger cross-border trade intensity.
- Medications:Anti-VEGF compounds and corticosteroids constitute the revenue backbone, with United States Medicare Part B and German G-BA reimbursement anchoring volume concentration. Hospital formularies in Boston and Munich drive protocol standardization for chronic glaucomatous progression.
- Therapies:Gene therapy platforms for Leber hereditary optic neuropathy command orphan pricing premiums. PMDA Sakigake designation in Japan and FDA breakthrough pathways compress development timelines for mitochondrial-targeted interventions.
- Surgery:Optic nerve decompression and shunt procedures rely on specialized neuro-ophthalmology suites in academic medical centers.
- Supplements:Neuroprotective nutraceuticals targeting retinal ganglion cell metabolism circulate through direct-to-consumer channels and neurology-ophthalmology crossover practices.
Medications holds the largest share; momentum sits with Therapies.
End User:
Customer concentration varies by intervention complexity, with high-acuity settings absorbing advanced delivery modes and community practices handling maintenance protocols.
- Ophthalmologists:Retinal specialists in United States integrated delivery networks administer the majority of intravitreal injections, with UnitedHealthcare and CVS Aetna step-therapy protocols influencing prescribing patterns.
- Neurologists:Neuro-ophthalmology crossover care in academic centers drives oral neuroprotective agent adoption for ischemic and toxic etiologies.
- Hospitals:Tertiary centers in Paris and Boston maintain dedicated gene therapy infusion suites for AAV-based mitochondrial interventions.
- Clinics:Ambulatory surgery centers in Germany and Japan handle high-volume anti-VEGF administration through standardized injection workflows.
Hospitals command premium pricing; clinics are expanding fastest through workflow consolidation.
Delivery Mode:
Route selection tracks posterior versus anterior segment targeting, with invasive methods dominating sight-threatening conditions and oral routes gaining traction for chronic management.
- Intravitreal Injection:Direct vitreal administration of anti-VEGF and neuroprotective agents represents the procedural standard for glaucomatous optic neuropathy. German hospital ophthalmology departments and United States Medicare Advantage networks have standardized these protocols.
- Oral Administration:Systemic neuroprotective compounds bridge neurology and ophthalmology prescribing, with academic medical centers in the United States integrating these into crossover care pathways.
- Topical Application:Anterior segment delivery of neuroprotective drops targets early-stage disease in community practice settings.
- Infusion:Intravenous gene therapy delivery requires specialized infusion suites with viral vector handling capabilities.
Intravitreal Injection retains dominant share; Oral Administration is climbing the fastest through specialty integration.
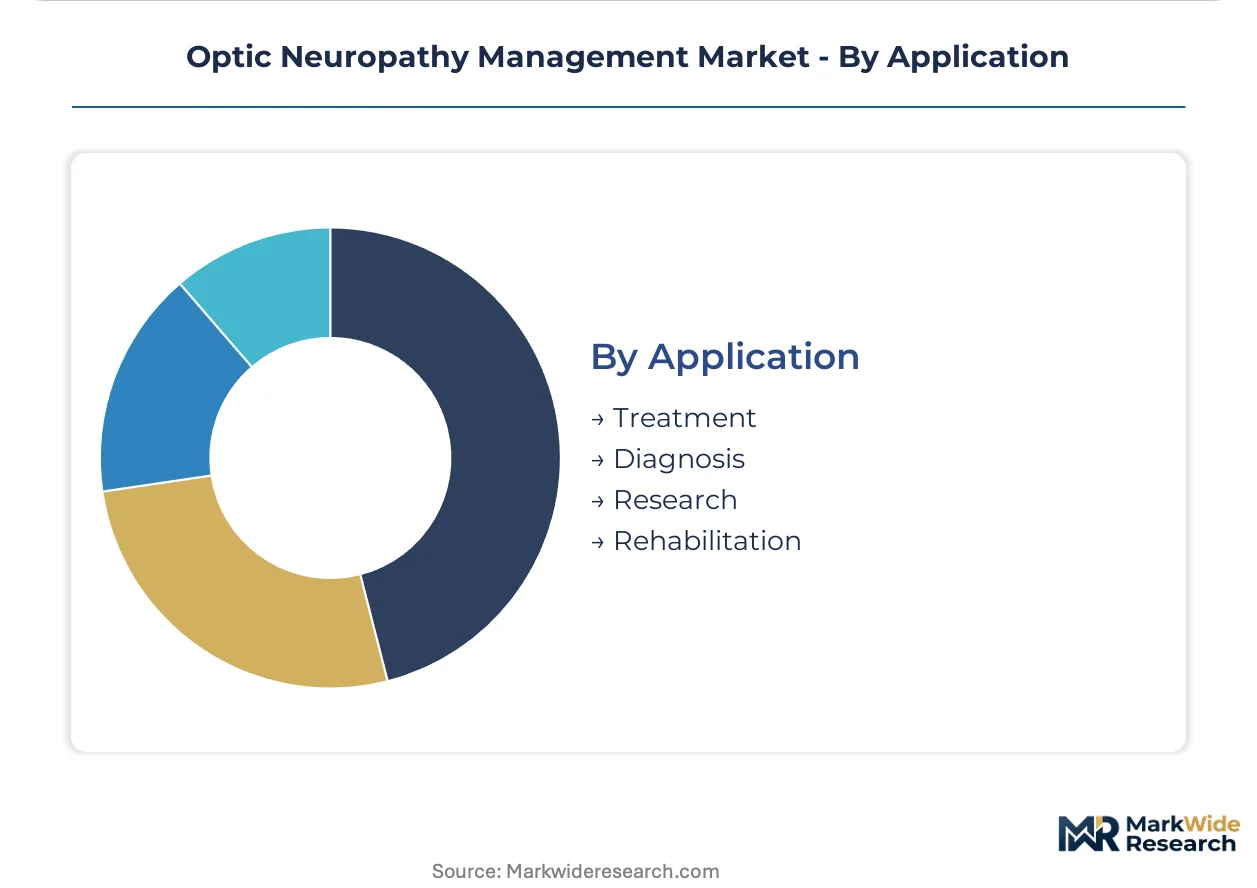
Application:
Functional segmentation separates revenue-generating therapeutic activity from supporting diagnostic and rehabilitative services that enable longitudinal patient management.
- Treatment:Therapeutic interventions for active disease progression generate the majority of segment revenue, spanning pharmacologic, surgical, and gene therapy modalities across United States, German, and Japanese reimbursement systems.
- Diagnosis:Visual field testing and retinal ganglion cell biomarker assessment face endpoint validation challenges that extend clinical trial timelines and inflate development costs.
- Research:Academic and industry-sponsored trials for hereditary optic neuropathy therapies concentrate in Boston, Paris, and Tokyo gene therapy clusters.
- Rehabilitation:Low-vision services and adaptive technologies support patients with irreversible axonal damage.
Treatment dominates value capture; Research exhibits the steepest expansion trajectory through orphan indication prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug designation and Japan's PMDA Sakigake pathway compress development timelines for gene therapy developers, while EMA PRIME eligibility and Germany's G-BA procedures create divergent access timelines across major markets.
United States
Medicare Part B reimbursement anchors volume concentration for anti-VEGF intravitreal protocols. HIPAA-compliant data infrastructure investments enable outcomes-based contracting for high-cost gene therapies. Boston academic medical centers maintain dedicated gene therapy infusion suites for AAV-based mitochondrial interventions.
Germany
G-BA benefit assessment procedures impose 12-18 month delays between EMA approval and statutory health insurance coverage. CE marking under EU MDR reorganizes competitive access for device-drug combination therapies. Munich hospital ophthalmology departments standardize injection workflows for chronic glaucomatous progression management.
Japan
PMDA Sakigake designation creates first-mover advantages for developers conducting parallel development with domestic clinical sites. The regenerative medicine fast-track accelerates novel mechanism approvals for Leber hereditary optic neuropathy. Tokyo gene therapy clusters concentrate academic and industry-sponsored trials for hereditary indications.
Switzerland
AAV production capacity concentrates among contract manufacturers, creating supply bottlenecks for GMP-grade viral vector material. Swissmedic standards align with EMA advanced therapy medicinal products frameworks for gene therapy submissions. Basel anchors neuroprotective compound manufacturing for European distribution.
France
ANSM oversight integrates with EMA centralized procedures for ophthalmologic advanced therapies. Paris academic medical centers establish dedicated infusion capabilities alongside Boston and Tokyo clusters. The national health insurance system negotiates orphan pricing premiums for mitochondrial-targeted interventions.
Optic Neuropathy Management Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established ophthalmology franchises alongside specialized gene therapy developers. Market structure shows moderate concentration, with top-tier firms commanding hospital formulary relationships and manufacturing scale advantages. Three archetypes dominate: broad-based pharma with neuroprotective pipelines, gene therapy specialists targeting orphan indications, and regional manufacturers with topical delivery expertise. Competitive moves center on platform manufacturing approaches and pre-submission engagement with European notified bodies for MDR certification.
Within the diversified pharmaceutical tier, Novartis leverages its ophthalmology franchise to sustain leadership across European and North American markets. Santen Pharmaceutical competes on manufacturing scale in topical and intravitreal delivery formats, while GenSight Biologics anchors its position through gene therapy specialization for Leber hereditary optic neuropathy. These three firms represent the spectrum from broad portfolio coverage to single-mechanism depth that characterizes competitive positioning in this market.
| Leading Market Players |
|---|
| Novartis |
| Santen Pharmaceutical |
| GenSight Biologics |
| Stealth BioTherapeutics |
| Chiesi Farmaceutici |
| Santhera Pharmaceuticals |
| Roche Holding AG |
| Bausch Health Companies |
| AbbVie |
| Others |
Value Network & Pricing Analysis
AAV viral vector substitution for traditional small-molecule neuroprotective compounds simultaneously shifts manufacturing gravity toward Swiss and United States contract manufacturers and compresses pricing premiums for chronic glaucoma management as hospital formularies consolidate vendor relationships.
Pricing Analysis
Certification level under EU MDR and FDA gene therapy guidance creates the primary spread between premium gene therapy pricing and standard intravitreal protocols. Three-tier pricing structure across orphan-designated biologics, established anti-VEGF agents, and commoditized corticosteroids dominates reimbursement negotiations. Pricing pressure stems from UnitedHealthcare and CVS Aetna step-therapy protocols that prioritize established intravitreal regimens. Community ophthalmology practices exhibit highest price sensitivity; academic medical centers with dedicated gene therapy suites demonstrate lowest.
Supply Chain Analysis
Inventory lead times for GMP-grade AAV material extend 18-24 months due to viral vector manufacturing scarcity. Supply concentrates in Switzerland and the United States among contract manufacturers with commercial-scale bioreactor capacity. Raw material dependencies include plasmid DNA, helper virus stocks, and specialized cell culture media. Single-source vulnerability at the viral vector production tier poses structural risk. Distribution runs through hospital procurement committees and integrated delivery network formulary managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy commercialization threatens incumbent positions in chronic glaucoma management, forcing traditional pharmaceutical manufacturers to defend against platform-based substitution before mitochondrial-targeted interventions capture hospital formulary slots.
For Market Incumbents: Secure hospital formulary relationships through multi-year anti-VEGF contract bundling that locks in neuroprotective agent access. Deepen backward integration into AAV manufacturing capacity or captive supply agreements with Swiss contract manufacturers to offset viral vector scarcity. This defends against gene therapy specialists capturing academic medical center infusion suites. For New Entrants and Emerging Players: Post-marketing real-world evidence collection services represent an under-served layer where incumbents lack HIPAA-compliant infrastructure. Target Medicare Advantage networks with outcomes-based contracting models that align manufacturer and payer incentives for high-cost therapies. Lead with data infrastructure partnerships rather than molecule development. For Investors and Strategic Acquirers: Capital is best deployed toward gene therapy platform developers with PMDA Sakigake or FDA breakthrough designation momentum. Long-term viability hinges on manufacturing scale-up execution rather than clinical trial success alone. Watch for EMA PRIME eligibility announcements as inflection indicators for reimbursement timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | AAV viral vector capacity expansion in Switzerland reduces supply bottlenecks for gene therapy developers. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses clinical trial timelines for Leber hereditary optic neuropathy therapies. |
| Hospital System Partnership | Integrated delivery network formulary contracts bundle neuroprotective access with anti-VEGF protocols. |
| Reimbursement Strategy | G-BA benefit assessment navigation accelerates statutory health insurance coverage in Germany. |
| Pipeline Diversification | Neuro-ophthalmology crossover indications expand addressable patient pools beyond retinal specialists. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underpinning this analysis. Primary interviews with payer access specialists and gene therapy manufacturing heads combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down reimbursement system analysis provided triangulation across data sources.
Segmentation dimensions modeled include treatment line, administration route, delivery mode, patient population etiology, and regional regulatory cluster across the projection horizon. CAGRs derived from procedure volume trajectories, pricing elasticity assumptions, and gene therapy adoption curves. Forecast inputs incorporated viral vector manufacturing capacity expansion timelines and G-BA benefit assessment procedural delays.
Forecasts assume regulatory continuity in FDA gene therapy guidance, EMA advanced therapy medicinal products frameworks, and Japan's PMDA Sakigake pathway; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neuroprotection Market
Neurology
Movement Disorder Market
Neurology
Vocal Cord Paralysis Market
Neurology
Spasticity Treatment Market
Neurology
Spinal Laminoplasty Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Chile Neurology Devices Market
Neurology
Chordoma Disease Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Labyrinthitis Market
Neurology
Argentina Neurology Devices Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Acute Repetitive Seizures Market