
 Global Sciatica Treatment Market | 2026-2036
Global Sciatica Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sciatica Treatment Market Foresight
The gap between premium neuromodulation implants and commodity oral analgesics is repositioning how payers structure reimbursement tiers and how providers allocate capital. Pfizer Inc. leverages its generic portfolio breadth to sustain volume in oral NSAIDs across retail pharmacy channels. Medtronic plc anchors the high-value implant segment through its spinal cord stimulation platforms and direct-to-provider training infrastructure. Boston Scientific Corporation competes in radiofrequency ablation systems with specialized catheter designs that differentiate its interventional pain portfolio.
Sciatica treatment encompasses interventions targeting compression or irritation of the sciatic nerve, typically involving L4-S1 nerve root pathology, with modalities ranging from systemic pharmacotherapy to percutaneous thermal lesioning and implanted pulse generator systems. The primary purpose is restoration of functional mobility and reduction of neuropathic pain burden in ambulatory and surgical patient populations. Pharmaceuticals still command the largest revenue pool due to volume scale, though neuromodulation devices represent the fastest-expanding margin segment as implant technology improves battery longevity and programming flexibility. Ambulatory surgery centers are capturing growing procedure share as minimally invasive delivery modes reduce length-of-stay requirements and shift site-of-service economics.
The FDA regulates implantable neuromodulation devices through premarket approval pathways while the EMA's Medical Device Regulation tightens clinical evidence standards for European market access, both frameworks elevating R&D costs but protecting incumbent positions. Japan's PMDA maintains distinct quality management system inspections for foreign manufacturers, creating layered compliance obligations for cross-border suppliers. Stakeholders must monitor how CMS reimbursement adjustments for Category III CPT codes reshape provider willingness to adopt next-generation thermal and electrical therapies.
Market Dynamics
The neuromodulation implant segment is pulling capital away from pharmaceutical R&D as payers recalibrate reimbursement tiers around functional outcomes rather than symptom relief alone.
Growth Catalysts
- Aging demographics in developed economies:Germany, Japan, and the United States face expanding patient populations with degenerative lumbar spine conditions requiring interventional treatment.
- FDA breakthrough device designation:The accelerated approval pathway compresses time-to-market for novel spinal cord stimulation systems and dorsal root ganglion stimulators.
- Minimally invasive delivery techniques:Percutaneous thermal ablation and endoscopic decompression reduce recovery timelines and shift procedures to ambulatory surgery centers.
Market Restraints
- Implant battery longevity limitations:Current lithium-ion cell technology requires surgical replacement every 5-7 years, creating recurring cost and infection risk burdens.
- European clinical evidence requirements:EMA Medical Device Regulation mandates expanded pre-market clinical trials, elevating compliance costs for neuromodulation manufacturers.
- Oral analgesic substitution:Generic NSAIDs and neuropathic pain agents retain formulary preference among primary care physicians for first-line therapy.
Strategic Opportunities
- India's underpenetrated interventional pain market:Limited access to implantable devices in tier-2 and tier-3 cities creates whitespace for training partnerships and localized manufacturing.
- Closed-loop stimulation algorithms:Integration of accelerometer and evoked potential feedback is automating therapeutic adjustment without clinician reprogramming.
- Brazil's ANVISA fast-track pathway:The priority review mechanism for breakthrough medical devices accelerates market entry for next-generation radiofrequency systems.
Industry Challenges
- Interventional pain physician training pipelines:Fellowship programs in neuromodulation and advanced fluoroscopic techniques produce insufficient specialists relative to procedure demand.
- EMR integration complexity:Implant programming platforms require costly customization to interface with hospital electronic medical record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sciatica Treatment Market |
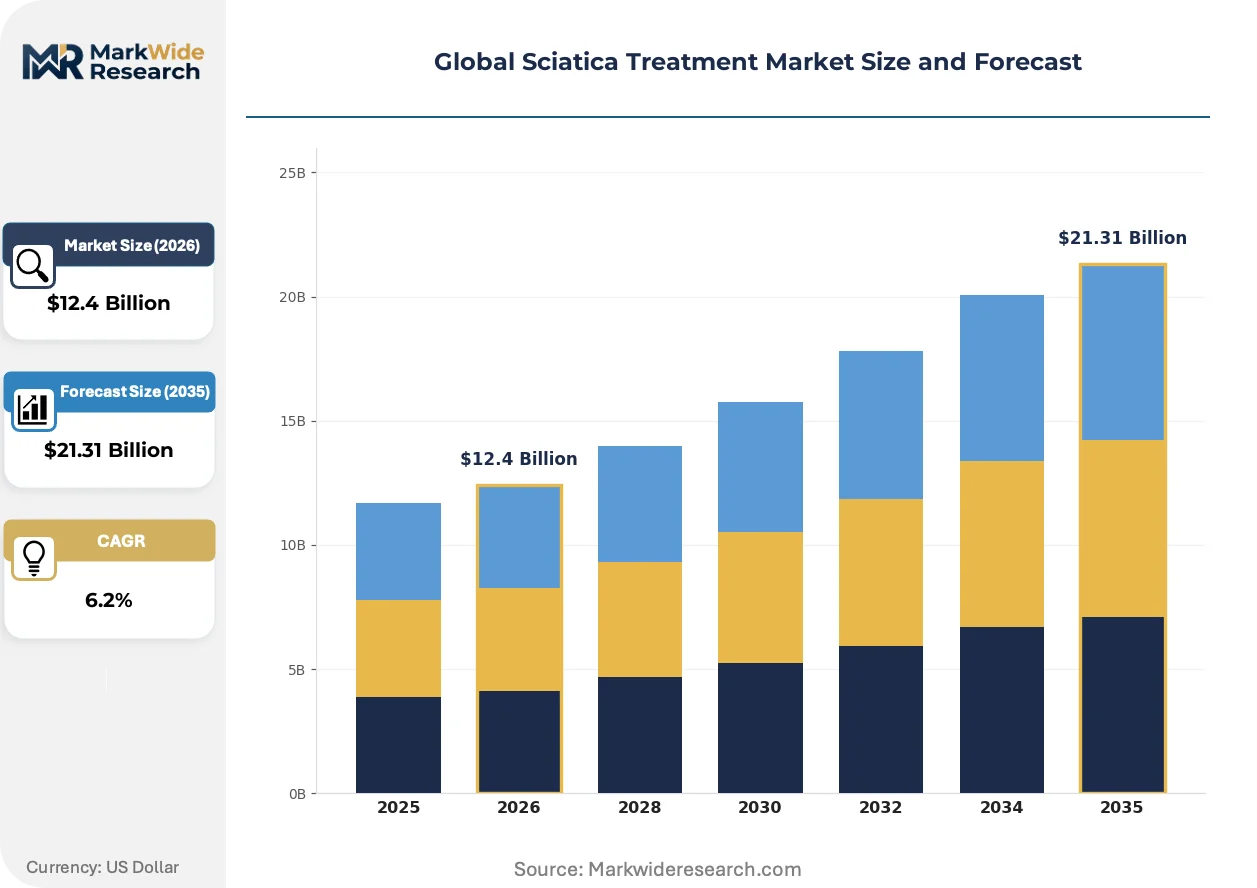
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $21.31 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Surgical Devices, Physical Therapy Equipment, Neuromodulation Devices, Orthopedic Supports Therapy Area: Non-Steroidal Anti-Inflammatories, Epidural Steroid Injections, Nerve Block, Radiofrequency Ablation, Spinal Cord Stimulation End User: Specialty Clinics, Rehabilitation Centers, Ambulatory Surgery Centers, Pain Management Centers, Diagnostic Imaging Facilities Delivery Mode: Oral, Injectable, Topical, Implantable, Minimally Invasive Procedures |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Pfizer Inc., Medtronic plc, Scilex Holding, Sorrento Therapeutics Inc., Boston Scientific Corporation, Johnson & Johnson Services Inc., Sun Pharmaceutical Industries Ltd., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sciatica Treatment Market Shifts & Advancements
Digital health integration and closed-loop feedback systems are transforming how neuromodulation devices deliver therapy, compressing the gap between implantation and optimal pain relief.
Artificial intelligence-enabled programming platforms are automating parameter optimization for spinal cord stimulation patients. Pain management centers in the United States are deploying machine learning algorithms that analyze patient movement patterns and pain diary entries. This capability is automating the traditionally labor-intensive trial-and-error process of stimulation setting adjustment.
Europe's MDR clinical evidence requirements are forcing manufacturers to conduct larger, longer-term post-market surveillance studies. The regulation mandates systematic collection of real-world performance data for implantable devices. High-value neuromodulation systems face the steepest compliance burden as notified bodies apply stricter scrutiny to novel stimulation waveforms.
Patients are demanding earlier escalation to interventional modalities after failing conservative management. Primary care referral patterns in Germany and Japan show compressed timelines between initial diagnosis and pain specialist consultation. This behavioral shift is accelerating procedure volume growth in ambulatory settings where same-day discharge protocols dominate.
Global Sciatica Treatment Market Segmentation
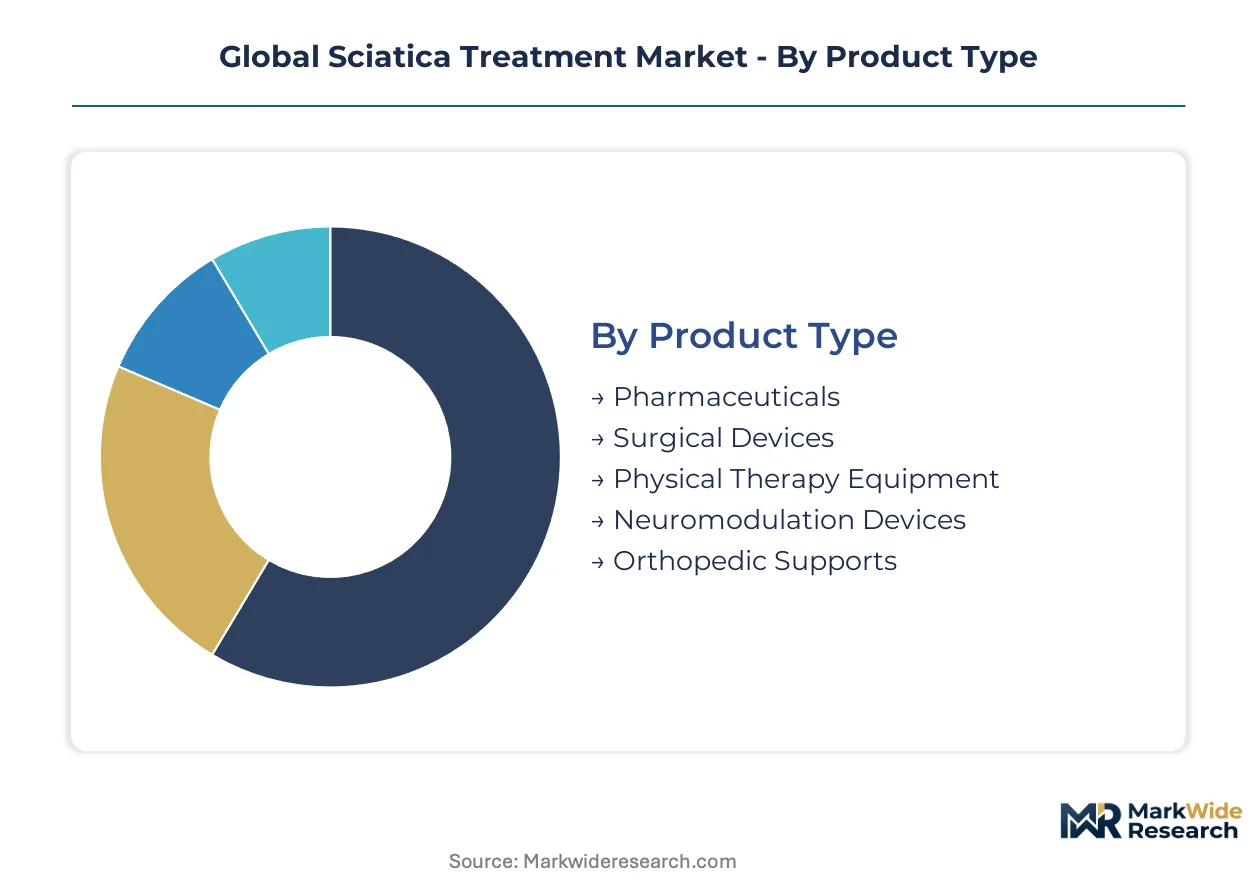
Sciatica treatment modalities span a wide spectrum from commodity oral formulations to precision-implanted electrical systems. Understanding how patient severity, reimbursement tiers, and site-of-service economics fragment demand across these categories enables targeted portfolio allocation and geographic prioritization.
Product Type:
The customization-vs-standardization spectrum runs from mass-manufactured oral tablets to patient-specific implanted pulse generators requiring surgical programming.
- Pharmaceuticals:Oral NSAIDs, neuropathic pain agents, and muscle relaxants dominate prescription volume through retail pharmacy channels. Demand concentrates in primary care settings across the United States and Germany where generic substitution rates exceed 80 percent and formulary controls limit branded access.
- Neuromodulation Devices:Implantable spinal cord stimulators and dorsal root ganglion systems deliver electrical pulses to modulate pain signaling. Japan's PMDA has accelerated approvals for closed-loop systems, concentrating demand in tertiary pain centers with advanced programming capabilities.
- Surgical Devices:Microdiscectomy instruments and endoscopic decompression tools address structural nerve compression.
- Physical Therapy Equipment:Traction devices, electrotherapy units, and lumbar stabilization systems support conservative management protocols.
- Orthopedic Supports:Lumbar braces and ergonomic cushions provide mechanical offloading for ambulatory patients.
Most installed capacity flows through Pharmaceuticals. Expansion is steepest in Neuromodulation Devices.
Therapy Area:
Cost tier stratification separates acute symptomatic relief from durable interventional outcomes, with reimbursement codes determining site-of-service viability.
- Non-Steroidal Anti-Inflammatories:First-line systemic agents including ibuprofen, naproxen, and celecoxib reduce inflammatory mediators at the nerve root. Volume concentrates in Germany's statutory health insurance system where generic prescribing mandates minimize per-dose expenditure.
- Spinal Cord Stimulation:Implanted electrode arrays modulate dorsal column signaling through programmable electrical waveforms. The FDA's breakthrough device designation has compressed approval timelines, accelerating adoption in United States pain management centers with dedicated neuromodulation service lines.
- Epidural Steroid Injections:Image-guided corticosteroid delivery targets perineural inflammation.
- Nerve Block:Local anesthetic and corticosteroid combinations interrupt sympathetic and somatic pain transmission.
- Radiofrequency Ablation:Thermal lesioning of medial branch nerves disrupts nociceptive signaling.
Procedure volume clusters in Non-Steroidal Anti-Inflammatories. Value capture is climbing fastest in Spinal Cord Stimulation.
End User:
Volume scale inversely correlates with reimbursement intensity, shifting margin capture toward specialized procedural settings.
- Pain Management Centers:Dedicated facilities combine interventional suites with long-term device programming capabilities. Germany's integrated care contracts and Japan's Diagnosis Procedure Combination payments support multidisciplinary staffing models that sustain implant follow-up revenue.
- Ambulatory Surgery Centers:Same-day discharge protocols for minimally invasive thermal and electrical procedures reduce facility fees while maintaining specialist reimbursement. United States site-of-service differentials favor ASC migration for Category III CPT codes.
- Specialty Clinics:Orthopedic and neurosurgical practices provide diagnostic and conservative management.
- Rehabilitation Centers:Post-acute facilities deliver physical therapy and functional restoration.
- Diagnostic Imaging Facilities:MRI and CT centers enable pre-procedural planning and post-treatment monitoring.
Patient encounters concentrate in Specialty Clinics. Margin expansion is strongest in Ambulatory Surgery Centers.
Delivery Mode:
Patient compliance and therapeutic durability trade off across administration routes, with invasive options reserved for refractory cases.
- Oral:Tablet and capsule formulations enable self-administered chronic therapy. United States retail pharmacy networks and Germany's mail-order dispensaries sustain volume through 90-day maintenance prescriptions.
- Implantable:Surgical placement of pulse generators and drug delivery systems provides continuous therapy without patient adherence burden. Japan's PMDA quality management inspections for foreign manufacturers create compliance barriers that protect domestic device suppliers.
- Injectable:Parenteral corticosteroids and anesthetics require clinical administration.
- Topical:Transdermal patches and creams offer localized drug delivery with minimal systemic exposure.
- Minimally Invasive Procedures:Percutaneous thermal and chemical techniques reduce recovery time versus open surgery.
Dose volume flows predominantly through Oral delivery. Therapeutic intensity is advancing most rapidly in Implantable systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional pain specialists concentrate in Germany's university hospitals, Japan's tertiary referral networks, and United States metropolitan surgical corridors. These talent clusters shape where neuromodulation adoption accelerates and where implant programming capabilities mature fastest.
United States
Pain management centers in Texas, Florida, and California drive spinal cord stimulation volume through dedicated neuromodulation service lines. The FDA's breakthrough device designation compresses approval timelines for closed-loop systems, concentrating early adoption in academic medical centers with research infrastructure. Minneapolis and Boston anchor device programming training networks that feed specialist pipelines.
Germany
Integrated care contracts in Bavaria and North Rhine-Westphalia sustain multidisciplinary pain clinics with implant follow-up revenue. The EMA's Medical Device Regulation mandates expanded clinical evidence for neuromodulation systems, elevating compliance costs that favor incumbent manufacturers. Berlin and Munich host the largest concentrations of interventional pain fellowship programs.
Japan
Tertiary pain centers in Tokyo and Osaka deploy closed-loop stimulation systems following PMDA accelerated approvals. Japan's Diagnosis Procedure Combination payment structure supports multidisciplinary staffing models for device management. The PMDA's quality management system inspections for foreign manufacturers create layered compliance barriers protecting domestic suppliers.
India
Tier-2 and tier-3 cities present whitespace for implantable device access as interventional pain training partnerships expand. The CDSCO's medical device rules align with international standards while maintaining distinct import licensing requirements. Mumbai and Delhi anchor diagnostic imaging capacity that enables pre-procedural planning for thermal ablation.
Brazil
ANVISA's priority review mechanism for breakthrough medical devices accelerates market entry for next-generation radiofrequency systems. São Paulo's private hospital networks capture premium neuromodulation cases while public sector formulary controls sustain oral analgesic volume. The southeast region concentrates pain specialist training programs relative to procedure demand.
Global Sciatica Treatment Market Competitive Landscape
Top-tier vendors anchor implantable neuromodulation systems, while mid-tier pharmaceutical manufacturers sustain volume in oral analgesics and generic substitution markets. The competitive structure stratifies across three tiers: integrated conglomerates with device-pharma portfolios, pure-play neuromodulation specialists, and commodity generic suppliers. Consolidation pressure concentrates in the device segment as programming platform complexity elevates R&D barriers. Strategic moves center on vertical integration into surgical training infrastructure and geographic licensing partnerships for regulatory pathway acceleration.
Among diversified healthcare conglomerates, Johnson & Johnson Services Inc., Medtronic plc, and Abbott Laboratories occupy positions spanning implantable devices through pharmaceutical distribution. These structures exemplify portfolio breadth strategies that capture margin across acute intervention and chronic maintenance phases. Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. represent generic-centric archetypes competing on manufacturing scale and formulary access. Pfizer Inc. anchors branded pharmaceutical positioning with retail pharmacy channel density.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Medtronic plc |
| Scilex Holding |
| Sorrento Therapeutics Inc. |
| Boston Scientific Corporation |
| Johnson & Johnson Services Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Lithium-ion cell procurement for implantable pulse generators flows from Japanese and South Korean suppliers through tiered pricing structures that separate premium closed-loop systems from standard fixed-output devices. Component cost concentration in East Asian battery manufacturing feeds downstream margin compression for neuromodulation OEMs while protecting pricing power for pharmaceutical API suppliers in India and China.
Pricing Analysis
Bundled device-plus-programming service packages dominate the implant segment while unbundled pharmaceutical pricing prevails in retail channels. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop spinal cord stimulators from conventional systems from commodity oral analgesics. Price differentiation rests on battery longevity certification and programming complexity. Cost compression in the generic NSAID tier is intensifying because formulary substitution mandates in Germany's statutory health insurance system eliminate brand premiums. Primary care physicians exhibit highest price sensitivity; tertiary pain centers with dedicated neuromodulation service lines demonstrate lowest sensitivity due to outcome-based reimbursement contracts.
Supply Chain Analysis
CE marking and FDA premarket approval pathways gate supplier qualification for electrode arrays and pulse generators, concentrating certified manufacturing in Ireland, Costa Rica, and Malaysia. Raw material dependencies include platinum-iridium alloys for electrodes, medical-grade silicone for insulation, and lithium thionyl chloride cells for power. Single-source vulnerability runs through Japanese battery suppliers serving closed-loop stimulation platforms. Distribution runs through GPO contracts with United States hospital systems and direct-to-provider shipments for European pain management centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory milestone acceleration, with FDA breakthrough device designation compressing approval timelines and expanding addressable procedure volume for implantable systems.
For Market Incumbents: Cement defensive positioning through backward integration into surgical training infrastructure and captive supply of lithium-ion cells. Generic substitution pressure from Indian and Chinese API manufacturers threatens oral analgesic margin pools. Priority investment in closed-loop algorithm R&D protects premium tier pricing against commoditization of fixed-output stimulation systems. For New Entrants and Emerging Players: Tier-2 and tier-3 cities in India represent the most penetrable buyer archetype for implantable device partnerships. White-space targets include localized manufacturing joint ventures with CDSCO-registered facilities and training academy partnerships with Mumbai and Delhi diagnostic imaging centers. Go-to-market execution should leverage distributor relationships with existing orthopedic instrument suppliers rather than direct hospital contracting. For Investors and Strategic Acquirers: Consolidation pressure builds where programming platform complexity elevates R&D barriers beyond mid-cap specialist reach. Long-term viability favors vertically integrated conglomerates with device-pharma portfolios spanning acute intervention and chronic maintenance phases. Acquisition target archetype: neuromodulation specialists with FDA breakthrough device pathway experience and established United States pain management center relationships. Signal to watch: CMS reimbursement adjustments for Category III CPT codes reshaping provider willingness to adopt next-generation thermal and electrical therapies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates spinal cord stimulator approvals, concentrating early adoption in academic medical centers. |
| CE Marking Compliance Investment | EMA MDR mandates expanded clinical evidence, elevating barriers for European market access. |
| Hospital System Partnership | Integrated care contracts in Germany sustain multidisciplinary pain clinics with implant follow-up revenue. |
| Software Companion Development | AI-enabled programming platforms automate parameter optimization, reducing clinician labor burden. |
| Reimbursement Strategy | CMS site-of-service differentials favor ambulatory surgery center migration for Category III CPT codes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional pain physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA MDR submission databases, ClinicalTrials.gov records, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Comparable-period anchoring linked historical implant procedure volumes to forward projections across the analysis window. Segmentation dimensions modeled include product type, therapy area, end user facility type, and delivery mode. CAGRs derived from regression analysis of installed base growth, replacement cycle timing, and pricing trajectory assumptions. Industry-specific inputs incorporated battery longevity improvement curves and training pipeline graduation rates.
Underlying measurement precision varies by segment; neuromodulation device forecasts carry tighter precision than pharmaceutical volume projections due to procedural reporting requirements. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement code stability. A model refresh is warranted upon material change in CMS Category III CPT code valuation or FDA breakthrough device designation criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
Neurology Software Market
Neurology
Brain Ischemia Market
Neurology
Bell Palsy Treatment Market
Neurology
South America Neurology Monitoring Market
Neurology
CNS Therapeutics Market
Neurology
Europe Neurology Monitoring Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Global Neurology Clinical Trials Market
Neurology
CNS Treatment and Therapy Market
Neurology
Neuroprotection Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
China Neurology Devices Market
Neurology
Hepatic Encephalopathy Market