
 Europe Neurology Monitoring Market | 2026-2036
Europe Neurology Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Neurology Monitoring Market Foresight
Silicon carbide sensor substrates are displacing traditional ceramic bases in next-generation intracranial pressure monitors, which is realigning component cost structures across the supply chain. Nihon Kohden Corporation leverages its proprietary amplifier technology to sustain premium positioning in long-term epilepsy monitoring suites. Koninklijke Philips N.V. anchors its European footprint through integrated critical care informatics that bundle neuro-monitoring with broader hospital systems. Siemens Healthineers AG dominates the high-field MRI-compatible EEG segment, where electromagnetic shielding requirements create steep technical barriers.
Europe neurology monitoring encompasses devices and systems that acquire, process, and interpret electrical, pressure, or hemodynamic signals from the central and peripheral nervous systems, typically operating with sampling rates exceeding 256 Hz for EEG acquisition and pressure measurement accuracy within ±2 mmHg for intracranial applications. These technologies serve primarily to detect neurological deterioration, guide therapeutic interventions, and stratify patient risk in acute and chronic care pathways. Electroencephalography devices command the largest installed base across European hospitals, though AI-driven analysis represents the fastest-expanding capability layer as algorithms gain CE marking under MDR for automated seizure detection. Sleep monitoring systems occupy a mature revenue pool concentrated in Nordic countries with established national sleep health programs, while neurostimulators carry the highest per-unit margins but face extended reimbursement negotiation cycles in France and Italy.
The European Medicines Agency (EMA) coordinates centralized neurotechnology assessments, while national competent authorities in Germany (BfArM) and France (ANSM) enforce MDR compliance through unannounced manufacturer audits that lengthen time-to-market for novel devices. REACH chemicals regulation additionally constrains electrode material selection, particularly for mercury-free sensor alternatives. Stakeholders must weigh the capital intensity of MDR clinical evidence generation against the revenue risk of delayed certification timelines when prioritizing product pipeline investments.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing time-to-market timelines and forcing manufacturers to front-load clinical evidence generation costs, fundamentally altering capital allocation across the European neurology monitoring supply chain.
Growth Catalysts
- Integrated stroke unit expansion:Germany's university hospital network is driving continuous EEG and intracranial pressure monitoring procurement as stroke care centralizes into specialized hubs.
- AI algorithm CE marking:Automated seizure detection algorithms gaining MDR approval are embedding intelligence directly into monitoring hardware, creating pull-through demand for upgraded base units.
- Silicon carbide substrate adoption:Next-generation intracranial pressure monitors are migrating from ceramic bases to silicon carbide, improving signal fidelity and device longevity in critical care settings.
Market Restraints
- MDR clinical evidence requirements:The EU Medical Device Regulation mandates extensive pre-market clinical data for neurodiagnostic equipment, extending certification timelines and inflating development budgets.
- Mercury-free electrode material constraints:REACH chemicals regulation restricts traditional sensor chemistries, forcing reformulation of EEG electrodes with alternative conductive materials that carry higher unit costs.
- Reimbursement negotiation cycles:Neurostimulators face protracted pricing discussions with statutory health insurers in France and Italy, delaying commercial traction despite technical readiness.
Strategic Opportunities
- Nordic sleep health program integration:Sweden, Norway, and Denmark maintain established national sleep disorder screening infrastructure, creating predictable demand streams for polysomnography systems.
- Remote patient monitoring scale-out:Hospital neurology departments across the United Kingdom are expanding ambulatory EEG and home-based ICP monitoring programs, opening recurring revenue models beyond capital equipment sales.
- Critical care informatics bundling:Neuro-monitoring modules are converging with broader hospital information systems, enabling vendors to capture larger share of IT capital budgets through integrated platform positioning.
Industry Challenges
- Electromagnetic compatibility engineering:High-field MRI-compatible EEG systems require specialized shielding expertise that resides in limited supplier pools, constraining production scaling.
- Legacy system interoperability:New monitoring platforms must interface with heterogeneous hospital IT architectures across fragmented European health systems, complicating deployment and support.
- Specialized clinical training gaps:Interpretation of continuous neuromonitoring data requires neurophysiology expertise that remains concentrated in tertiary centers, limiting adoption in secondary hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Neurology Monitoring Market |
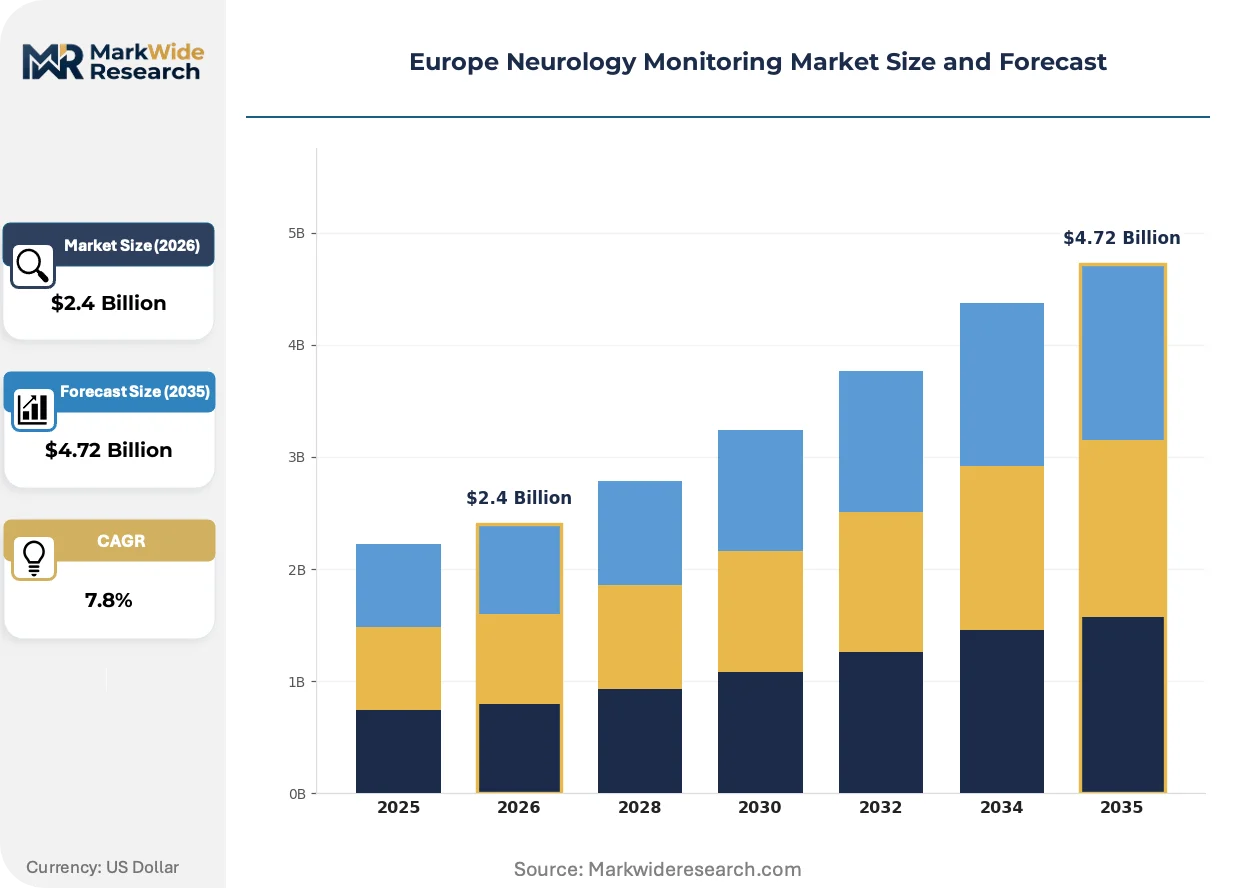
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalography Devices, Intracranial Pressure Monitors, Sleep Monitoring Systems, Neurostimulators End User: Hospitals, Neurology Clinics, Research Institutions, Homecare Settings Technology: Digital Monitoring, Wireless Monitoring, AI-driven Analysis, Telemedicine Application: Seizure Management, Sleep Disorders, Cognitive Impairment, Post-stroke Rehabilitation |
| Companies Covered | Natus Medical Inc., Nihon Kohden Corporation, Dragerwerk AG & Co. KGaA, Koninklijke Philips N.V., GE Healthcare, Medtronic PLC, Siemens Healthineers AG, Masimo Corporation, Compumedics Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Neurology Monitoring Market Shifts & Advancements
Artificial intelligence is embedding inference capabilities directly at the point of signal acquisition, compressing the latency between neurological event detection and clinical intervention across European acute care networks.
Silicon carbide sensor substrates are displacing alumina ceramic bases in intracranial pressure monitors, delivering superior thermal stability and biocompatibility for long-term implantation. German and French neurosurgical centers are adopting these devices in integrated stroke units, prioritizing measurement accuracy within the ±2 mmHg clinical threshold. This material transition is expanding into upstream component supply chains, forcing electrode and amplifier manufacturers to recalibrate thermal management specifications.
The EU Medical Device Regulation (MDR) is tightening unannounced manufacturer audit protocols enforced by Germany's BfArM and France's ANSM, extending certification timelines for novel neurodiagnostic devices. Small and mid-sized manufacturers face disproportionate compliance burdens as clinical evidence generation costs concentrate in pre-market phases. EEG and sleep monitoring segments are responding by consolidating pipeline priorities around platform extensions rather than breakthrough device categories.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, shifting toward multi-vendor maintenance agreements and third-party technical support. This disintermediation is compressing service margins for device manufacturers while creating openings for independent service organizations in the United Kingdom and Netherlands. The trend is most visible in university hospital networks where centralized biomedical engineering departments internalize routine calibration and repair functions.
Europe Neurology Monitoring Market Segmentation
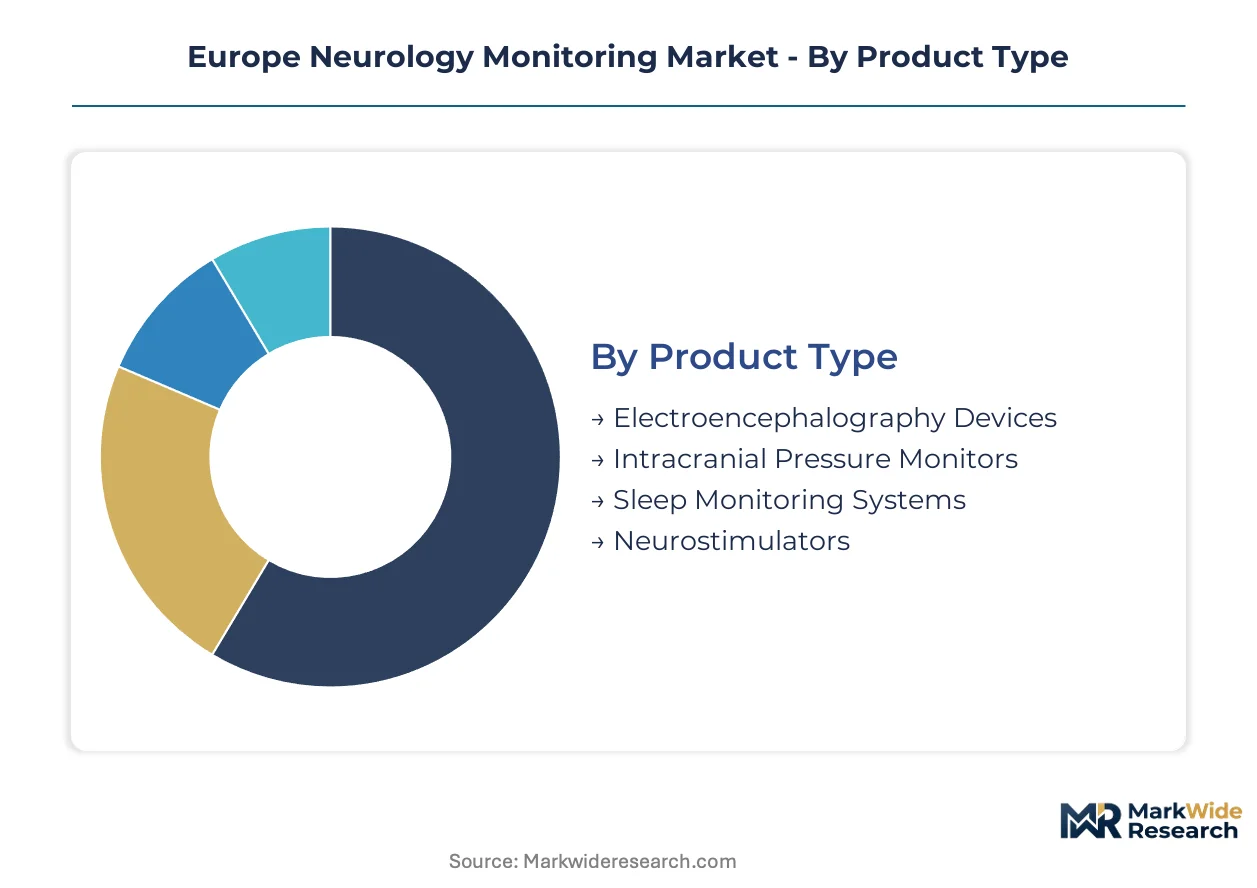
Segmentation in Europe neurology monitoring reveals divergent technology readiness across care settings. Product type splits between mature installed bases and emerging AI-augmented platforms, while end-user distribution tracks hospital centralization against ambulatory expansion.
Product Type:
Electroencephalography devices anchor volume procurement, while neurostimulators concentrate premium revenue despite constrained reimbursement pathways.
- Electroencephalography Devices:These systems acquire cortical electrical signals at sampling rates exceeding 256 Hz, with 32-256 channel configurations dominating German university hospital procurement. Demand concentrates in integrated stroke units across Germany, France, and the United Kingdom, where continuous monitoring requirements are tightening clinical specifications for amplifier fidelity and artifact rejection.
- Intracranial Pressure Monitors:Silicon carbide sensor substrates are displacing alumina ceramic bases, improving thermal stability and biocompatibility for long-term implantation. German and French neurosurgical centers prioritize measurement accuracy within the ±2 mmHg threshold in critical care settings, driving material transition across upstream component supply chains.
- Sleep Monitoring Systems:Polysomnography platforms serve established national sleep health programs in Sweden, Norway, and Denmark with predictable replacement cycles.
- Neurostimulators:These implantable devices carry the highest per-unit margins but face extended statutory health insurer negotiations in France and Italy.
Mature deployment sits with electroencephalography devices. Newer deployment is concentrated in neurostimulators.
End User:
Hospital infrastructure commands capital equipment budgets, while homecare settings are expanding fastest as remote patient monitoring programs scale.
- Hospitals:Tertiary centers in Germany's university hospital network drive continuous EEG and intracranial pressure monitoring procurement, with integrated stroke units centralizing neurocritical care. These institutions bundle neuro-monitoring with broader critical care informatics platforms, shifting vendor selection toward integrated system suppliers.
- Neurology Clinics:Specialized outpatient facilities concentrate ambulatory EEG and diagnostic sleep study volumes, particularly in France's regional hospital groupings.
- Research Institutions:Academic medical centers in the Netherlands and Belgium pilot next-generation AI algorithm validation for automated seizure detection.
- Homecare Settings:United Kingdom hospital neurology departments are expanding remote patient monitoring programs, opening recurring revenue models beyond capital equipment sales.
Revenue concentration remains with hospitals. Steepest expansion trajectory is emerging in homecare settings.
Technology:
Digital monitoring platforms constitute the installed base, while AI-driven analysis is embedding inference capabilities at the point of signal acquisition.
- Digital Monitoring:Conventional wired EEG and pressure monitoring systems maintain dominance in European intensive care units, with 24-bit analog-to-digital conversion now standard for clinical-grade acquisition. These platforms face replacement pressure as wireless and AI-augmented alternatives gain MDR certification.
- AI-driven Analysis:Automated seizure detection algorithms are gaining CE marking under MDR, embedding intelligence directly into monitoring hardware and creating pull-through demand for upgraded base units. These systems compress latency between neurological event detection and clinical intervention across acute care networks.
- Wireless Monitoring:Ambulatory EEG and home-based ICP monitoring systems are scaling in the United Kingdom through hospital-led remote patient programs.
- Telemedicine:Cloud-connected diagnostic platforms enable centralized interpretation of continuous neuromonitoring data from secondary hospitals lacking neurophysiology expertise.
Installed base concentration favors digital monitoring. Capability investment is shifting toward AI-driven analysis.
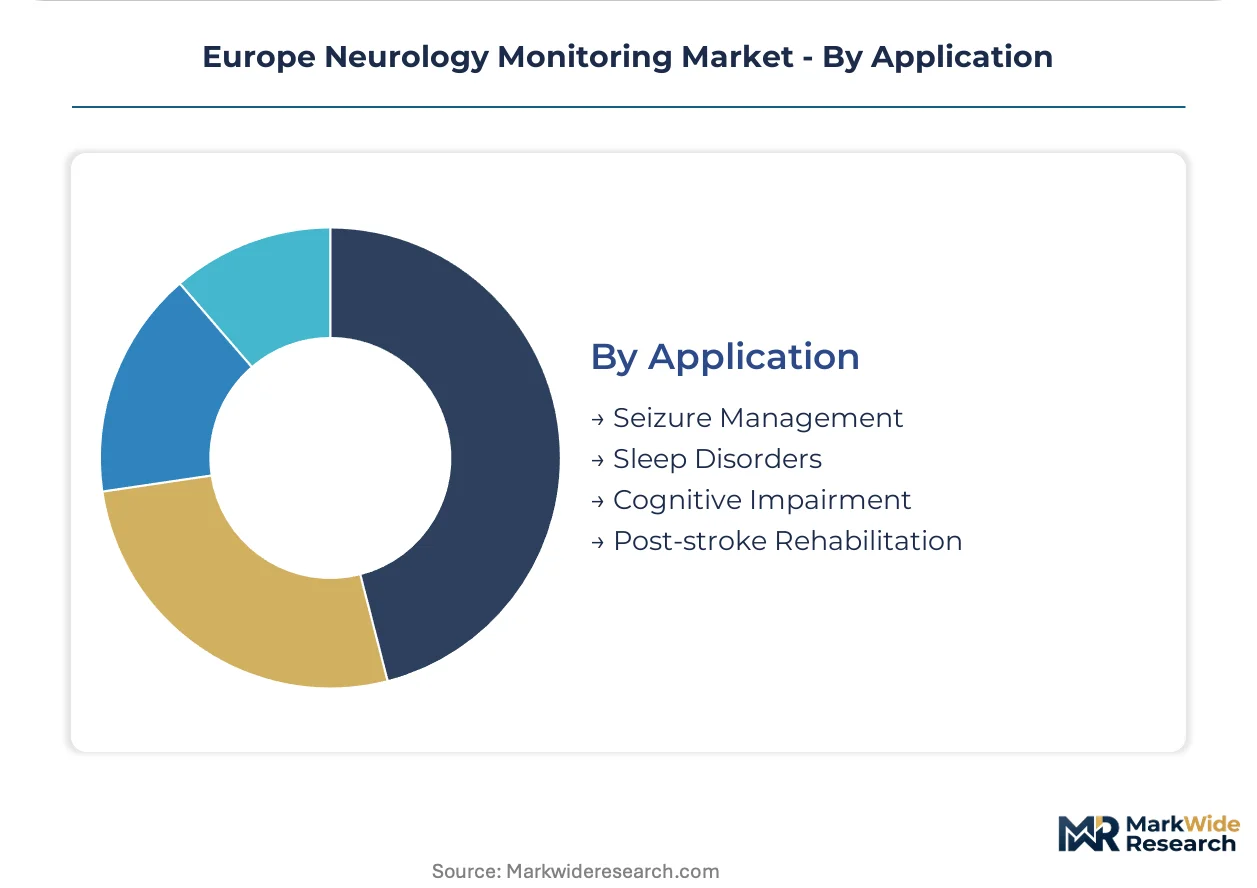
Application:
Seizure management absorbs the largest diagnostic monitoring volume, while post-stroke rehabilitation is integrating continuous monitoring into standardized care pathways.
- Seizure Management:Long-term epilepsy monitoring suites in German and French tertiary centers drive demand for high-channel-count EEG systems with video synchronization. These installations require specialized amplifier technology to sustain signal fidelity during prolonged acquisition periods.
- Post-stroke Rehabilitation:Continuous EEG and intracranial pressure monitoring are becoming standard in integrated stroke units, with Germany's university hospital network centralizing procurement for specialized hubs. This application is tightening technical requirements for electromagnetic compatibility in high-field MRI environments.
- Sleep Disorders:Nordic national sleep health programs maintain mature demand for polysomnography systems with predictable replacement cycles.
- Cognitive Impairment:Diagnostic EEG and neuropsychological testing platforms serve dementia assessment pathways in France's memory clinic networks.
Volume concentration rests with seizure management. Fastest capability integration is occurring in post-stroke rehabilitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital neurology departments concentrate procurement authority in Germany's university hospital network, where integrated stroke units drive continuous EEG and intracranial pressure monitoring adoption. France and the United Kingdom follow with expanding remote patient monitoring programs, while Nordic countries maintain mature sleep health infrastructure. Southern European markets face extended reimbursement cycles that delay neurostimulator commercial traction.
Germany
Integrated stroke units in Berlin, Munich, and Hamburg centralize neurocritical care procurement, driving demand for high-channel-count EEG systems and MRI-compatible monitoring platforms. BfArM enforces MDR compliance through unannounced manufacturer audits that extend certification timelines for novel devices. The Baden-Württemberg medical technology cluster anchors production of silicon carbide sensor substrates for next-generation intracranial pressure monitors.
France
Regional hospital groupings concentrate ambulatory EEG volumes in Paris, Lyon, and Marseille, while memory clinic networks in Île-de-France drive cognitive impairment diagnostic demand. ANSM coordinates national MDR enforcement alongside EMA centralized assessments, lengthening pre-market clinical evidence requirements. The Grenoble neurotechnology corridor hosts academic medical centers piloting AI algorithm validation for automated seizure detection.
United Kingdom
NHS neurology departments in London, Manchester, and Birmingham scale ambulatory EEG and home-based ICP monitoring programs, opening recurring revenue models beyond capital equipment sales. MHRA operates under retained EU law alignment for MDR transition, maintaining CE marking recognition while building sovereign capacity. The Cambridge-Oxford-London life sciences triangle concentrates neurodiagnostic R&D partnerships between academic hospitals and monitoring device developers.
Sweden
National sleep health programs in Stockholm, Gothenburg, and Malmö maintain predictable replacement cycles for polysomnography systems with established screening infrastructure. The Medical Products Agency enforces REACH chemical regulations that constrain mercury-free electrode material selection. The Uppsala medical technology cluster specializes in wireless monitoring platforms for ambulatory neurological assessment.
Italy
Tertiary centers in Milan, Rome, and Naples concentrate epilepsy monitoring suite installations, though neurostimulator commercial traction faces protracted pricing negotiations with statutory health insurers. The Italian Medicines Agency implements MDR transitional provisions that stagger certification deadlines across device risk classes. The Emilia-Romagna medical device district hosts contract manufacturers serving European neurology monitoring OEMs with component assembly and sterilization services.
Europe Neurology Monitoring Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers recalibrate pipeline priorities around platform extensions rather than breakthrough device categories. The vendor base concentrates among integrated critical care informatics suppliers, specialized neurodiagnostic equipment makers, and component technology providers. Three archetypes define positioning: diversified medtech conglomerates bundling neuro-monitoring with hospital IT systems, pure-play neurology specialists defending amplifier technology advantages, and upstream material suppliers controlling silicon carbide sensor substrate production. M&A activity and technology licensing agreements represent the primary competitive moves as firms acquire AI algorithm capabilities and electromagnetic shielding expertise.
Among diversified medtech conglomerates, Koninklijke Philips N.V. and Siemens Healthineers AG exemplify the integrated platform strategy, anchoring European hospital procurement through critical care informatics bundling. Nihon Kohden Corporation occupies a specialist position, representing the pure-play archetype with proprietary amplifier technology sustaining premium positioning in long-term epilepsy monitoring suites. These three entities collectively illustrate the competitive tension between horizontal integration and vertical capability depth across the European neurology monitoring supply chain.
| Leading Market Players |
|---|
| Natus Medical Inc. |
| Nihon Kohden Corporation |
| Dragerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic PLC |
| Siemens Healthineers AG |
| Masimo Corporation |
| Compumedics Limited |
| Others |
Supply & Pricing Matrix
Neurophysiology engineering talent clusters in southern Germany's medical technology corridor, where labor-cost differentials between Baden-Württemberg specialists and contract manufacturers in Italy's Emilia-Romagna district widen pricing spreads between premium integrated systems and economy-tier component assemblies.
Pricing Analysis
Volume concentrates in electroencephalography base units while margins pool in neurostimulator implants and AI-augmented monitoring platforms. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified systems with full clinical validation from transitional devices and unbundled component sales. Pricing pressure stems from hospital procurement departments unbundling after-sales service contracts and internalizing routine calibration through centralized biomedical engineering. Secondary hospitals exhibit highest price sensitivity due to concentrated neurophysiology expertise in tertiary centers limiting utilization rates.
Supply Chain Analysis
Freight costs for silicon carbide sensor substrates from German foundries to French neurosurgical centers and UK hospital networks have intensified margin scrutiny on intracranial pressure monitor assemblies. Component sourcing draws from Germany for precision amplifiers, Japan for specialized electromagnetic shielding materials, and the Netherlands for wireless telemetry modules. Single-source vulnerability concentrates in MRI-compatible EEG shielding expertise residing with limited supplier pools. Distribution runs through hospital procurement consortiums in university networks and group purchasing organizations serving regional hospital groupings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate adoption is displacing legacy ceramic bases in intracranial pressure monitors, compressing margins for incumbent ceramic suppliers while opening premium positioning for integrated device manufacturers with captive material capabilities.
For Market Incumbents: Extend platform architecture investments to absorb AI algorithm modules gaining MDR certification, creating pull-through demand that defends installed base positions against modular competitors. Deepen backward integration into silicon carbide sensor substrate production to capture margin migrating upstream from device assembly. Prioritize electromagnetic shielding expertise acquisition as MRI-compatible EEG technical barriers widen competitive moats.
For New Entrants and Emerging Players: Launch via software-as-a-service models embedding seizure detection algorithms into existing hospital IT infrastructure, bypassing capital equipment procurement cycles. Target homecare settings in the United Kingdom where NHS remote patient monitoring programs create predictable demand without tertiary center concentration. Exploit interoperability gaps in fragmented European hospital IT architectures through cloud-connected diagnostic platforms.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play neurology specialists possessing proprietary amplifier technology given AI algorithm CE marking accelerating hardware upgrade cycles. Long-term viability favors vendors controlling both sensor substrate supply and critical care informatics bundling capability. Watch MDR audit enforcement intensity from BfArM and ANSM as inflection indicator for certification timeline risk and consolidation pressure on mid-tier manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements for AI algorithms compress time-to-market for automated seizure detection systems. |
| Hospital System Partnership | Integrated stroke unit procurement in Germany's university network anchors multi-year monitoring platform contracts. |
| Backward Integration | Captive silicon carbide sensor substrate production secures margin and thermal stability specifications for ICP monitors. |
| Software Companion Development | Cloud-connected diagnostic platforms enable centralized interpretation from secondary hospitals lacking neurophysiology expertise. |
| Reimbursement Strategy | Statutory health insurer negotiations in France and Italy determine neurostimulator commercial traction timelines. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and EMA neurotechnology assessment records underwrites the qualitative findings. Primary interviews with clinicians in German integrated stroke units, biomedical engineers in UK NHS trusts, and GPO contracts managers in French regional hospital groupings combined with secondary validation from BfArM audit disclosures, ANSM enforcement bulletins, and REACH chemical regulation amendments. Bottom-up demand modeling across product types and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to historical MDR transition timelines and pre-pandemic procurement cycles established baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, end-user setting, technology layer, and application pathway with regional regulatory cluster differentiation. CAGRs derive from installed base replacement cycles, AI algorithm adoption curves, and remote patient monitoring program scale-out trajectories. Forecast inputs incorporate REACH chemical constraint impacts on electrode material costs and MDR audit frequency effects on certification timelines.
Regulatory enforcement intensity from BfArM and ANSM, REACH chemical restriction expansion, and NHS remote monitoring budget allocation shifts are the dominant revision risks. Forecasts reflect assumptions about MDR transitional provision deadlines and statutory health insurer negotiation outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Optic Neuritis Treatment Market
Neurology
Chordoma Disease Market
Neurology
Spain Neurology Devices Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
Hepatic Encephalopathy Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Middle-East and Africa Neurology Monitoring Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Global Narcolepsy Therapeutics Market
Neurology
Canada Neurology Devices Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Arachnoiditis Treatment Market
Neurology
South Korea Neurology Devices Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
Global Diabetic Neuropathy Treatment Market