
 3D Neuroscience Market | 2026-2036
3D Neuroscience Market Size, Share, and Industry Trends Forecast 2026-2036
3D Neuroscience Market Outlook
Pharmaceutical end users is repositioning the 3D neuroscience equipment landscape as CNS drug developers seek higher-resolution neuroanatomy data. Siemens Healthineers leverages its installed base of MRI platforms to extend into integrated brain mapping workflows. Thermo Fisher Scientific anchors its position through R&D intensity in electron microscopy for neural circuit reconstruction. Bruker Corporation specializes in preclinical imaging systems that dominate academic core facilities.
3D neuroscience encompasses volumetric imaging, computational reconstruction, and spatial analysis technologies that render neural structures in three dimensions at resolutions spanning millimeters to nanometers. Functional parameters include voxel resolution, temporal sampling rates, and registration accuracy across multimodal datasets for applications ranging from clinical diagnosis to cognitive research. Brain mapping tools lead technology adoption as laboratories prioritize connectome-scale projects, while neuroimaging software captures expanding margin pools through recurring licensing models. Scanners remain the largest product type by capital expenditure, though analysis platforms are growing fastest as cloud-native architectures displace on-premise workstations.
FDA 510(k) pathways and EMA MDR frameworks govern clinical deployment of neuroimaging devices, while HIPAA and GDPR constrain cross-border data flows for patient-derived brain datasets. The EU AI Act introduces conformity requirements for diagnostic algorithms embedded in imaging software, reshaping market access for non-European vendors. Stakeholders must monitor how regulatory divergence between FDA's predicate-based system and EMA's emerging software-as-medical-device rules affects platform development costs and geographic rollout sequencing.
Market Dynamics
Pharmaceutical procurement of brain mapping infrastructure is compressing sales cycles for high-resolution neuroimaging systems as CNS drug pipelines expand validation requirements for digital biomarkers.
Growth Catalysts
- NIH-funded laboratory upgrades:United States research facilities are accelerating scanner and workstation replacement cycles. Federal neuroscience initiatives channel capital toward connectome-scale imaging platforms.
- EMA MDR framework expansion:European medical device regulations are formalizing software-as-medical-device pathways for neuroimaging algorithms. Vendors are pre-emptively building conformity documentation for algorithmic diagnostic tools.
- Cloud-native architectures:Computational reconstruction platforms are displacing on-premise analysis workstations. Academic core facilities and pharmaceutical R&D groups are adopting subscription-based licensing for spatial analysis tools.
Market Restraints
- Helium supply concentration:MRI scanner magnet cooling depends on geographically concentrated helium extraction. Price volatility in noble gas markets elevates total cost of ownership for high-field neuroimaging systems.
- FDA 510(k) predicate limitations:Novel neuroimaging software lacking established predicate devices faces extended validation timelines. Digital biomarker developers encounter regulatory friction when clinical claims exceed cleared indications.
- Electron microscopy infrastructure requirements:Neural circuit reconstruction demands specialized facilities with vibration isolation and electromagnetic shielding. Capital intensity constrains adoption outside elite academic and government laboratories.
Strategic Opportunities
- Preclinical imaging outsourcing:Contract research organizations are building dedicated small-animal neuroimaging capabilities. Pharmaceutical sponsors seek externalized access to Bruker and Siemens preclinical platforms without capital commitment.
- EU AI Act diagnostic algorithm certification:Early compliance with European artificial intelligence conformity requirements creates first-mover positioning. Vendors embedding explainability features into neuroimaging software capture regulatory preference.
- Asia-Pacific academic consortia:National brain mapping initiatives in Japan, South Korea, and Australia are aggregating procurement for multimodal imaging systems. Regional purchasing cooperatives concentrate demand for integrated hardware-software packages.
Industry Challenges
- Computational neuroanatomy talent scarcity:Volumetric reconstruction and multimodal registration require specialized expertise spanning imaging physics and machine learning. Universities produce insufficient cross-trained graduates for vendor and end-user hiring needs.
- HIPAA-GDPR data flow fragmentation:Patient-derived brain datasets face conflicting cross-border transfer requirements. Multi-site neuroimaging studies encounter operational friction in constructing compliant data sharing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Neuroscience Market |
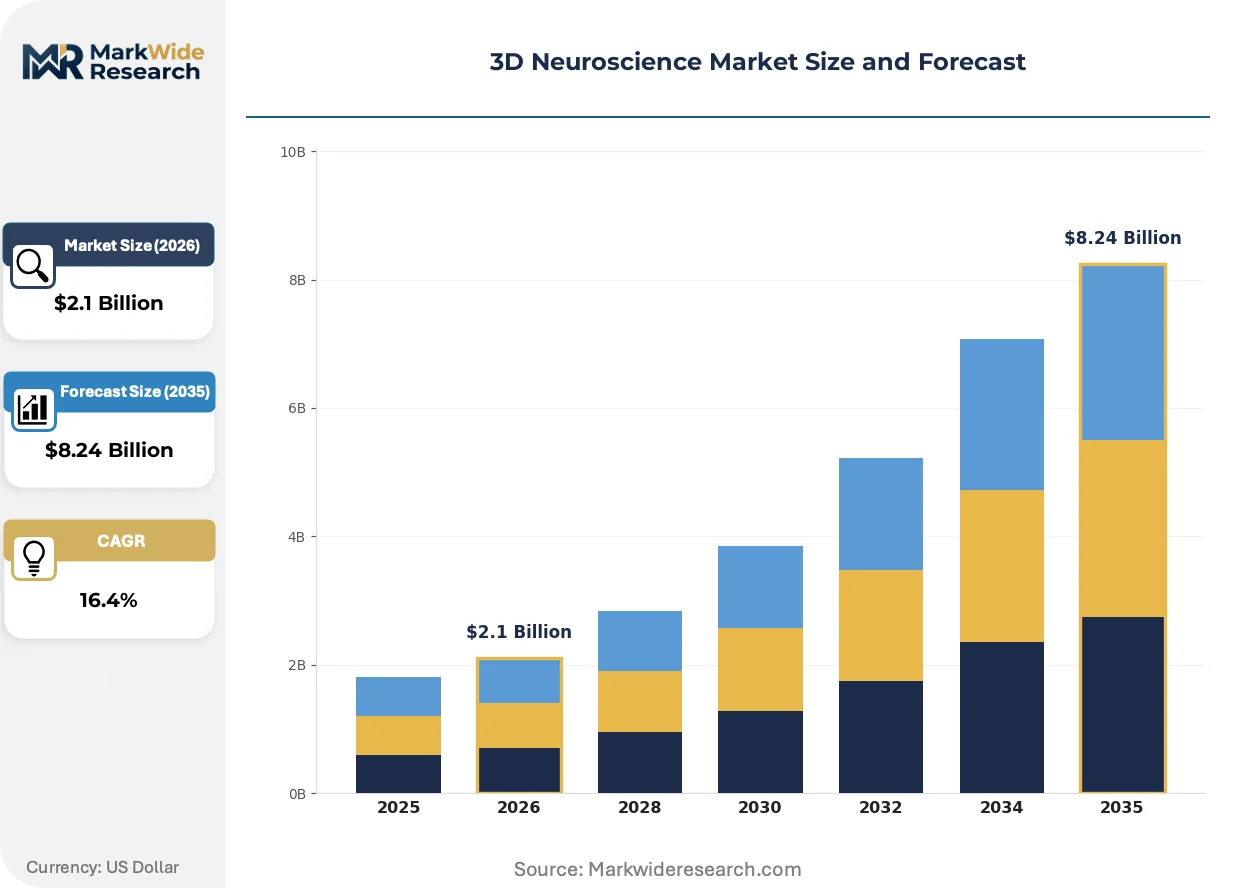
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.24 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 3D Imaging, Neuroimaging Software, Brain Mapping Tools, Simulation Software End User: Academic Institutions, Pharmaceuticals, Research Laboratories, Hospitals Application: Clinical Diagnosis, Drug Development, Cognitive Research, Neuroanatomy Studies Product Type: Scanners, Workstations, Imaging Software, Analysis Platforms |
| Companies Covered | GE HealthCare, Siemens Healthineers, Thermo Fisher Scientific, Bruker Corporation, Doric Lenses Inc., Laserglow Technologies, Mightex Systems, NeuroNexus Technologies, Noldus Information Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Neuroscience Market Strategic Shifts
Deep learning architectures are compressing manual annotation burdens in neural circuit reconstruction while regulatory frameworks for algorithmic diagnostics crystallize across major jurisdictions.
Machine learning-based segmentation is automating voxel-level classification of neural structures in electron microscopy volumes. Pharmaceutical neuroanatomy groups are adopting these tools for target validation studies. The technology is automating previously manual tracing workflows that consumed months of postdoctoral researcher time per dataset.
The EU AI Act introduces conformity assessment requirements for diagnostic algorithms embedded in neuroimaging software. European vendors are restructuring quality management systems to accommodate notified body involvement in algorithm updates. Imaging software developers targeting European clinical deployment are prioritizing explainability documentation and risk classification protocols.
Academic core facilities are unbundling scanner access from analysis services, creating standalone revenue streams for computational reconstruction expertise. Pharmaceutical sponsors increasingly contract directly with university imaging centers for specialized preprocessing pipelines rather than acquiring perpetual software licenses. This pattern concentrates most visibly in United States research corridors where NIH-funded cores compete for industrial contracts.
3D Neuroscience Market Segmentation
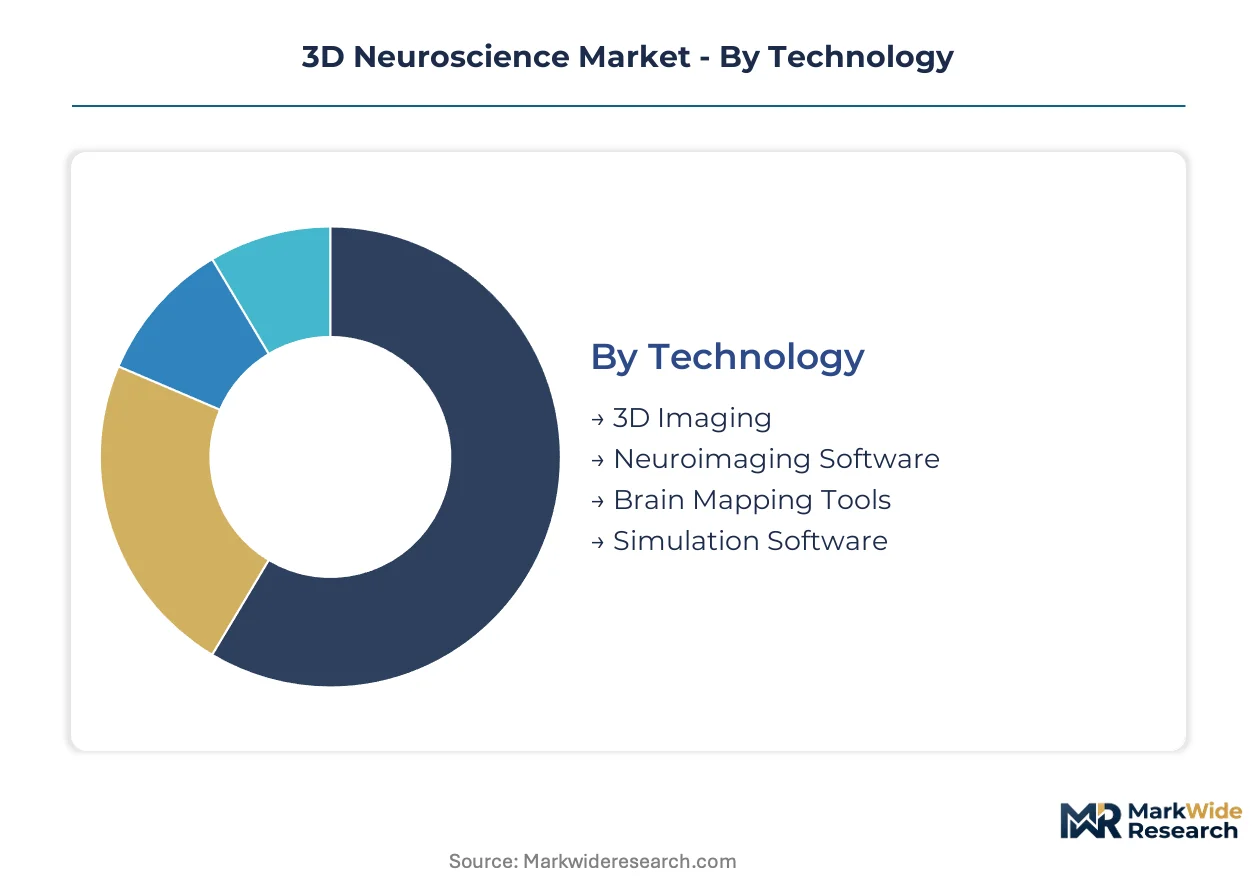
Segmentation in 3D neuroscience reveals divergent commercial logics across hardware, software, and service layers. Technology categories split between capital-intensive imaging infrastructure and recurring-license analytics, while end-user concentration in United States federal laboratories shapes regional demand patterns.
Technology:
Volume concentrates in imaging hardware where scanner replacement cycles dominate procurement budgets, while premium margin capture shifts toward algorithmic and cloud-native platforms.
- 3D Imaging:Volumetric acquisition systems span MRI, PET, and optical modalities with field strengths from 3T to 7T for human neuroimaging. NIH-funded facilities in Bethesda and Boston drive upgrade demand as connectome-scale projects require higher spatial resolution.
- Neuroimaging Software:Computational reconstruction and multimodal registration platforms command recurring revenue through subscription licensing. Pharmaceutical R&D groups in Cambridge and South San Francisco prioritize cloud-native architectures that displace on-premise workstations.
- Brain Mapping Tools:Specialized hardware-software bundles for connectome reconstruction target elite academic consortia.
- Simulation Software:Neural circuit modeling environments support computational psychiatry and target validation workflows.
Today's leader: 3D Imaging. Tomorrow's challenger: Neuroimaging Software.
End User:
Customer types separate by procurement authority—federal grant funding versus pharmaceutical capital budgets versus hospital operational expenditure.
- Academic Institutions:University imaging cores combine scanner access with analysis service revenue. Harvard-MIT and Stanford clusters compete for pharmaceutical outsourcing contracts.
- Pharmaceuticals:CNS drug developers compress sales cycles for high-resolution systems as digital biomarker validation requirements tighten. Roche and Biogen procurement teams prioritize preclinical-to-clinical translational platforms.
- Research Laboratories:Government facilities including NIH intramural programs and Broad Institute drive standardized platform adoption.
- Hospitals:Clinical deployment faces FDA 510(k) pathway constraints for algorithmic diagnostic claims.
Pharmaceuticals currently anchor procurement volume. Academic Institutions are gaining share fastest through service unbundling strategies.
Application:
Use cases diverge by regulatory intensity—clinical claims face FDA and EMA validation requirements while research applications operate under lighter oversight.
- Drug Development:Target validation and biomarker qualification demand preclinical imaging through Phase IIa proof-of-mechanism studies. Contract research organizations build dedicated small-animal capabilities to serve sponsor demand without capital commitment.
- Clinical Diagnosis:Algorithmic diagnostic tools embedded in neuroimaging software face tightening EU AI Act conformity requirements and FDA predicate limitations for novel claims.
- Cognitive Research:Connectome-scale projects prioritize temporal resolution for functional connectivity mapping.
- Neuroanatomy Studies:Electron microscopy volumes for neural circuit reconstruction require specialized facility infrastructure.
Drug Development commands current spending intensity. Clinical Diagnosis faces the steepest regulatory climb to commercial scale.
Product Type:
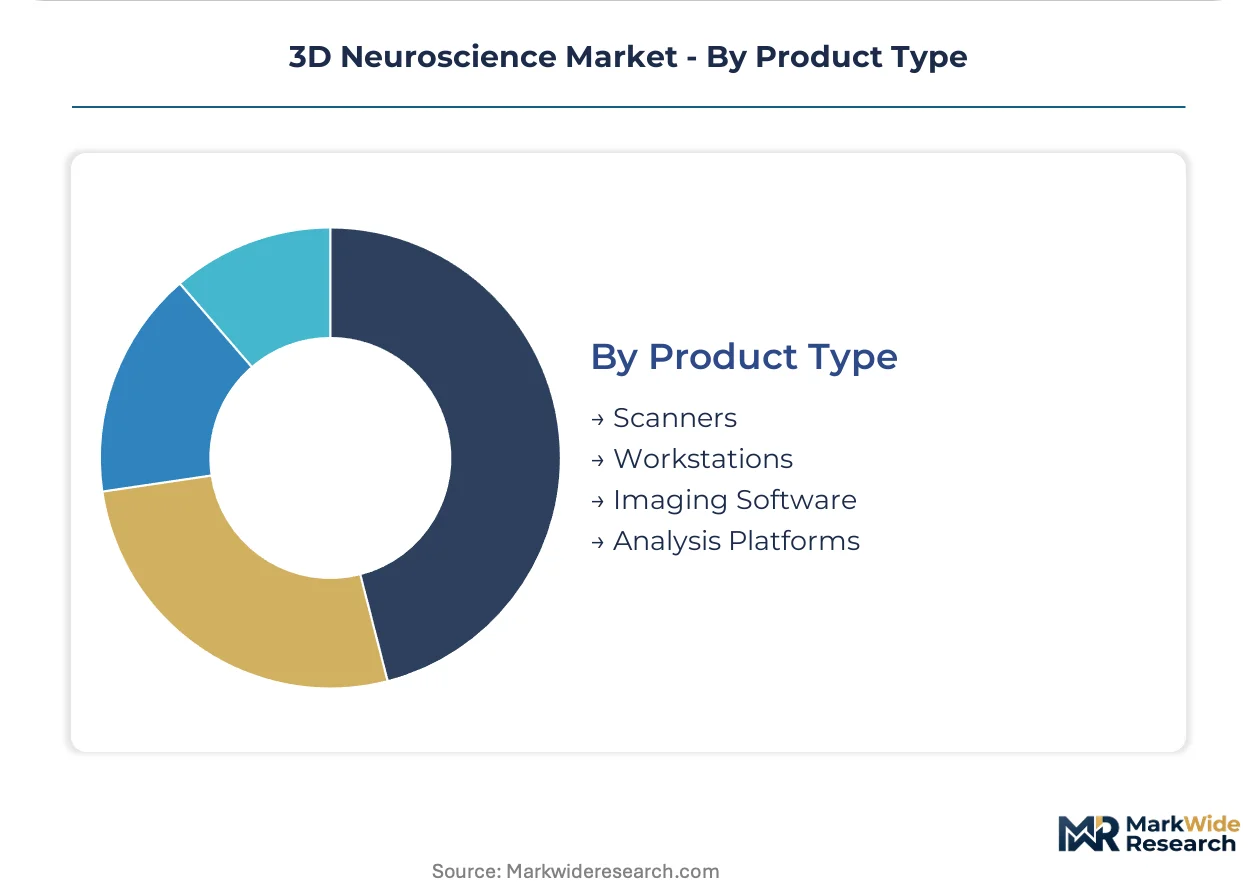
Hardware-software margin structures separate by ownership model—capital sale versus recurring license versus usage-based service.
- Scanners:MRI and preclinical imaging systems represent the largest capital expenditure category with magnet cooling dependencies on geographically concentrated helium supply. Siemens Healthineers and Bruker Corporation installed bases create switching costs for academic core facilities.
- Analysis Platforms:Cloud-native spatial analysis tools are expanding most quickly as subscription licensing displaces perpetual software purchases. Academic cores unbundle these services for standalone revenue streams.
- Workstations:On-premise computational hardware faces displacement by cloud architectures.
- Imaging Software:Embedded diagnostic algorithms require explainability documentation for EU AI Act compliance.
Scanners dominate capital deployment. Analysis Platforms are climbing the fastest through recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge neuroscience corridor anchors procurement intensity for high-resolution neuroimaging infrastructure as pharmaceutical R&D groups and NIH-funded laboratories concentrate scanner demand. Federal neuroscience initiatives channel capital toward connectome-scale platforms while regulatory divergence between FDA predicate-based pathways and EMA software-as-medical-device frameworks shapes vendor rollout sequencing.
United States
NIH intramural programs in Bethesda and Harvard-MIT imaging cores drive replacement cycles for 7T MRI and preclinical systems. FDA 510(k) pathways constrain novel neuroimaging software lacking established predicates, extending validation timelines for digital biomarker developers. The Stanford-South San Francisco corridor concentrates pharmaceutical outsourcing demand for specialized preprocessing pipelines.
Germany
Siemens Healthineers leverages its installed base in Munich and Erlangen to extend integrated brain mapping workflows. The EU AI Act introduces conformity assessment requirements for diagnostic algorithms, forcing quality management system restructuring for vendors targeting clinical deployment. Heidelberg and Berlin academic consortia aggregate procurement for multimodal imaging packages.
Japan
METI-funded national brain mapping initiatives in Tokyo and Osaka concentrate demand for electron microscopy and optical imaging systems. PMDA regulatory frameworks govern clinical neuroimaging device approval, though research applications operate under lighter oversight. The Riken Brain Science Institute in Wako anchors elite facility infrastructure for neural circuit reconstruction.
United Kingdom
The Francis Crick Institute and UCL Queen Square Neuroimaging Centre in London prioritize cloud-native analysis architectures over on-premise workstations. GDPR constraints on patient-derived brain datasets create operational friction for multi-site studies requiring cross-border data flows. Cambridge neurotechnology clusters compete for pharmaceutical service contracts.
Australia
National imaging facilities at Monash and Queensland Brain Institute aggregate academic demand for preclinical-to-clinical translational platforms. TGA regulatory pathways align with FDA frameworks for neuroimaging software, reducing vendor adaptation costs. Melbourne and Sydney research corridors specialize in cognitive research applications with lighter regulatory intensity.
3D Neuroscience Market Competitive Environment
Portfolio diversification dominates the current landscape as established imaging hardware vendors extend into recurring-revenue software and service layers. The market structure tiers between capital-intensive scanner manufacturers with deep installed bases and emerging cloud-native analysis platforms capturing margin expansion. Three archetypes define competitive positioning: integrated hardware-software conglomerates, specialized preclinical imaging specialists, and algorithmic diagnostic developers. M&A activity concentrates on software capabilities that complement legacy scanner portfolios, while strategic partnerships between academic core facilities and pharmaceutical sponsors externalize capital commitment.
Within the integrated conglomerate tier, Siemens Healthineers and GE HealthCare exemplify archetypes leveraging MRI platform installed bases to capture brain mapping workflow revenue. Thermo Fisher Scientific occupies a position representing R&D-intensive specialization in electron microscopy for neural circuit reconstruction. Bruker Corporation anchors the preclinical imaging specialist archetype, dominating academic core facility procurement with small-animal neuroimaging systems. These three companies collectively illustrate how vendor positioning diverges by resolution scale and end-user capital authority.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Bruker Corporation |
| Doric Lenses Inc. |
| Laserglow Technologies |
| Mightex Systems |
| NeuroNexus Technologies |
| Noldus Information Technology |
| Others |
Value Chain & Pricing Dynamics
EU AI Act conformity requirements gate qualified supply for neuroimaging software vendors and anchor premium-tier pricing for embedded diagnostic algorithms with explainability documentation. Helium supply concentration for MRI magnet cooling and cloud-native architecture migration reshape procurement economics across hardware and service layers.
Pricing Analysis
Distributor margins for scanner systems compress as direct OEM relationships expand, while subscription licensing for neuroimaging software captures recurring revenue through SaaS-tiered models. Price differentiation hinges on FDA 510(k) clearance tier and cloud deployment architecture, with academic core facilities showing highest price sensitivity and pharmaceutical R&D groups least sensitive due to biomarker validation timelines. Cost compression in on-premise workstation tiers intensifies because cloud-native platforms displace perpetual license models.
Supply Chain Analysis
Freight costs for MRI scanner magnet components elevate total landed cost from Germany, Japan, and United States manufacturing hubs. The supply chain draws from concentrated helium extraction in Qatar, Algeria, and Russia for magnet cooling, plus specialized semiconductor foundries in Taiwan and South Korea for detector arrays. Single-source vulnerability in noble gas markets threatens scanner production continuity. Distribution runs through authorized service networks for hardware and direct API provisioning for cloud-native software platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D neuroscience market functions as a geographic-arbitrage play where EU AI Act compliance costs in Europe diverge from FDA predicate-based validation expenses in the United States, creating differential margin structures for vendors with regulatory flexibility.
For Market Incumbents: Deploy cloud-native platform extensions to defend against specialized algorithmic diagnostic developers eroding software margins. Siemens Healthineers and GE HealthCare should deepen backward integration into helium recycling infrastructure to offset noble gas price volatility. Certification investment in EU AI Act conformity documentation preserves European market access against emerging software-as-medical-device rules.
For New Entrants and Emerging Players: Begin with preclinical imaging outsourcing services where CRO demand concentrates pharmaceutical sponsor relationships without capital-intensive scanner manufacturing. Contract research organizations in the Boston-Cambridge corridor represent the most penetrable entry point. A go-to-market angle anchored in specialized preprocessing pipelines for digital biomarker developers bypasses direct competition with installed-base incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for cloud-native neuroimaging software specialists because fragmented academic core facility procurement lacks standardized platform consolidation. The five-to-ten-year viability window favors vendors with recurring license architectures over perpetual sale dependencies. Acquisition targets should demonstrate EU AI Act conformity progress. The signal to watch is FDA software-as-medical-device guidance alignment with EMA frameworks as inflection indicator for regulatory arbitrage closure.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription licensing displaces perpetual sales for Thermo Fisher and Bruker software divisions. |
| EU AI Act Conformity Investment | Early compliance creates positioning advantage against FDA-centric competitors in European clinical markets. |
| Preclinical CRO Capacity Buildout | Externalized access to Bruker and Siemens platforms reduces pharmaceutical capital commitment requirements. |
| Helium Recycling Infrastructure | Backward integration into noble gas recovery mitigates Qatar supply concentration risk for MRI manufacturers. |
| Academic Core Facility Partnership | Harvard-MIT and Stanford clusters concentrate demand for specialized preprocessing pipeline contracts. |
Study Parameters
Direct dialogue with neuroimaging core facility directors, pharmaceutical CNS drug development executives, FDA regulatory affairs specialists, and academic principal investigators grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EMA MDR submissions, NIH RePORTER grant databases, and GPO hospital procurement records. Bottom-up scanner shipment tracking and top-down neuroscience research expenditure analysis provided triangulation across market sizing dimensions.
Bottom-up modeling of installed base replacement cycles and top-down NIH funding allocation patterns converged across the projection horizon. Segmentation dimensions included technology modality, end-user capital authority, application regulatory intensity, and product ownership model. CAGRs derived from connectome-scale project pipeline analysis and pharmaceutical biomarker validation timeline compression. Industry-specific inputs incorporated helium market price volatility curves and cloud infrastructure adoption rates in academic research settings.
Caveats apply where FDA software-as-medical-device guidance evolution or EU AI Act enforcement discretion could materially shift the outlook for algorithmic diagnostic deployment. Forecasts reflect assumptions about federal neuroscience funding continuity and noble gas supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Canada Neurology Devices Market
Neurology
Global Neuromarketing Market
Neurology
Neuroendocrine Carcinoma Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
Arachnoiditis Market
Neurology
Status Epilepticus Treatment Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Brazil Neurology Devices Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
Global Neuroblastoma Market
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Intracranial Aneurysm Market
Neurology
Optic Neuritis Treatment Market
Neurology
Hydrocephalus Market