
 TMJ Disorders Market | 2026-2036
TMJ Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
TMJ Disorders Market Outlook
Multi-source procurement of temporomandibular joint implants and pharmaceutical APIs is consolidating as hospitals and specialty clinics seek supply security amid raw material volatility. Zimmer Biomet anchors the orthopedic device segment through its established craniomaxillofacial portfolio. Bristol-Myers Squibb leverages its immunology pipeline to compete in adjunctive therapies for TMJ-related inflammation. Sun Pharmaceutical Industries Ltd specializes in cost-competitive generic formulations that sustain pricing pressure across emerging markets.
Temporomandibular joint disorders encompass dysfunctions of the masticatory system involving the mandibular condyle, articular disc, and glenoid fossa, with diagnostic criteria relying on MRI visualization of disc displacement and joint effusion alongside clinical examination of mandibular range of motion. The condition primarily serves to restore functional occlusion and pain-free mandibular movement in patients presenting with myofascial pain, internal derangement, or degenerative joint disease. Medications dominate current revenue flows due to chronic management requirements, while surgical treatments command premium positioning despite restricted eligibility. Non-surgical therapeutic approaches are gaining fastest traction as payers prioritize conservative intervention protocols and outpatient cost containment.
FDA 510(k) premarket notification requirements govern temporomandibular joint prostheses, while HIPAA privacy rules shape how orofacial pain clinics manage digital patient records and telehealth consultations. The European Medicines Agency's Medical Device Regulation imposes additional clinical evidence burdens on manufacturers seeking CE marking for joint replacement systems. Stakeholders must monitor evolving reimbursement codes for TMJ-specific procedures across Medicare and private payers to align portfolio investments with covered care pathways.
Market Dynamics
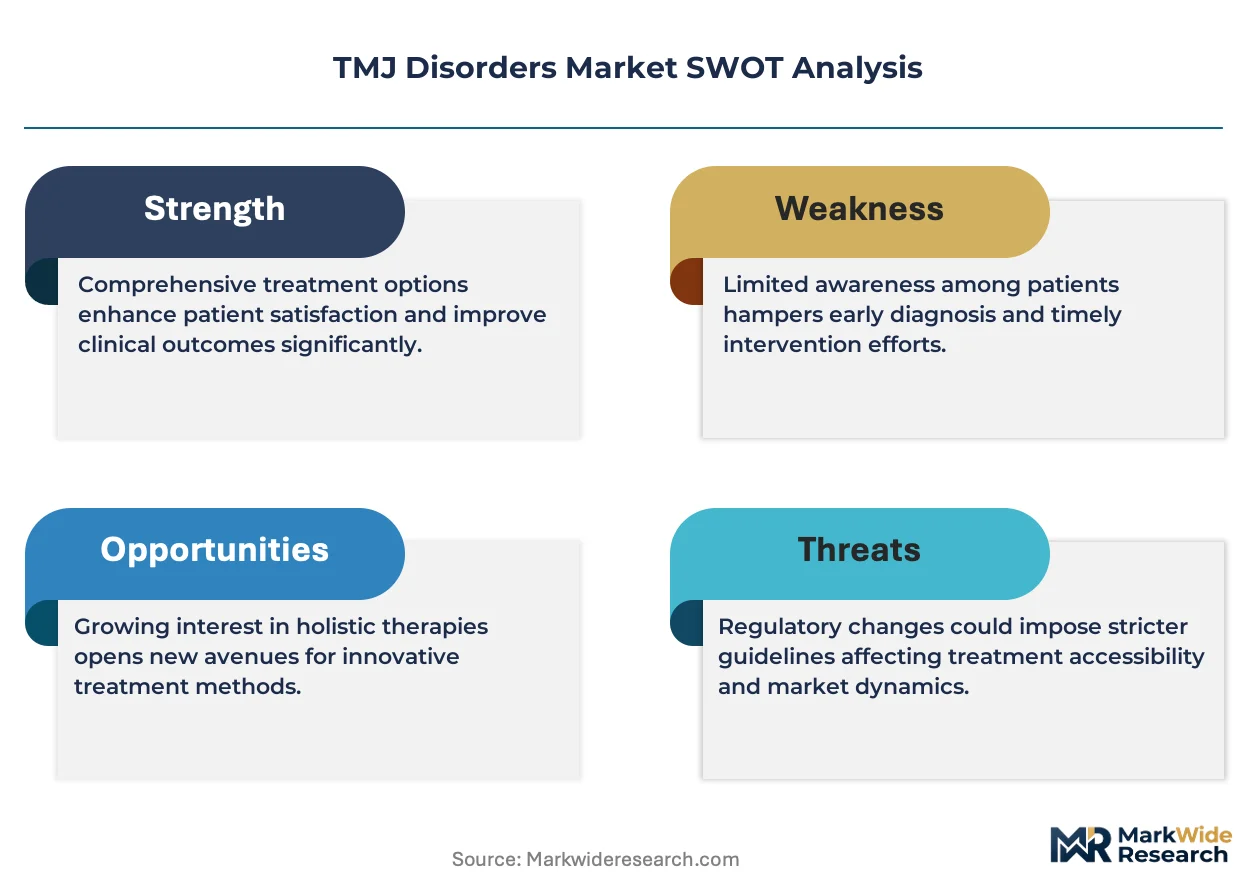
Conservative intervention protocols mandated by United States payers are compressing surgical volumes while amplifying pharmaceutical and device-based outpatient management across dental and orofacial pain networks.
Growth Catalysts
- Diagnostic Imaging Advancement:MRI visualization protocols for disc displacement and joint effusion are expanding specialist referral capacity across United States academic medical centers.
- HIPAA-Compliant Telehealth Expansion:Digital consultation platforms are extending orofacial pain specialist reach into underserved rural counties without requiring physical clinic infrastructure.
- Generic Formulation Proliferation:Cost-competitive NSAID and muscle relaxant production is sustaining patient access to chronic pharmacological management in price-sensitive markets.
Market Restraints
- Titanium Alloy Supply Concentration:Joint prosthesis manufacturers face raw material volatility concentrated among a limited set of aerospace-grade metal suppliers.
- FDA 510(k) Scrutiny Intensification:Premarket notification requirements for temporomandibular joint implants are extending regulatory timelines and elevating clinical evidence burdens.
- Conservative Protocol Substitution:Payer-mandated non-surgical first-line treatment is restricting eligible patient pools for premium arthroplasty procedures.
Strategic Opportunities
- Point-of-Care Device Integration:Portable ultrasound and jaw tracking systems are enabling chairside diagnostic confirmation within general dentistry practices.
- European MDR Harmonization:Streamlined CE marking pathways under the Medical Device Regulation are reducing redundant clinical testing for manufacturers with existing FDA clearance.
- Academic Medical Center Clustering:Specialized orofacial pain centers surrounding major United States research universities are creating concentrated high-value referral networks.
Industry Challenges
- Interdisciplinary Care Coordination:Treatment planning across dentistry, neurology, and physical therapy requires fragmented electronic health record integration.
- Prosthesis Longevity Uncertainty:Long-term implant performance data gaps complicate patient informed consent and malpractice risk assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TMJ Disorders Market |
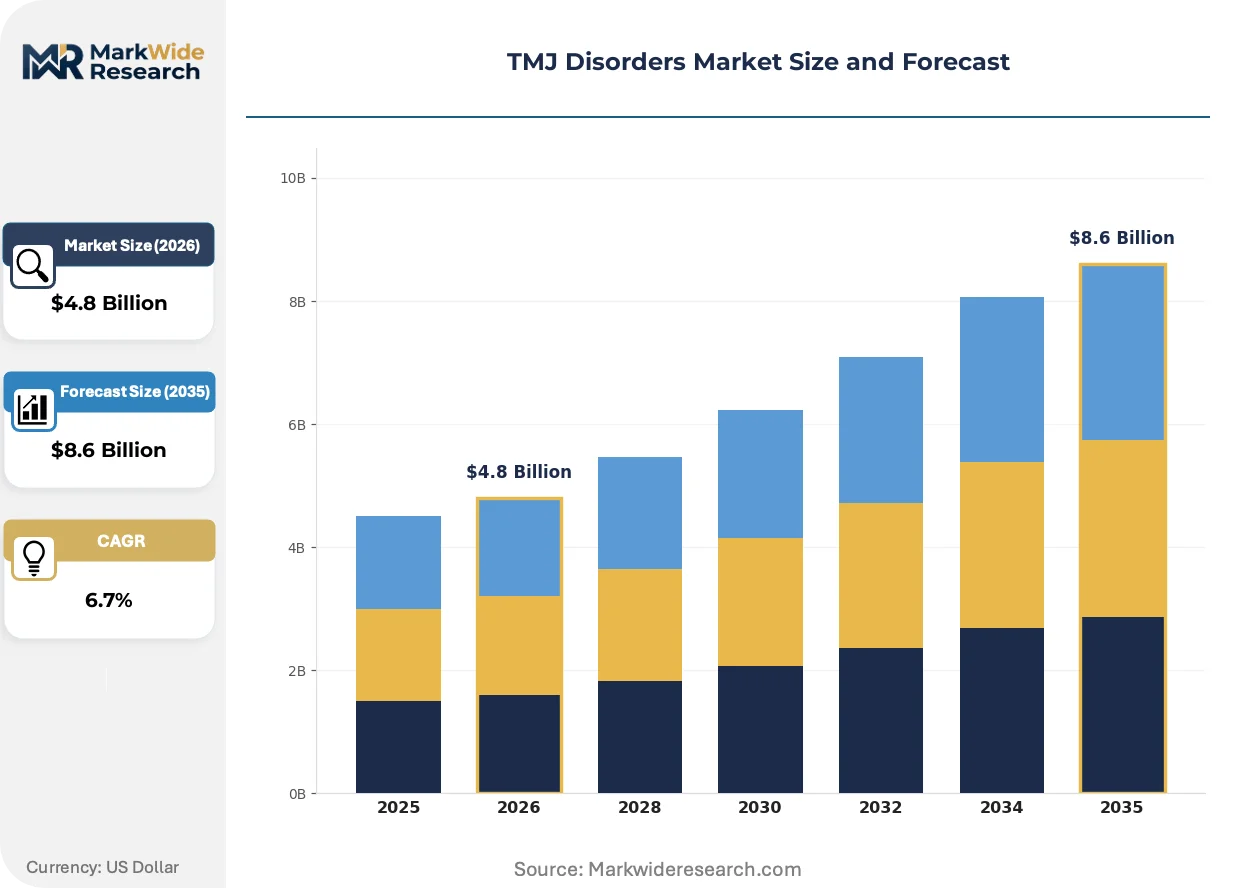
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthoses, Medications, Physical Therapy, Surgical Treatments Application: Pain Management, Dental Procedures, Rehabilitation, Supportive Care End User: Clinics, Hospitals, Home Care, Rehabilitation Centers Treatment Method: Non-Surgical, Surgical, Medication-Based, Therapeutic |
| Companies Covered | Bristol-Myers Squibb Company, Allergan, Sun Pharmaceutical Industries Ltd, Novartis, Zydus Cadila, Abbott Laboratories, Bayer, Zimmer Biomet, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TMJ Disorders Market Strategic Shifts
Digital diagnostic platforms and minimally invasive intervention modalities are displacing traditional open surgical approaches while reshaping how temporomandibular disorders are triaged across primary and specialty care boundaries.
Custom-fitted 3D-printed occlusal splints fabricated from biocompatible resins are rewriting treatment personalization standards in the dental clinic segment. These patient-specific appliances reduce adjustment appointments and improve mandibular positioning accuracy compared to thermoformed alternatives. Specialist practices in the United States are adopting intraoral scanning workflows that compress fabrication turnaround from weeks to days.
EMA Medical Device Regulation clinical evidence requirements are elevating post-market surveillance obligations for temporomandibular joint replacement manufacturers. The regulation mandates systematic literature reviews and periodic safety updates that extend compliance costs across the product lifecycle. European orthopedic device firms are restructuring quality management systems to accommodate these expanded documentation burdens.
Self-referral patterns among chronic pain patients are fragmenting traditional gatekeeper relationships between primary care and specialty orofacial pain services. Direct-to-consumer educational content and symptom-checking platforms are enabling patients to bypass general dentistry entirely. This behavioral shift concentrates highest-acuity cases in academic medical centers while community practices manage stable chronic presentations.
TMJ Disorders Market Segmentation
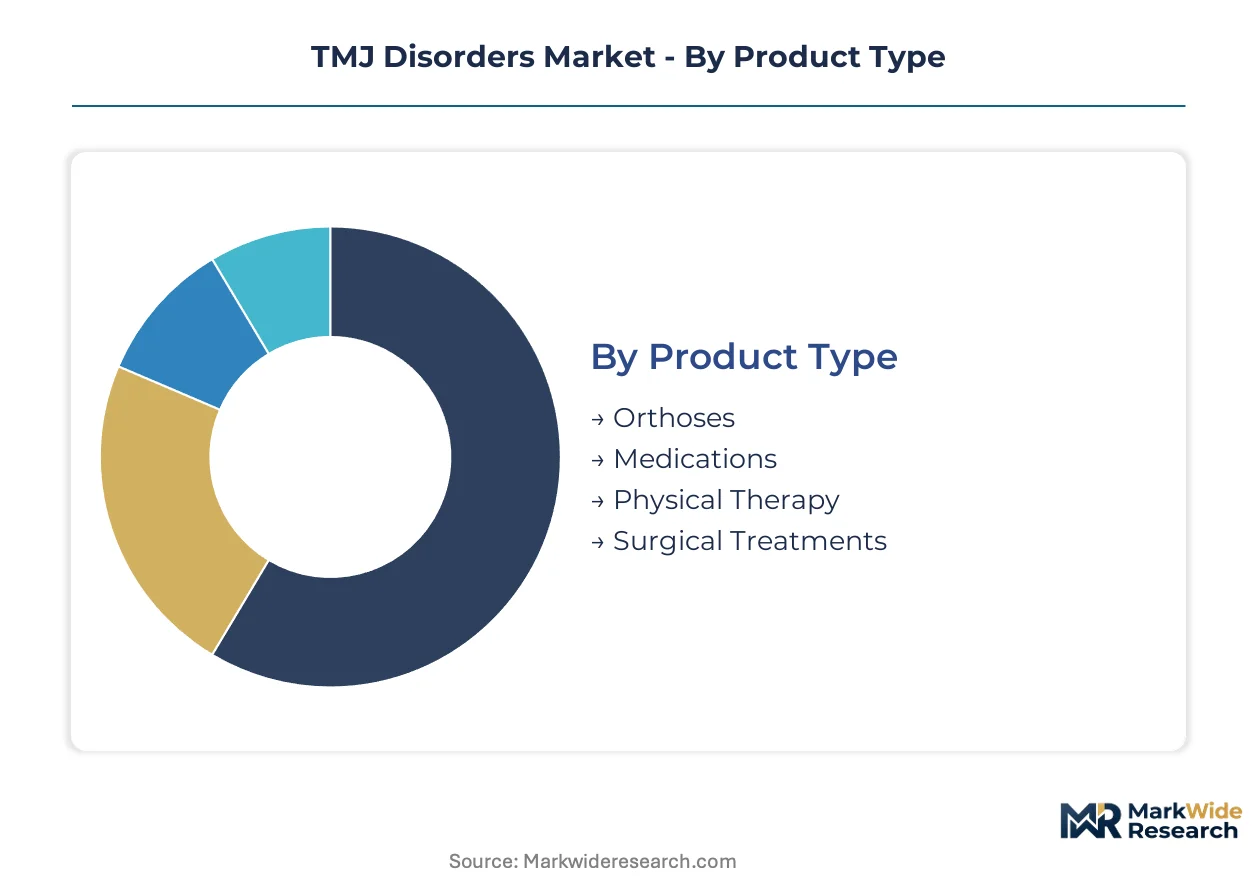
TMJ disorder treatment pathways fragment across diagnostic intensity, intervention invasiveness, and care setting economics. Supply concentration in implant-grade materials and specialized imaging equipment shapes how segments compete for patient volume and reimbursement dollars.
Product Type:
Supply concentration in biocompatible polymers and pharmaceutical APIs determines margin structures across this category.
- Medications:NSAIDs, muscle relaxants, and corticosteroid formulations dominate chronic management protocols. Demand clusters in United States retail pharmacy chains and Indian generic export markets where cost-competitive manufacturing sustains patient access.
- Orthoses:Custom-fitted occlusal splints and stabilization appliances fabricated from medical-grade resins. United States dental laboratories and German precision manufacturers capture premium positioning through digital scanning workflows and rapid turnaround capabilities.
- Physical Therapy:Jaw mobilization devices and biofeedback systems for neuromuscular retraining.
- Surgical Treatments:Arthrocentesis instruments, arthroscopic systems, and total joint prostheses requiring aerospace-grade titanium alloys.
Today's leader: Medications. Tomorrow's challenger: Orthoses.
Application:
Cost tier differentiation separates acute intervention from chronic maintenance protocols across reimbursement systems.
- Pain Management:Multimodal pharmacological and interventional approaches targeting myofascial pain and neuropathic symptoms. United States orofacial pain centers and interdisciplinary headache clinics drive specialist referral volume amid opioid-sparing mandates.
- Dental Procedures:Occlusal adjustment, restorative rehabilitation, and orthodontic intervention to correct functional occlusion. Private practice dentists in Germany and Japan integrate chairside diagnostic imaging to capture specialty referrals.
- Rehabilitation:Structured physical therapy protocols restoring mandibular range of motion.
- Supportive Care:Patient education, behavioral modification, and stress management adjuncts.
Pain Management commands the steepest expansion trajectory as diagnostic criteria formalize and chronic pain recognition spreads.
End User:
Volume concentration in outpatient settings reflects payer preference for lower-acuity care delivery.
- Clinics:Dedicated orofacial pain clinics, dental practices, and ambulatory surgery centers performing diagnostics and conservative interventions. United States metropolitan clusters around academic medical centers concentrate highest-complexity cases and specialist density.
- Hospitals:Inpatient and outpatient surgical departments managing arthroplasty and complex revision procedures. German university hospitals and Japanese tertiary centers anchor European and Asian surgical volume.
- Home Care:Self-administered splint therapy, medication compliance, and telehealth monitoring.
- Rehabilitation Centers:Structured programs combining physical therapy with psychological support.
Clinics absorb the majority of new patient volume. Hospitals retain pricing power for surgical cases.
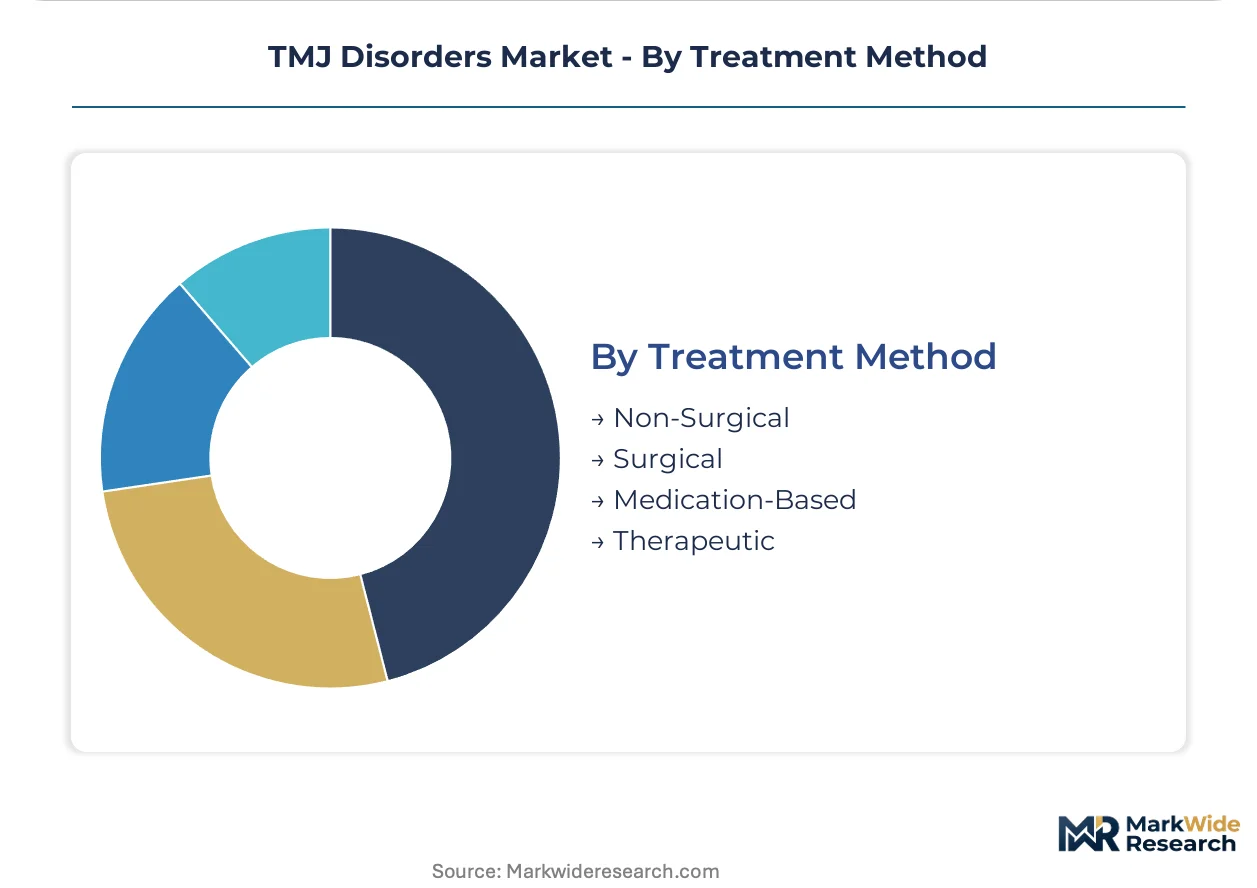
Treatment Method:
Application maturity separates established protocols from emerging minimally invasive alternatives.
- Non-Surgical:First-line interventions including splint therapy, physical therapy, and behavioral modification. United States payer mandates and European conservative care guidelines restrict surgical eligibility and expand this segment's patient pool.
- Medication-Based:Chronic pharmacological management addressing inflammation, muscle spasm, and neuropathic pain. Indian and Chinese generic manufacturers supply cost-competitive APIs to emerging markets.
- Surgical:Arthroscopy, disc repositioning, and total joint replacement requiring specialized training and implant inventory.
- Therapeutic:Emerging modalities including botulinum toxin injection, platelet-rich plasma, and regenerative approaches.
Non-Surgical dominates current volume. Therapeutic methods are climbing the fastest as evidence accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are reshaping where TMJ device manufacturing concentrates. FDA premarket scrutiny elevates compliance burdens for US-bound products while EMA pathways offer alternative clearance economics for European market entry.
United States
Orofacial pain centers cluster around academic medical hubs in Boston, Baltimore, and San Francisco where MRI diagnostic capacity expands specialist referral networks. HIPAA privacy rules shape telehealth consultation protocols across rural county extensions. The Mayo Clinic Rochester and UCLA Health anchor high-complexity surgical volume for total joint arthroplasty.
Germany
Precision dental laboratories in Stuttgart and Munich dominate custom occlusal splint fabrication through digital scanning workflows. The national pharmaceutical regulator imposes post-market surveillance obligations that exceed baseline EMA MDR requirements. University hospitals in Heidelberg and Hamburg anchor European surgical training and complex revision case concentration.
Japan
Ministry of Health, Labour and Welfare reimbursement guidelines prioritize conservative intervention protocols that expand non-surgical patient pools. PMDA medical device review timelines for joint prostheses run longer than FDA equivalents, filtering market entry to established manufacturers. Tokyo and Osaka metropolitan areas concentrate specialist orofacial pain clinics with integrated physical therapy capabilities.
India
Cost-competitive API manufacturing for NSAIDs and muscle relaxants supplies domestic and export markets from Gujarat and Maharashtra production clusters. CDSCO medical device registration requirements are tightening for imported joint prostheses while streamlining pathways for domestic manufacturers. Sun Pharmaceutical and Zydus Cadila anchor generic formulation capacity that sustains pricing pressure across emerging markets.
Brazil
ANVISA medical device regulations for temporomandibular joint implants require in-country clinical evidence that extends market entry timelines for foreign manufacturers. São Paulo and Rio de Janeiro concentrate private dental clinic networks that drive demand for orthotic and pharmaceutical interventions. The national health system SUS coverage limitations restrict surgical eligibility to tertiary referral centers.
TMJ Disorders Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue minimally invasive device niches and digital diagnostic platforms. The vendor base stratifies across pharmaceutical incumbents with chronic pain portfolios, orthopedic device specialists with craniomaxillofacial expertise, and generic manufacturers competing on cost. Three archetypes dominate: diversified pharma conglomerates, precision orthopedic device houses, and emerging-market API suppliers. Competitive moves concentrate on portfolio diversification into adjacent orofacial pain indications and geographic expansion through distributor partnerships in underserved regions.
Among diversified pharmaceutical incumbents, Bristol-Myers Squibb and Novartis occupy positions anchored by immunology and pain therapeutic pipelines. Zimmer Biomet represents the orthopedic device archetype with craniomaxillofacial specialization. Sun Pharmaceutical Industries Ltd exemplifies the emerging-market generic manufacturer model with cost-competitive API and formulation capacity.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Allergan |
| Sun Pharmaceutical Industries Ltd |
| Novartis |
| Zydus Cadila |
| Abbott Laboratories |
| Bayer |
| Zimmer Biomet |
| Teva Pharmaceutical Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive titanium alloy sourcing from aerospace-grade metal suppliers anchors both supply security and premium pricing power for joint prosthesis manufacturers navigating FDA 510(k) scrutiny. This upstream control over implant-grade materials insulates established orthopedic device houses from raw material volatility while compressing margins for generic pharmaceutical competitors in price-sensitive emerging markets.
Pricing Analysis
Distributor margins on custom-fitted occlusal splints absorb 25-40% of end-user pricing, with dental laboratories in Germany and the United States capturing premium positioning through digital scanning workflows. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared joint prostheses from CE-marked alternatives and unbranded generics. Cost compression in the medication segment is intensifying because Indian API manufacturers are expanding export capacity. Retail pharmacy chains in the United States demonstrate highest price sensitivity, while academic medical centers retain lowest sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
Direct-to-specialist channels handle high-complexity arthroplasty demand, with manufacturer sales forces maintaining implant inventory at orofacial pain centers and university hospitals. Aerospace-grade titanium alloy supply concentrates in the United States, Germany, and Japan, with joint prosthesis production drawing from these precision metalworking clusters. Pharmaceutical APIs for NSAIDs and muscle relaxants source from Gujarat and Maharashtra production hubs in India. Single-source vulnerability in titanium sponge processing creates supply chain risk for implant manufacturers. Distribution runs through orthopedic device distributors with consignment inventory models at major surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the TMJ disorders market rests on the shift toward premium custom-fitted orthoses and point-of-care diagnostic platforms that command pricing power above commoditized pharmaceutical alternatives.
For Market Incumbents: Acquire digital diagnostic platform capabilities to defend against emerging entrants with chairside ultrasound and jaw tracking systems. Incumbent orthopedic device houses should deepen backward integration into titanium alloy processing to secure supply continuity amid aerospace demand competition. Certification investment in EMA MDR compliance creates differentiation against manufacturers facing extended European clinical evidence timelines. For New Entrants and Emerging Players: Capture white-space opportunity in portable point-of-care devices for general dentistry practices seeking to retain TMJ referrals without specialist handoffs. The most penetrable segment lies in rural United States counties where HIPAA-compliant telehealth platforms extend orofacial pain specialist reach without physical clinic infrastructure. A direct-to-clinic sales model bypassing traditional distributor markups enables competitive positioning against established implant houses. For Investors and Strategic Acquirers: Roll-up economics work for precision dental laboratory networks because fragmented custom occlusal splint fabrication lacks national scale players with digital workflow integration. Long-term viability centers on consolidation of chairside diagnostic and fabrication capabilities into integrated service platforms. The signal to watch is payer coding changes that expand reimbursement for conservative intervention protocols over surgical alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Clearance pathways for temporomandibular joint implants are tightening scrutiny and extending timelines. |
| CE Marking Pathway Under MDR | European clinical evidence requirements elevate post-market surveillance obligations for manufacturers. |
| Hospital System Partnership | Academic medical center clustering around research universities creates concentrated high-value referral networks. |
| Software Companion Development | Digital diagnostic platforms and telehealth consultations reshape patient triage across care boundaries. |
| Reimbursement Strategy | Medicare and private payer coding alignment determines portfolio investment prioritization for covered pathways. |
Study Parameters
Multiple input streams — structured interviews with orofacial pain specialists, regulatory affairs leads at orthopedic device manufacturers, hospital purchasing committee members, and GPO contracts managers — were reconciled against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement data, and hospital procurement records. Secondary validation drew from clinical literature on temporomandibular joint prosthesis outcomes and pharmaceutical API trade flows. Bottom-up patient volume modeling and top-down market sizing triangulation ensured cross-verification of segment estimates.
Historical surgical volume trends were cross-referenced against panel input from orofacial pain clinic administrators to project procedure trajectories across the analysis window. The analytical framework modeled segmentation across treatment method, product type, end-user setting, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating payer protocol shifts and diagnostic imaging penetration rates. Forecast inputs included MRI diagnostic capacity expansion at academic medical centers and generic API manufacturing capacity buildout in India.
Regulatory timeline delays, titanium alloy supply disruptions, and payer coding restrictions are the dominant revision risks that could compress surgical volume projections or accelerate non-surgical substitution. Forecasts reflect assumptions about conservative protocol adherence rates and telehealth reimbursement permanence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Global Thyroid Disorder Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Mucinoses Management Market