
 Diabetic Neuropathy Market | 2026-2036
Diabetic Neuropathy Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Neuropathy Market Intelligence
The EU Green Deal's pharmaceutical sustainability criteria is shifting procurement standards across European hospital networks, forcing reformulation priorities for chronic disease therapies. Pfizer leverages its manufacturing scale to supply broad-spectrum neuropathic pain portfolios across multiple continents. Eli Lilly and Company anchors its position through sustained R&D intensity in biologic pain modulation. Glenmark Pharmaceuticals competes aggressively in emerging markets with cost-optimized generic anticonvulsant offerings.
Diabetic neuropathy constitutes progressive peripheral nerve damage resulting from sustained hyperglycemia, characterized by demyelination, axonal degeneration, and altered nerve conduction velocities typically measured below 40 m/s in affected sensory fibers. The condition serves as the leading cause of non-traumatic lower limb amputation and drives substantial demand for chronic pain management interventions across healthcare systems. Anticonvulsants dominate current prescribing patterns due to established efficacy in voltage-gated calcium channel modulation, while topical treatments represent the fastest-expanding category as clinicians prioritize localized delivery to minimize systemic adverse effects. Hospital pharmacies capture the largest margin pools through centralized procurement of high-volume opioid and antidepressant therapies for inpatient neuropathic pain protocols.
The FDA maintains stringent efficacy benchmarks for novel diabetic neuropathy analgesics through its Division of Anesthesiology, Addiction Medicine, and Pain Medicine, while the EMA's Committee for Medicinal Products for Human Use enforces centralized neuropharmacological safety assessments across EU member states. Japan's PMDA imposes additional ethnic bridging study requirements that extend development timelines for multinational sponsors seeking simultaneous approval. Stakeholders must monitor evolving opioid prescribing restrictions and parallel non-opioid reimbursement expansions to align portfolio investments with shifting regulatory risk profiles.
Market Dynamics
FDA's accelerated approval pathways for novel analgesics are compressing competitive entry timelines while forcing incumbents to defend positioning through faster cycle times and expanded label claims.
Growth Catalysts
- EU Green Deal pharmaceutical sustainability criteria:Procurement standards across European hospital networks now mandate reformulation priorities, creating pull for biodegradable excipients and reduced-carbon manufacturing processes in chronic disease therapies.
- Aging diabetic populations in Japan, Germany, and the United States:Sustained therapeutic uptake concentrates in these three markets where reimbursement clarity supports long-term prescription adherence and specialty pharmacy penetration.
- Voltage-gated calcium channel modulation:Anticonvulsants maintain established efficacy profiles that clinicians trust for first-line neuropathic pain management, preserving volume through familiarity and formulary security.
Market Restraints
- Opioid prescribing restrictions:DEA quota reductions and state-level prescription drug monitoring programs constrain hospital pharmacy procurement flexibility for inpatient neuropathic pain protocols.
- Ethnic bridging study requirements:Japan's PMDA imposes additional clinical trial obligations that extend development timelines for multinational sponsors seeking simultaneous approval across regulatory jurisdictions.
- Topical formulation manufacturing complexity:Localized delivery systems require specialized equipment and excipient sourcing that limits supplier base concentration to North American and Western European contract manufacturers.
Strategic Opportunities
- Centralized neuropharmacological safety assessments:EMA's Committee for Medicinal Products for Human Use creates harmonized approval pathways that reduce redundant country-by-country filings for sponsors targeting EU member states.
- Biologic pain modulation convergence:Eli Lilly's sustained R&D intensity signals viable white space for monoclonal antibody and peptide-based mechanisms targeting nerve growth factor pathways.
- Emerging market generic substitution:Glenmark Pharmaceuticals demonstrates cost-optimized anticonvulsant positioning can capture volume in markets where price sensitivity exceeds brand loyalty.
Industry Challenges
- Specialized pain management protocol staffing:Hospital systems expanding dedicated diabetic neuropathy programs face scarcity of board-certified pain medicine physicians and advanced practice providers.
- Legacy EHR integration with novel diagnostic algorithms:Nerve conduction velocity tracking below 40 m/s requires workflow reconfiguration that conflicts with existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Neuropathy Market |
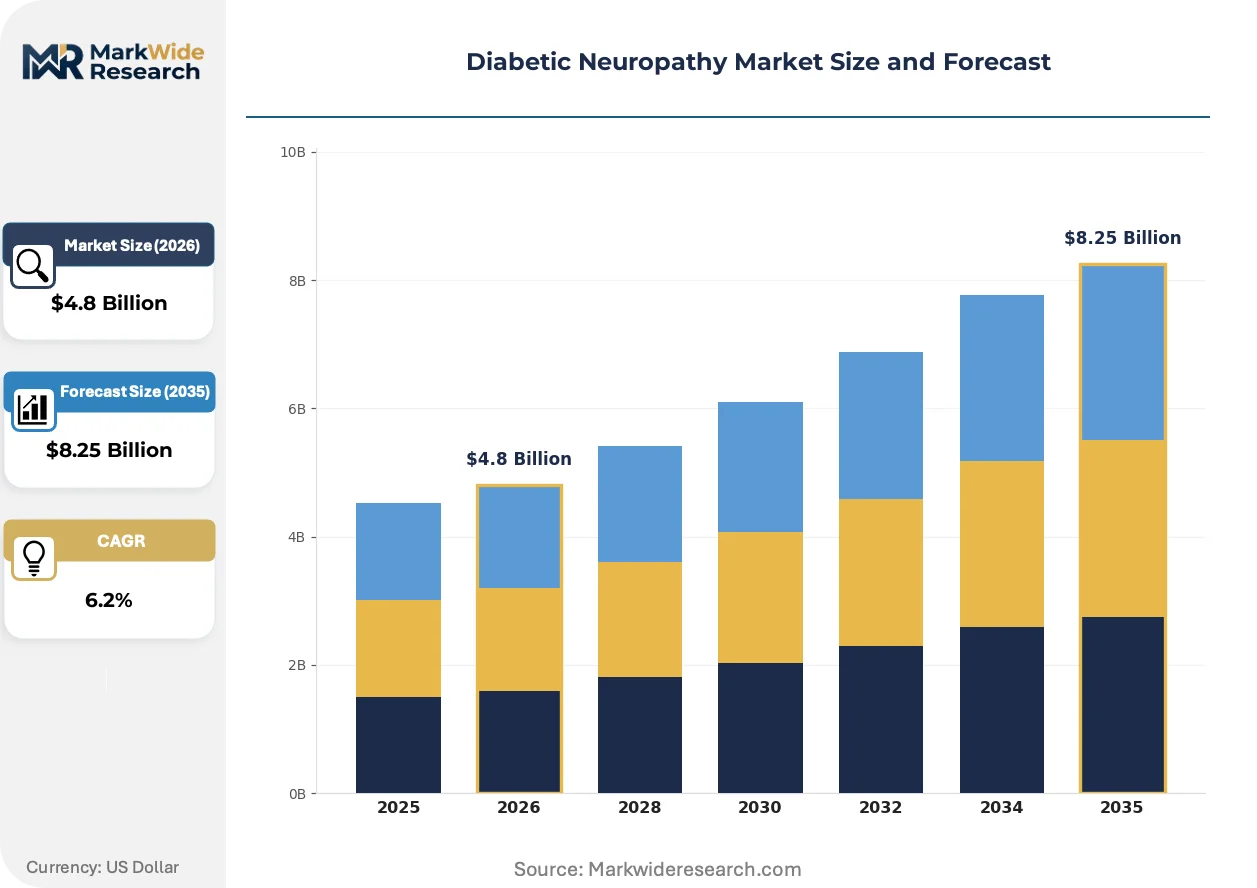
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Anticonvulsants, Topical Treatments, Opioids End User: Hospitals, Clinics, Home Care, Specialty Centers Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Drug Stores Treatment Method: Medication, Physical Therapy, Electrical Stimulation, Alternative Therapies |
| Companies Covered | Abbott, Eli Lilly and Company, Pfizer, Janssen Pharmaceuticals, Lupin, Astellas Pharma, Glenmark Pharmaceuticals, Boehringer Ingelheim, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Neuropathy Market Strategic Shifts & Innovations
Peripheral nerve damage biomarker identification and localized drug delivery engineering are compressing the gap between diagnostic confirmation and therapeutic intervention in progressive diabetic neuropathy management.
Transdermal iontophoresis systems are converging with sustained-release lidocaine formulations to enable patient-controlled dosing without systemic absorption risks. Pain management clinics in the United States are piloting these combinations for ambulatory patients who have failed oral anticonvulsant therapy. The technology is converging with existing reimbursement codes for durable medical equipment, creating viable economic models for home-based administration.
EMA's Medical Device Regulation (MDR) reclassification of active implantable pain stimulators has extended conformity assessment timelines for spinal cord stimulation devices used in refractory diabetic neuropathy. Manufacturers must now engage with notified bodies for clinical evaluation reports that were previously self-certified. German hospital procurement consortia are responding by consolidating purchasing power to offset extended supplier qualification periods.
Hospital pharmacy buyers are unbundling after-sales clinical support from device and drug procurement contracts, forcing manufacturers to compete on product performance metrics alone. This behavioral shift concentrates margin pressure on vendors who previously captured value through bundled education and training services. The pattern is most visible in United States academic medical centers where centralized value analysis committees now mandate line-item cost transparency.
Diabetic Neuropathy Market Segmentation
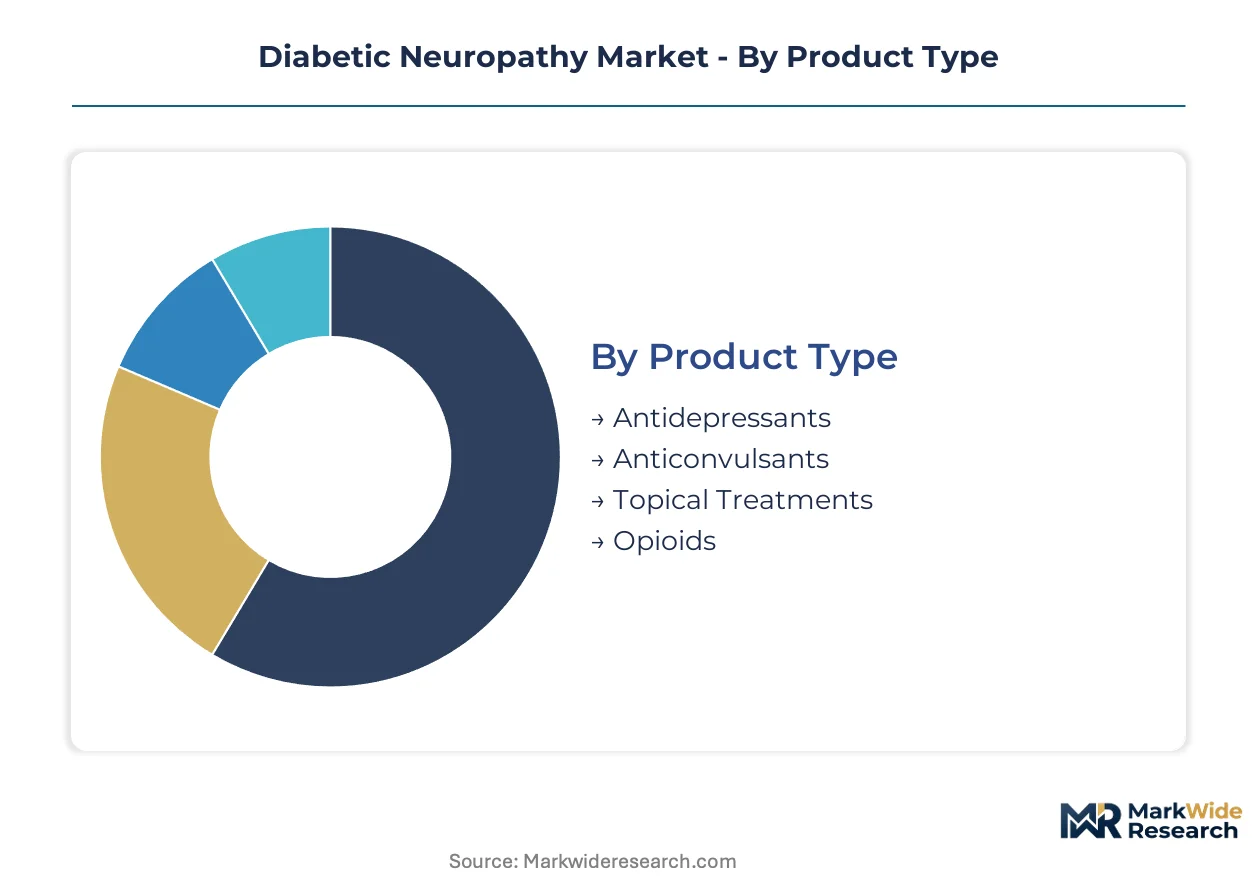
Segmentation in diabetic neuropathy therapeutics reveals distinct regulatory pathways and reimbursement dynamics across product categories. Each segment carries unique approval burdens from the FDA, EMA, and PMDA that shape competitive entry strategies and portfolio prioritization decisions.
Product Type:
FDA's Division of Anesthesiology, Addiction Medicine, and Pain Medicine applies divergent efficacy benchmarks across these therapeutic classes, with controlled substance scheduling creating additional DEA compliance layers for specific segments.
- Anticonvulsants:Voltage-gated calcium channel modulators including pregabalin and gabapentin dominate hospital formularies through established nerve conduction velocity improvement data. Demand concentrates in United States academic medical centers where centralized value analysis committees prioritize generic substitution for chronic prescribing.
- Topical Treatments:Lidocaine patches and capsaicin formulations enable localized delivery with minimal systemic absorption, attracting clinicians managing polypharmacy in elderly diabetic populations. United States pain management clinics pilot transdermal iontophoresis combinations for ambulatory patients failing oral therapy.
- Antidepressants:Serotonin-norepinephrine reuptake inhibitors carry dual-label indications requiring cardiovascular safety monitoring.
- Opioids:DEA quota reductions and state prescription drug monitoring programs constrain procurement flexibility.
Leading the category by volume: Anticonvulsants. Growing fastest: Topical Treatments.
End User:
Procurement authority and reimbursement coding vary sharply across these settings, with hospital pharmacy centralized purchasing commanding the largest margin pools.
- Hospitals:Inpatient neuropathic pain protocols rely on high-volume opioid and antidepressant procurement through centralized pharmacy operations. German hospital procurement consortia consolidate purchasing power to offset extended supplier qualification periods under EMA MDR requirements.
- Specialty Centers:Dedicated pain management clinics in the United States pilot novel device-drug combinations including spinal cord stimulation with sustained-release formulations. Reimbursement codes for durable medical equipment create viable economic models for technology adoption.
- Clinics:Outpatient settings face staffing scarcity for board-certified pain medicine physicians.
- Home Care:Patient-controlled dosing systems require integration with existing durable medical equipment reimbursement pathways.
Dominating procurement volume: Hospitals. Expanding most quickly: Specialty Centers.
Distribution Channel:
Channel selection determines formulary access speed and clinical support bundling possibilities, with hospital pharmacies capturing centralized contract advantages.
- Hospital Pharmacies:Centralized procurement of high-volume therapies for inpatient protocols creates the largest margin concentration. United States academic medical centers now mandate line-item cost transparency, unbundling after-sales clinical support from device and drug contracts.
- Online Pharmacies:Specialty pharmacy penetration in Japan and Germany supports long-term prescription adherence for chronic therapies. Digital platforms enable direct patient engagement for topical treatment refills with minimal systemic adverse effect counseling.
- Retail Pharmacies:Community access points face formulary tier placement competition.
- Drug Stores:Convenience-focused locations prioritize over-the-counter topical offerings.
Commanding procurement volume: Hospital Pharmacies. Gaining share fastest: Online Pharmacies.
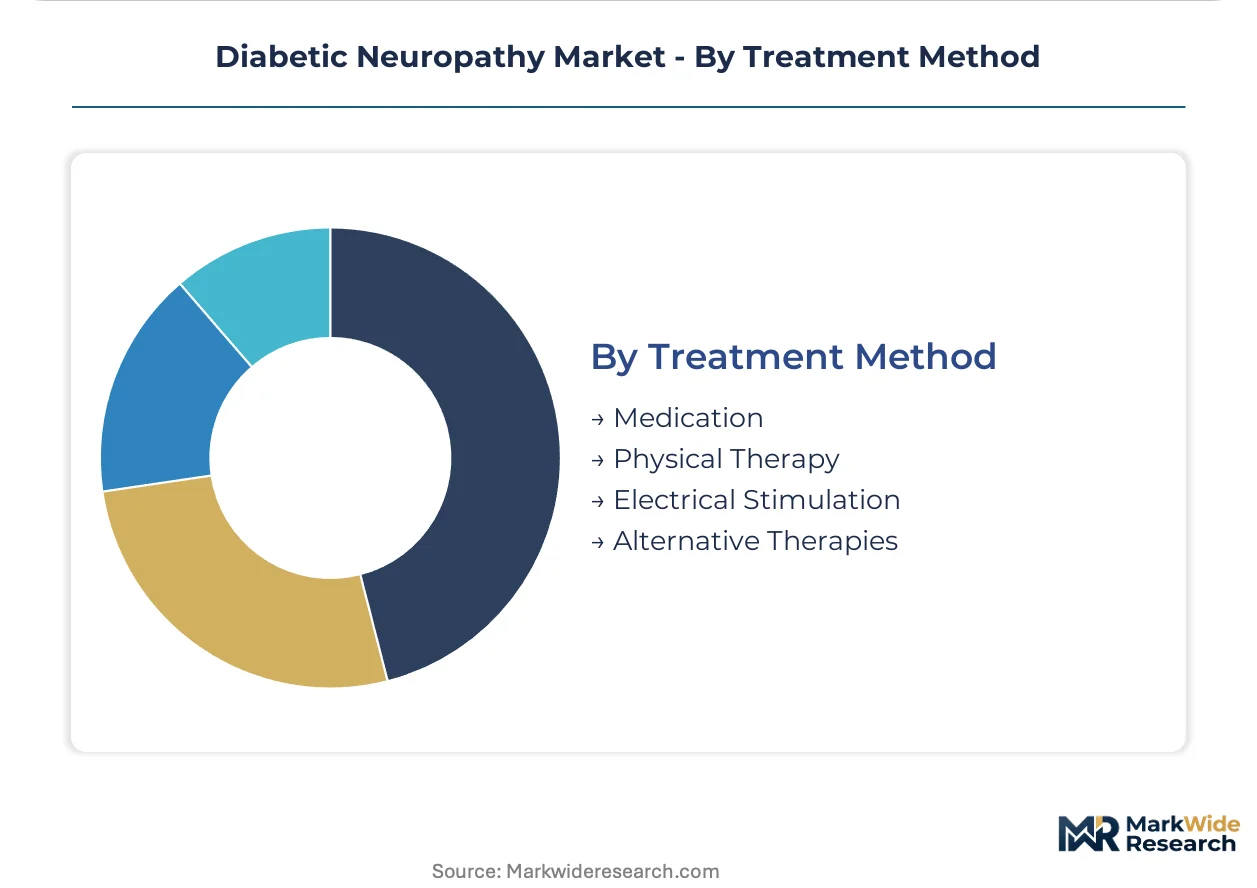
Treatment Method:
Reimbursement clarity and evidence requirements from CMS and national health technology assessment bodies determine adoption velocity across modalities.
- Medication:Pharmaceutical interventions maintain established efficacy documentation through randomized controlled trials in voltage-gated calcium channel modulation. Anticonvulsant prescribing patterns persist through clinician familiarity and formulary security.
- Electrical Stimulation:Spinal cord stimulation devices for refractory diabetic neuropathy face extended EMA MDR conformity assessment timelines. German hospital procurement consortia respond by consolidating purchasing power to offset supplier qualification delays.
- Physical Therapy:Reimbursement coding varies across United States Medicare regional contractors.
- Alternative Therapies:Evidence requirements from health technology assessment bodies limit formal adoption.
Holding largest patient volume: Medication. Steepest expansion trajectory: Electrical Stimulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors North American demand for diabetic neuropathy therapeutics, with Massachusetts General Hospital and Brigham and Women's Hospital driving protocol standardization across the United States hospital network.
United States
Academic medical centers in Massachusetts and California concentrate prescribing volume for anticonvulsant therapies through centralized value analysis committees. The FDA's Division of Anesthesiology, Addiction Medicine, and Pain Medicine maintains stringent efficacy benchmarks for novel analgesics entering this market. Philadelphia's hospital procurement consortia unbundle after-sales clinical support from device contracts, forcing manufacturers to compete on product performance metrics alone.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia expand dedicated pain management protocols for diabetic neuropathy patients, capturing the largest margin pools through centralized pharmacy operations. The EU Green Deal's pharmaceutical sustainability criteria mandates reformulation priorities for biodegradable excipients across European hospital networks. Frankfurt's procurement consortia consolidate purchasing power to offset extended supplier qualification periods under EMA MDR requirements.
Japan
Aging diabetic populations in Tokyo and Osaka sustain therapeutic uptake where reimbursement clarity supports long-term prescription adherence through specialty pharmacy penetration. The PMDA imposes additional ethnic bridging study requirements that extend development timelines for multinational sponsors seeking simultaneous approval. Nagoya's pain management clinics pilot transdermal iontophoresis combinations for ambulatory patients who have failed oral anticonvulsant therapy.
United Kingdom
Hospital pharmacies in London and the Southeast capture centralized contract advantages for high-volume opioid and antidepressant therapies used in inpatient neuropathic pain protocols. The EMA's Committee for Medicinal Products for Human Use enforces centralized neuropharmacological safety assessments that reduce redundant country-by-country filings. Manchester's National Health Service trusts prioritize localized delivery systems to minimize systemic adverse effects in elderly diabetic populations.
India
Cost-optimized generic anticonvulsant positioning captures volume in Maharashtra and Gujarat where price sensitivity exceeds brand loyalty in outpatient settings. The CDSCO aligns with international regulatory standards while maintaining accelerated pathways for chronic disease therapies. Hyderabad's pharmaceutical manufacturing corridor supplies broad-spectrum neuropathic pain portfolios across emerging markets with reformulation capabilities for reduced-carbon production processes.
Diabetic Neuropathy Market Key Industry Players
Premium-margin players sit above commodity-margin players across the innovation-manufacturing spectrum, with biologic developers commanding valuation multiples that generic manufacturers cannot replicate. The vendor base concentrates around three strategic tiers: multinational pharmaceutical conglomerates with integrated pain portfolios, mid-cap specialists in voltage-gated calcium channel modulation, and emerging market generic houses competing on cost-optimized anticonvulsant production. Dominant competitive moves include portfolio diversification into localized delivery systems and strategic partnerships to secure biodegradable excipient supply chains under EU Green Deal procurement standards.
Within the multinational tier, Pfizer and Eli Lilly and Company occupy positions that exemplify divergent strategic archetypes—manufacturing scale leverage versus sustained R&D intensity in biologic pain modulation. Glenmark Pharmaceuticals represents the emerging market generic substitution model, demonstrating how cost-optimized positioning captures volume where price sensitivity exceeds brand loyalty. These three anchors collectively illustrate the competitive tension between premium innovation cycles and accessible therapeutic penetration across divergent geographic markets.
| Leading Market Players |
|---|
| Abbott |
| Eli Lilly and Company |
| Pfizer |
| Janssen Pharmaceuticals |
| Lupin |
| Astellas Pharma |
| Glenmark Pharmaceuticals |
| Boehringer Ingelheim |
| Novartis |
| Others |
Cost & Logistics Intelligence
Board-certified pain medicine physicians and advanced practice providers cluster in Massachusetts and California academic medical centers, creating labor-cost differentials that spread pricing tiers across premium academic protocols and economy outpatient settings.
Pricing Analysis
Value-based pricing anchored to nerve conduction velocity improvement outcomes dominates United States hospital formularies, with three-tier pricing structure across premium biologic modulation, standard anticonvulsant, and economy generic gabapentin levels. Price differentiation stems from FDA breakthrough therapy designation tier and after-sales clinical support bundling. Cost compression in the generic anticonvulsant tier is intensifying because of centralized value analysis committee mandates for line-item transparency. Outpatient clinics in India and Maharashtra exhibit highest price sensitivity; German hospital procurement consortia demonstrate lowest sensitivity due to consolidated purchasing power.
Supply Chain Analysis
EMA MDR conformity assessment and FDA DEA controlled substance scheduling create dual certification gating that segments supplier qualification timelines. Active pharmaceutical ingredient manufacturing concentrates in India, China, and the United States. Specialized excipient sourcing for biodegradable formulations and transdermal iontophoresis equipment draws from Western European and North American contract manufacturers. Single-source vulnerability runs through lidocaine patch polymer substrate suppliers. Distribution runs through hospital pharmacy centralized procurement with unbundled clinical support contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive supply of biodegradable excipients to satisfy EU Green Deal procurement standards.
For Market Incumbents: Cement formulary security through backward integration into specialized excipient production and expanded label claims for voltage-gated calcium channel modulators. Emerging market generic houses like Glenmark Pharmaceuticals threaten volume in price-sensitive geographies; counter through certification investment for EMA centralized neuropharmacological safety assessments. For New Entrants and Emerging Players: Begin with transdermal iontophoresis combinations for ambulatory patients failing oral anticonvulsant therapy in United States pain management clinics. The specialty center segment offers lowest competitive density and clearest reimbursement coding through durable medical equipment pathways. Pursue hospital system partnerships that unbundle device procurement from clinical training services. For Investors and Strategic Acquirers: Re-rating potential sits with biologic pain modulation developers given Eli Lilly's sustained R&D intensity signaling viable nerve growth factor pathway commercialization. Long-term viability favors sponsors with simultaneous FDA-EMA-PMDA filing strategies that compress approval timelines. Watch for ethnic bridging study requirement harmonization between Japan's PMDA and other regulators as inflection indicator for multinational portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Excipient Supply Chain Integration | EU Green Deal procurement standards mandate reformulation priorities across European hospital networks. |
| Transdermal Iontophoresis System Development | United States pain management clinics pilot patient-controlled dosing for failed oral therapy cases. |
| EMA Centralized Neuropharmacological Assessment | Harmonized approval pathways reduce redundant country-by-country filings for EU member state entry. |
| Specialty Center Channel Partnership | Reimbursement codes for durable medical equipment create viable economic models for technology adoption. |
| Ethnic Bridging Study Optimization | Japan's PMDA requirements extend timelines; simultaneous filing strategies compress competitive entry. |
Research Approach
Multi-period observation of nerve conduction velocity biomarker adoption, anticonvulsant prescribing patterns, and topical treatment penetration anchored the trend analysis, supplemented by interviews with drug development executives at multinational pharmaceutical conglomerates, regulatory affairs leads navigating FDA Division of Anesthesiology pathways, formulary directors at United States academic medical centers, hospital procurement managers in German procurement consortia, and payer access specialists in Japanese specialty pharmacy networks. Secondary validation drew from FDA filings, EMA centralized assessment reports, ClinicalTrials.gov entries for diabetic neuropathy interventions, hospital procurement databases, and CMS Medicare reimbursement coding updates. Bottom-up patient-volume modeling and top-down therapeutic-class revenue triangulation cross-checked segment outputs.
Input-output matrices mapped voltage-gated calcium channel modulation efficacy data, topical formulation manufacturing capacity, and electrical stimulation device approval timelines across the projection horizon. Segmentation dimensions modeled include product type, end user setting, distribution channel, treatment modality, and regional regulatory cluster. CAGRs derived from patient population growth, pricing trajectory assumptions, and therapy switching rates between oral and localized delivery systems. Forecast inputs incorporated PMDA ethnic bridging study completion rates and EU Green Deal procurement standard adoption curves.
Regulatory pathway delays, opioid prescribing restriction intensification, and biodegradable excipient supply shortages are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding reimbursement clarity maintenance in Japan, Germany, and the United States. A model refresh is warranted upon material change in EMA MDR conformity assessment timelines for active implantable pain stimulators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Pediatric Neurology Device Market
Neurology
Neurology Services Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Hydrocephalus Market
Neurology
Spasticity Treatment Market
Neurology
India Neurology Devices Market
Neurology
Vocal Cord Paralysis Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
White Matter Injury Treatment Market
Neurology
Mild Traumatic Brain Injury Treatment Market