
 Excavator Augers Market | 2026-2036
Excavator Augers Market Size, Share, and Industry Trends Forecast 2026-2036
Excavator Augers Market Analytics
Buyer concentration among construction companies is hardening as mid-tier contractors merge to qualify for larger municipal contracts. Caterpillar leverages its dealer network to dominate fleet sales for foundation drilling applications. Komatsu sustains competitive pressure through integrated hydraulic system design that matches auger torque to excavator class.
Excavator augers are cylindrical boring attachments with helical flighting welded to a central drive shaft, typically powered by planetary gearboxes delivering torque from 1,500 to 150,000 Nm depending on carrier size and soil condition. Their primary purpose is vertical or angled earth penetration for pilings, poles, posts, and utility conduits without dedicated drilling rigs. Single flight augers lead in landscaping and agricultural tilling where clean spoil removal matters, while double flight designs anchor margin pools in foundation drilling by reducing pullback resistance in cohesive soils. Extra large augers represent the fastest-growing size category as wind farm developers specify deeper anchor foundations.
OSHA Subpart P excavation standards and EPA Clean Water Act stormwater provisions shape equipment specifications by mandating shoring-compatible drilling methods and spill containment. ISO 13031 earth-moving machinery safety standards govern guarding and emergency stop requirements for hydraulic attachments. Stakeholders must monitor how state-level Buy America provisions affect sourcing of alloy steel flighting and gearbox housings.
Market Dynamics
Federal infrastructure appropriations in the United States are compressing project timelines, forcing contractors to prioritize attachment interchangeability and rapid mobilization over dedicated drilling rigs.
Growth Catalysts
- EPA Stormwater Regulations:Municipal trenchless installation mandates in the United States require shoring-compatible auger systems for utility burial, expanding specification requirements across public procurement.
- Fiber Optic Deployment:Broadband burial programs funded by federal infrastructure legislation are accelerating demand for compact auger attachments suited to narrow right-of-way constraints.
- Wind Farm Anchoring:Extra large auger specifications for deeper turbine foundations are displacing traditional piling methods in renewable energy construction across the Great Plains.
Market Restraints
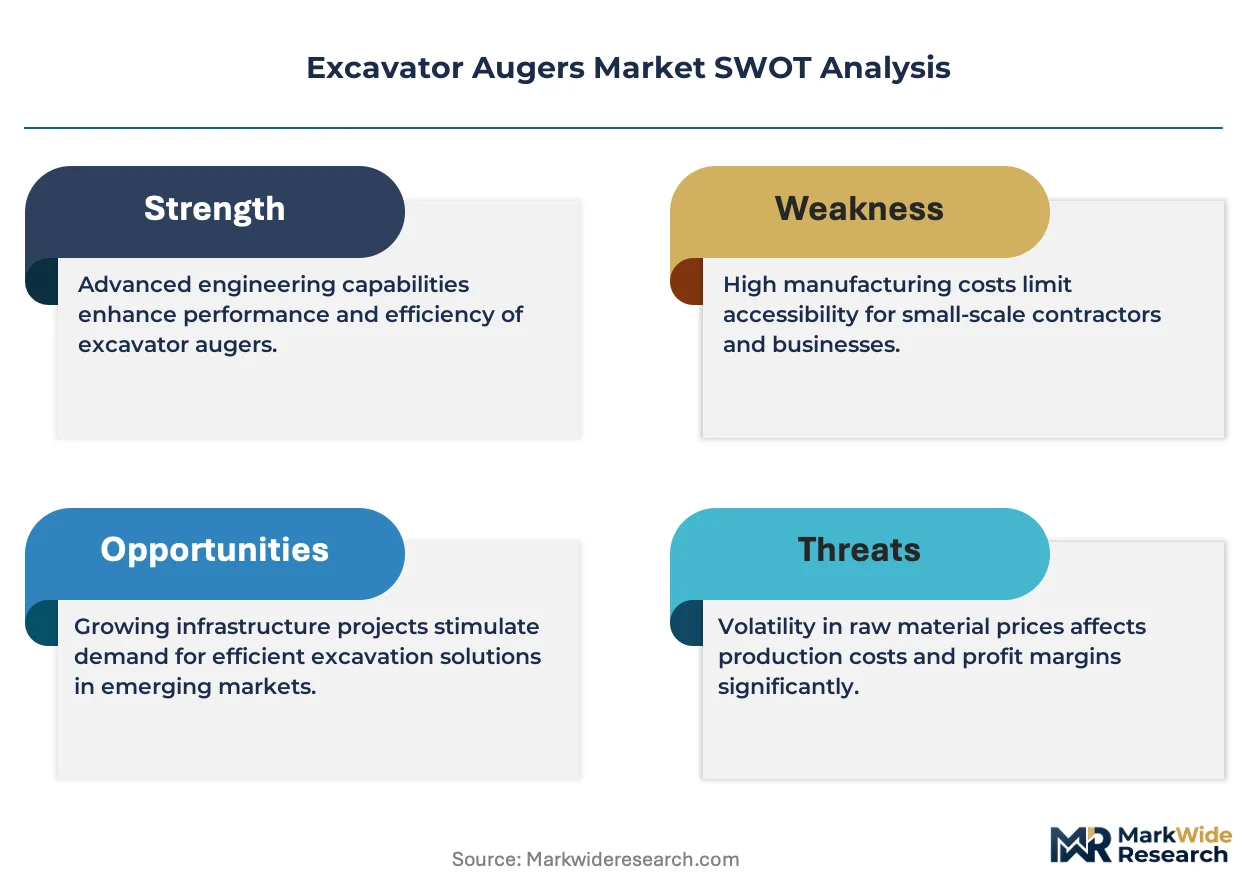
- Alloy Steel Volatility:Flighting material costs fluctuate with scrap metal indices, compressing margin pools for attachment fabricators without long-term supply agreements.
- Regional Supply Concentration:Planetary gearbox manufacturing clusters in Germany and Japan create lead time exposure for North American assemblers during ocean freight disruptions.
- Hydraulic Matching Constraints:Excavator class compatibility limits prevent universal attachment deployment, forcing fleet-specific inventory duplication among rental houses.
Strategic Opportunities
- Canadian Municipal Expansion:Provincial water main replacement schedules in Ontario and Alberta are opening specification windows for auger systems meeting CSA earth-moving standards.
- Telescoping Drive Shaft Convergence:Integration of variable-length auger shafts with GPS-guided excavator controls enables single-setup multi-depth drilling for solar farm pile arrays.
- OSHA Subpart P Alignment:Safety-compliant auger designs that eliminate manual spoil handling qualify for preferential bidding on federally funded excavation contracts.
Industry Challenges
- Planetary Gearbox Technician Scarcity:Specialized hydraulic diagnostics expertise required for field repairs outpaces vocational training program output in rural construction markets.
- ISO 13031 Certification Timelines:Emergency stop and guarding compliance testing delays product launches by 8-14 months for attachment manufacturers seeking CE marking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excavator Augers Market |
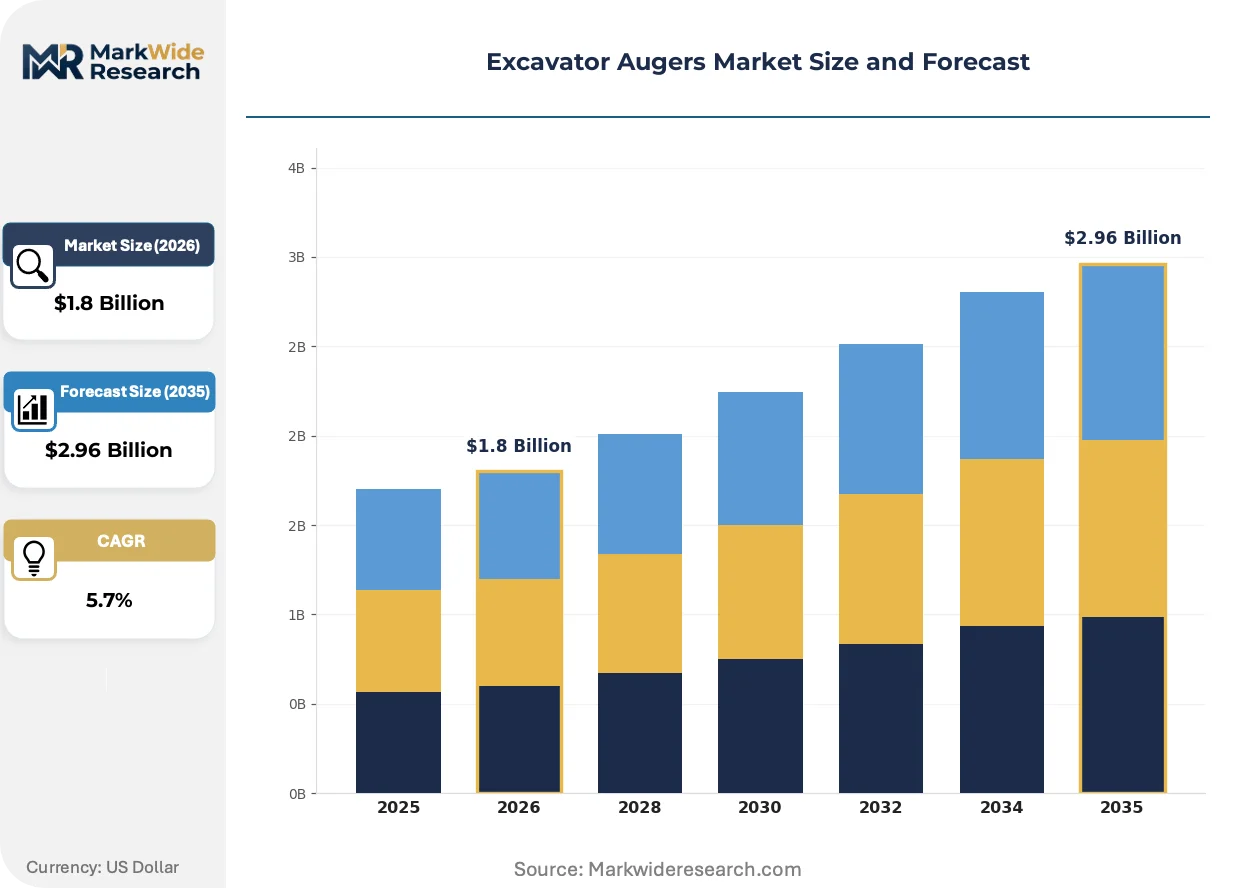
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Flight, Double Flight, Triple Flight, Specialty Augers Application: Foundation Drilling, Landscaping, Agricultural Tilling, Utility Installation End User: Construction Companies, Landscaping Firms, Agricultural Operators, Municipalities Size: Small, Medium, Large, Extra Large |
| Companies Covered | Caterpillar, John Deere, Komatsu, Bobcat Doosan Company, JCB, Digga, Auger Torque, Palfinger, Epiroc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excavator Augers Market Evolving Landscape
Attachment intelligence and soil-condition responsiveness are redefining competitive differentiation, shifting value capture from hardware durability toward operational data integration and predictive maintenance capabilities.
Variable-displacement hydraulic motors paired with torque-feedback sensors are consolidating control precision across heterogeneous soil profiles. Foundation contractors in the United States are retrofitting mid-size excavator fleets with these systems to reduce operator-dependent depth variance. The technology is consolidating specification authority among integrated system providers capable of calibrating motor response to real-time geological data.
OSHA excavation safety standards are tightening shoring-method documentation requirements for utility burial projects. Equipment specifications now mandate compatibility with trench box installation sequences, forcing auger manufacturers to redesign spoil discharge geometry. Municipal contractors in Texas and California are prioritizing attachments certified for zero-entry excavation protocols.
Rental channel consolidation is compressing equipment procurement cycles for mid-tier construction firms. United Rentals and Sunbelt are unbundling after-sales service from daily rates, pushing attachment manufacturers to establish direct field technician networks. This pattern is most pronounced in the southeastern United States where hurricane recovery schedules demand 24-hour mobilization guarantees.
Excavator Augers Market Segmentation
Excavator auger specifications diverge sharply across soil conditions, carrier compatibility, and spoil-handling requirements. Attachment geometry and flighting configuration determine torque transmission efficiency and project economics across distinct construction verticals.
Product Type:
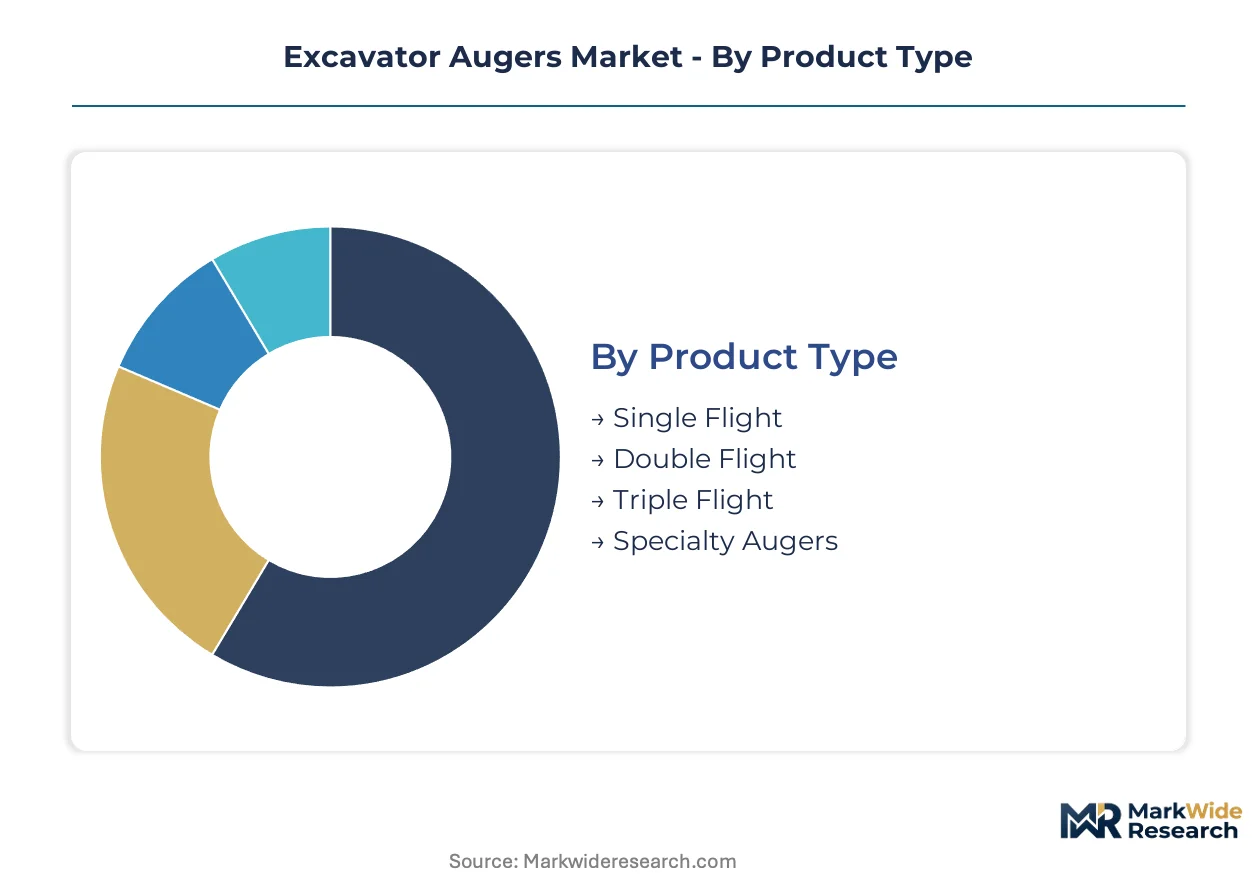
Helical flighting geometry governs spoil removal efficiency and pullback resistance in varying soil compositions.
- Single Flight:One continuous helical blade welded to the central drive shaft maximizes clean spoil evacuation in loose or sandy substrates. Landscaping contractors in the United States specify these for fence post and tree planting operations where minimal soil disturbance preserves turf integrity.
- Double Flight:Dual opposing helices balance cutting forces and reduce rotational resistance in cohesive clay soils. Foundation drilling contractors across Texas and the Great Plains deploy these for pier shaft applications where auger withdrawal torque limits equipment stress.
- Triple Flight:Triple-helix configurations distribute bearing loads across extended drilling depths in rock-embedded formations.
- Specialty Augers:Custom flighting geometries address frozen ground, coral substrates, or contaminated site conditions requiring sealed spoil containment.
Single flight leads on scale; double flight leads on momentum in foundation applications.
Application:
Project scale and soil penetration depth dictate attachment specification authority across construction disciplines.
- Foundation Drilling:High-torque planetary systems drive reinforced concrete pier shafts for commercial and residential structures. Wind farm developers in the United States specify extra-large double-flight configurations for turbine anchor foundations exceeding standard depth requirements.
- Utility Installation:Compact auger systems navigate narrow right-of-way constraints for fiber optic and water main burial. Federal broadband funding accelerates trenchless deployment across municipal contracts in California and Florida.
- Landscaping:Light-duty single-flight attachments prioritize turf preservation and rapid mobilization for residential contractors.
- Agricultural Tilling:Tractor-mounted auger variants address fence line and irrigation pivot installation in row-crop operations.
Foundation drilling commands specification authority; utility installation expands most quickly on infrastructure funding.
End User:
Procurement sophistication and fleet standardization separate volume buyers from specification influencers.
- Construction Companies:Tier-one contractors standardize across excavator classes to minimize attachment inventory duplication. Mid-tier mergers in the United States consolidate fleet purchasing power for municipal qualification.
- Municipalities:Public procurement mandates OSHA Subpart P compliance and Buy America sourcing for alloy steel components. Water main replacement schedules in Ontario and Alberta specify CSA-certified earth-moving attachments.
- Landscaping Firms:Rental channel dependence shapes procurement cycles for seasonal demand spikes.
- Agricultural Operators:Dealer network proximity drives attachment selection for seasonal fencing and irrigation projects.
Construction companies dominate volume procurement; municipalities drive compliance-driven specification evolution.
Size:
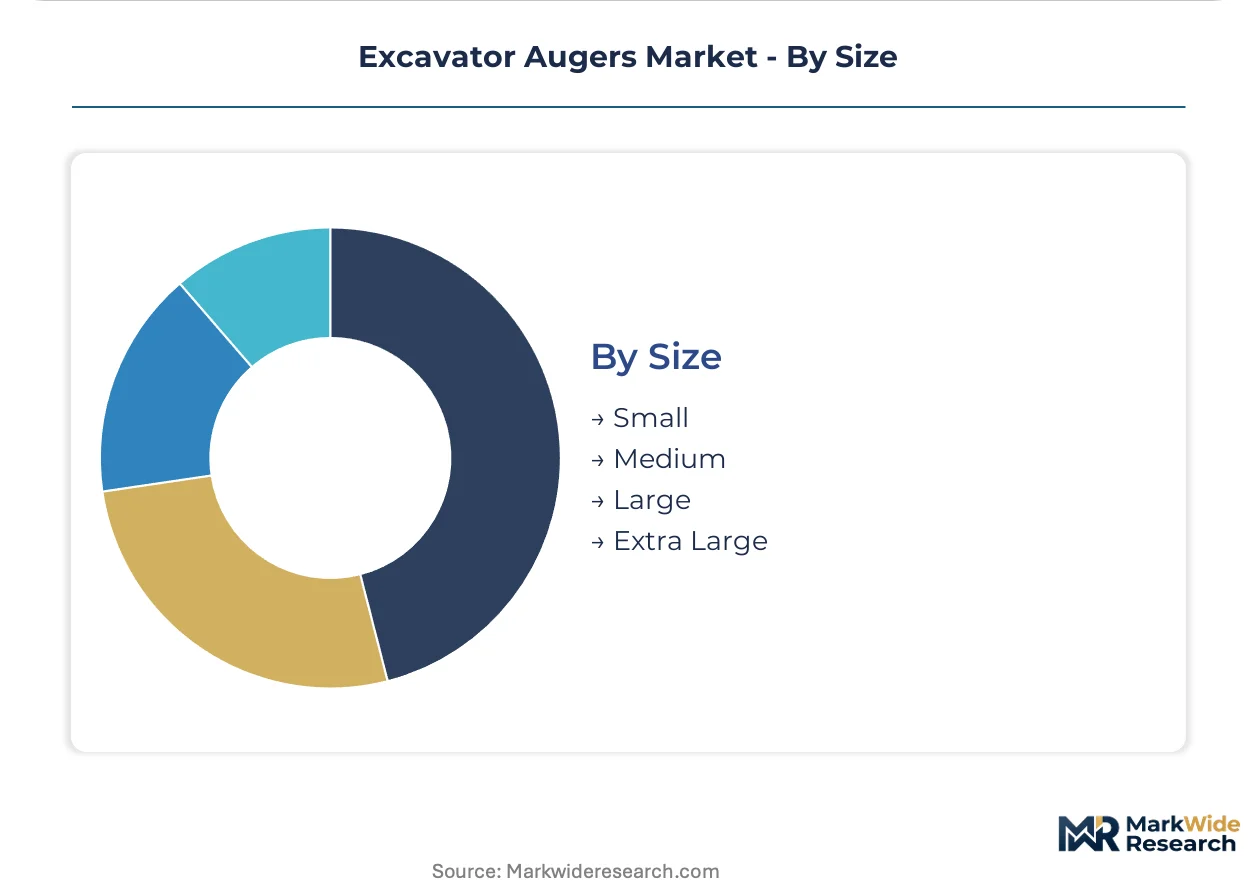
Excavator carrier class and torque output determine auger diameter compatibility across project scales.
- Extra Large:Diameters exceeding 48 inches deliver the torque and depth capacity for wind turbine anchor foundations. Renewable energy developers across the Great Plains displace traditional piling methods with these systems.
- Large:24-48 inch configurations anchor commercial foundation drilling and heavy utility transmission projects.
- Medium:12-24 inch diameters match mid-size excavator fleets for standard pier shaft and pole installation.
- Small:Sub-12 inch attachments serve compact excavators in residential landscaping and limited-access utility burial.
Medium sizes anchor fleet standardization; extra large configurations gain share fastest on renewable energy construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled hydraulic technicians cluster around excavator auger demand centers, concentrating maintenance expertise in construction-heavy jurisdictions with active infrastructure programs.
United States
Federal infrastructure appropriations compress project timelines for water main replacement and broadband burial across Texas and California. OSHA Subpart P excavation standards mandate shoring-compatible auger systems for municipal trenchless installation contracts. Houston and Dallas anchor specification authority for foundation drilling attachments serving wind farm developments across the Great Plains.
Canada
Provincial water main replacement schedules in Ontario and Alberta accelerate specification windows for earth-moving attachments. CSA earth-moving standards govern public procurement of alloy steel flighting and gearbox housings for municipal contracts. Calgary and Edmonton concentrate rental channel consolidation for mid-tier contractors qualifying for larger infrastructure awards.
Germany
Planetary gearbox manufacturing clusters supply precision torque transmission systems to North American assemblers. REACH chemical regulations and CE marking requirements shape alloy steel sourcing protocols for attachment fabricators. Stuttgart and Munich anchor engineering expertise for variable-displacement hydraulic motor integration with excavator controls.
Japan
Integrated hydraulic system design capabilities match auger torque output to excavator carrier classes for foundation drilling applications. METI industrial standards influence gearbox efficiency benchmarks exported to renewable energy construction markets. Osaka and Nagoya concentrate manufacturing of compact drive shaft assemblies for narrow right-of-way utility burial.
Australia
Mining sector rehabilitation programs generate demand for specialty auger configurations addressing rock-embedded formations and contaminated site containment. ISO 13031 earth-moving machinery safety standards govern guarding requirements for hydraulic attachments in remote construction zones. Perth anchors demand for extra-large diameter systems serving resource extraction infrastructure renewal.
Excavator Augers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across attachment specification tiers. The vendor base organizes around three strategic archetypes: integrated equipment manufacturers leveraging captive excavator fleets, independent attachment fabricators serving rental channels, and precision gearbox specialists supplying torque transmission subsystems. Competitive moves concentrate on dealer network expansion for fleet standardization and direct field technician deployment for 24-hour mobilization guarantees.
Within the integrated equipment tier, Caterpillar and Komatsu exemplify scale-driven positioning through hydraulic system integration and distribution network reach. Among independent specialists, Digga occupies a position representing rental channel-focused fabrication capabilities. These anchors illustrate how competitive differentiation concentrates on attachment interchangeability and rapid mobilization protocols rather than hardware durability alone.
| Leading Market Players |
|---|
| Caterpillar |
| John Deere |
| Komatsu |
| Bobcat Doosan Company |
| JCB |
| Digga |
| Auger Torque |
| Palfinger |
| Epiroc |
| Others |
Value Network & Pricing Analysis
Tier-one construction companies consolidating fleet purchasing power negotiate contract-based long-term offtake agreements that compress margin pools for attachment fabricators without integrated service networks. Rental channel consolidation across the southeastern United States unbundles after-sales support from daily rates, forcing manufacturers to absorb field technician deployment costs or cede specification authority to vertically integrated equipment OEMs.
Pricing Analysis
The bundled-versus-unbundled service split distinguishes competitive positioning across procurement channels. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Pricing pressure stems from alloy steel scrap metal index volatility compressing flighting material margins. Municipal contractors exhibit highest price sensitivity due to public procurement constraints, while wind farm developers prioritize torque precision over unit cost.
Supply Chain Analysis
Skilled planetary gearbox technicians concentrate in Stuttgart and Osaka manufacturing clusters, creating field repair bottlenecks for North American assemblers during ocean freight disruptions. Planetary gearbox manufacturing draws from Germany and Japan, with alloy steel flighting sourcing tethered to scrap metal markets. Single-source vulnerability in precision torque transmission components exposes assemblers to lead time compression. Distribution runs through consolidated rental houses and OEM dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The excavator augers market represents a late-cycle quality story as wind farm developers displace traditional piling methods with specification-grade extra-large configurations demanding integrated hydraulic system precision.
For Market Incumbents: Cement specification authority by deepening backward integration into planetary gearbox manufacturing and establishing captive field technician networks for 24-hour mobilization guarantees. Rental channel consolidation threatens margin pools for attachment-only fabricators; defend by locking multi-year fleet standardization contracts with merged mid-tier contractors qualifying for municipal infrastructure awards. For New Entrants and Emerging Players: Enter via narrow right-of-way utility burial segments where compact drive shaft assemblies face specification gaps against integrated hydraulic systems. Canadian provincial water main replacement schedules in Ontario and Alberta present penetrable procurement windows for CSA-certified attachments. Pursue direct municipal qualification bypassing rental channel gatekeepers. For Investors and Strategic Acquirers: Integrated equipment manufacturers are the most active acquirer in this space, targeting independent attachment fabricators with rental channel density and CSA certification pathways. Long-term viability hinges on renewable energy construction momentum and trenchless utility installation mandates. Monitor federal infrastructure appropriation continuity as primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gearbox Manufacturing | Captive torque transmission supply secures margin control against German and Japanese supplier concentration. |
| Direct Field Technician Network Deployment | 24-hour mobilization capability qualifies for hurricane recovery and municipal emergency repair contracts. |
| CSA Certification Investment | Canadian provincial procurement mandates require CSA earth-moving standards for water main replacement awards. |
| GPS-Guided Excavator Control Integration | Variable-length auger shaft convergence enables single-setup multi-depth drilling for solar farm pile arrays. |
| Zero-Entry Excavation Protocol Certification | OSHA Subpart P alignment qualifies for preferential bidding on federally funded trenchless installation contracts. |
Research Methodology
Bottom-up utility installation and foundation drilling modeling reconciled against top-down planetary gearbox manufacturing tracking forms the analytical core. Primary interviews with maintenance directors at construction firms, OEM procurement teams, aftermarket service heads, and municipal contract officers combined with secondary validation from EPA stormwater regulation filings, OSHA excavation standard updates, federal infrastructure appropriation documents, and customs alloy steel trade data.
Input-output matrices map excavator carrier class compatibility against torque output requirements across single-flight, double-flight, and extra-large configurations. Segmentation dimensions span product type, application vertical, end-user procurement sophistication, and size category. CAGRs derive from project pipeline analysis across renewable energy construction and broadband burial programs. Forecast inputs include municipal water main replacement schedules and wind farm development permits.
Inputs from federal infrastructure appropriation databases and provincial procurement registries were available through the study window; gaps in real-time alloy steel scrap pricing introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding regulatory continuity and skilled technician training program output. Material deviation in federal funding authorization or REACH chemical regulation scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rotary Dryers Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Cable Winches Market
Construction Equipment
Refurbished Construction Equipment Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Hydraulic Shearing Machine Market