
 Field Marking Equipment Market | 2026-2036
Field Marking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Field Marking Equipment Market Analytics
Autonomous navigation is narrowing the performance gap between robotic line markers and conventional ride-on sprayers across professional sports turf. Graco leverages its fluid handling engineering to sustain dominance in high-volume paint delivery systems for roadway contractors. Turf Tank anchors its position through GPS-guided robotic units that eliminate string-line setup time for athletic field crews.
Field marking equipment encompasses mechanical and robotic systems that deposit paint, thermoplastic, or temporary pigments onto turf, asphalt, or concrete surfaces at specified widths and thicknesses, typically 50-150 mm for athletic lines and 100-200 mm for parking stalls. The primary purpose is to create durable, visible demarcations that withstand weather, traffic, and maintenance equipment. Sprayers capture the largest margin pool due to recurring paint consumption and attachment sales to existing chassis fleets. Robotics represents the fastest-expanding segment as sports facilities and municipalities evaluate labor reduction against capital outlay. Rollers retain share in budget-conscious school districts where simple line refresh cycles suffice.
EPA volatile organic compound rules constrain solvent-based paint formulations in the United States, while REACH registration requirements govern chemical composition across European coatings. OSHA workplace exposure standards further influence equipment design for operator safety during spray application. Stakeholders must weigh regulatory compliance costs against automation premiums when configuring product portfolios for municipal procurement cycles.
Market Dynamics
Autonomous line-marking robotics is compressing labor dependencies across municipal sports infrastructure and commercial turf management, while EU Green Deal solvent restrictions force reformulation of conventional paint chemistries.
Growth Catalysts
- REACH Registration Requirements:European coatings manufacturers are accelerating water-based and low-VOC formulation R&D to maintain market access, creating demand for compatible spray equipment.
- Germany Municipal Investment:Elevated federal-state funding for community sports complexes sustains replacement cycles for ride-on sprayers and first-time robotic acquisitions.
- GPS-Guided Robotics:Athletic field crews eliminate string-line setup labor through centimeter-accurate autonomous navigation, reducing crew size requirements for seasonal line refresh programs.
Market Restraints
- Solvent Price Volatility:Petroleum-derived solvents face input cost swings that compress margin on conventional paint formulations still used in budget segments.
- Battery Supply Concentration:Lithium-ion cell production for robotic units clusters in East Asian manufacturing, exposing European and North American equipment assemblers to supply rationing.
- Thermoplastic Application Limitations:High-temperature melt equipment requires specialized operator certification, constraining adoption outside professional roadway contractor networks.
Strategic Opportunities
- India School Infrastructure:Government-funded K-12 campus expansion under central education schemes creates first-time demand for mechanized marking in districts still using manual methods.
- OSHA Exposure Standard Alignment:Tightening US workplace aerosol limits position closed-cab robotic systems as compliance pathways for municipal procurement.
- Computer Vision Convergence:Integration of lidar obstacle detection with existing GPS navigation enables unsupervised operation in complex multi-use field environments.
Industry Challenges
- Robotics Technician Scarcity:Municipal maintenance departments lack in-house capability to diagnose sensor drift and hydraulic faults in autonomous units.
- Paint-Equipment Certification Timelines:EPA and state-level VOC compliance testing extends product launch cycles by 8-14 months for new formulation-equipment pairings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Marking Equipment Market |
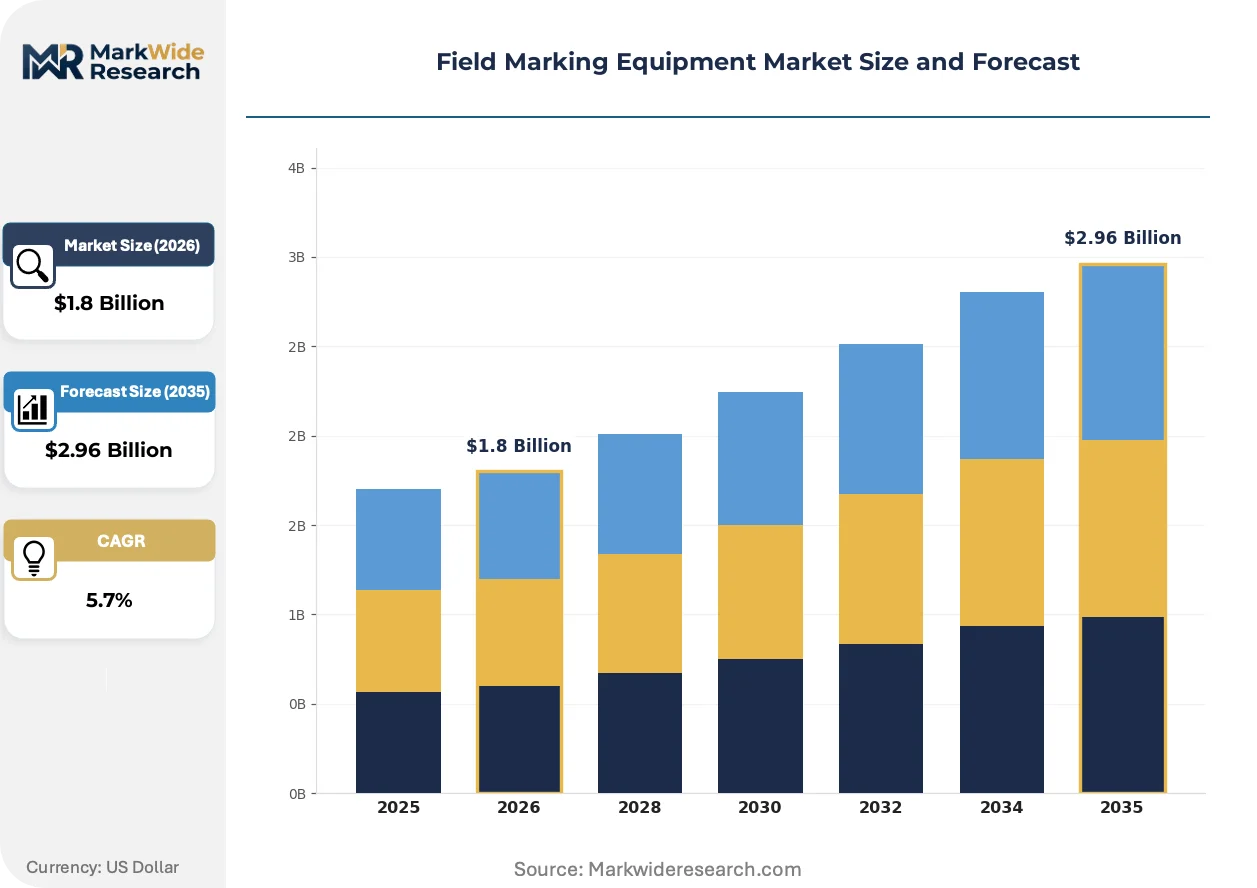
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprayers, Rollers, Paints, Stencils End User: Schools, Sports Facilities, Municipalities, Contractors Application: Athletic Fields, Parking Lots, Roadways, Playgrounds Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Graco, Titan, Fleet Line Maker, Turf Tank, TineMobileRobots, Ennis Flint, Hempel, Geveko Markings, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Marking Equipment Market Evolving Landscape
Equipment intelligence and coating chemistry are advancing in parallel, with automation hardware and environmental compliance requirements locking into a co-evolutionary cycle that rewards integrated system providers.
Lidar-augmented GPS navigation is digitizing field layout workflows for collegiate and professional sports turf managers. Athletic departments with compressed maintenance windows between events are deploying these units for overnight line restoration. The technology is digitizing crew deployment models by collapsing multi-person string-line teams into single-operator oversight roles.
EU Green Deal volatile organic compound limits are tightening solvent-based paint availability across member states. Coatings suppliers are reformulating toward water-borne and bio-based alternatives that demand modified spray tip geometries and pressure profiles. German municipalities, operating under federal clean-air implementation plans, are specifying low-emission equipment packages in public tenders.
Rental and subscription service models are displacing outright equipment ownership among seasonal users. School districts and youth sports leagues with 90-day annual usage windows are accessing robotic units through regional equipment cooperatives. This pattern is most visible in US Midwest states where interscholastic athletic conferences aggregate procurement leverage.
Field Marking Equipment Market Segmentation
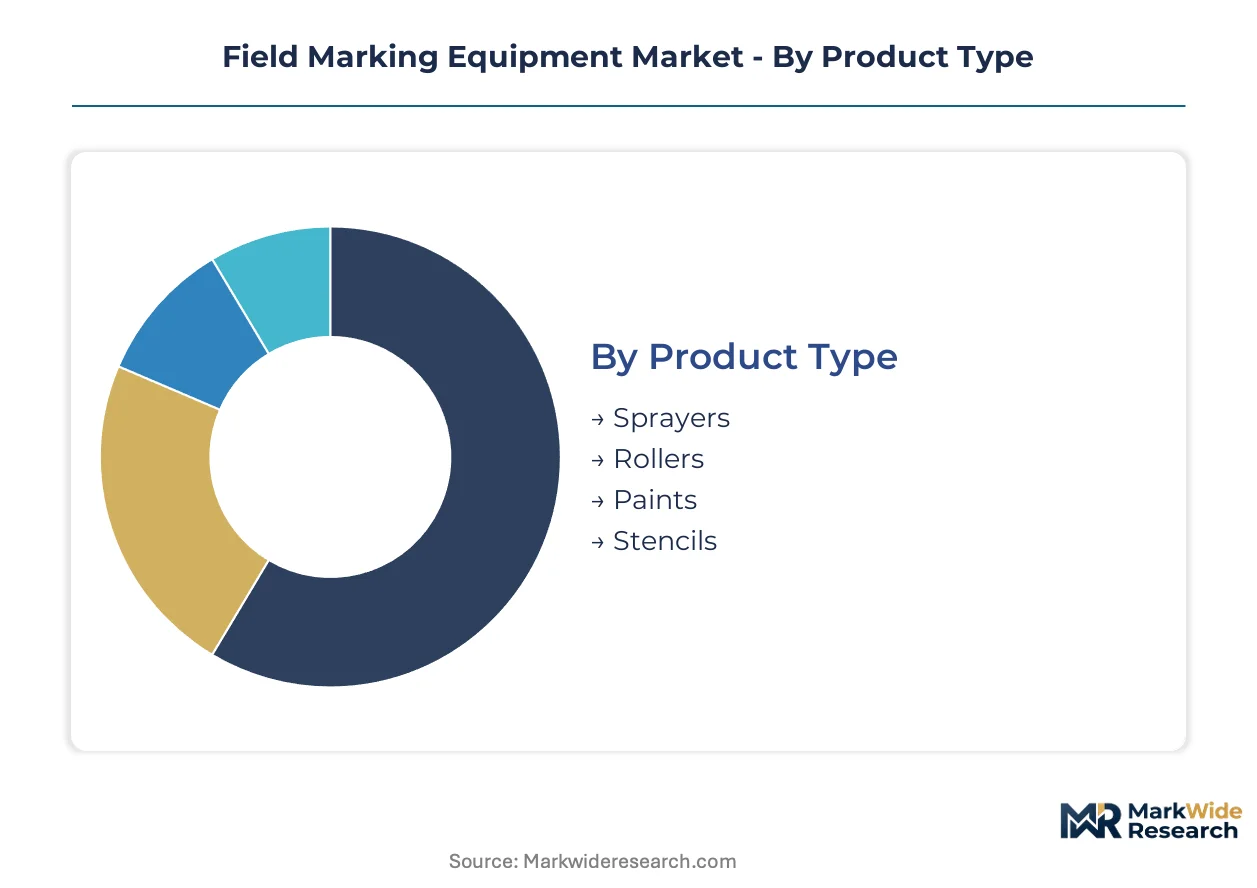
Field marking equipment spans divergent performance requirements across professional sports turf, municipal infrastructure, and educational facilities. Segmentation reveals how technology investment, regulatory exposure, and labor economics reshape procurement patterns across customer categories.
Product Type:
Sprayers dominate high-throughput applications where paint delivery precision determines line durability, while robotics and manual alternatives serve cost-constrained or specialized use cases.
- Sprayers:These systems atomize paint through pressurized nozzles at 50-150 mm widths for athletic lines, with hydraulic or pneumatic drive systems supporting 4-12 km daily output on professional turf. Demand concentrates among German municipal contractors executing federal sports infrastructure programs, where equipment replacement cycles align with REACH-compliant paint formulation upgrades.
- Rollers:Mechanical transfer systems deposit temporary or semi-permanent pigments through fabric or foam cylinders, offering sub-$5,000 entry points for budget-conscious operators. School districts in India's government-funded K-12 expansion are adopting these units as first mechanized alternatives to manual brush methods.
- Paints:Water-based, solvent-based, and thermoplastic formulations constitute recurring revenue streams with formulation-specific equipment compatibility requirements. EPA VOC regulations and EU Green Deal limits are accelerating water-borne chemistry transitions.
- Stencils:Rigid templates for logos, numbers, and specialized markings enable standardized graphic replication across multi-field complexes. Athletic departments with compressed event turnover windows rely on these for rapid brand deployment.
The dominant share belongs to Sprayers, while GPS-guided autonomous variants within this category are closing the gap fastest.
End User:
Procurement authority and budget scale vary sharply across institutional buyers, with federal funding streams and seasonal usage patterns dictating equipment configuration choices.
- Schools:K-12 and collegiate athletic departments operate on 90-120 day annual usage windows, driving rental cooperative membership and mid-tier sprayer acquisitions. US Midwest interscholastic conferences aggregate procurement leverage through shared equipment pools.
- Sports Facilities:Professional stadiums and training complexes demand overnight line restoration capability, positioning lidar-augmented robotic units for unsupervised operation. These buyers absorb premium pricing for labor elimination and precision repeatability.
- Municipalities:German federal-state funding for community sports complexes sustains replacement cycles, with public tenders increasingly specifying low-emission equipment packages under clean-air implementation plans.
- Contractors:Roadway and turf maintenance firms amortize equipment across multiple client sites, favoring high-volume paint delivery systems with attachment compatibility for existing chassis fleets.
Sports Facilities command premium equipment configurations, though Municipalities provide the steadiest replacement demand through cyclical infrastructure programs.
Application:
Surface material and traffic exposure create divergent durability requirements, with thermoplastic and paint chemistry selections tied to substrate preparation standards.
- Athletic Fields:Natural and synthetic turf surfaces require 50-150 mm line widths with weather-resistant formulations withstanding cleat traffic and maintenance equipment. GPS-guided robotics eliminate string-line setup labor for seasonal refresh programs.
- Parking Lots:Asphalt and concrete substrates demand 100-200 mm stall markings with thermoplastic or epoxy options for heavy vehicle loading. OSHA workplace exposure standards influence closed-cab system specifications for municipal procurement.
- Roadways:High-temperature melt thermoplastic application requires specialized operator certification, constraining adoption to professional contractor networks with established training pipelines.
- Playgrounds:Temporary and semi-permanent pigments serve seasonal recreational marking with lower durability thresholds, supporting roller-based methods in budget-constrained settings.
Athletic Fields absorb the most sophisticated navigation technology, yet Parking Lots generate broader equipment volume through standardized marking protocols.
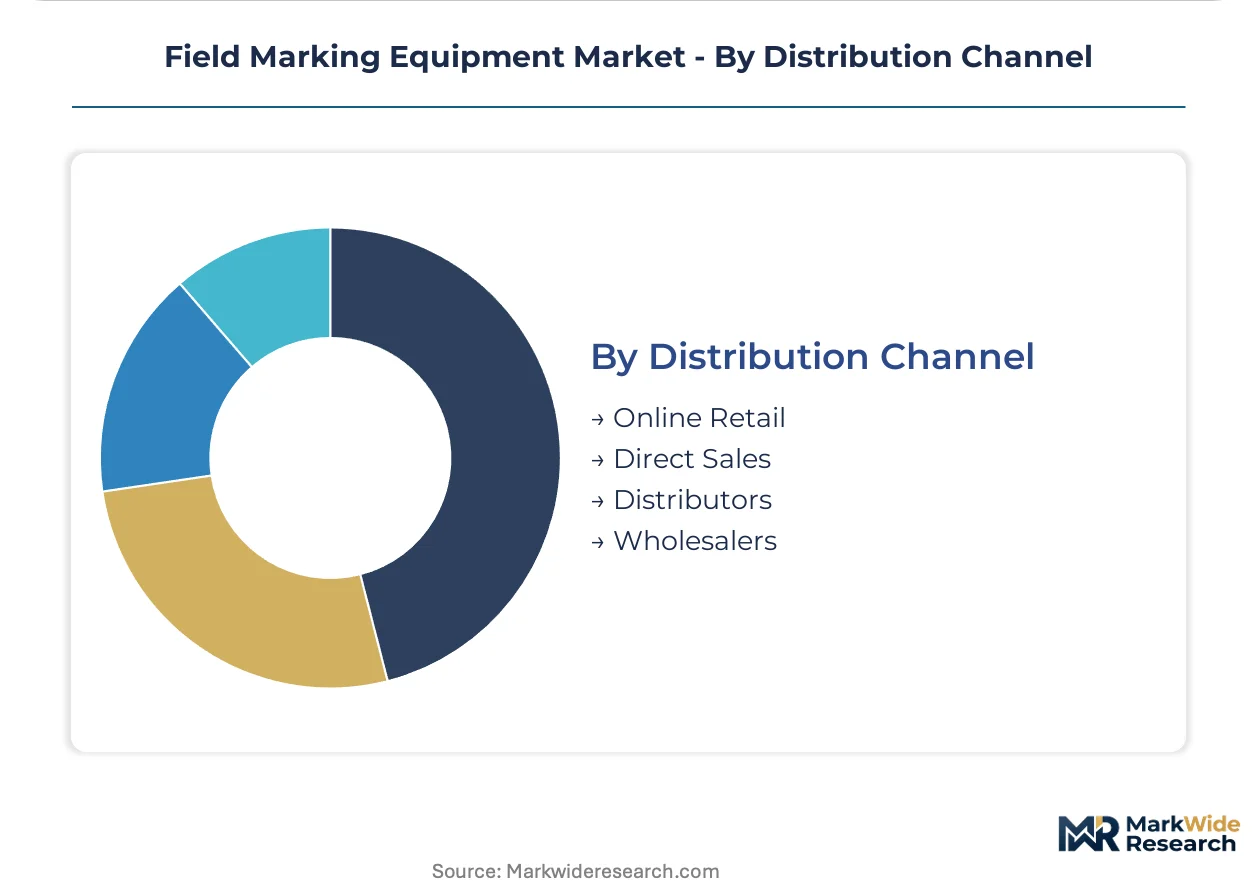
Distribution Channel:
Channel selection reflects customer technical sophistication, seasonal urgency, and aftermarket service requirements for calibration and parts availability.
- Online Retail:E-commerce platforms serve stencil and consumable purchases with immediate fulfillment, though capital equipment transactions remain limited by demonstration and service requirements.
- Direct Sales:Manufacturer field representatives configure integrated paint-equipment packages for large municipal and collegiate accounts, navigating EPA and state-level VOC compliance testing timelines.
- Distributors:Regional equipment houses maintain demonstration fleets and technician networks for sensor calibration and hydraulic diagnostics, addressing robotics technician scarcity in municipal departments.
- Wholesalers:Volume aggregators serve rental cooperatives and contractor fleets with standardized configurations, concentrating inventory in seasonal demand corridors.
Direct Sales capture the most complex integrated system transactions, while Distributor networks are expanding most quickly through robotic unit service dependencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement departments and sports facility operators concentrate equipment demand in economies with active federal infrastructure programs and stringent environmental compliance frameworks. Buyer archetypes split between German municipal contractors executing clean-air mandates and US school districts aggregating seasonal rental cooperatives.
Germany
Federal-state funding for community sports complexes sustains replacement cycles for ride-on sprayers and first-time robotic acquisitions. EU Green Deal volatile organic compound limits enforce water-borne paint transitions through REACH registration requirements. Equipment clusters concentrate in North Rhine-Westphalia, where municipal tender specifications increasingly mandate low-emission spray packages.
United States
Midwest interscholastic athletic conferences aggregate procurement leverage through shared equipment pools serving 90-day seasonal usage windows. EPA volatile organic compound rules constrain solvent-based formulations, positioning closed-cab robotic systems as OSHA workplace exposure compliance pathways. Turf management technology adoption concentrates in collegiate athletic departments across the Southeast and Pacific Northwest.
India
Central government-funded K-12 campus expansion creates first-time mechanized marking demand in districts transitioning from manual brush methods. Bureau of Indian Standards certification requirements shape equipment import specifications for municipal education tenders. Manufacturing and assembly activity clusters in Maharashtra and Gujarat, serving northern and western state school infrastructure programs.
United Kingdom
Local authority sports facility maintenance budgets prioritize cost-efficient line refresh cycles amid compressed municipal finance conditions. Environment Agency discharge permits influence paint formulation selections for turf and hard surface applications. Equipment distribution networks concentrate in the Midlands and Greater London, serving combined authority procurement frameworks.
China
Municipal sports infrastructure investment under national fitness programs sustains volume demand for mid-tier mechanical marking systems. Ministry of Ecology and Environment standards tighten solvent emissions in urban coating applications. Manufacturing capacity clusters in the Yangtze River Delta, supplying domestic municipal procurement and export markets across Southeast Asia.
Field Marking Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement pathways serving municipal, educational, and commercial end users. The vendor base organizes around three strategic archetypes: fluid handling engineering specialists with attachment compatibility for existing chassis fleets, GPS-guided robotics developers eliminating string-line labor, and coatings-integrated system providers bundling compliant paint formulations with delivery hardware. Dominant competitive moves include geographic expansion through regional distributor partnerships and portfolio diversification into rental service models.
Within the robotics-specialist tier, Turf Tank and TineMobileRobots exemplify autonomous navigation developers targeting athletic field labor reduction. Graco anchors the fluid handling engineering segment through high-volume paint delivery systems. Fleet Line Maker occupies a position among equipment fabricators serving municipal contractor networks with ride-on configurations.
| Leading Market Players |
|---|
| Graco |
| Titan |
| Fleet Line Maker |
| Turf Tank |
| TineMobileRobots |
| Ennis Flint |
| Hempel |
| Geveko Markings |
| PPG Industries |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster anchors lithium-ion cell output for robotic line markers, concentrating battery cost leverage among East Asian suppliers and compressing margin negotiation room for European and North American equipment assemblers facing supply rationing exposure.
Pricing Analysis
Cost-plus contracts with solvent price indexation dominate paint procurement between German municipal contractors and coatings suppliers. Pricing stratifies across GPS-guided robotic systems, mid-tier ride-on sprayers, and sub-$5,000 roller units based on navigation sophistication and after-sales service bundling. Cost compression in solvent-based formulations is intensifying because petroleum-derived input volatility erodes margin on conventional chemistry still specified in budget segments. School districts operating through Midwest rental cooperatives exhibit highest price sensitivity, while professional sports facilities absorb premium positioning for labor-eliminating autonomy.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities have become standard for distributors serving municipal procurement cycles with 90-120 day seasonal usage windows. Component sourcing concentrates in China for lithium-ion cells, Germany for precision hydraulic systems, and India for emerging roller assembly capacity. Raw material dependencies span petroleum-derived solvents, high-grade steel for chassis fabrication, and semiconductor chips for GPS navigation modules. Single-source vulnerability in East Asian battery cell production exposes equipment assemblers to supply rationing. Distribution runs through regional equipment houses maintaining demonstration fleets and technician networks for sensor calibration and hydraulic diagnostics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotics technician scarcity constrains municipal adoption velocity, creating a capability gap between autonomous equipment deployment and in-house maintenance competence that shapes competitive positioning across integrated system providers.
For Market Incumbents: Harden service network density around GPS-guided robotic units to capture recurring calibration revenue and lock out distributor competitors. Deepen backward integration into REACH-compliant water-borne paint formulations to offset solvent price volatility exposure. Anchor fleet compatibility architectures that protect installed-base attachment sales from emerging robotics specialists. For New Entrants and Emerging Players: Build out rental cooperative relationships in US Midwest interscholastic conferences where seasonal aggregation models reduce customer acquisition cost. Target India's government-funded K-12 campus expansion as the most penetrable geography, positioning mechanical rollers as first mechanized alternatives to manual brush methods. Pursue Bureau of Indian Standards certification as a procurement gatekeeper for central education tenders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coatings-integrated system providers bundling compliant formulations with delivery hardware over pure-play robotics developers facing technician scarcity headwinds. Long-term viability rests on regulatory co-evolution with EU Green Deal enforcement and EPA VOC rule tightening. Acquisition target archetype: regional distributors with embedded municipal relationships and technician training pipelines. Monitor REACH registration timelines for water-borne formulation approvals as inflection indicator for equipment-paint package demand.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Service Network Expansion | Regional technician density captures recurring calibration revenue from municipal GPS-guided deployments. |
| REACH-Compliant Formulation Integration | Water-borne paint bundling locks equipment-pairing relationships under EU Green Deal enforcement. |
| Rental Cooperative Partnership | Midwest interscholastic aggregation models reduce customer acquisition cost for seasonal usage segments. |
| Lidar-Computer Vision Convergence | Unsupervised operation capability opens overnight line restoration contracts in professional sports facilities. |
| India Manufacturing Localization | Maharashtra and Gujarat assembly positions for Bureau of Indian Standards certification in central education tenders. |
Research Methodology
The analysis maps sprayers, robotics, rollers, and coatings segments, each validated through maintenance directors at collegiate athletic departments, municipal procurement officers, aftermarket service heads at regional distributors, and coatings R&D directors. Primary fieldwork combined with secondary validation from EPA VOC rule filings, EU REACH registration databases, Bureau of Indian Standards certification records, and municipal tender documentation. Bottom-up equipment shipment tracking triangulates against top-down federal infrastructure program allocations.
Assumptions held fixed include EU Green Deal enforcement trajectory and lithium-ion cell supply concentration, while variables included municipal budget cycles and school district rental cooperative formation rates. Segmentation dimensions modeled span product type, end user category, surface application, and regional regulatory cluster across the projection horizon. CAGRs derive from equipment replacement cycle analysis overlaid with autonomous adoption curve modeling. Industry-specific inputs include paint formulation-equipment compatibility certification timelines and GPS navigation precision improvement rates.
Practitioners should monitor solvent price volatility spikes and REACH registration approval delays for early signals of margin compression or product launch timeline extension. Forecasts reflect these documented assumptions; macroeconomic deviation in municipal infrastructure spending, regulatory acceleration in VOC limits, or breakthrough battery chemistry substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Grader Blades Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Piling Machine Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Suction Excavator Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Asia Pacific Construction Equipment Market