
 Overhead Cranes Market | 2026-2036
Overhead Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Cranes Market Intelligence
Modular crane kit configurations is expanding buyer flexibility across project scales. Konecranes leverages its technology leadership in automated harbor systems. DeShazo Crane Company, LLC anchors regional manufacturing capacity in the southeastern United States. Gorbel differentiates through ergonomic workstation crane specialization.
Overhead cranes are load-lifting mechanisms suspended from parallel runway beams, rated typically from one ton to several hundred tons capacity, designed for repetitive vertical and horizontal material transport within fixed facility footprints. Double girder types dominate heavy-lift applications due to superior hook height and span capabilities, while single girder configurations occupy cost-sensitive manufacturing installations. Wire rope hoist technology leads in high-cycle port and mining environments, whereas electric motor drives are displacing hydraulic systems in warehousing applications seeking precision positioning.
OSHA crane operator certification mandates and FEM 1.001 mechanical equipment standards shape product design and aftermarket service obligations across the United States and Europe. China's SAMR enforcement of GB/T crane safety codes is raising compliance costs for domestic and imported equipment alike. Stakeholders must monitor how regional certification divergence affects cross-border equipment deployment and service network economics.
Market Dynamics
Shipbuilding yards in South Korea are accelerating automated crane procurement, while port modernization across Chinese coastal cities is compressing replacement cycles and reshaping supplier qualification requirements.
Growth Catalysts
- OSHA certification mandates:US facilities face expanded operator training requirements, forcing equipment upgrades and aftermarket service bundling.
- Wire rope hoist technology:Mining and bulk port terminals adopt high-cycle configurations to reduce downtime in 24/7 operations.
- Chinese port clusters:Ningbo-Zhoushan and Shanghai container throughput expansion drives double girder crane deployment.
Market Restraints
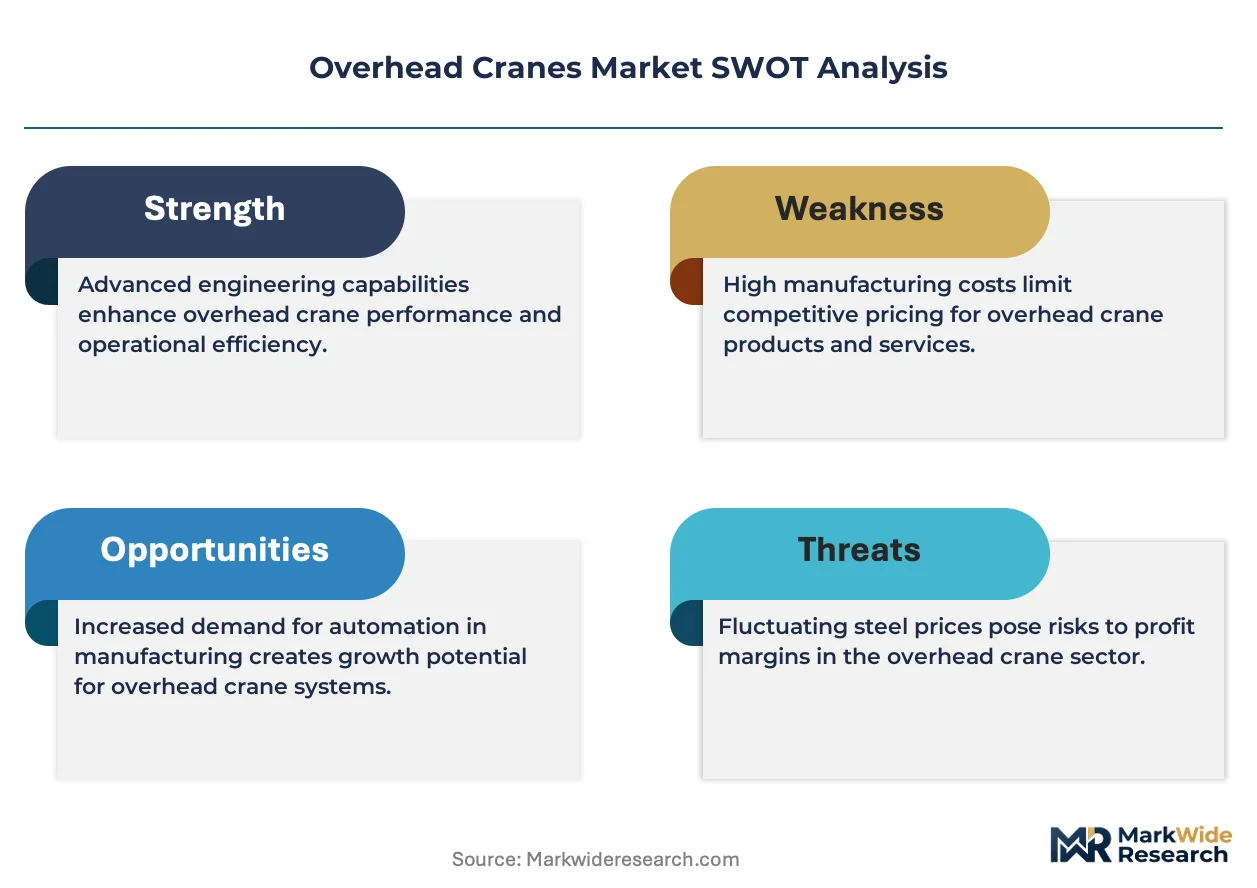
- Steel input volatility:Structural beam and trolley fabrication costs swing with commodity pricing, squeezing fixed-price contract margins.
- European supplier concentration:FEM-certified component sourcing clusters in Germany and Italy, creating lead time vulnerability.
- Electric drive substitution limits:Heavy-lift mining applications above 500 tons retain hydraulic systems due to torque density constraints.
Strategic Opportunities
- Indian manufacturing corridors:PLI scheme incentives for electronics and automotive assembly create greenfield crane demand in Tamil Nadu and Gujarat.
- Remote monitoring convergence:IoT sensor networks and predictive maintenance algorithms unlock subscription revenue from installed bases.
- Modular kit distribution:Online configuration tools and regional assembly partnerships reduce capital barriers for mid-scale buyers.
Industry Challenges
- Certified technician scarcity:OSHA and FEM inspection credentials require 18-24 month training pipelines, constraining service network expansion.
- Legacy control integration:Analog-era crane fleets in US Midwest manufacturing plants resist digital retrofit without full electrical rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Cranes Market |
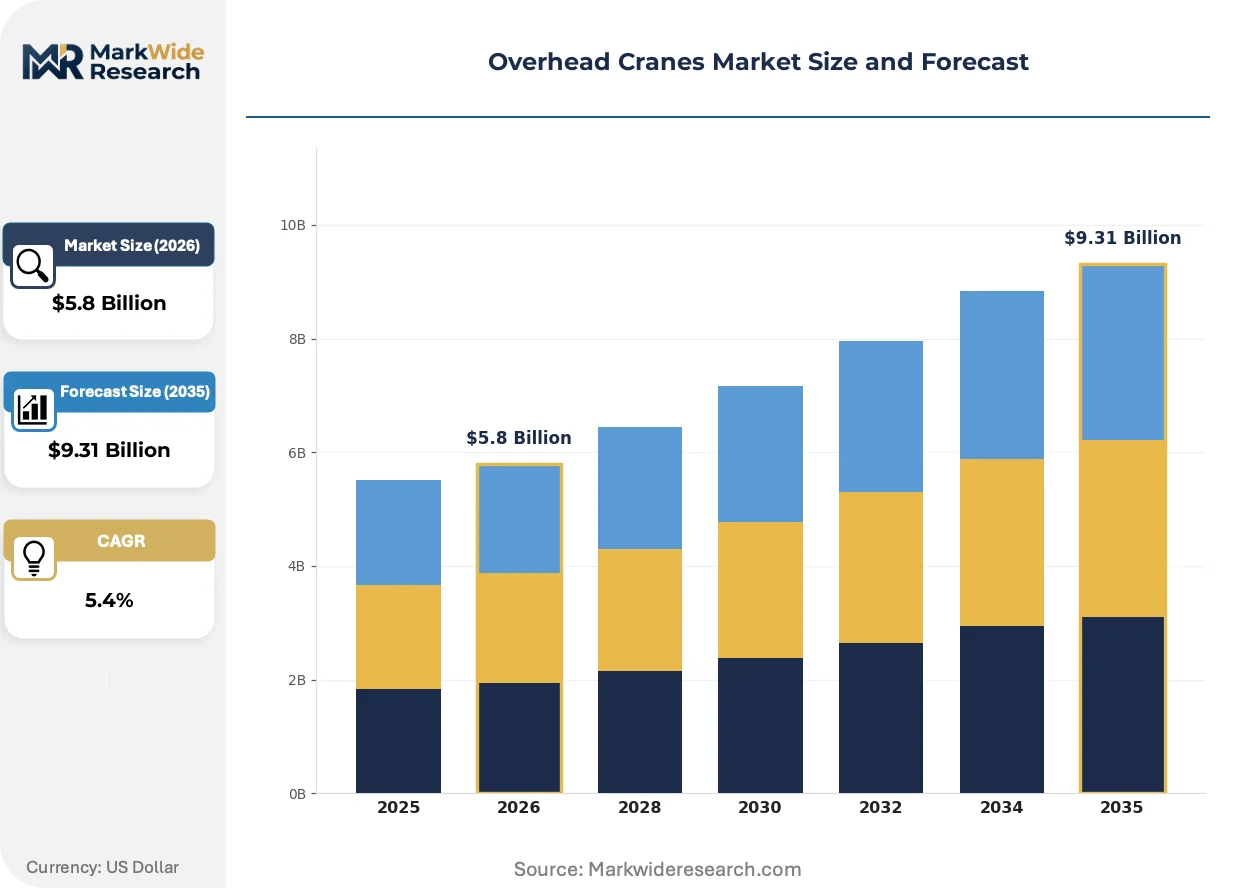
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Girder, Double Girder, Gantry, Jib, Stacker Technology: Wire Rope Hoist, Chain Hoist, Electric Motor, Hydraulic, Manual Application: Manufacturing, Shipbuilding, Construction Sites, Warehousing, Mining End User: Heavy Equipment Manufacturers, Port Operators, Warehouse Facilities, Mining Firms, Construction Contractors |
| Companies Covered | DeShazo Crane Company, LLC, American Crane & Equipment Corp, Konecranes, Mazzella Companies, Whiting Corporation, Demag Cranes & Components Corp., Gorbel, Spanco, Inc., Engineered Material Handling (EMH) Cranes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Cranes Market Strategic Shifts & Innovations
Automation architectures and predictive service models are compressing the traditional equipment-sales cycle into integrated lifecycle partnerships.
Collision-avoidance sensor arrays is unifying crane-to-crane coordination in dense port environments. Terminal operators in Rotterdam and Hamburg deploy these systems to stack containers closer while maintaining safety clearances. This convergence of LiDAR and machine-vision processing is compressing yard footprint requirements per throughput unit.
China's SAMR enforcement of updated GB/T crane safety codes is mandating redundant braking systems and real-time load monitoring on all new installations. Domestic manufacturers absorb compliance costs through vertical integration into control system production. Imported equipment faces extended type-approval timelines, favoring local assembly partnerships.
Buyers in automotive and aerospace assembly are unbundling maintenance from capital purchase, contracting uptime guarantees directly with crane OEM service arms. This shift displaces independent repair shops in Germany and Japan. Tier-one suppliers now compete on mean-time-between-failure metrics rather than initial equipment pricing.
Overhead Cranes Market Segmentation
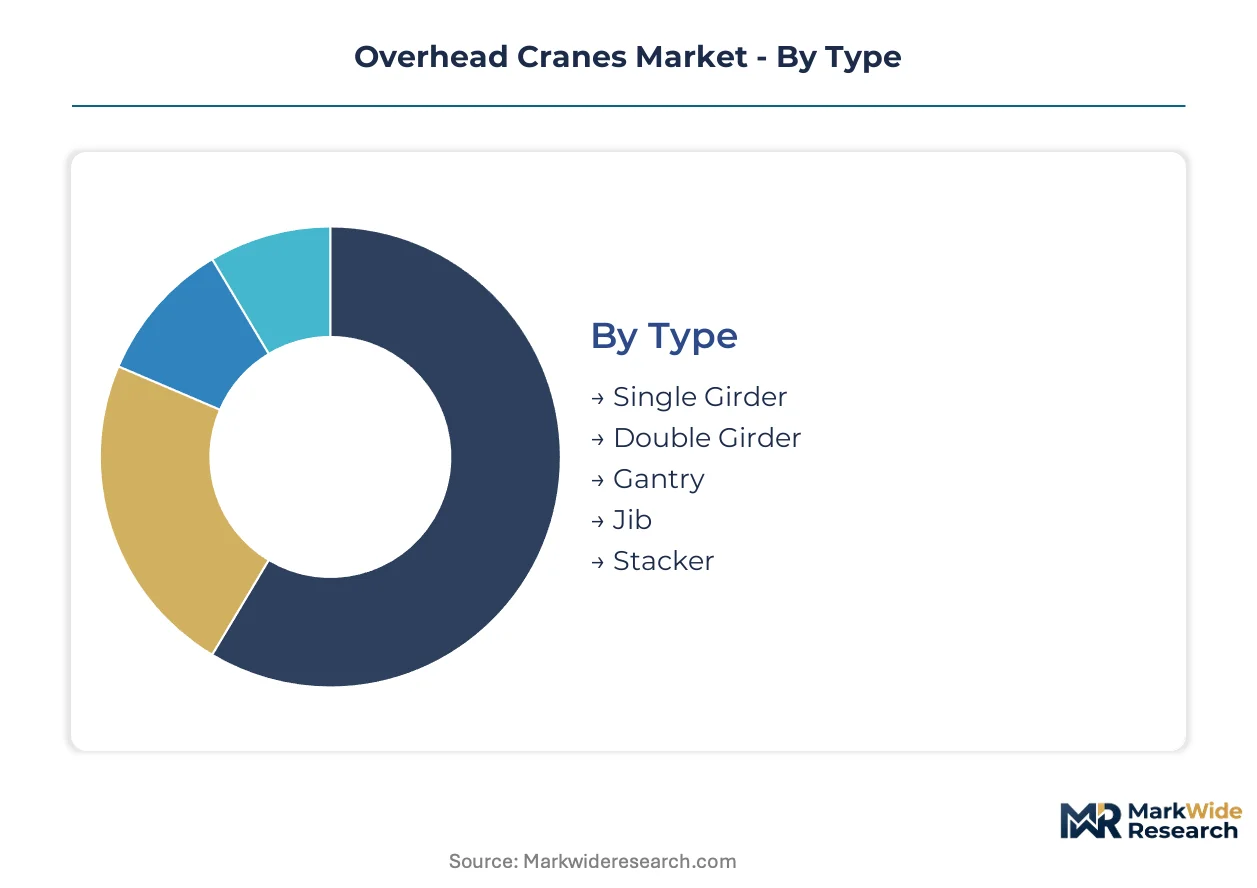
Overhead crane segmentation reveals distinct capital-intensity tiers that determine procurement cycles and supplier economics. Equipment type and technology choices drive installation costs across multiple orders of magnitude, from manual jib cranes to automated double-girder port systems.
Type:
Capital requirements vary dramatically across crane architectures, with span and lift capacity determining structural steel tonnage and foundation engineering.
- Single Girder:Economical bridge design utilizing one primary beam for spans under 20 meters and capacities below 20 tons. Light manufacturing facilities in India and Vietnam favor this configuration for assembly-line material feeding where ceiling height is constrained.
- Double Girder:Twin-beam construction delivers superior hook height and span capabilities exceeding 30 meters. Ningbo-Zhoushan port terminals deploy these for container handling above 50 tons, though foundation costs can exceed equipment purchase price.
- Gantry:Floor-supported leg structure eliminates building column dependency for outdoor material yards. Mining operations in Western Australia specify these for ore stockpile management where runway beam installation is impractical.
- Jib:Cantilevered boom rotates on a fixed column or wall bracket for localized workstation coverage. Automotive component suppliers integrate these at individual assembly stations for ergonomic part positioning.
- Stacker:Automated storage and retrieval crane optimized for high-bay warehouse density. Cold chain distribution centers in the Netherlands specify these for frozen goods handling where floor space carries premium valuation.
Double girder configurations absorb the bulk of installed capacity in heavy-lift environments; stacker cranes are expanding most quickly in e-commerce fulfillment infrastructure.
Technology:
Hoist mechanism selection determines maintenance intervals, energy consumption, and precision control characteristics across operating environments.
- Wire Rope Hoist:Multi-strand cable drum system rated for high-cycle duty classifications. Bulk port terminals adopt these for 24/7 operation exceeding 500,000 annual cycles, with drum inspection intervals mandated by FEM 1.001 standards.
- Chain Hoist:Linked metal chain drive offers compact headroom and true vertical lift without lateral hook drift. Machine shops in Germany specify these for precision positioning below 5 tons where floor space is severely constrained.
- Electric Motor:Variable frequency drives enable smooth acceleration profiles and regenerative braking. Warehouse operators in the United States displace hydraulic systems with these for energy recovery and reduced oil contamination risk.
- Hydraulic:Fluid power transmission delivers torque density unmatched by electric alternatives above 500 tons. Open-pit mining in Chile retains these for shovel maintenance and crusher feed where peak loads exceed motor thermal limits.
- Manual:Hand chain or push-type operation for intermittent lifting below 2 tons. Maintenance departments in small machine shops specify these where electrical supply is unavailable or capital budgets are severely restricted.
Wire rope technology dominates heavy-cycle port and mining installations; electric motor drives are climbing the fastest as warehousing automation accelerates.
Application:
End-use environment dictates corrosion protection, explosion-proofing, and automation integration requirements.
- Manufacturing:Repetitive material handling integrated with production line pacing. Automotive stamping plants in Mexico specify synchronized crane groups for die change operations compressed under 10 minutes.
- Shipbuilding:Block assembly and outfitting in covered building docks. South Korean yards deploy automated double-girder systems for hull section positioning where tolerances measure in millimeters.
- Construction Sites:Temporary installation for structural steel erection and equipment placement. Tower crane supplementation with mobile gantry units accelerates high-rise core construction in Dubai and Singapore.
- Warehousing:High-velocity storage and retrieval in distribution networks. Amazon fulfillment centers specify stacker cranes with aisle-changing capability for SKU proliferation management.
- Mining:Harsh-duty extraction and processing material flow. Copper concentrators in Peru utilize gantry configurations for ball mill reline operations in abrasive dust environments.
Manufacturing absorbs the bulk of installed base volume; shipbuilding is gaining share fastest as naval and commercial vessel construction revives.
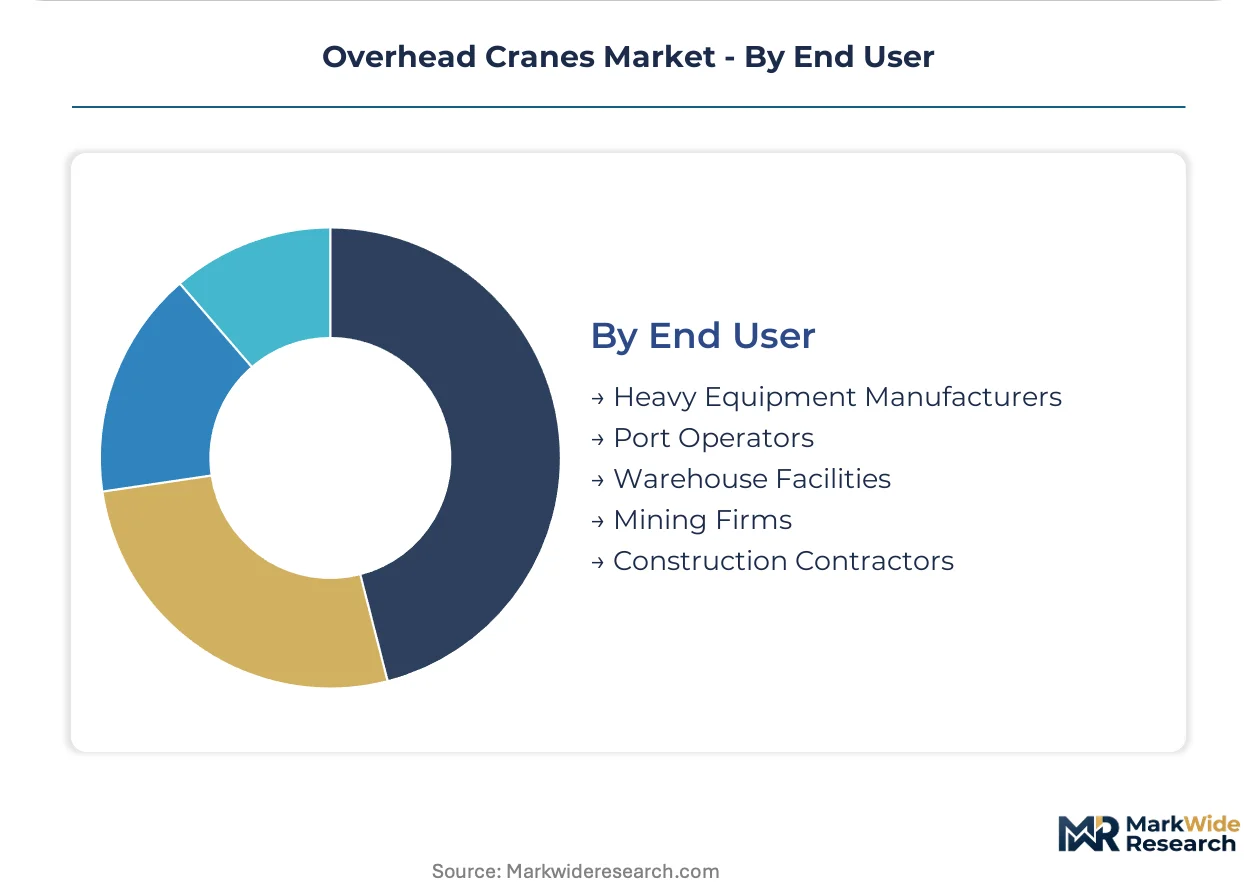
End User:
Procurement sophistication and lifecycle cost analysis maturity vary substantially across buyer categories.
- Heavy Equipment Manufacturers:Capital-intensive production facilities with in-house maintenance capabilities. Caterpillar and Komatsu specify OEM service contracts with uptime guarantees exceeding 98% availability.
- Port Operators:Terminal velocity maximization through automation and predictive maintenance. Rotterdam terminal operators bundle crane procurement with 15-year service agreements displacing independent repair vendors.
- Warehouse Facilities:Third-party logistics providers and e-commerce fulfillment networks. Prologis development specifications increasingly mandate crane-ready clear heights above 12 meters.
- Mining Firms:Remote site operations with extreme duty cycle and environmental exposure. BHP and Rio Tinto specify corrosion-resistant coatings and sealed electrical enclosures for desert and tropical installations.
- Construction Contractors:Project-based rental and lease arrangements for temporary installations. Turner Construction and Bechtel source mobile gantry packages through equipment rental networks rather than capital purchase.
Heavy equipment manufacturers absorb the bulk of replacement demand; warehouse facilities are expanding procurement fastest as distribution automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of structural steel components while the United States and Germany absorb premium automated systems. Demand fragmentation across port modernization, automotive assembly, and mining operations creates distinct procurement patterns by geography.
China
SAMR enforcement of updated GB/T crane safety codes mandates redundant braking systems on all new installations. Domestic manufacturers absorb compliance costs through in-house production of control systems. Ningbo-Zhoushan port terminals deploy double-girder configurations for container handling above 50 tons.
United States
OSHA certification mandates force equipment upgrades and aftermarket service bundling across Midwest manufacturing plants. The Department of Labor expanded operator training requirements compress replacement cycles. Automotive stamping facilities in Michigan specify synchronized crane groups for die change operations.
Germany
FEM 1.001 mechanical equipment standards shape product design obligations across European supply chains. Machine shops in Baden-Württemberg specify chain hoists for precision positioning below 5 tons. Terminal operators in Hamburg deploy collision-avoidance sensor arrays to compress yard footprint requirements.
South Korea
Shipbuilding yards accelerate automated crane procurement for hull section positioning where tolerances measure in millimeters. The Ministry of Trade, Industry and Energy supports smart manufacturing infrastructure investments. Ulsan and Geoje shipbuilding clusters drive double-girder system deployment.
India
PLI scheme incentives for electronics and automotive assembly create greenfield crane demand in Tamil Nadu and Gujarat. The Central Electricity Authority mandates certification for electrical installation safety. Manufacturing corridors near Chennai and Ahmedabad attract modular crane kit distribution partnerships.
Overhead Cranes Market Key Industry Players
The competitive structure tilts toward technology-integrated specialists capable of bundling equipment with predictive maintenance subscriptions. Mid-scale regional fabricators compete on delivery speed and customization flexibility. Two dominant strategic archetypes have emerged: automation-focused harbor system providers and ergonomic workstation specialists. Competitive moves concentrate on M&A for control system capabilities and geographic expansion through regional assembly partnerships.
Among North American fabricators, DeShazo Crane Company, LLC anchors regional manufacturing capacity in the southeastern United States, while Gorbel occupies a position exemplifying ergonomic workstation crane specialization. Konecranes represents the automation-integrated tier with harbor system technology leadership.
| Leading Market Players |
|---|
| DeShazo Crane Company, LLC |
| American Crane & Equipment Corp |
| Konecranes |
| Mazzella Companies |
| Whiting Corporation |
| Demag Cranes & Components Corp. |
| Gorbel |
| Spanco, Inc. |
| Engineered Material Handling (EMH) Cranes |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up regional fabricators now control substantial aftermarket service networks across the southeastern United States, tightening pricing discipline through captive maintenance bundling while compressing margins for independent repair shops. This ownership concentration reshapes how steel input volatility transmits through contract structures.
Pricing Analysis
Margin tightening in standard-duty crane tiers traces to Chinese port operators demanding extended warranty terms as SAMR compliance costs mount. Three-tier pricing structure across premium, standard, and economy levels separates FEM-certified European systems from Chinese domestic brands and unbundled component kits. Price differentiation rests on certification grade and after-sales service bundling. Warehouse facilities exhibit highest price sensitivity due to capital budget constraints, while port operators prioritize uptime guarantees over initial equipment cost.
Supply Chain Analysis
FEM 1.001 certification requirements gate component sourcing to German and Italian specialist suppliers, creating qualification bottlenecks for new market entrants. Structural steel fabrication concentrates in China, Germany, and the United States, with control system production drawing from South Korean and Japanese electronics clusters. Supply chain risk centers on single-source vulnerability for high-cycle wire rope hoist mechanisms. Distribution runs through OEM-direct channels for automated harbor systems and regional assembly partnerships for modular kit configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA certification mandates have erected a formidable compliance moat, elevating qualified incumbents while raising capital barriers for speculative entrants. This cost-of-compliance dynamic favors technology-integrated specialists with established service networks.
For Market Incumbents: Hedge steel input exposure through long-term supply agreements with Korean and Chinese mills while accelerating predictive maintenance subscription penetration. Defensive consolidation of regional service networks protects against IoT-native entrants offering remote diagnostics without legacy technician overhead.
For New Entrants and Emerging Players: Collision-avoidance sensor integration offers a technology-first wedge into dense port environments where incumbent systems lack machine-vision coordination. White-space targets include Indian manufacturing corridors seeking modular kit partnerships and Midwest US facilities requiring analog-to-digital control retrofits without full electrical rebuilds.
For Investors and Strategic Acquirers: Accelerated procurement timelines from South Korean shipbuilding yards signal inflection that automation-integrated specialists will capture disproportionate value across the projection horizon. Long-term viability favors targets with captive control system production and established FEM or OSHA certification pathways. Monitor SAMR enforcement intensity as the leading indicator for Chinese market access conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Systems | Captive production of safety-critical electronics reduces SAMR approval timelines for Chinese deployments. |
| Predictive Maintenance Platform Launch | IoT sensor networks unlock recurring revenue from Konecranes and DeShazo installed bases. |
| Regional Assembly Partnership | Tamil Nadu and Gujarat facilities reduce logistics costs for Indian PLI-scheme manufacturing corridors. |
| Collision-Avoidance Technology Licensing | LiDAR and machine-vision systems address Rotterdam and Hamburg terminal footprint compression requirements. |
| Certified Technician Training Pipeline | OSHA and FEM credential programs alleviate service network expansion constraints across Midwest manufacturing. |
Research Approach
Trade association filings, customs shipment records, and equipment registration databases formed the secondary backbone, cross-referenced with primary interviews involving maintenance directors at heavy equipment manufacturers, port terminal operations managers, plant engineers at automotive stamping facilities, and aftermarket service heads at regional crane distributors. Bottom-up and top-down triangulation validated segmentation assumptions across duty classifications and geographic procurement clusters.
Bottom-up modeling anchored forecasts in installed base depreciation curves and replacement cycle analysis, while top-down approaches tested aggregate demand against macro-industrial capacity indicators across the projection horizon. Segmentation dimensions included crane architecture, hoist technology, end-use environment, and buyer sophistication tier. CAGRs derived from regression analysis of historical procurement patterns against regulatory compliance cost indices and steel price volatility metrics.
Several conditions sit outside the modeled scope, including abrupt tariff regime changes affecting Chinese component sourcing and unanticipated technological substitution in heavy-lift mining applications above 500 tons. Forecasts reflect documented assumptions about certification timeline stability and technician training pipeline throughput. A model refresh is warranted upon material change in OSHA enforcement intensity or SAMR type-approval procedural revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Winch Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Mini Excavators Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Used Backhoe Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Walform Machines Market
Construction Equipment
Boring Bar Market
Construction Equipment
North America Crane Rental Market