
 United States Completion Equipment and Services Market | 2026-2036
United States Completion Equipment and Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Completion Equipment and Services Market Analytics
The gap between premium engineered completion systems and commodity-grade equipment is broadening as operators push deeper into unconventional reservoirs. Halliburton Company leverages proprietary frac plug technologies to anchor its position in high-pressure horizontal wells. Baker Hughes Company competes through integrated wellhead and production tree portfolios that reduce surface footprint. Schlumberger Ltd differentiates via digital completion platforms that optimize stage-by-stage perforation efficiency.
Completion equipment and services encompass the hardware, fluids, and intervention technologies required to prepare a drilled well for hydrocarbon production, including wellheads rated to 20,000 psi, production trees with subsea or surface configurations, and packers that isolate zones for selective stimulation. The primary purpose is to establish controlled, safe flow paths from reservoir to surface while enabling future intervention. Stimulation services command the largest margin pools as operators extend lateral lengths beyond 15,000 feet in the Permian and Eagle Ford. Coiled tubing activity is accelerating fastest in refrac programs across maturing Bakken wells. Wellheads remain a mature, replacement-driven segment where price competition limits differentiation.
The EPA enforces methane emissions standards under the Clean Air Act that compel operators to deploy low-leakage completion hardware and flare-reduction systems. The Texas Railroad Commission mandates casing and cementing requirements that directly shape packer and tubing specifications for well integrity. OSHA oversees pressure-testing protocols for coiled tubing and wireline operations. Stakeholders must monitor how evolving federal methane rules and state-level seismicity restrictions reshape equipment procurement criteria across the major shale basins.
Market Dynamics
Multi-stage hydraulic fracturing intensity in the Permian Basin is compressing equipment cycle times while EPA methane rules force hardware retrofits across existing well inventories.
Growth Catalysts
- EPA Methane Standards:The Clean Air Act enforcement compels operators to replace high-leakage wellheads and install flare-reduction systems, generating replacement demand for low-emission completion hardware.
- Lateral Length Extension:Permian operators pushing beyond 15,000-foot laterals require additional frac stages per well, directly multiplying packer, plug, and perforating gun consumption per completion.
- Refracturing Maturation:Bakken and Eagle Ford vintage wells entering their second production cycle drive coiled tubing intervention demand for zonal isolation and restimulation.
Market Restraints
- Specialized Steel Alloy Volatility:Chromium-molybdenum tubing and high-pressure wellhead forgings face price swings tied to mining concentration in South Africa and Kazakhstan.
- Texas Railroad Commission Casing Mandates:Cementing and pressure-testing requirements extend procurement timelines for deep horizontal wells in the Delaware Basin.
- Electrification Substitution:Grid-powered drilling and completion spreads reduce diesel engine maintenance contracts, compressing traditional power unit service revenue.
Strategic Opportunities
- New Mexico Permian Expansion:Lea and Eddy counties host underdeveloped acreage where multi-well pad development favors integrated completion packages over discrete equipment sourcing.
- Digital Completion Convergence:Real-time pressure monitoring fused with automated perforation selection enables stage-specific optimization in high-variable geology.
- OSHA Pressure-Testing Protocols:Enhanced coiled tubing certification requirements create service differentiation for operators with certified maintenance facilities.
Industry Challenges
- Specialized Technician Scarcity:Wireline engineers and frac crew supervisors with horizontal well expertise command premium wages, constraining crew scaling in the Permian.
- Legacy Wellhead Integration:10,000-psi rated surface equipment from 2010-2015 vintages requires adapter kits and pressure derating analysis to interface with modern 15,000-psi stimulation designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Completion Equipment and Services Market |
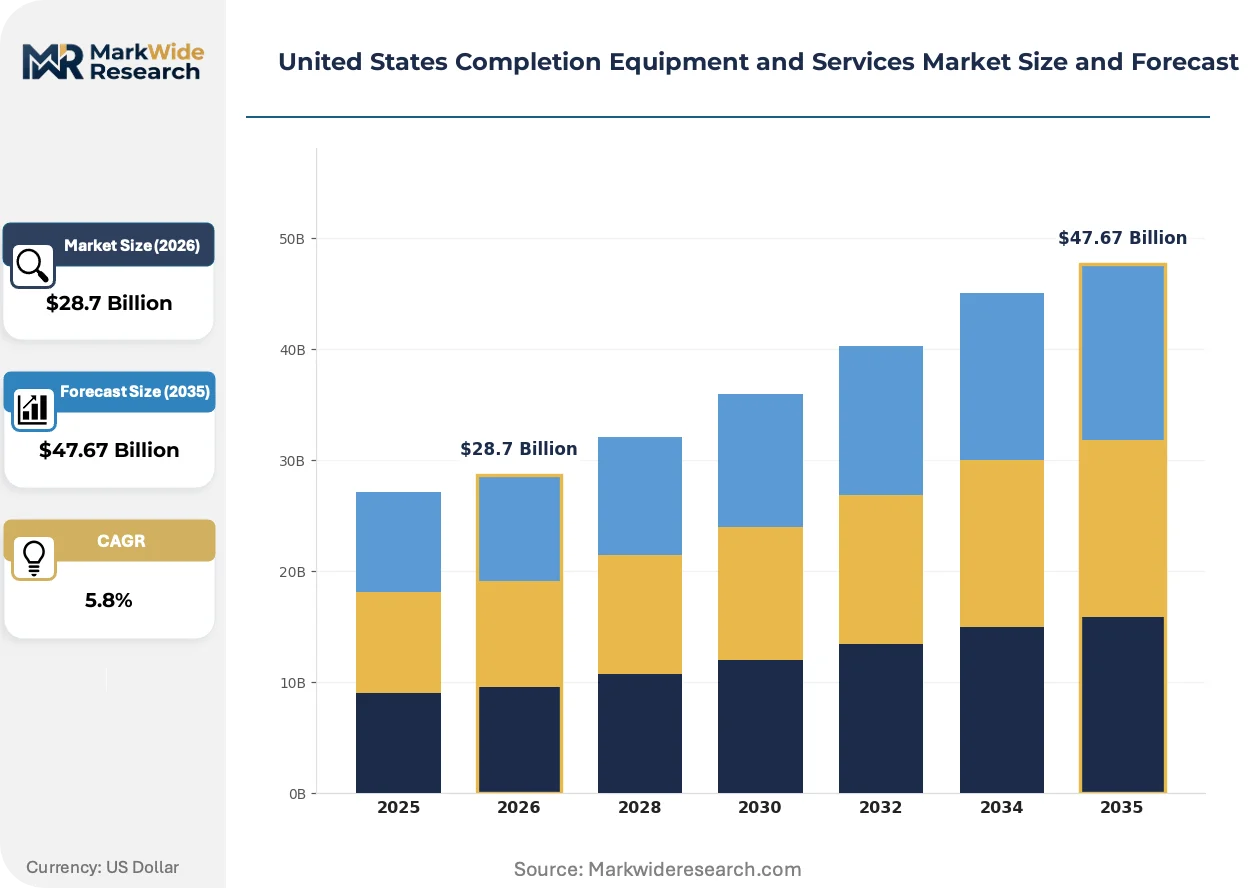
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wellheads, Production Tree, Tubing, Packer Service Type: Coiled Tubing, Cementing, Stimulation, Wireline End User: Onshore Operators, Offshore Operators, Independents, NOCs Application: Oil Production, Gas Production, Geothermal, Enhanced Oil Recovery |
| Companies Covered | Schlumberger Ltd, Halliburton Company, Baker Hughes Company, Weatherford International plc, National-Oilwell Varco Inc, Schoeller-Bleckmann Oilfield Equipment AG, Packers Plus Energy Services Inc, Superior Energy Services Inc, Trican Well Service Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Completion Equipment and Services Market Evolving Landscape
Digital instrumentation and modular hardware architectures are compressing the traditional boundary between downhole tools and surface control systems in unconventional completions.
Wireless frac plug activation is decentralizing perforating operations by eliminating wireline runs between stages. Permian operators with 50-plus stage wells adopt this technology to reduce flat time and crew exposure. The shift compresses day rates for traditional wireline providers while expanding the addressable market for battery-powered downhole tools.
EPA methane detection and repair mandates under the Clean Air Act are forcing real-time emissions monitoring integration into wellhead and production tree specifications. Operators in the Permian and Bakken must deploy continuous monitoring hardware to avoid enforcement actions. Equipment vendors respond by embedding sensor arrays directly into flange connections and valve actuators.
Integrated service contracting is consolidating procurement decisions as E&P companies reduce vendor counts to simplify logistics and liability management. Supermajors and large independents now bundle stimulation, coiled tubing, and wellhead installation under single-source agreements. This concentration is most visible in Texas and New Mexico, where multi-well pad development favors coordinated crew scheduling over discrete service bidding.
United States Completion Equipment and Services Market Segmentation
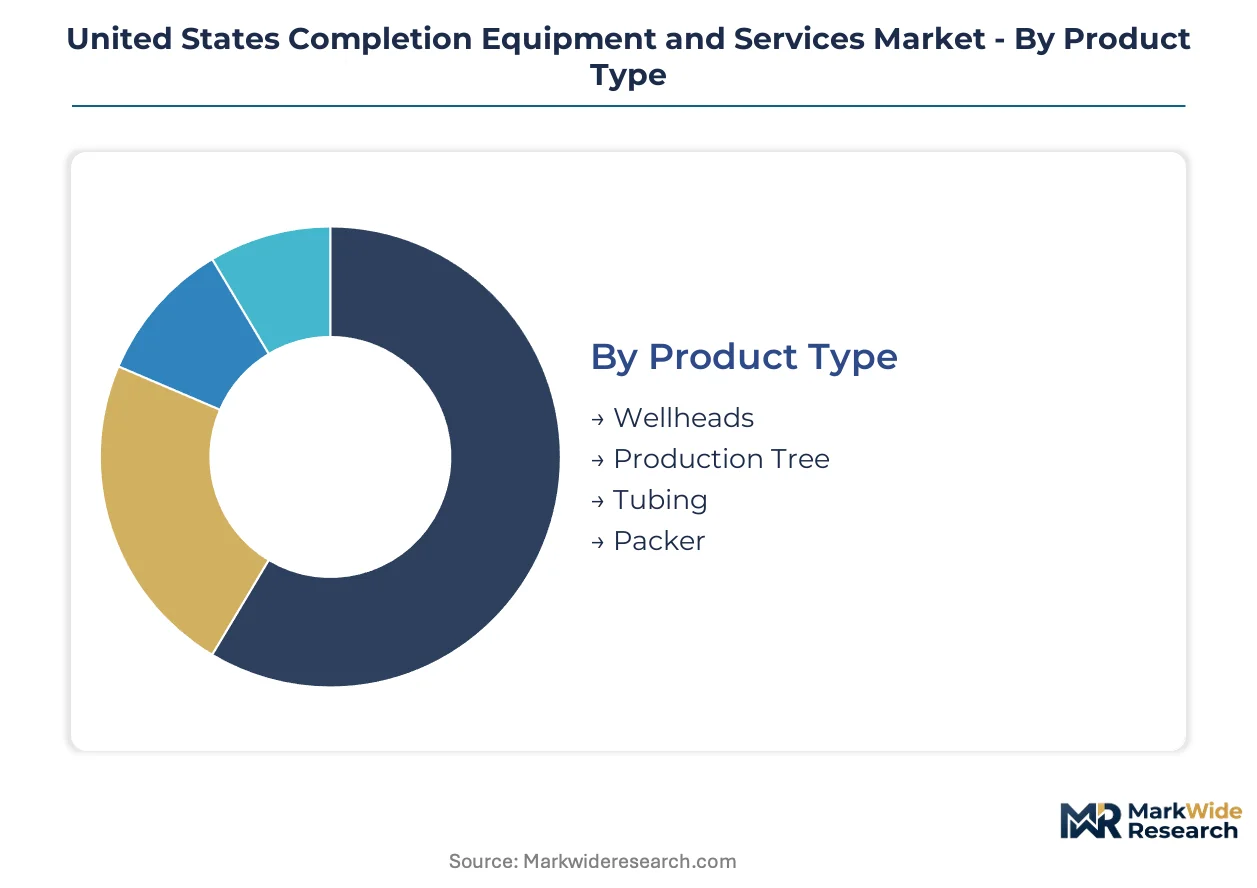
Completion equipment procurement in the United States follows distinct technical and commercial logics across product hardware, intervention services, operator categories, and production applications. Understanding these segment boundaries clarifies where capital deployment concentrates and where margin compression threatens.
Product Type:
Replacement cycles dominate hardware procurement as EPA methane rules and higher-pressure stimulation designs force upgrades across installed bases.
- Wellheads:Surface and subsea wellheads rated to 20,000 psi anchor well integrity systems. Demand concentrates in Permian Basin multi-well pads where 15,000-psi stimulation programs outstrip 10,000-psi legacy ratings, compelling replacement of 2010-2015 vintages.
- Production Tree:Valve assemblies controlling flow from wellhead to gathering lines integrate choke mechanisms and pressure monitoring. Texas and New Mexico operators prioritize compact configurations that reduce surface footprint on crowded pads.
- Tubing:Chromium-molybdenum alloy production strings withstand corrosive high-pressure environments. Procurement timelines extend under Texas Railroad Commission casing mandates for deep Delaware Basin horizontals.
- Packer:Zonal isolation tools enable selective stimulation and production management. Consumption multiplies with extended lateral lengths beyond 15,000 feet requiring 50-plus frac stages.
Wellheads sit at the top of the volume ranking, with packers climbing the fastest as stage counts proliferate.
Service Type:
Service margins diverge sharply based on technical specialization barriers and crew availability constraints.
- Stimulation:Multi-stage hydraulic fracturing consumes the largest share of completion budgets. Permian operators extending lateral lengths drive consumption of frac plugs, perforating guns, and high-pressure pumping spreads.
- Coiled Tubing:Continuous steel tubing deployed for well intervention and refrac programs accelerates fastest in maturing Bakken wells entering second production cycles. OSHA pressure-testing protocols differentiate certified providers.
- Cementing:Casing cementation ensures zonal isolation and well integrity per Texas Railroad Commission specifications. Activity correlates with drilling permits in Lea and Eddy counties.
- Wireline:Electric cable services deploy perforating guns and logging tools. Wireless frac plug activation is displacing traditional wireline runs between stages, compressing day rates.
Stimulation commands the steepest revenue concentration, while coiled tubing gains share fastest through refrac maturation.
End User:
Procurement scale and technical sophistication separate operator categories in equipment sourcing decisions.
- Onshore Operators:Unconventional shale developers in Texas, New Mexico, and North Dakota drive equipment intensity through multi-well pad development and extended-reach horizontals.
- Independents:Mid-size producers favor discrete service bidding over integrated packages, maintaining flexibility across volatile commodity cycles.
- Offshore Operators:Gulf of Mexico developments require subsea-rated production trees and high-pressure wellheads with remote monitoring capabilities.
- NOCs:State-affiliated producers maintain steady, specification-heavy procurement through long-term supply agreements.
Onshore operators dominate equipment consumption volume, with independents expanding most quickly through Permian acreage consolidation.
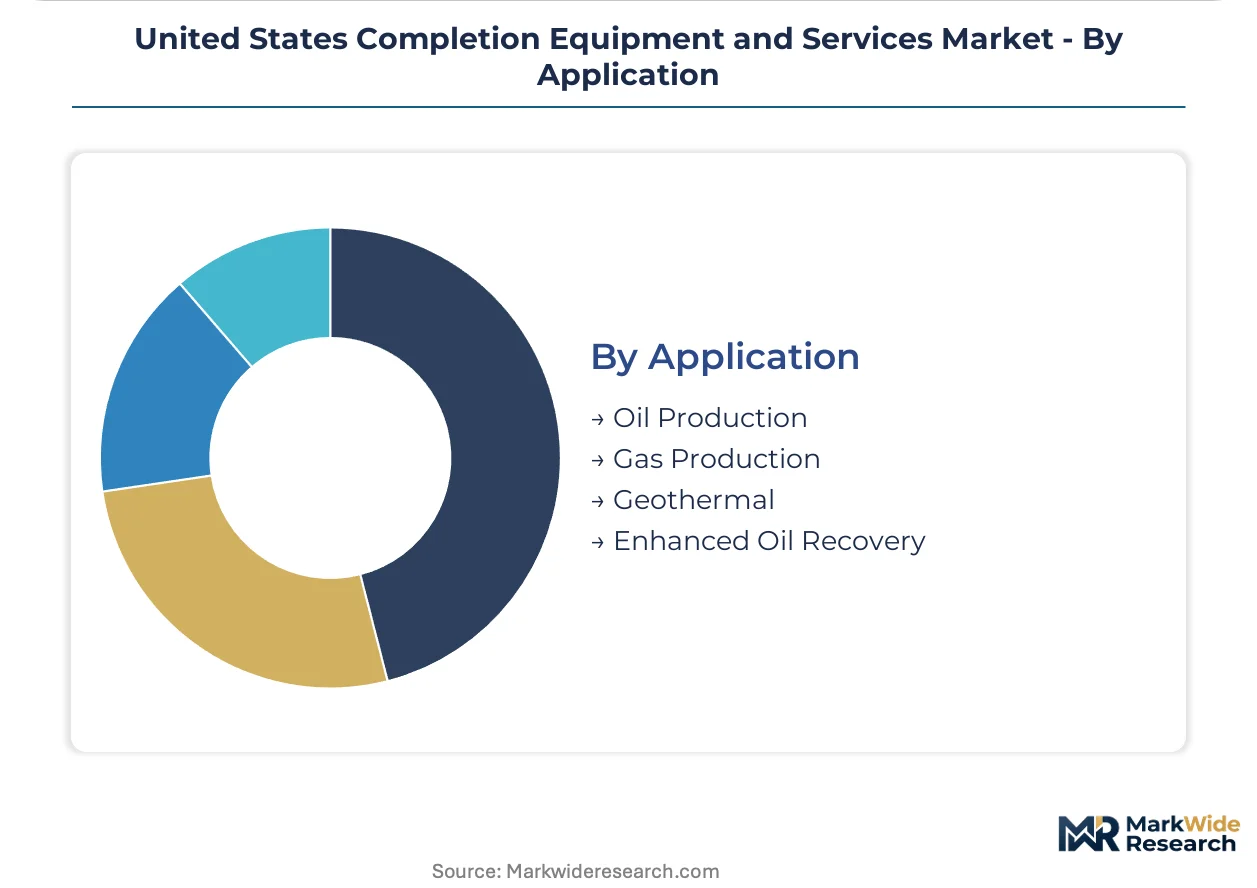
Application:
Production chemistry and reservoir characteristics dictate completion hardware specifications and service intensity.
- Oil Production:Light tight oil in Permian and Bakken formations drives the highest completion intensity per well, with extended laterals and dense frac stage spacing.
- Gas Production:Dry gas developments in Appalachia and Haynesville prioritize low-leakage wellheads and continuous methane monitoring to satisfy EPA Clean Air Act enforcement.
- Enhanced Oil Recovery:CO2 and waterflood conversions in mature Texas fields require recompletion with packers and tubing suited for corrosive injection environments.
- Geothermal:Emerging applications in Nevada and Utah adapt oilfield completion technologies for high-temperature, high-pressure geothermal production.
Oil production anchors equipment demand by volume, with geothermal expanding most quickly from negligible base as permitting accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized frac crews and coiled tubing technicians cluster in the Permian Basin and Williston Basin, creating tight labor markets that constrain service capacity expansion across the major shale plays.
Texas
Multi-well pad development in the Permian's Midland and Delaware sub-basins consumes the highest density of high-pressure wellheads and packer systems. The Texas Railroad Commission mandates casing and cementing specifications that extend procurement timelines for deep horizontal wells. Midland-Odessa anchors the largest concentration of stimulation service providers, with integrated contracting now dominating Lea County-adjacent acreage.
New Mexico
Lea and Eddy counties host underdeveloped Permian acreage where extended-reach laterals drive 50-plus stage completion intensity. The New Mexico Environment Department enforces methane capture requirements that compel low-leakage wellhead retrofits. Hobbs and Carlsbad form the primary logistics corridor for cross-border equipment movements from Midland-based service centers.
North Dakota
Maturing Bakken wells entering refrac cycles generate accelerating demand for coiled tubing intervention and zonal isolation services. The North Dakota Industrial Commission regulates hydraulic fracturing through chemical disclosure and well integrity rules. Williston Basin operators concentrate in McKenzie and Dunn counties, where vintage 2010-2015 wellheads require pressure derating analysis for modern stimulation designs.
Oklahoma
Stack and Scoop play operators deploy multi-stage completions in the Anadarko Basin despite compressed drilling economics. The Oklahoma Corporation Commission oversees induced seismicity protocols that shape frac scheduling and pressure limitations. Kingfisher and Canadian counties host the densest concentration of stacked-pay laterals targeting Meramec and Woodford formations.
Colorado
Niobrara and Codell formation development in the Denver-Julesburg Basin requires high-pressure completion hardware for overpressured zones. The Colorado Oil and Gas Conservation Commission enforces setback rules and flowline regulations that influence pad design and surface equipment specifications. Weld County maintains the highest completion activity level, with operators balancing urban interface constraints against lateral length economics.
United States Completion Equipment and Services Market Competitive Landscape
Top-tier vendors anchor integrated service contracting, while mid-tier specialists compete on discrete intervention capabilities. The vendor base stratifies across three tiers: full-service oilfield service companies with bundled offerings, regional specialists with basin-specific expertise, and equipment fabricators focused on discrete hardware categories. Strategic archetypes include technology licensors monetizing proprietary frac plug designs, integrated providers capturing multi-service contracts, and pure-play intervention companies scaling coiled tubing fleets. M&A activity concentrates on tuck-in acquisitions of regional pressure pumping assets, while organic expansion targets certified maintenance facilities for OSHA compliance differentiation.
Within the full-service tier, Schlumberger Ltd, Halliburton Company, and Baker Hughes Company exemplify the integrated model dominating Permian and Bakken contracting. These Houston-based entities occupy positions as default service providers for supermajors and large independents bundling stimulation, wellhead installation, and digital monitoring platforms. Their scale enables captive supply chains for high-pressure forgings and chromium-molybdenum tubing that smaller competitors must source through third-party distributors.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| National-Oilwell Varco Inc |
| Schoeller-Bleckmann Oilfield Equipment AG |
| Packers Plus Energy Services Inc |
| Superior Energy Services Inc |
| Trican Well Service Ltd |
| Others |
Value Network & Pricing Analysis
Wireless frac plug activation compressing wireline day rates simultaneously concentrates procurement power among integrated service providers and fragments pricing leverage for discrete equipment vendors. This technology shift rewards bundled contracting while penalizing standalone hardware suppliers.
Pricing Analysis
Bundled-versus-unbundled service contracting splits pricing power across the United States Completion Equipment and Services Market. Integrated packages spanning stimulation, wellhead installation, and digital monitoring command premium positioning against discrete service bidding. Price differentiation rests on OSHA certification tier and captive chromium-molybdenum tubing supply. Cost compression in commodity wellhead replacements intensifies as EPA methane rules force hardware retrofits. Independents operating onshore shale plays exhibit highest price sensitivity; supermajors bundling multi-well pad contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with South African and Kazakh chromium-molybdenum mining concentration for high-pressure tubing and forging feedstock. Manufacturing of 20,000-psi wellhead forgings draws from United States, Germany, and Japan. Raw material dependencies encompass chromium, molybdenum, and specialized nickel alloys. Tariff exposure on alloy imports presents structural risk. Distribution runs through Midland-Odessa and Hobbs-Carlsbad logistics corridors serving Permian Basin operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Completion Equipment and Services Market functions as a stable compounder where EPA methane enforcement generates replacement-driven revenue visibility regardless of drilling cycle volatility.
For Market Incumbents: To counter wireless frac plug displacement of traditional wireline runs, Halliburton Company and Baker Hughes Company should deepen captive supply chains for high-pressure forgings while embedding continuous methane monitoring sensors into wellhead flange connections as standard specification. For New Entrants and Emerging Players: Mid-tier independents in the Delaware Basin represent underserved buyer archetype seeking discrete cementing and coiled tubing services outside integrated packages. White-space concentration appears in OSHA-certified maintenance facilities for pressure-testing differentiation. Go-to-market angle targets Lea County multi-well pads with certified crew guarantees. For Investors and Strategic Acquirers: Valuations sit cheapest among regional pressure pumping specialists with basin-specific expertise but lacking digital platform integration. Long-term viability frames around electrification substitution risk and refrac maturation tailwinds. Acquisition target archetype encompasses coiled tubing fleets with Bakken refrac exposure. Signal to watch is Texas Railroad Commission seismicity rule tightening affecting frac scheduling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Bundling stimulation, wellhead, and digital monitoring reduces vendor count for Permian supermajors. |
| Wireless Frac Plug Deployment | Battery-powered downhole tools eliminate wireline runs between stages in 50-plus stage wells. |
| OSHA Certification Investment | Certified maintenance facilities create service differentiation for coiled tubing pressure-testing protocols. |
| Captive Alloy Supply Integration | Upstream control over chromium-molybdenum tubing secures margin against South African mining volatility. |
| Methane Sensor Embedding | Continuous emissions monitoring hardware integrated into wellhead specifications satisfies EPA Clean Air Act enforcement. |
Research Methodology
Direct dialogue with frac crew supervisors, wireline engineers, E&P procurement managers, and coiled tubing operations directors grounded qualitative findings in operational reality. Secondary validation drew from EPA enforcement databases, Texas Railroad Commission permitting records, EIA drilling productivity reports, and OSHA inspection summaries. Bottom-up equipment consumption modeling triangulated against top-down operator capital expenditure disclosures.
Segment-level value outputs across the projection horizon reflect equipment intensity per lateral foot, stage count proliferation, and replacement cycle acceleration from regulatory retrofit mandates. Segmentation dimensions encompassed product hardware, intervention service type, operator category, and production application. CAGRs derived from regression against historical drilling permit trajectories and stimulation design evolution. Forecast inputs included Permian Basin lateral length extension curves and Bakken refrac inventory maturation.
Underlying measurement precision varies by segment; stimulation services and wellhead hardware carry tighter precision than emerging geothermal applications. Forecasts reflect assumptions around EPA methane rule enforcement continuity and Texas Railroad Commission casing specification stability. Commodity price volatility, seismicity-induced frac moratoria, and electrification substitution present revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Piling Machine Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Boom Cranes Market
Construction Equipment
Piles Turner Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Crane Aftermarket Market