
 Global Portable Light Towers Market | 2026-2036
Global Portable Light Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Light Towers Market Outlook
Multi-source procurement among rental fleet operators is expanding as contractors seek supply resilience across volatile engine and LED component markets. Atlas Copco AB leverages its manufacturing scale to anchor European distribution networks for towable diesel-hybrid units. Generac Power Systems competes through vertical integration into alternator and enclosure production, while Wacker Neuson SE specializes in compact, road-towable designs for urban construction zones.
Portable light towers are self-contained mobile illumination systems typically mounted on telescopic masts reaching 30 feet, powered by diesel generators, battery packs, or solar arrays, and designed to deliver 4,000 to 20,000+ lumens across temporary work sites. LED product types now dominate new unit sales due to lumen-per-watt efficiency gains and 50,000-hour operational lifespans that compress total cost of ownership. Diesel end user demand within mining and remote construction remains structurally entrenched where grid access is absent, though hybrid power source configurations are capturing the fastest growth as fuel cost volatility and emissions compliance intensify.
EPA Tier 4 Final standards and EU Stage V regulations are forcing diesel engine redesigns and catalytic after-treatment additions that add cost and weight to fuel-based portable light towers, compressing margins for smaller assemblers. OSHA workplace illumination requirements and ISO 8528 generator set standards further shape product certification pathways and market access conditions across North America and Europe. Stakeholders must monitor battery energy density improvements and solar panel efficiency gains that could accelerate displacement of conventional diesel architectures in medium-duty deployment applications.
Market Dynamics
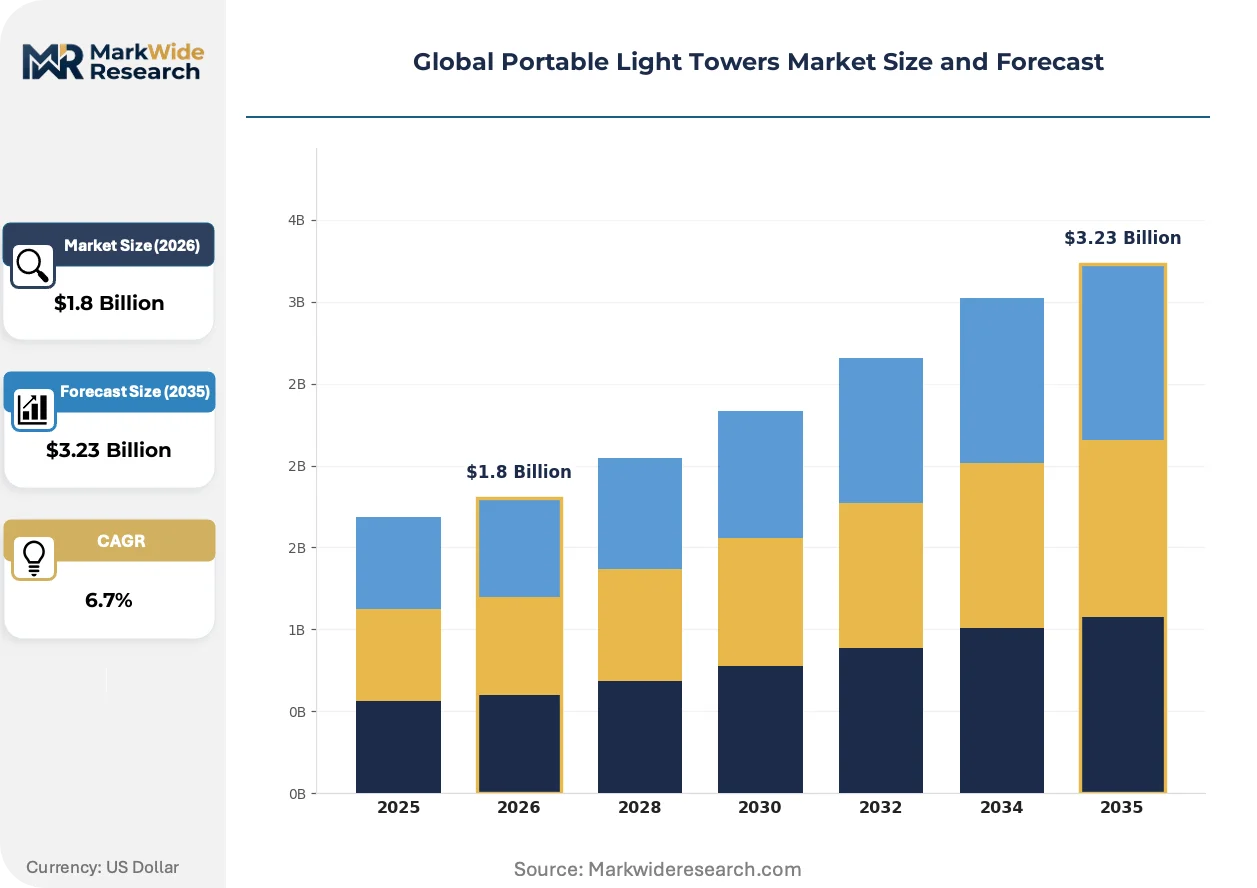
EPA Tier 4 Final and EU Stage V emissions mandates are compressing diesel equipment margins while battery energy density improvements accelerate hybrid architecture adoption across rental fleets.
Growth Catalysts
- Emissions Compliance Deadlines:EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe are forcing fleet operators to retire legacy diesel units ahead of schedule, creating replacement demand for cleaner alternatives.
- Mining Sector Expansion:Remote extraction operations in Australia and Canada require mobile illumination where grid infrastructure is absent, sustaining diesel-hybrid procurement despite electrification trends elsewhere.
- LED Lumen Efficiency:Solid-state lighting technology now delivers 150+ lumens per watt, cutting fuel consumption by 40 percent versus metal halide predecessors and shortening payback periods for capital-intensive upgrades.
Market Restraints
- Lithium-Ion Price Volatility:Battery cell costs fluctuate with cobalt and nickel spot markets, complicating total cost of ownership calculations for solar-battery hybrid configurations.
- After-Treatment Component Shortages:Diesel particulate filters and selective catalytic reduction systems face concentrated supplier bases in Germany and Japan, creating procurement bottlenecks for Tier 4 Final compliant engines.
- Solar Panel Efficiency Limits:Crystalline silicon conversion rates plateau near 22 percent in field conditions, constraining off-grid runtime for pure solar units during winter months at high latitudes.
Strategic Opportunities
- India Infrastructure Stimulus:National highway construction and smart city programs generate demand for towable lighting across states lacking reliable grid access, favoring diesel-solar hybrid architectures.
- Rental Channel Digitalization:Equipment-as-a-service platforms enable usage-based billing and predictive maintenance, capturing fleet operators seeking to outsource capital deployment and technical risk.
- EU Green Deal Alignment:Member state recovery funds prioritize zero-emission construction equipment, creating subsidy pools for battery-electric light tower procurement in Germany, France, and the Netherlands.
Industry Challenges
- Electrical Systems Integration:Technicians skilled in both diesel engine maintenance and high-voltage battery management remain scarce, lengthening service response times for hybrid fleets.
- Multi-Jurisdiction Certification:ISO 8528 generator compliance, CE marking, and OSHA workplace illumination standards impose overlapping testing requirements that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Light Towers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, Diesel, Hybrid, LED End User: Construction, Emergency Services, Mining, Events Power Source: Battery, Fuel-Based, Grid-Connected, Alternative Energy Deployment: Portable, Stationary, Towable, Fixed |
| Companies Covered | Doosan Portable Power, Larson Electronics LLC, Atlas Copco AB, Wanco Incorporated, JLG Industries, Generac Power Systems, Wacker Neuson SE, Jiangsu Ocean's King Lighting Science and Technology, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Light Towers Market Strategic Shifts
Solid-state power electronics and intelligent load management are reconfiguring how temporary illumination is deployed, financed, and serviced across construction and extractive industries.
Battery-solar hybrid architectures are decentralizing site power infrastructure by eliminating diesel fuel logistics and enabling silent operation modes. Remote mining contractors in Western Australia and oil sands operators in Alberta are adopting these configurations for 24-hour illumination cycles. The technology is decentralizing traditional rental fleet economics by shifting capital risk toward energy storage performance guarantees.
EU Stage V emission standards are mandating diesel particulate filters and selective catalytic reduction across all non-road mobile machinery above 19 kW. Engine manufacturers have responded with compact after-treatment packages that add 15-20 percent to unit weight and cost. Compact urban construction segments in Germany and the Netherlands are absorbing these premiums most acutely, accelerating interest in full electrification for sub-30 kW applications.
Rental fleet operators are consolidating supplier relationships around integrated power and illumination providers capable of delivering telematics-enabled uptime guarantees. Traditional equipment distributors face margin compression as direct manufacturer-to-fleet digital channels capture specification influence. This consolidation is most visible in the United States, where United Rentals and Sunbelt Rentals collectively influence North American procurement standards through volume commitment programs.
Global Portable Light Towers Market Segmentation
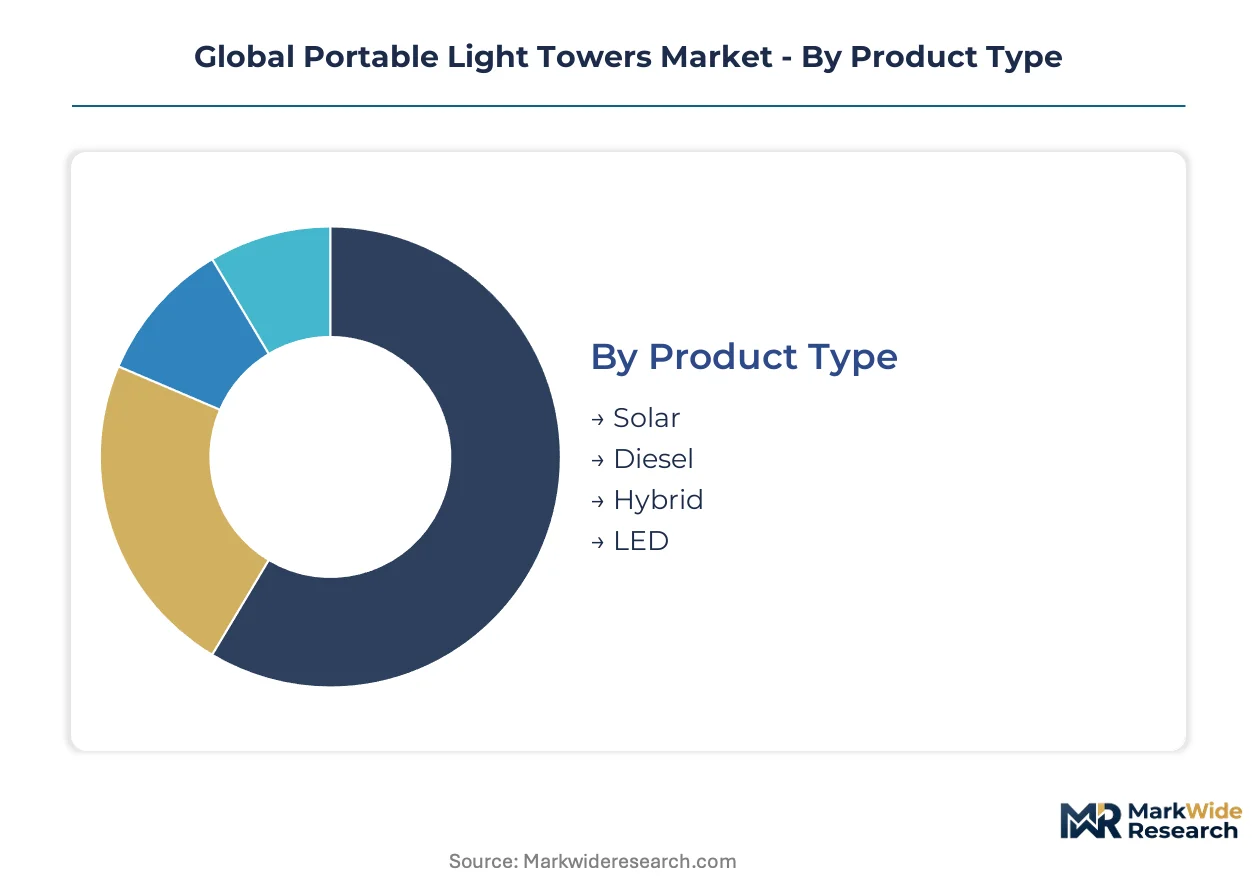
Portable light tower procurement splits across four intersecting dimensions: illumination technology, end-use environment, power architecture, and mobility configuration. These axes determine capital intensity, operating cost structure, and regulatory compliance burden for fleet operators and rental channels.
Product Type:
LED efficiency gains and solar-battery cost curves are reconfiguring the technology mix across construction and extractive applications.
- LED:Solid-state arrays delivering 150+ lumens per watt with 50,000-hour operational lifespans dominate new unit procurement in Germany, the United States, and Australia where infrastructure stimulus accelerates fleet replacement. Metal halide retrofits concentrate in developing markets with constrained capital budgets.
- Hybrid:Diesel-battery architectures capture expanding share in remote mining corridors of Western Australia and Alberta where 24-hour illumination cycles demand fuel security plus silent operation capability. Fuel cost volatility and EPA Tier 4 Final compliance costs accelerate adoption.
- Solar:Pure photovoltaic configurations serve seasonal construction and emergency response in sunbelt regions; crystalline silicon efficiency plateaus near 22 percent in field conditions, constraining winter runtime at high latitudes.
- Diesel:Conventional generator-powered units retain structural demand in grid-absent extraction sites across Canada and Chile; EU Stage V after-treatment requirements add 15-20 percent to unit weight and cost, compressing margins for smaller assemblers.
LED leads on scale; hybrid leads on momentum.
End User:
Application-specific illumination requirements drive divergent specifications for lumen output, runtime autonomy, and environmental protection ratings.
- Construction:Urban infrastructure projects in the Netherlands and Germany specify compact, road-towable units with sub-30 kW power draws; EU Green Deal recovery funds subsidize zero-emission alternatives.
- Mining:Remote extraction operations in Australia and Canada require diesel-hybrid resilience where fuel logistics dominate operating economics; 4,000 to 20,000+ lumen outputs cover pit and processing areas.
- Emergency Services:Rapid-deployment configurations prioritize telescopic mast deployment speed and battery-silent operation for disaster response in Japan and the United States; OSHA workplace illumination standards shape certification pathways.
- Events:Temporary entertainment and sports lighting in France and the United Kingdom favors grid-connected or battery units for noise-sensitive venues; rental channel procurement dominates with usage-based billing models.
Construction commands absolute volume; mining shows steepest expansion trajectory as commodity prices sustain capital deployment.
Power Source:
Energy storage chemistry and grid access availability determine total cost of ownership calculations across deployment scenarios.
- Fuel-Based:Diesel generators remain entrenched where grid infrastructure is absent; EPA Tier 4 Final and EU Stage V mandates force catalytic after-treatment redesigns that concentrate supplier relationships around German and Japanese component manufacturers.
- Battery:Lithium-ion configurations gain share in urban construction zones with charging infrastructure; cobalt and nickel price volatility complicates procurement planning for fleet operators.
- Alternative Energy:Solar-hybrid architectures eliminate fuel logistics for remote site operators in Western Australia; energy density improvements in solid-state batteries could accelerate displacement of conventional diesel in medium-duty applications.
- Grid-Connected:Stationary event lighting in metropolitan France and Germany leverages existing electrical infrastructure; lowest capital cost option where three-phase power is accessible.
Fuel-based retains installed base dominance; battery is climbing the fastest as energy density improves and charging infrastructure expands.
Deployment:
Mobility configuration determines transport logistics, site preparation requirements, and rental fleet utilization economics.
- Towable:Highway-legal trailers with hydraulic mast systems serve multi-site construction contractors across the United States and Germany; United Rentals and Sunbelt Rentals consolidate procurement standards through volume commitment programs.
- Portable:Skid-mounted or wheel-based units deploy in confined urban zones and underground mining operations; compact footprints accommodate road weight restrictions in European city centers.
- Stationary:Fixed installations serve semi-permanent mining camps and industrial facilities in Chile and Canada; lowest mobility premium but highest site preparation cost.
- Fixed:Permanent mast structures with integrated electrical feeds illuminate long-term extraction and processing sites; minimal relevance for temporary work site applications.
Towable captures rental channel volume; portable is gaining share fastest as urban construction density intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly capacity toward jurisdictions with lighter emissions compliance burdens, creating cost-of-compliance arbitrage between EPA Tier 4 Final jurisdictions and emerging production hubs. This migration pattern concentrates final assembly in lower-regulatory-cost environments while maintaining component sourcing from established precision-manufacturing clusters.
United States
Infrastructure stimulus programs and rental fleet renewal cycles drive diesel-hybrid procurement across Texas and California construction corridors. EPA Tier 4 Final compliance deadlines force early retirement of legacy metal halide units, compressing replacement timelines for contractors serving Department of Transportation highway projects. Oklahoma and North Dakota oil patch operators sustain demand for remote-deployment configurations where grid access remains absent.
Germany
EU Stage V after-treatment mandates add 15-20 percent to diesel unit production costs, accelerating interest in full electrification for urban construction zones in Bavaria and North Rhine-Westphalia. The country's national recovery fund prioritizes zero-emission construction equipment, creating subsidy pools for battery-electric procurement. Industrial clusters around Stuttgart and Munich concentrate LED component fabrication and generator set integration expertise.
Australia
Western Australia mining operators require 24-hour illumination cycles across pit and processing areas, sustaining diesel-hybrid demand despite electrification trends elsewhere. The country's workplace health and safety regulator mandates minimum lux levels across temporary work sites, shaping certification requirements for imported equipment. Perth-based rental channels consolidate procurement around telematics-enabled uptime guarantees for fly-in-fly-out operations.
India
National highway construction and smart city programs generate demand for towable lighting across Maharashtra and Gujarat where grid reliability varies seasonally. The country's Bureau of Indian Standards imposes electromagnetic compatibility testing on imported electrical equipment, creating technical barriers for non-compliant suppliers. Delhi-Mumbai Industrial Corridor projects favor diesel-solar hybrid architectures that eliminate fuel logistics for remote staging areas.
Canada
Alberta oil sands and British Columbia mining operations require mobile illumination resilient to temperature extremes and fuel supply disruptions. Environment and Climate Change Canada enforces increasingly stringent off-road diesel emissions standards, mirroring EPA Tier 4 Final stringency. Edmonton and Calgary serve as distribution hubs for equipment deployed across the Prairie Provinces and northern extraction territories.
Global Portable Light Towers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue solar-battery hybrid architectures and rental-channel digitalization. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive power equipment divisions, specialized lighting manufacturers with deep LED integration expertise, and rental fleet operators backward-integrating into specification influence. Dominant competitive moves include capacity consolidation through strategic partnerships and geographic expansion into infrastructure stimulus markets in India and Southeast Asia.
Among European-based industrial groups, Atlas Copco AB and Wacker Neuson SE exemplify divergent specialization paths within the portable illumination segment. Atlas Copco occupies a position anchored in manufacturing scale and distribution network density across continental Europe. Wacker Neuson represents the compact-equipment specialist archetype, with organizational heritage in road-towable designs for constrained urban environments. Doosan Portable Power anchors the Korean industrial conglomerate tier, sitting within a broader power equipment portfolio that spans generator sets and compressed air systems. These three entities collectively illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Doosan Portable Power |
| Larson Electronics LLC |
| Atlas Copco AB |
| Wanco Incorporated |
| JLG Industries |
| Generac Power Systems |
| Wacker Neuson SE |
| Jiangsu Ocean's King Lighting Science and Technology |
| Terex Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EPA Tier 4 Final compliant diesel-hybrid units and uncertified legacy equipment manifests in both pricing premiums and supply chain sourcing patterns. Fleet operators absorb tiered cost structures while manufacturers route component procurement through distinct supplier networks based on emissions compliance requirements.
Pricing Analysis
Distributor margins on rental channel sales compress as United Rentals and Sunbelt Rentals consolidate volume commitment programs across North American procurement. Three-tier pricing structure across premium, standard, and economy levels reflects LED lumen output, telematics integration depth, and after-treatment certification status. Pricing pressure stems from lithium-ion cell cost volatility and catalytic component shortages. Small construction contractors exhibit highest price sensitivity; mining operators demonstrate lowest sensitivity due to fuel logistics dominance in total cost calculations.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns for diesel engines, LED arrays, and battery pack assembly. Diesel particulate filters and selective catalytic reduction systems draw from concentrated German and Japanese supplier bases. Single-source vulnerability concentrates around cobalt and nickel feedstocks for lithium-ion configurations. Distribution runs through rental fleet operators and specialized equipment distributors rather than direct manufacturer-to-site channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost differentials between EPA Tier 4 Final jurisdictions and lighter regulatory environments create geographic-arbitrage opportunities for assembly relocation. EU Stage V compliance burdens in Germany and the Netherlands accelerate interest in sourcing from lower-regulatory-cost production hubs.
For Market Incumbents: To counter emerging solar-battery hybrid specialists, Atlas Copco AB and Generac Power Systems should deepen backward integration into alternator and enclosure production while anchoring European distribution networks. Captive supply of LED driver electronics and generator set components defends margin position against smaller assemblers facing after-treatment cost compression.
For New Entrants and Emerging Players: The premium-to-economy price gap in Indian highway construction and smart city programs offers white-space entry through diesel-solar hybrid architectures. Target Maharashtra and Gujarat states lacking reliable grid access. Pursue Bureau of Indian Standards electromagnetic compatibility certification as a technical barrier moat against non-compliant imports.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU Green Deal subsidy pools concentrate procurement influence among telematics-enabled fleet operators. Five-to-ten year viability favors acquisition targets with integrated power and illumination capabilities plus digital channel relationships. Monitor battery energy density improvement curves as inflection signal for diesel displacement velocity in medium-duty applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternator Production | Generac Power Systems captures margin from captive supply while reducing Tier 4 Final component exposure. |
| Solar-Battery Hybrid Architecture Development | Western Australia mining contractors eliminate fuel logistics costs through 24-hour silent operation capability. |
| Telematics-Enabled Uptime Guarantee Programs | Perth-based rental channels consolidate procurement around predictive maintenance for fly-in-fly-out operations. |
| EU Green Deal Subsidy Alignment | German and Dutch fleet operators access recovery fund pools for zero-emission battery-electric procurement. |
| India Bureau of Standards Certification Investment | Compliant suppliers secure technical barrier protection across Delhi-Mumbai Industrial Corridor projects. |
Study Parameters
Bottom-up construction and mining end-use modeling reconciled against top-down diesel engine and LED component supply tracking forms the analytical core. Primary interviews with rental fleet procurement directors, mining maintenance supervisors, construction project managers, and aftermarket service heads combined with secondary validation from EPA enforcement databases, EU Stage V type-approval registries, and customs trade records. Top-down and bottom-up triangulation ensures segmentation integrity across power source and illumination technology dimensions.
Input-output matrices project unit shipments and revenue across the analysis window by intersecting product type, end user, power architecture, and mobility configuration. CAGRs derive from regression analysis against infrastructure stimulus disbursement timelines and mining capital expenditure cycles. Forecast inputs include lithium-ion cell cost curves and solar panel efficiency improvement trajectories.
Caveats apply where battery chemistry breakthroughs or emissions regulation delays could materially shift the outlook. Forecasts reflect documented assumptions regarding EPA Tier 4 Final enforcement stringency and EU Green Deal subsidy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Baler Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Cranes Rental Market