
 France Prefab Homes Market | 2026-2036
France Prefab Homes Market Size, Share, and Industry Trends Forecast 2026-2036
France Prefab Homes Market Insights
Green leasing and project-finance vehicles are reshaping how prefab developers fund large-scale residential rollouts in France. Bouygues Construction leverages its captive financing arm to anchor turnkey modular contracts with social-housing operators. Hexaom sustains competitive positioning through vertical control over timber sourcing and panel fabrication in western France. Cougnaud Construction specializes in single-storey rural dwellings, occupying a defensible niche outside major urban corridors.
France prefab homes are factory-built residential structures assembled from standardized or customized modules, typically incorporating engineered wood frames, steel skeletons, or precast concrete panels with thermal performance ratings calibrated to RE2020 thresholds. Their primary purpose is to compress construction timelines while meeting stringent energy-efficiency mandates for permanent or semi-permanent housing. Modular units command the strongest margin pools due to customization premiums and repeatability at scale, while off-site construction dominates deployment volumes by minimizing weather delays and site labor costs. Mobile homes remain the most mature product type, with growth concentrating in multi-storey modular systems for dense urban infill.
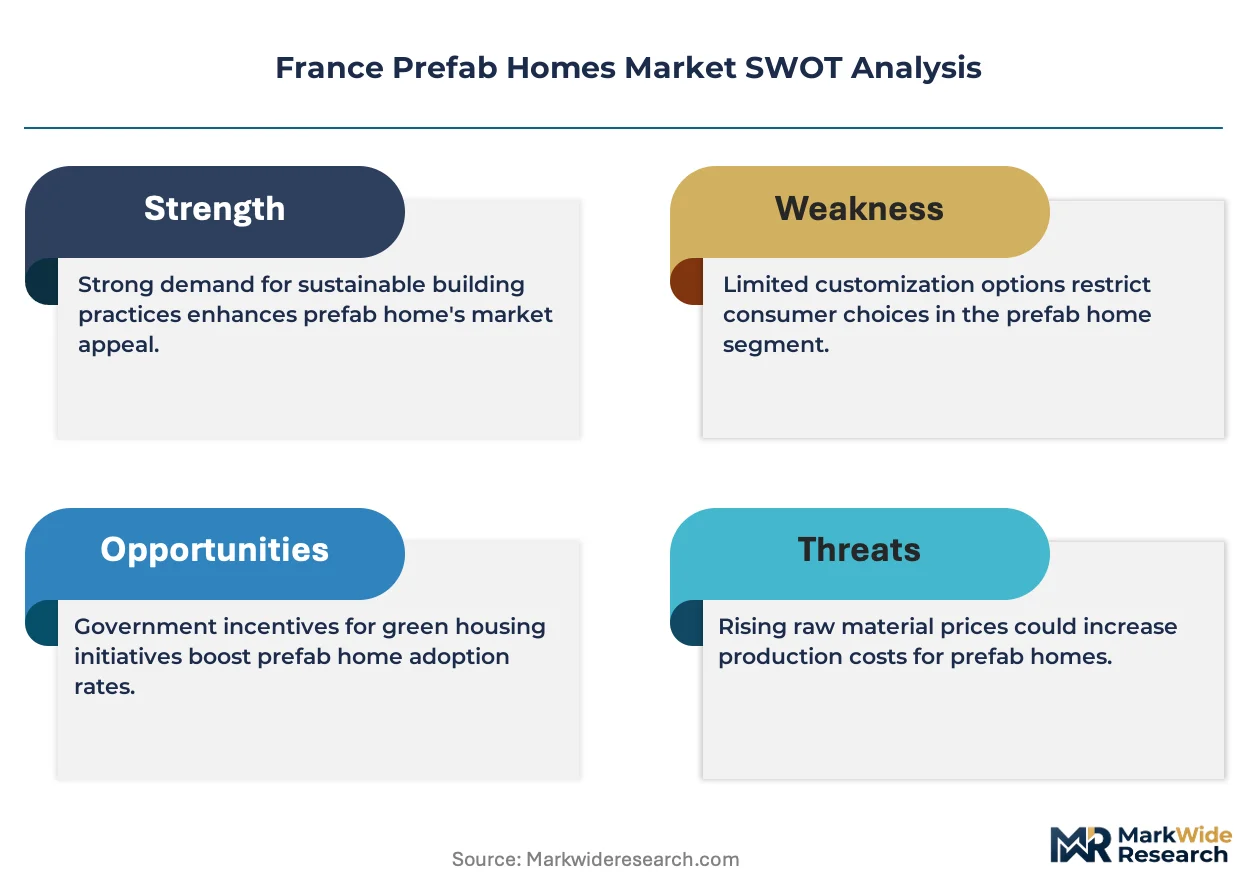
ANAH, the French national housing agency, channels subsidies toward low-carbon prefab builds, directly steering developer portfolios toward timber and composite material lines. RE2020 and the broader EU Green Deal framework tighten embodied-carbon limits, forcing material substitutions and supply-chain certification upgrades across the sector. CSRD disclosure requirements will soon extend to mid-cap construction firms, raising compliance stakes for prefab manufacturers serving institutional buyers. Stakeholders must monitor how rapidly local planning authorities relax height and density restrictions for factory-built multi-storey housing in France's constrained urban zones.
Market Dynamics
RE2020's tightening energy-performance thresholds are compressing construction timelines and forcing material substitutions across French prefab manufacturing, while municipal procurement in Île-de-France accelerates demand for multi-storey modular systems.
Growth Catalysts
- ANAH subsidy channels:The French national housing agency directs capital toward low-carbon timber and composite builds, steering developer portfolios away from conventional concrete-intensive methods.
- Île-de-France municipal procurement:Social-housing operators in the Paris basin are expanding turnkey modular contracts to address chronic supply shortages in constrained urban zones.
- Timber-frame cluster formation:Manufacturing concentration around Pau and Toulouse in Occitanie creates localized supply advantages for engineered wood systems.
Market Restraints
- Embodied-carbon certification costs:RE2020 and EU Green Deal compliance requires supply-chain documentation upgrades that raise input costs for mid-cap fabricators.
- Skilled installation labor scarcity:Factory-built modules require specialized crane crews and assembly technicians concentrated in only three French regions.
- Height restriction friction:Local planning authorities in dense urban cores maintain conservative density limits that constrain multi-storey modular deployment.
Strategic Opportunities
- Rural single-storey white space:Cougnaud Construction's niche positioning outside major corridors demonstrates underexploited demand for affordable rural dwellings in Nouvelle-Aquitaine and Brittany.
- CSRD disclosure preparation:Upcoming corporate sustainability reporting requirements create first-mover advantages for prefab manufacturers serving institutional buyers with pre-certified carbon accounting.
- Green leasing convergence:Project-finance vehicles linking factory output to long-term municipal leases offer alternative capital structures beyond traditional construction lending.
Industry Challenges
- Cross-trade coordination complexity:Modular delivery requires precise sequencing between factory fabrication, transport logistics, and site preparation that few general contractors have mastered.
- RE2020 thermal-bridge compliance:Panel-to-panel junction detailing demands computational modeling capabilities that smaller fabricators lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Prefab Homes Market |
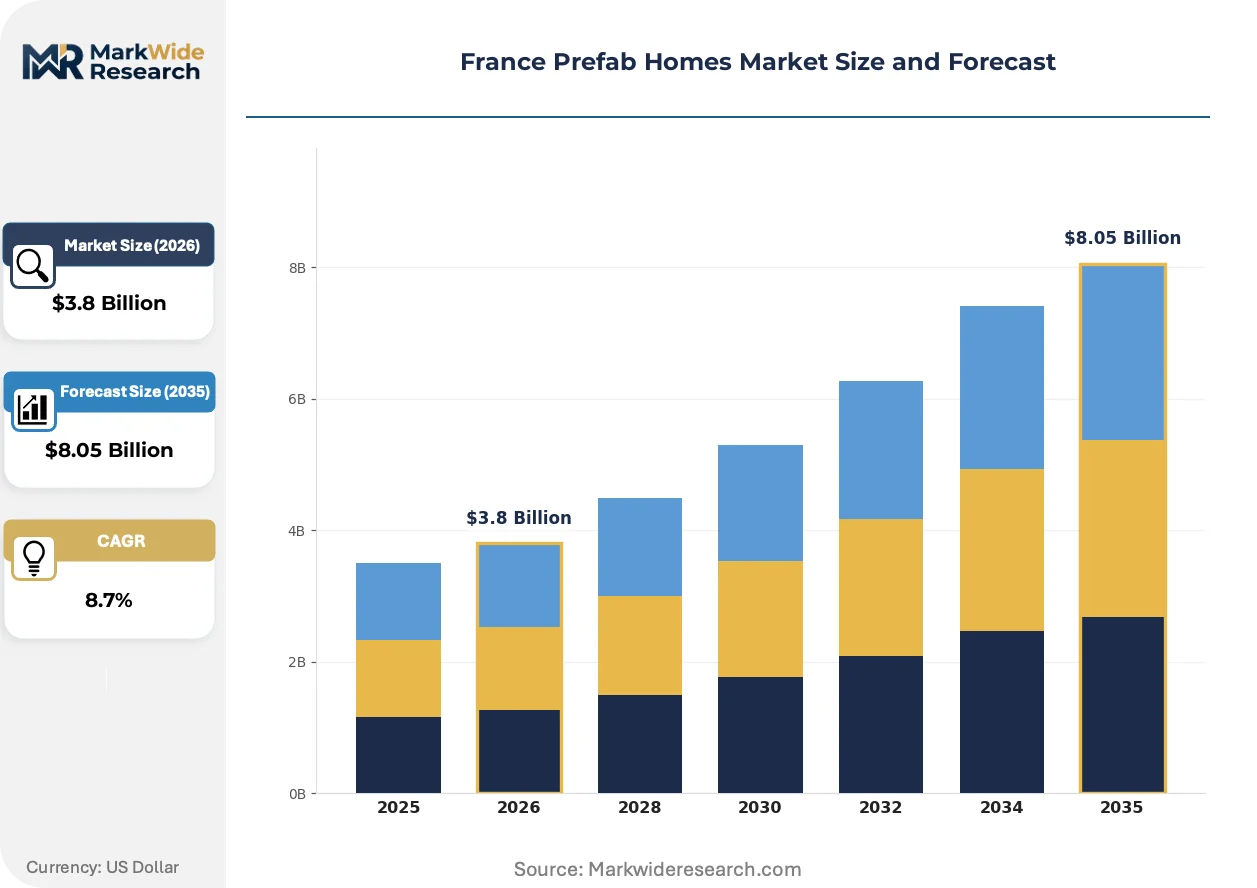
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Storey, Multi-Storey, Modular Units, Mobile Homes End User: Individual Buyers, Real Estate Developers, Government Projects, Rental Agencies Deployment: On-Site Construction, Off-Site Construction, Hybrid Systems, Custom Builds Material: Wood, Steel, Concrete, Composite Materials |
| Companies Covered | Cougnaud Construction, OBM Construction, Bouygues Construction, Hexaom, Bonhomme Bâtiment, VINCI Construction, Bodard Construction, MARC SA, Eiffage Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Prefab Homes Market Trends and Innovations
Digital fabrication and regulatory disclosure requirements are converging to reshape how French prefab manufacturers design, certify, and finance residential modules. Three developments merit close attention.
Building information modeling integrated with automated panel-cutting machinery is digitizing the transition from architectural drawings to factory floor instructions. Social-housing operators in Lyon and Marseille are requiring BIM deliverables as contract preconditions. This compression of design-to-production workflows is eliminating traditional shop-drawing bottlenecks that previously added weeks to project schedules.
CSRD disclosure mandates will extend sustainability reporting obligations to mid-cap construction firms serving institutional buyers. The regulation forces granular tracking of embodied carbon across engineered wood, steel, and precast concrete supply chains. Prefab manufacturers with pre-certified environmental product declarations are capturing preferential procurement status from ANAH-subsidized developments.
Municipal buyers are consolidating vendor relationships around turnkey performance contracts that bundle design, fabrication, installation, and twenty-year energy guarantees. This displaces fragmented procurement across separate architectural, engineering, and contracting entities. The shift is most visible in Île-de-France, where housing authorities favor single-point accountability for delivery timelines and thermal performance outcomes.
France Prefab Homes Market Segmentation
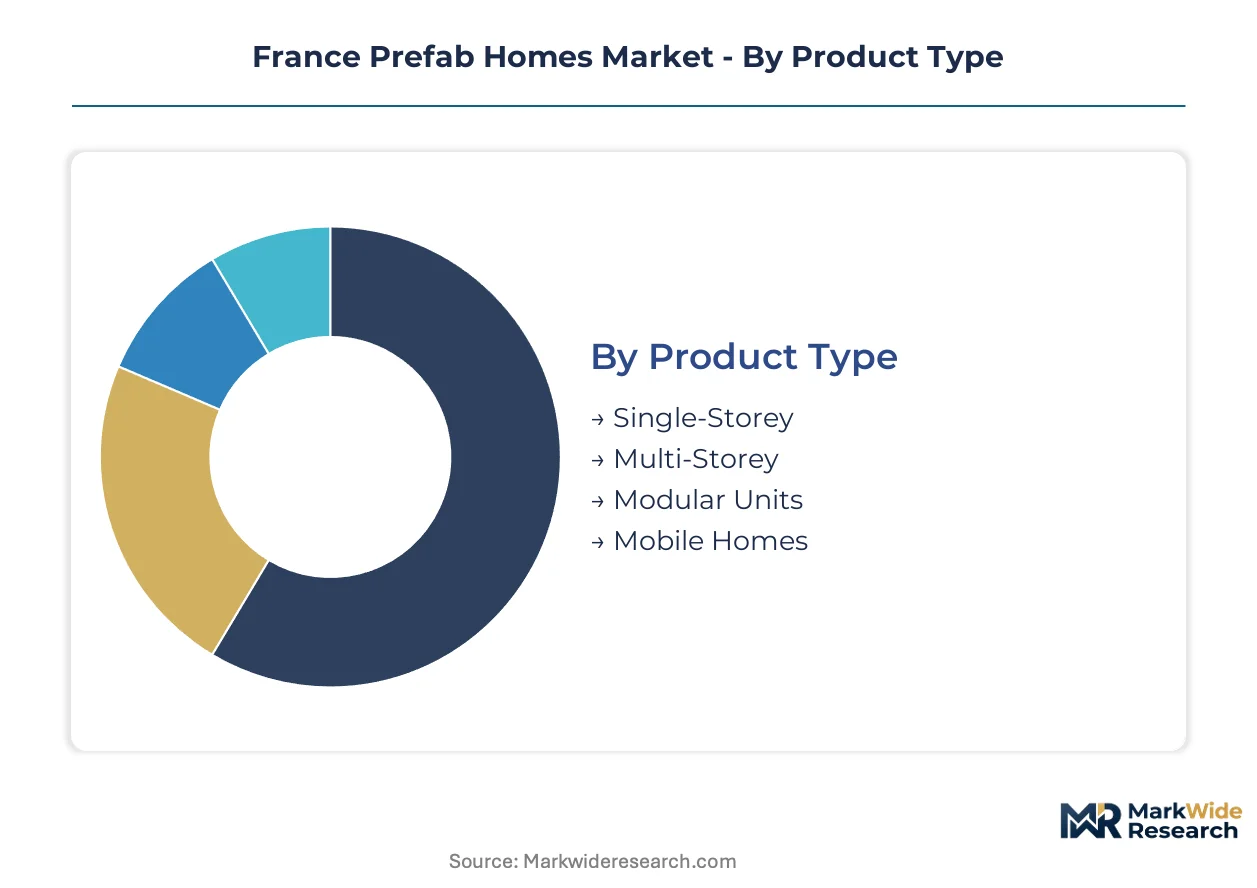
Segmentation in the France prefab homes market reveals how RE2020 compliance pressures and municipal procurement patterns concentrate value across distinct product architectures and buyer categories. Understanding these divisions exposes where margin pools form and which deployment modes scale under regulatory tightening.
Product Type:
Mature formats dominate current volumes while emerging multi-storey systems capture the fastest policy tailwinds.
- Multi-Storey:Factory-built vertical modules with steel-reinforced cores and RE2020-calibrated thermal envelopes. Municipal housing authorities in Île-de-France are accelerating procurement of these systems to address density constraints in Paris basin urban zones.
- Modular Units:Standardized volumetric segments assembled from engineered wood or composite panels, offering customization premiums alongside factory repeatability. ANAH subsidy channels steer social-housing operators toward timber-frame modular configurations for low-carbon compliance.
- Single-Storey:Ground-level prefabricated dwellings serving rural markets in Nouvelle-Aquitaine and Brittany.
- Mobile Homes:Transportable residential units on chassis foundations, the most mature product category with established deployment protocols.
Mobile homes handle the majority of throughput; multi-storey systems are expanding most quickly on share.
End User:
Procurement concentration varies sharply between institutional buyers with long-term lease structures and fragmented individual demand.
- Government Projects:Municipal housing authorities and ANAH-subsidized developments procuring turnkey modular contracts with twenty-year energy performance guarantees. RE2020 thresholds and CSRD disclosure requirements favor vendors with pre-certified carbon accounting.
- Real Estate Developers:Private firms integrating prefab modules into mixed-use residential portfolios, leveraging off-site construction to compress timelines on constrained urban infill sites.
- Rental Agencies:Institutional landlords seeking rapid deployment for social-housing stock expansion.
- Individual Buyers:Single-family purchasers of custom or semi-custom prefabricated dwellings, concentrated in rural and peri-urban zones.
Government projects anchor volume commitments; real estate developers are climbing the fastest on procurement sophistication.
Deployment:
Cost tier differentiation separates high-control factory environments from site-dependent hybrid approaches.
- Off-Site Construction:Complete module fabrication in controlled factory conditions before transport to prepared foundations. Manufacturing clusters around Pau and Toulouse in Occitanie create localized supply advantages for engineered wood systems delivered through this mode.
- Hybrid Systems:Partial factory prefabrication combined with on-site assembly, balancing customization flexibility with schedule compression.
- On-Site Construction:Traditional assembly of prefabricated components at the final location, subject to weather delays.
- Custom Builds:Bespoke architectural configurations requiring specialized design-to-production workflows and BIM integration.
Off-site construction commands the largest deployment share; hybrid systems are gaining share fastest as general contractors seek risk mitigation.
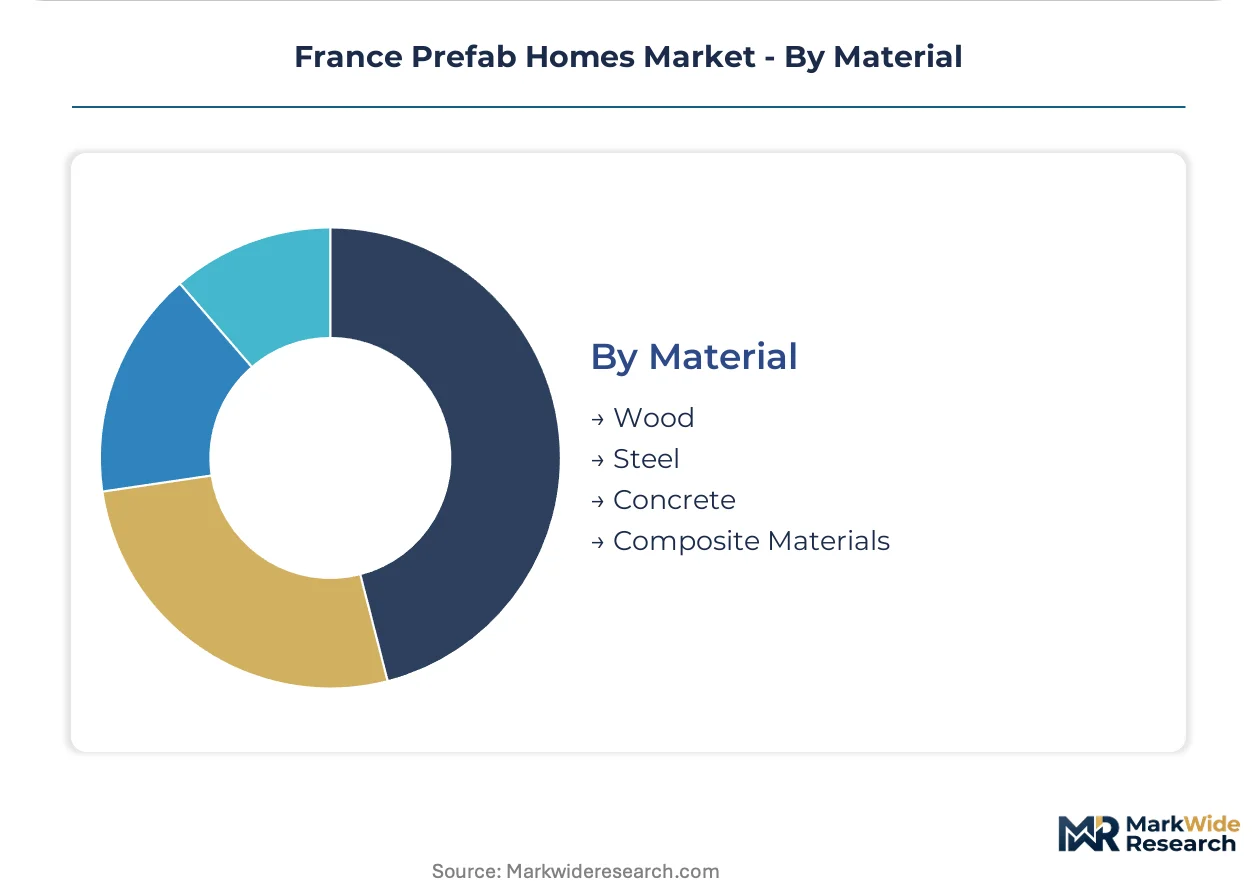
Material:
Supply concentration around specific geographies dictates regional competitive positioning.
- Wood:Engineered timber frames and cross-laminated panels, favored by ANAH subsidy channels for embodied-carbon advantages. Timber-frame manufacturing clusters in Occitanie provide upstream control over sourcing and panel fabrication.
- Composite Materials:Fiber-reinforced polymers and hybrid timber-composite systems offering thermal-bridge compliance without computational modeling capabilities required by smaller fabricators.
- Steel:Structural skeletons for multi-storey modular systems requiring seismic and wind-load resistance.
- Concrete:Precast panels for foundation and core elements, facing substitution pressure under EU Green Deal embodied-carbon limits.
Wood dominates current procurement volumes; composite materials are on the steepest expansion trajectory as RE2020 thermal-bridge compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's prefab homes sector operates as a net importer of engineered timber components from neighboring European markets, while exporting modular system designs to North African housing programs. This trade dynamic shapes regional supply configurations across metropolitan and rural deployment zones.
Île-de-France
Municipal housing authorities in the Paris basin are accelerating turnkey modular procurement to address chronic supply shortages in constrained urban zones. ANAH subsidy channels direct capital toward low-carbon timber builds meeting RE2020 thresholds. Manufacturing partners cluster around Le Bourget and Cergy-Pontoise to minimize transport logistics for multi-storey modules.
Occitanie
Timber-frame manufacturing concentration around Pau and Toulouse creates localized supply advantages for engineered wood systems. The region's forestry base supports backward integration into panel fabrication for social-housing operators. RE2020 compliance pressures favor composite material substitutions from suppliers anchored in this southwestern corridor.
Nouvelle-Aquitaine
Rural single-storey demand concentrates in peri-urban zones outside Bordeaux and Limoges where traditional construction labor remains scarce. Low-density planning codes accommodate ground-level prefab deployment without height restriction friction. Timber sourcing from the Landes forest provides embodied-carbon advantages for ANAH-subsidized developments.
Auvergne-Rhône-Alpes
Lyon and Grenoble housing authorities are requiring BIM deliverables as contract preconditions for modular projects. The region's engineering heritage supports digital fabrication integration with automated panel-cutting machinery. Seismic design requirements favor steel-reinforced cores for multi-storey systems deployed in Alpine foothill zones.
Hauts-de-France
Post-industrial regeneration zones around Lille are attracting hybrid construction approaches balancing customization flexibility with schedule compression. Cross-border supply relationships with Belgian fabricators supplement domestic timber panel capacity. CSRD disclosure preparation among mid-cap developers is creating first-mover advantages for pre-certified carbon accounting.
France Prefab Homes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper fabrication expertise. The vendor base organizes around three strategic archetypes: diversified construction conglomerates with captive financing arms, vertically integrated timber specialists controlling sourcing through panel production, and regional single-storey fabricators occupying defensible rural niches. Competitive moves concentrate on strategic partnerships with municipal housing authorities and capacity expansion in timber-frame clusters.
Among diversified construction groups, Bouygues Construction and VINCI Construction exemplify platform integrators leveraging turnkey performance contracts with social-housing operators. Hexaom occupies a position within the vertical integration archetype, with timber sourcing and panel fabrication control in western France. Cougnaud Construction represents the specialized rural fabricator model, anchoring demand outside major urban corridors in Nouvelle-Aquitaine.
| Leading Market Players |
|---|
| Cougnaud Construction |
| OBM Construction |
| Bouygues Construction |
| Hexaom |
| Bonhomme Bâtiment |
| VINCI Construction |
| Bodard Construction |
| MARC SA |
| Eiffage Construction |
| Others |
Pricing and Supply Chain Analysis
Timber-frame manufacturing clusters around Pau and Toulouse concentrate engineered wood panel capacity, granting Occitanie-based fabricators pricing leverage over ANAH-subsidized social-housing operators in constrained urban zones. This geographic concentration compresses logistics costs for modular delivery while amplifying margin pressure on smaller fabricators lacking backward integration into forestry assets.
Pricing Analysis
Government project buyers anchor a three-tier pricing structure across premium, standard, and economy levels for modular units. Price differentiation separates RE2020-certified timber systems with environmental product declarations from uncertified concrete-intensive alternatives. Pricing pressure stems from EU Green Deal embodied-carbon compliance costs that smaller fabricators cannot absorb. Individual buyers in rural Nouvelle-Aquitaine exhibit highest price sensitivity, while municipal housing authorities in Île-de-France prioritize thermal performance guarantees over unit cost.
Supply Chain Analysis
Hexaom and Bouygues Construction hold captive panel fabrication capacity through controlled manufacturing sites in western France and Le Bourget respectively. Raw material dependencies rest on Landes forest timber, Belgian cross-laminated timber imports, and domestic steel reinforcement for multi-storey cores. Single-source vulnerability concentrates in engineered wood adhesive suppliers serving the Occitanie cluster. Distribution runs through turnkey performance contracts bundling factory output with municipal lease structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's prefab homes sector is accelerating through a regulatory inflection as RE2020 thermal-bridge mandates and CSRD disclosure requirements force material substitutions and carbon-accounting upgrades across the value chain.
For Market Incumbents: Insulate margin pools by deepening upstream control over timber sourcing in the Landes forest region and securing pre-certified environmental product declarations ahead of CSRD implementation. Defend against composite material substitution threats by investing in computational modeling capabilities for panel-to-panel junction detailing that smaller fabricators cannot replicate.
For New Entrants and Emerging Players: Establish a beachhead in rural single-storey deployment across Nouvelle-Aquitaine and Brittany where Cougnaud Construction's niche positioning demonstrates underexploited demand outside major urban corridors. Target peri- zones around Bordeaux and Limoges with affordable ground-level prefab configurations exempt from height restriction friction.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among prefab manufacturers serving institutional buyers through twenty-year municipal lease structures with embedded energy performance guarantees. Long-term viability across the projection horizon favors vertically integrated timber specialists with captive panel fabrication and ANAH subsidy channel access. Monitor relaxation of density restrictions in Paris basin urban cores as the primary inflection signal for multi-storey modular scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Assets | Captive supply from Landes forest secures embodied-carbon advantages for ANAH-subsidized developments. |
| CSRD Pre-Certification Program | Environmental product declarations capture preferential procurement status from institutional buyers. |
| Turnkey Performance Contracting | Twenty-year energy guarantees displace fragmented procurement across architectural and engineering entities. |
| BIM Integration Investment | Automated panel-cutting machinery eliminates shop-drawing bottlenecks for Lyon and Marseille housing authorities. |
| Multi-Storey Modular Capacity Expansion | Steel-reinforced core fabrication addresses density constraints in Île-de-France constrained urban zones. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANAH subsidy disbursement records, RE2020 regulatory filings, and EU Green Deal implementation guidance. Primary interviews engaged prefab manufacturing executives, municipal housing authority procurement officers, timber supply specialists, and social-housing operator development directors. Secondary validation drew from French customs timber trade data, SEC filings of listed construction conglomerates, and regional planning authority density restriction databases. Bottom-up unit deployment estimates triangulate against top-down market value reconstruction.
Forecast inputs incorporate product type segmentation across multi-storey, modular, single-storey, and mobile home architectures; material categories spanning timber, composite, steel, and concrete; and deployment modes distinguishing off-site, hybrid, on-site, and custom build approaches. CAGRs derive from regression analysis of historical procurement volumes against regulatory threshold implementation timelines and municipal contract award patterns. Modeled variables include RE2020 compliance cost pass-through rates and timber-frame cluster capacity utilization.
Stress conditions across RE2020 enforcement intensity, skilled installation labor availability, and municipal lease structure adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy channel continuity and planning authority cooperation. Quarterly review of ANAH capital allocation shifts and Île-de-France municipal contract award velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Japan Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
3D Printing Building Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Indonesia Infrastructure Market
Building Construction
Energy-Efficient Building Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Prefabricated Buildings Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
India Commercial Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
Australia Construction Market
Building Construction
Guatemala Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Saudi Arabia Prefabricated Buildings Market