
 Construction Lasers Market | 2026-2036
Construction Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Lasers Market Intelligence
ISO 16331-1 certification for laser rangefinder performance is bifurcating the competitive landscape into qualified precision manufacturers and commodity suppliers. Hilti Corporation leverages its captive service network to sustain premium positioning across European job sites. Topcon Corporation anchors its presence through integrated positioning systems that combine optical and GNSS technologies. Trimble, Inc. differentiates via software-embedded calibration protocols that reduce field setup time for surveyors.
Construction lasers are electro-optical instruments that project visible or infrared beams—typically at 635 nm (red) or 532 nm (green) wavelengths—to establish horizontal, vertical, or graded reference planes across building sites. These devices serve the primary industrial purpose of eliminating manual string-line and water-level methods, thereby reducing layout errors in concrete forming, ceiling installation, and earthwork grading. Rotary lasers occupy the dominant revenue position due to their 360-degree plane generation and outdoor visibility range exceeding 800 meters with detector accessories. Green laser technology commands expanding share as human eye sensitivity at 532 nm improves beam visibility by roughly fourfold over red equivalents in bright ambient conditions. 3D imaging lasers represent the fastest-growing category, pairing LiDAR scanning with point-cloud software for as-built documentation and clash detection in commercial building information modeling workflows.
FAA regulations govern laser emission levels for devices operated near flight corridors, constraining output power and beam divergence specifications for urban construction zones. OSHA standards mandate eye protection protocols when Class 3R or higher lasers are deployed, directly influencing accessory bundling and training service offerings. The EU Machinery Directive and CE marking requirements enforce electromagnetic compatibility and safety interlock standards for equipment sold across member states. Stakeholders must monitor evolving green building certification schemes that reward dimensional accuracy in prefabrication, as these programs increasingly specify laser-verified tolerance thresholds for structural component fitment.
Market Dynamics
Green laser diode miniaturization and 532 nm wavelength adoption are compressing the cost gap with red systems while OSHA eye protection mandates reshape accessory bundling economics across commercial job sites.
Growth Catalysts
- Infrastructure modernization:United States federal highway programs and Germany's rail network upgrades accelerate rotary laser replacement cycles for precision grading contracts.
- CE marking convergence:The EU Machinery Directive's electromagnetic compatibility standards are harmonizing cross-border equipment certification, reducing manufacturer compliance duplication costs.
- Building information modeling integration:3D imaging lasers paired with point-cloud software are displacing manual as-built documentation in commercial construction verticals.
Market Restraints
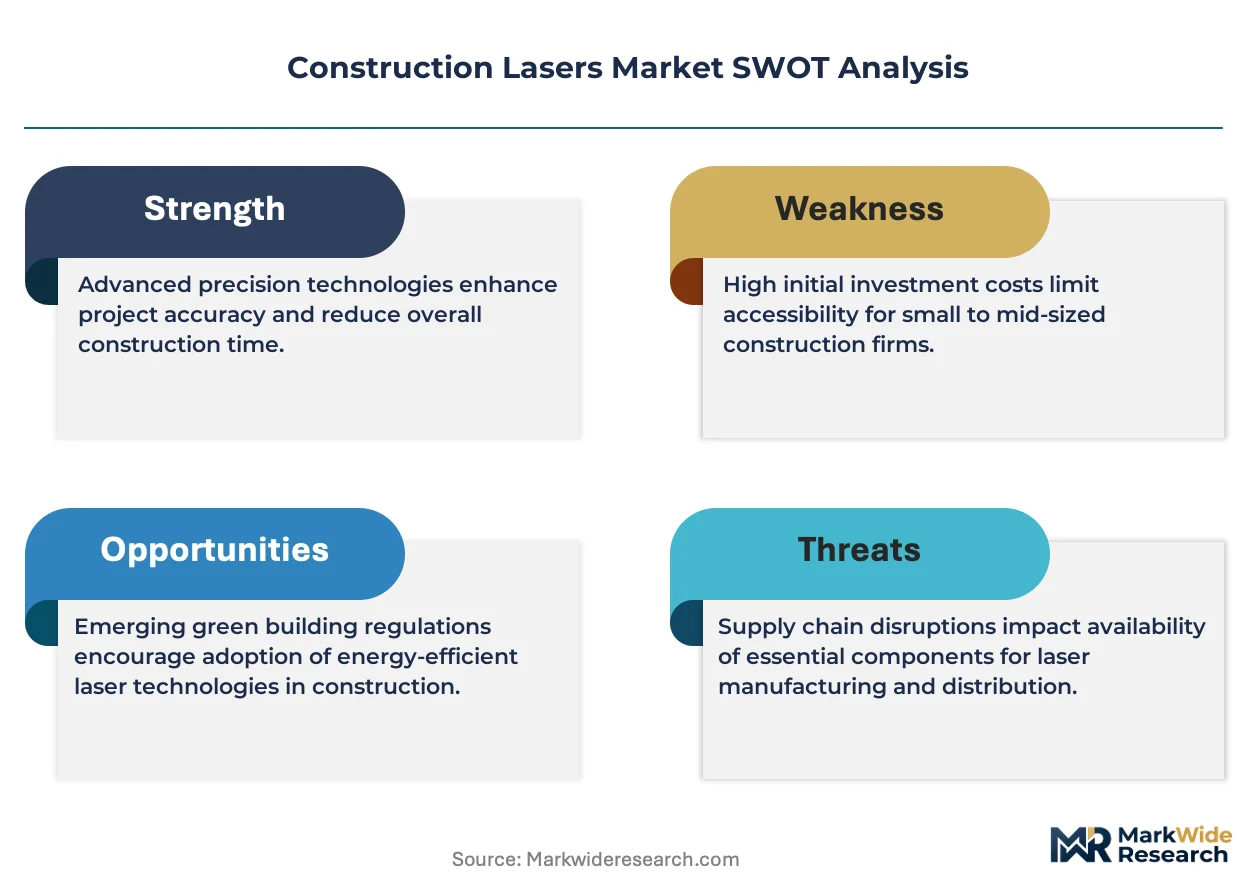
- Laser diode supply concentration:Green 532 nm diode fabrication capacity clusters in East Asian foundries, exposing OEMs to single-source disruption risk.
- FAA emission constraints:Federal Aviation Administration power limits near flight corridors restrict beam output specifications for urban high-rise projects.
- Optical component cost volatility:Rare-earth doped crystal prices for solid-state green conversion fluctuate with mining output from Chinese processing facilities.
Strategic Opportunities
- Prefabrication tolerance mandates:LEED and BREEAM green building schemes are specifying laser-verified dimensional thresholds for structural component fitment in modular construction.
- Service network unbundling:Independent calibration and repair channels are emerging alongside traditional manufacturer-captive service models.
- LiDAR-photogrammetry convergence:Hybrid scanning systems combining time-of-flight lasers with photogrammetric mesh generation are opening heritage documentation and forensic surveying applications.
Industry Challenges
- ISO 16331-1 certification timelines:The performance testing protocol for laser rangefinders extends product validation cycles by 8-14 months for precision-grade manufacturers.
- Field technician skill gaps:GNSS-integrated positioning systems require surveyor-level competency that general contractor crews rarely possess, forcing training investment or subcontractor reliance.
- Legacy optical instrument obsolescence:Theodolite and dumpy level knowledge bases are retiring with veteran operators, eroding transitional mentorship for hybrid system adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Lasers Market |
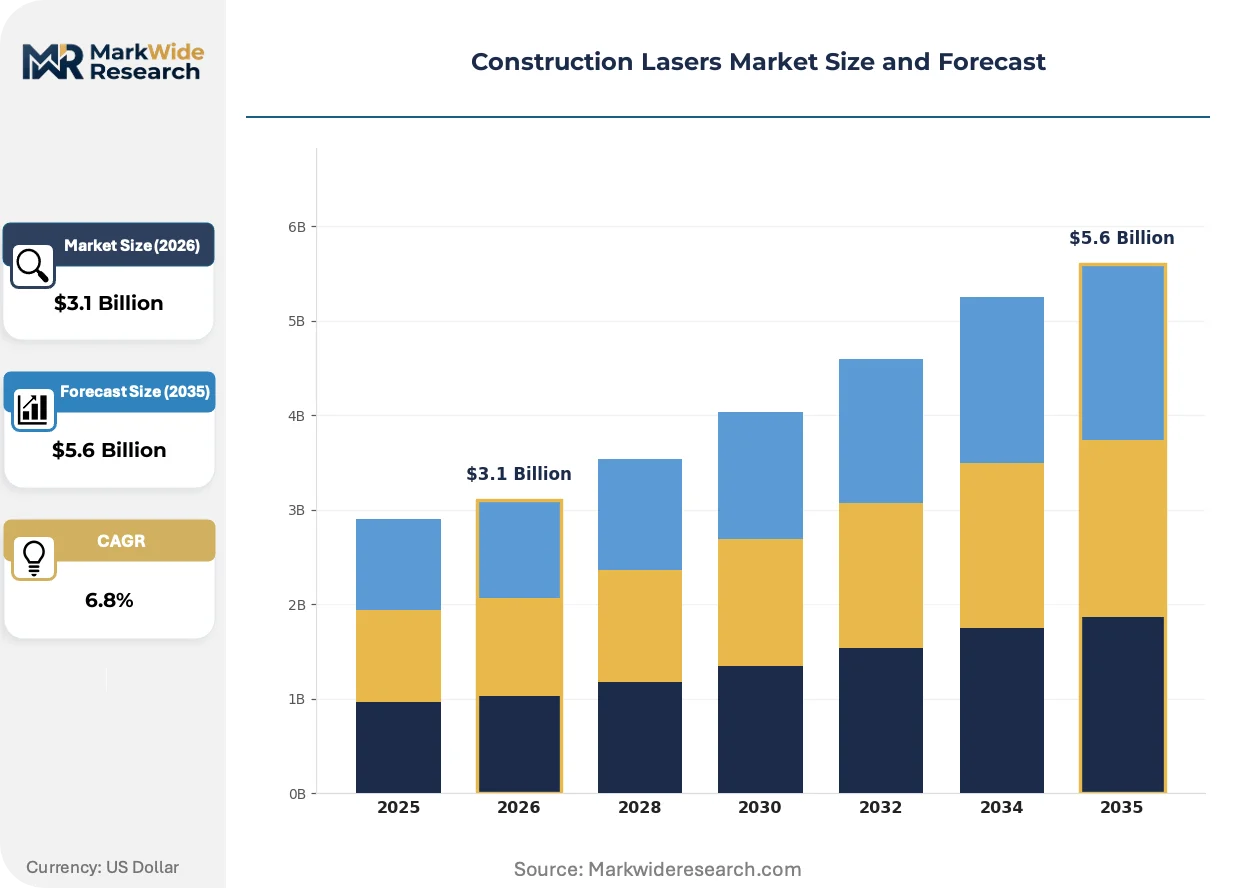
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Lasers, Line Lasers, Dot Lasers, 3D Lasers End User: Contractors, Architects, Surveyors, DIY Enthusiasts Technology: Green Laser, Red Laser, Blue Laser, 3D Imaging Application: Site Layout, Leveling, Alignment, Height Measurement |
| Companies Covered | Hilti Corporation, Robert Bosch GmbH, Topcon Corporation, Stanley Black & Decker, Inc., Trimble, Inc., Leica Geosystems, Johnson Level & Tool Mfg. Co., Inc., AdirPro, STABILA Messgeräte Gustav Ullrich GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Lasers Market Strategic Shifts & Innovations
Electro-optical component integration and software-embedded calibration are compressing field setup protocols while regulatory emission limits and certification schemes reshape competitive positioning.
MEMS-based laser scanning modules are miniaturizing 3D imaging payloads for handheld deployment. Commercial contractors deploying these units on renovation sites cut point-cloud acquisition time by half versus tripod-mounted systems. The form factor reduction is miniaturizing price points and expanding addressable buyer segments into residential remodeling.
OSHA Class 3R eye protection mandates are forcing accessory bundling strategies. Manufacturers now package laser safety glasses and warning signage with rotary systems to preempt liability exposure. Commercial roofing and steel erection crews in the United States face the strictest enforcement, driving standardized kit configurations.
Rental channel penetration is accelerating among mid-tier contractors. Equipment leasing firms in Germany and the United States now stock green rotary lasers with detector packages, displacing capital purchase for project-specific needs. This model concentrates fleet maintenance expertise with distributors while compressing manufacturer direct sales margins.
Construction Lasers Market Segmentation
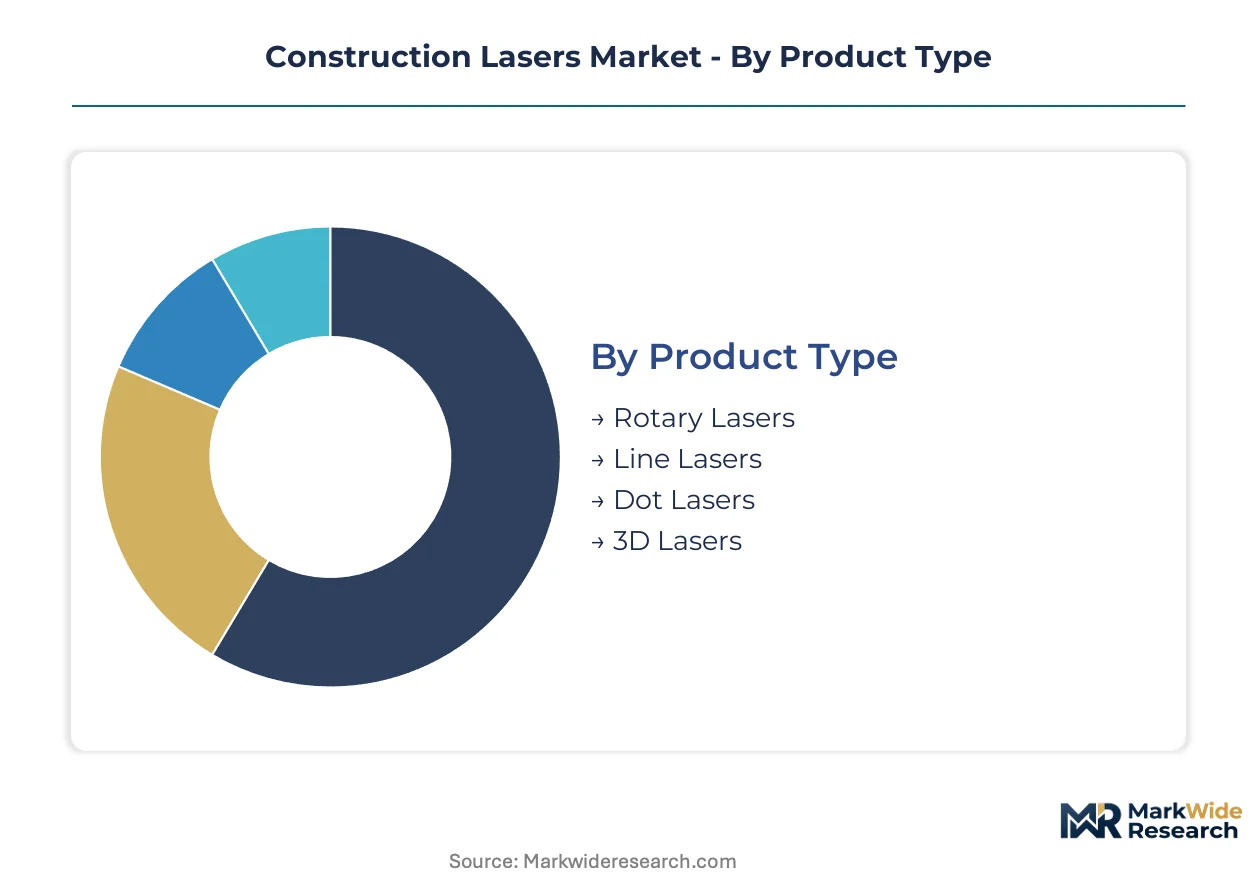
Construction laser procurement channels bifurcate sharply between rental fleets for project-based contractors and direct sales for permanent survey operations. Channel economics dictate which segments manufacturers prioritize for inventory placement and service bundling.
Product Type:
Channel placement varies dramatically by product complexity, with rotary and 3D systems concentrating in rental fleets while line and dot lasers move through retail distribution.
- Rotary Lasers:These 360-degree plane generators project horizontal, vertical, or graded reference planes across 800-meter ranges with detector accessories. Commercial grading contractors in the United States and Germany drive replacement demand through federal infrastructure programs requiring precision earthwork tolerances.
- 3D Lasers:LiDAR scanning systems paired with point-cloud software capture as-built documentation for building information modeling workflows. Commercial construction verticals in China are adopting these for clash detection in high-rise developments, displacing manual measurement methods.
- Line Lasers:Wall and ceiling alignment tools for interior finishing trades.
- Dot Lasers:Point-projection instruments for plumbing and squaring applications.
Rotary lasers dominate installed base. 3D lasers are where expansion concentrates.
End User:
Customer sophistication tiers separate calibration-dependent professional users from price-sensitive occasional buyers.
- Contractors:Commercial builders and specialty trades deploy rotary systems for concrete forming, steel erection, and site preparation. OSHA Class 3R eye protection mandates in the United States force safety accessory bundling for this segment.
- Surveyors:Licensed professionals require ISO 16331-1 certified rangefinders with traceable calibration protocols. European surveyors favor integrated GNSS-optical systems for geodetic control networks.
- Architects:Design-phase verification and existing conditions documentation.
- DIY Enthusiasts:Residential remodeling and home improvement applications.
Contractors represent the deepest replacement cycle. Surveyors concentrate the highest per-unit spend.
Technology:
Beam wavelength selection determines visibility performance, power consumption, and regulatory compliance thresholds.
- Green Laser:532 nm wavelength exploits fourfold human eye sensitivity improvement over red equivalents in bright ambient conditions. Miniaturized diode packages from East Asian foundries are compressing cost premiums versus red systems.
- Red Laser:635 nm wavelength maintains cost leadership for indoor applications with controlled lighting. Mature supply chains and abundant diode fabrication capacity insulate pricing from rare-earth volatility.
- Blue Laser:Shorter wavelength options for specialized industrial metrology.
- 3D Imaging:Time-of-flight and phase-shift scanning architectures for spatial data capture.
Red lasers anchor volume shipments. Green lasers are climbing the fastest.
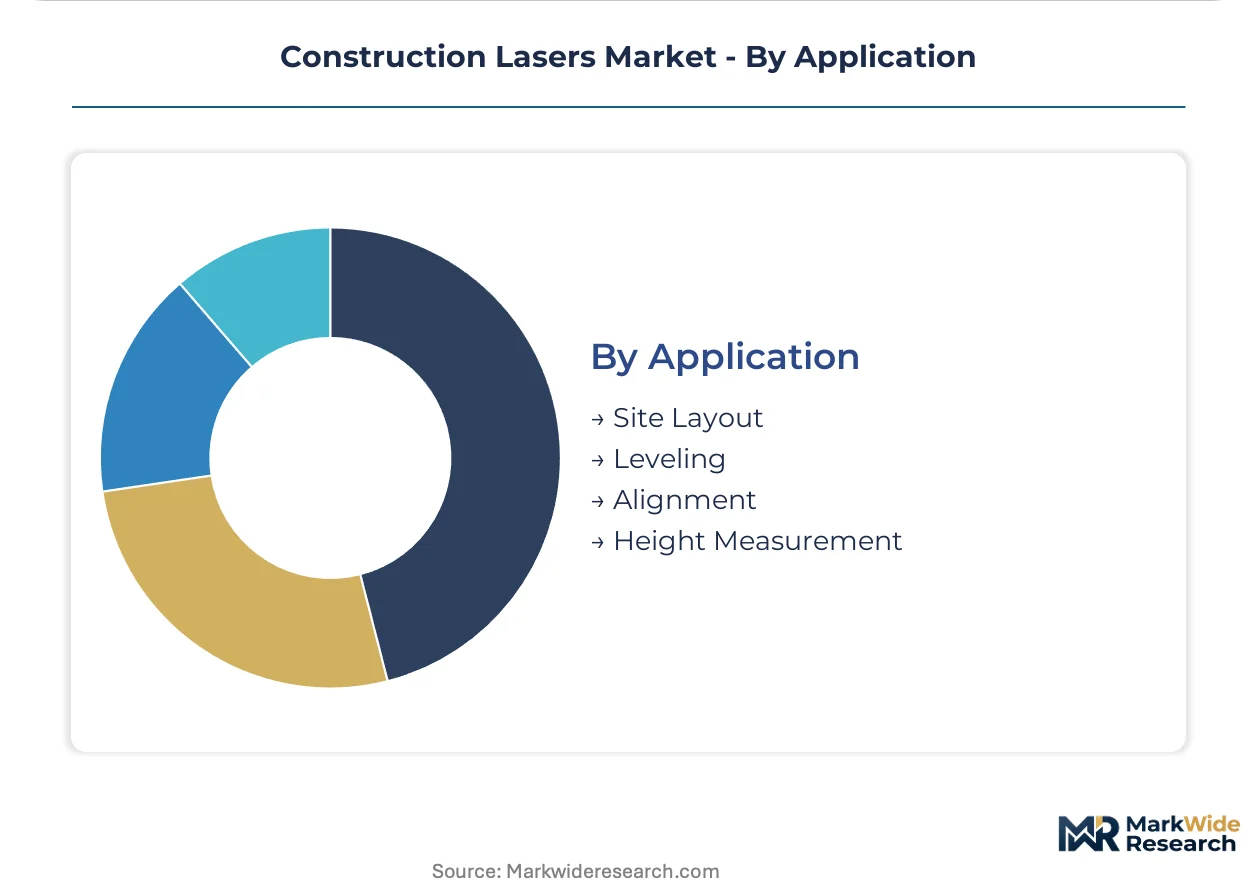
Application:
Use-case specificity determines instrument specification, with outdoor grading demanding maximum range and indoor alignment prioritizing compactness.
- Site Layout:Establishing control points, batter boards, and building footprints from survey datums. German rail network upgrades and United States highway programs are accelerating rotary laser deployment for precision staking operations.
- Leveling:Horizontal plane reference for concrete pours, ceiling grids, and equipment pads. Commercial contractors specify green rotary systems for exterior visibility in bright conditions.
- Alignment:Vertical and horizontal positioning for walls, partitions, and structural steel.
- Height Measurement:Elevation determination for earthwork verification and as-built documentation.
Site layout commands the premium instrument mix. Height measurement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure programs in the United States and Germany's rail modernization initiatives are accelerating rotary laser replacement cycles. China's high-rise construction boom and India's smart city projects are reshaping 3D imaging laser procurement patterns.
United States
Commercial grading contractors drive rotary laser demand through federal highway rehabilitation programs requiring precision earthwork tolerances. OSHA Class 3R eye protection mandates force safety accessory bundling for steel erection and roofing crews. The Dallas-Fort Worth metroplex concentrates rental fleet operations serving Texas infrastructure corridors.
Germany
Rail network upgrades and industrial facility modernization sustain premium instrument replacement demand among surveying professionals. CE marking requirements under the EU Machinery Directive harmonize cross-border equipment certification. Bavaria's precision engineering clusters anchor calibration service networks for geodetic control applications.
China
High-rise commercial developments in tier-one cities accelerate 3D imaging laser adoption for building information modeling workflows. GB standards for construction equipment safety shape domestic product specifications. The Yangtze River Delta manufacturing corridor concentrates green laser diode packaging operations.
India
Smart city infrastructure projects and metro rail expansions create demand for site layout and leveling instruments. BIS certification requirements for imported electro-optical equipment extend product validation timelines. Maharashtra's Mumbai-Pune industrial belt hosts distributor networks serving western India construction markets.
Japan
Seismic retrofit programs and Olympic legacy infrastructure maintenance sustain survey-grade instrument demand. METI industrial standards govern laser emission specifications for urban construction zones. The Kanto region around Tokyo concentrates integrated positioning system integration facilities.
Construction Lasers Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive distribution networks. Market structure exhibits tiered concentration with premium precision manufacturers, mid-range equipment suppliers, and commodity tool brands occupying distinct price-performance bands. Strategic archetypes include integrated positioning specialists, rental channel optimizers, and calibration-dependent survey-grade providers. Competitive moves center on service network expansion and software-embedded calibration protocol differentiation.
Within the integrated positioning tier, Topcon Corporation and Trimble, Inc. exemplify convergence between optical and satellite-based measurement technologies. Hilti Corporation anchors the premium service-intensive segment through its captive job-site support infrastructure. Among diversified industrial conglomerates, Robert Bosch GmbH and Stanley Black & Decker, Inc. occupy positions spanning professional contractor and retail consumer channels. Leica Geosystems represents the precision survey-grade archetype with traceable calibration protocols. STABILA Messgeräte Gustav Ullrich GmbH exemplifies specialized European manufacturing heritage in measurement tools.
| Leading Market Players |
|---|
| Hilti Corporation |
| Robert Bosch GmbH |
| Topcon Corporation |
| Stanley Black & Decker, Inc. |
| Trimble, Inc. |
| Leica Geosystems |
| Johnson Level & Tool Mfg. Co., Inc. |
| AdirPro |
| STABILA Messgeräte Gustav Ullrich GmbH |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with East Asian diode foundries lock in green laser supply access and stabilize component pricing visibility for OEMs serving United States infrastructure contractors. These contracts insulate manufacturers from rare-earth crystal volatility while embedding volume commitments that shape tiered procurement economics across the value chain.
Pricing Analysis
Certification level creates the primary spread between precision-grade and commodity-tier equipment. ISO 16331-1 verified rangefinders command premium positioning through traceable calibration protocols, while CE-marked standard units compete on unit economics for general contractor fleets. Pricing pressure stems from rental channel expansion compressing direct sales margins. DIY enthusiasts exhibit highest price sensitivity, whereas licensed surveyors prioritize accuracy guarantees over acquisition cost.
Supply Chain Analysis
China and Taiwan anchor green laser diode fabrication, with Japan and Germany supplying precision optical assemblies and calibration reference standards. Nd:YAG crystal and rare-earth doped components draw from Chinese processing facilities. Single-source vulnerability concentrates in 532 nm diode packaging operations. Distribution runs through manufacturer-captive service networks in Europe and independent rental fleets in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rental fleet consolidation among United States equipment lessors is shifting procurement leverage toward distributors, fragmenting manufacturer pricing power and forcing service bundling concessions.
For Market Incumbents: Fortify calibration service networks to defend against independent repair channel encroachment. Invest in backward integration into green diode sourcing to reduce East Asian foundry dependency. Prioritize software-embedded calibration protocols that reduce field technician skill requirements and accelerate setup protocols. For New Entrants and Emerging Players: Lead with MEMS-based handheld 3D scanning systems targeting residential remodeling contractors underserved by tripod-mounted platforms. Penetrate India's smart city infrastructure corridor through BIS-certified distribution partnerships. Emphasize project-based rental economics over capital purchase positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated positioning specialists with captive service networks. Five-to-ten year viability favors precision-grade manufacturers with ISO certification moats. Monitor FAA emission constraint relaxation near urban flight corridors as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Service Network Expansion | Hilti's captive job-site infrastructure sustains premium positioning across German rail modernization contracts. |
| Software-Embedded Calibration | Trimble's automated protocols reduce surveyor setup time for United States highway grading operations. |
| Green Diode Backward Integration | Upstream control over 532 nm fabrication insulates margins from rare-earth crystal volatility. |
| Rental Channel Partnership | Equipment leasing concentration in Dallas-Fort Worth displaces direct sales for mid-tier contractors. |
| LiDAR-Photogrammetry Convergence | Hybrid scanning opens heritage documentation applications beyond traditional construction verticals. |
Research Approach
Operator-level perspectives from commercial grading contractors, licensed surveyors, rental fleet managers, and calibration service technicians anchored the qualitative base. Primary fieldwork combined with secondary validation from OSHA regulatory filings, FAA emission standards documentation, EU Machinery Directive implementation guidance, and customs trade data for electro-optical equipment. Bottom-up instrument shipment analysis triangulated against top-down infrastructure spending forecasts across the analysis window.
Sensitivity analysis tested demand elasticity under varying infrastructure appropriation scenarios and green building certification adoption rates. Segmentation modeling incorporated product type, beam wavelength technology, end-user sophistication tier, and application specificity throughout the forecast period. CAGRs derived from replacement cycle analysis, technology substitution curves, and regional construction output projections. Green diode cost compression trajectories and ISO certification timeline assumptions shaped volume forecasts.
Forecasts assume regulatory continuity in OSHA eye protection mandates, FAA urban emission limits, and EU CE marking requirements; material policy shifts would require re-modeling. Supply disruption scenarios for East Asian diode fabrication and rare-earth processing facilities inform risk-adjusted projections. Recalibration cycles align with material shifts in federal infrastructure appropriations and green building certification scheme evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Grader Blades Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
Jib Crane Market
Construction Equipment
Brazil Construction Equipment Market