
 Rotary Dryers Market | 2026-2036
Rotary Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Dryers Market Insights
The EU Green Deal's industrial decarbonization targets are pivoting cement and mineral processors toward electric-heating and biomass-compatible rotary dryer configurations. ANDRITZ AG leverages its combustion technology heritage to anchor European retrofit demand, while FLSmidth competes on mining-sector integration across Australasia. SPX Flow differentiates through sanitary-design dryers that sustain pharmaceutical and food-grade certification requirements.
A rotary dryer is a cylindrical drum apparatus that tumbles moist feedstock through heated gas streams, typically operating at shell temperatures between 200°C and 750°C depending on material sensitivity and thermal efficiency targets. Its primary purpose is bulk solids dehydration across continuous-process industries where uniform moisture reduction preserves downstream handling, storage stability, or combustion performance. Direct rotary dryers dominate mineral processing and biomass applications where gas-to-material contact efficiency governs throughput economics, while indirect rotary dryers command premium positioning in food and pharmaceutical chains where product contamination risk disqualifies open-flame exposure. Electric heating technology is gaining fastest in jurisdictions with carbon border adjustments, though combustion retains installed-base dominance in energy-intensive mining corridors.
EPA emissions standards in the United States, REACH chemical safety protocols in Europe, and China's GB standards on industrial energy intensity collectively shape equipment specification sheets, fuel-switching timelines, and cross-border equipment certification costs. The EU F-Gas Regulation and evolving state-level carbon pricing in California and New York are accelerating electric-heating pilot installations among multinational processors. Stakeholders must monitor regulatory divergence between thermal-efficiency mandates and carbon-accounting rules to avoid stranded capital in long-tenure drying assets.
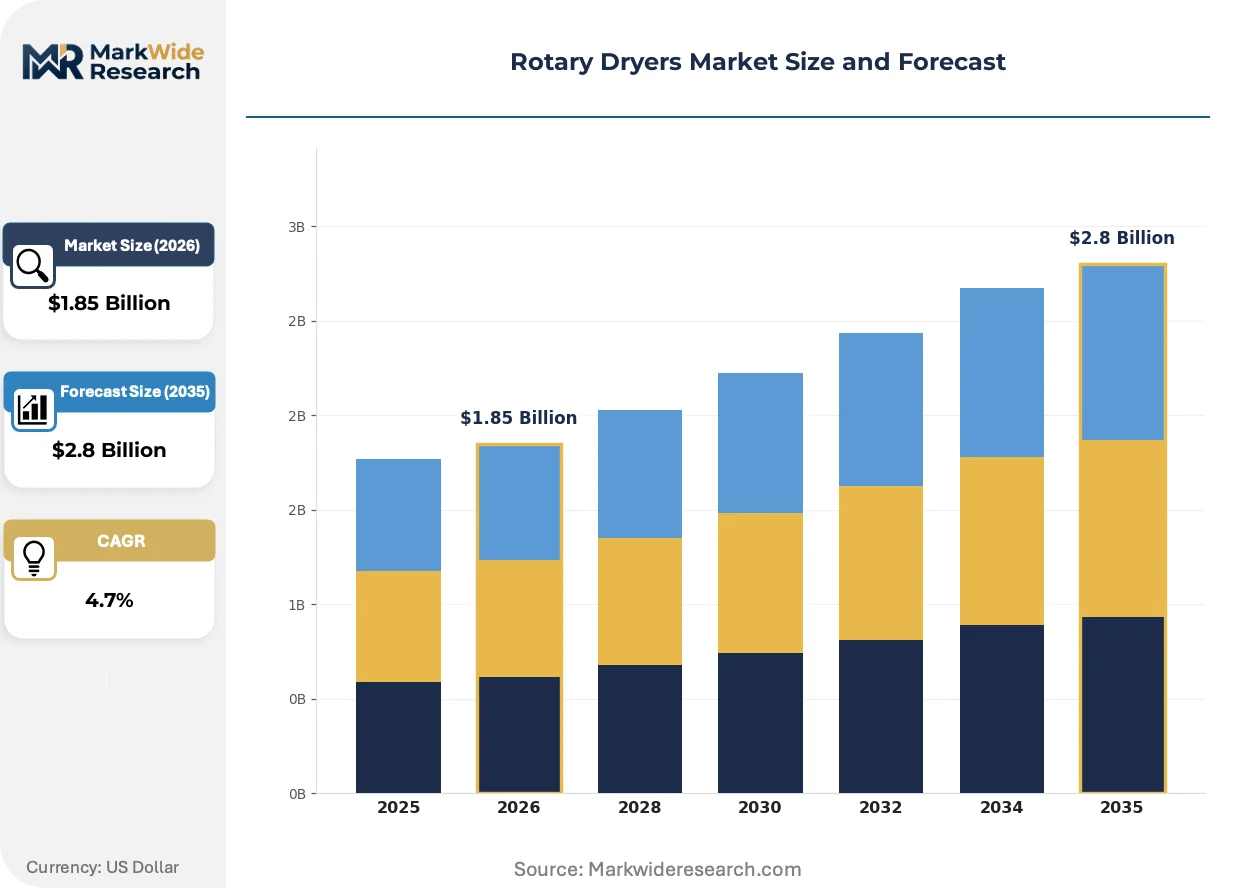
Market Dynamics
Electric-heating retrofits are compressing the fuel-switching timeline for installed rotary dryer bases as carbon border adjustments in Europe and North America rewrite procurement specifications for energy-intensive mineral processors.
Growth Catalysts
- EPA emissions mandates:Tightening limits on industrial combustion systems in the United States are forcing cement and aggregate producers toward low-NOx burner retrofits and continuous emissions monitoring upgrades.
- Biomass feedstock expansion:Wood pellet and agricultural residue processors across Southeast Asia are scaling continuous-drying capacity to serve export markets for renewable fuel certification.
- Mineral processing throughput:Iron ore and lithium concentrate operations in Western Australia are adding shell capacity to handle higher-grade ore volumes and downstream battery supply chain offtake.
Market Restraints
- Natural gas price volatility:Direct-fired dryer operating economics remain exposed to European and Asian spot LNG fluctuations that compress margin predictability for contract manufacturers.
- Refractory supply concentration:High-alumina brick and specialized lining materials for high-temperature shells concentrate among Chinese and Indian suppliers, creating single-source vulnerability.
- Heat pump thermal limits:Electric alternatives currently face technical ceilings around 200°C for industrial-scale throughput, disqualifying them from cement clinker and certain mineral calcination applications.
Strategic Opportunities
- Indonesia food processing infrastructure:Palm oil and copra drying operations lack modern continuous systems, creating whitespace for sanitary-design indirect dryer penetration.
- EU Green Deal retrofit incentives:Industrial decarbonization grants in Germany, Poland, and Italy are covering 30-50% of electric-heating conversion capex for qualifying processors.
- Digital twin convergence:IoT sensor networks combined with predictive maintenance software are enabling moisture-control-as-a-service offerings that bypass traditional equipment sale models.
Industry Challenges
- Combustion engineering talent scarcity:The retirement wave of experienced burner technicians and thermal process engineers is outpacing vocational pipeline replenishment in North America and Western Europe.
- Legacy control system integration:Brownfield sites running 1990s-era PLC architectures face protocol incompatibility when retrofitting modern emissions monitoring and automated moisture feedback loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Dryers Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Rotary Dryers, Indirect Rotary Dryers, Spray Rotary Dryers, Flash Rotary Dryers Technology: Combustion, Solar, Electric Heating, Fluidized Bed, Microwave Application: Mineral Processing, Chemical Processing, Food Processing, Paper & Pulp, Biomass Drying End User: Mining, Pharmaceuticals, Food & Beverage, Cement Manufacturing, Agricultural Processing |
| Companies Covered | ALLGAIER, Carrier, ANDRITZ AG, Bühler, SPX Flow, FLSmidth, Metso, Hosokawa Micron, FEECO International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Dryers Market Trends and Innovations
Heat recovery and electrification architectures are converging to redefine thermal efficiency benchmarks, while digitalization layers create new service revenue streams that decouple vendor economics from equipment shipment cycles.
Electromagnetic heating coils are rewriting the temperature control precision available to pharmaceutical and specialty chemical processors. These systems eliminate open flame contact while enabling rapid ramp rates that batch processors demand. European contract manufacturers are piloting retrofits at pilot scale, and the technology is compressing the qualification timeline for ATEX-certified drying operations.
The EU F-Gas Regulation is accelerating refrigerant-based heat pump dryer development for sub-150°C applications. Industrial processors in food and biomass sectors must now account for phasedown quotas in long-term equipment planning. German and Dutch engineering firms are responding with CO2 transcritical cycle designs that sidestep conventional hydrofluorocarbon dependency.
Performance-based service contracts are displacing traditional capex procurement in mining-sector rotary dryer fleets. Major copper and iron ore operators in Chile and Australia now specify guaranteed moisture output and availability uptime rather than equipment ownership. This shift concentrates vendor risk on reliability engineering while opening decade-long revenue streams for OEM maintenance networks.
Rotary Dryers Market Segmentation
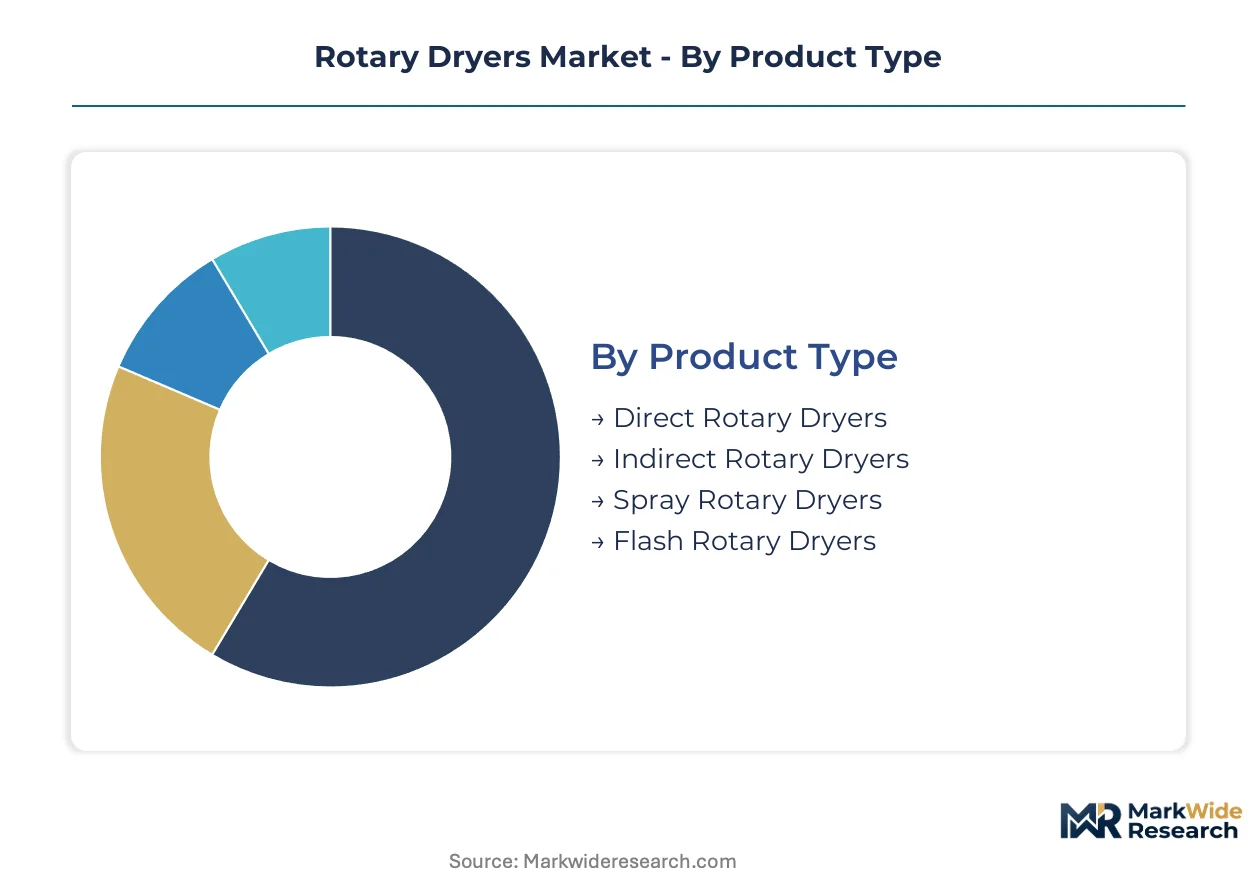
Rotary dryer procurement decisions split sharply between bulk mineral throughput economics and contamination-sensitive batch precision. Equipment specification sheets diverge across thermal source, material contact architecture, and end-use certification requirements.
Product Type:
Volume deployment favors direct gas contact designs, while premium positioning concentrates in sealed systems for regulated products.
- Direct Rotary Dryers:These systems expose feedstock directly to heated combustion gases, achieving rapid moisture stripping through turbulent gas-to-solids contact. Iron ore and lithium concentrate operations in Western Australia specify these units for their thermal efficiency and tonnage scalability under mining-sector procurement timelines.
- Indirect Rotary Dryers:Heat transfers through the drum shell or internal tubes, eliminating product contamination from combustion gases. Pharmaceutical manufacturers in Germany and food processors across the Netherlands mandate these configurations to satisfy EFSA hygiene protocols and REACH chemical safety documentation.
- Spray Rotary Dryers:Atomized liquid feeds encounter concurrent or countercurrent hot gas streams for rapid powder formation. Nutraceutical contract manufacturers in Switzerland deploy these for protein isolate and enzyme drying where particle size distribution governs downstream tableting performance.
- Flash Rotary Dryers:Pneumatic conveying suspends particles in high-velocity heated air for sub-minute residence times. Starch and modified cellulose processors in Belgium favor these for heat-sensitive biopolymers requiring minimal thermal degradation.
Mature deployment sits with Direct Rotary Dryers. Newer deployment is concentrated in Indirect Rotary Dryers.
Technology:
Carbon border adjustments are compressing the fuel-switching timeline for installed bases, with electric alternatives gaining fastest in jurisdictions with emissions pricing.
- Combustion:Natural gas, diesel, or biomass burners deliver shell temperatures exceeding 700°C for cement clinker and mineral calcination. Cement manufacturers in Poland and aggregate processors in Texas retain this dominance where grid electricity costs and thermal density requirements disqualify alternatives.
- Electric Heating:Resistance elements or electromagnetic coils eliminate stack emissions and enable precise temperature ramp control. Battery materials processors in Sweden and specialty chemical manufacturers in California are piloting these configurations to align with EU Green Deal incentives and state-level carbon pricing.
- Solar:Concentrated thermal collectors pre-heat air or generate steam for low-temperature drying cycles. Agricultural cooperatives in Spain and olive pomace processors in Greece exploit these for seasonal operations with favorable insolation profiles.
- Fluidized Bed:Perforated plates suspend particles in hot air streams, combining rotary drum mechanics with enhanced heat transfer. Fertilizer granulation plants in Morocco and phosphate processors in Jordan specify these for uniform moisture profiles across variable feedstock sizes.
- Microwave:Dielectric heating penetrates volumetrically, reducing surface crusting and thermal gradients. Wood modification facilities in Finland and timber treatment operations in Austria trial these for preservative impregnation cycles requiring controlled moisture gradients.
Combustion retains the largest installed base. Electric Heating is expanding most quickly among new installations.
Application:
End-use moisture specifications and throughput economics determine equipment architecture selection across continuous-process industries.
- Mineral Processing:High-tonnage iron ore, copper concentrate, and rare earth element operations require robust shell construction and refractory linings. Pilbara mining corridors in Australia and Chilean copper belts specify direct-fired units with automated moisture feedback to optimize smelter feed preparation.
- Chemical Processing:Catalyst support drying, polymer flake conditioning, and specialty salt crystallization demand tight temperature control. BASF and Evonik production networks in Ludwigshafen specify indirect configurations with nitrogen blanketing for oxidation-sensitive intermediates.
- Food Processing:Milk powder, starch derivatives, and protein concentrates require sanitary-design construction with CIP capability. FrieslandCampina and Arla facilities in Denmark and the Netherlands mandate 3A sanitary standards and ATEX certification for combustible dust atmospheres.
- Paper & Pulp:Black liquor evaporation and pulp sheet conditioning integrate with recovery boiler systems. Södra and Stora Enso mills in Sweden deploy these as thermal efficiency nodes within integrated biorefinery configurations.
- Biomass Drying:Wood pellet, agricultural residue, and energy crop processors require consistent moisture reduction for combustion efficiency and storage stability. Enviva pellet plants in Mississippi and Drax supply chain operations in Louisiana specify these for renewable fuel certification compliance.
Mineral Processing commands the highest unit throughput. Food Processing is gaining share fastest on sanitary-design premiums.
End User:
Procurement authority and maintenance capabilities shape vendor relationships and service contract structures across capital-intensive sectors.
- Mining:Integrated majors and contract miners specify availability guarantees and predictive maintenance packages. BHP and Rio Tinto operations in Western Australia negotiate decade-long service agreements with moisture-output penalties and uptime bonuses.
- Pharmaceuticals:FDA and EMA validation requirements impose documentation burdens and change-control protocols. Novartis and Roche manufacturing networks in Basel specify IQ/OQ/PQ qualification packages with electronic batch record integration.
- Food & Beverage:Nestlé and Unilever procurement frameworks emphasize energy efficiency and water recovery metrics. Maggi production facilities in Germany and Lipton tea processing in Kenya specify these for Scope 3 emissions reduction targets.
- Cement Manufacturing:HeidelbergCement and LafargeHolcim plants prioritize thermal substitution rates and alternative fuel compatibility. Polish and Italian facilities retrofit for refuse-derived fuel co-firing under EU ETS compliance timelines.
- Agricultural Processing:Grain elevators, oilseed crush facilities, and cotton gins operate seasonal cycles with variable feedstock moisture. Cargill and ADM networks in Iowa and Illinois specify modular units with rapid deployment and relocation capabilities.
Mining represents the most concentrated procurement volume. Pharmaceuticals commands the highest specification premiums per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotary dryer production concentrates in Germany, Switzerland, and Austria, while consumption clusters in mining corridors of Australia and agricultural processing zones of Indonesia. This geographic split creates equipment export flows from European engineering centers toward resource extraction and food processing frontiers.
United States
EPA emissions mandates on industrial combustion systems are forcing cement and aggregate producers toward low-NOx burner retrofits. The Inflation Reduction Act provides tax credits for electrification projects in energy-intensive manufacturing. Houston and Gulf Coast chemical clusters are piloting electric-heating configurations to align with state-level carbon pricing in California and New York.
Germany
EU Green Deal industrial decarbonization targets are pivoting cement processors toward biomass-compatible rotary dryer configurations. The EU F-Gas Regulation accelerates refrigerant-based heat pump development for sub-150°C applications. Ludwigshafen and the Rhine-Neckar chemical triangle specify indirect configurations with nitrogen blanketing for oxidation-sensitive intermediates.
Australia
Iron ore and lithium concentrate operations in Western Australia are adding shell capacity to handle higher-grade ore volumes. The country's national environmental regulator enforces strict emissions monitoring on mining-sector combustion equipment. Pilbara mining corridors specify direct-fired units with automated moisture feedback to optimize smelter feed preparation.
Indonesia
Palm oil and copra drying operations lack modern continuous systems, creating whitespace for sanitary-design indirect dryer penetration. The country's national industrial standards body mandates energy efficiency certifications for imported processing equipment. Java and Sumatra agricultural processing zones are scaling drying capacity to serve export markets for renewable fuel certification.
Sweden
Battery materials processors are piloting electric-heating configurations to align with EU Green Deal incentives. REACH chemical safety protocols impose documentation burdens on equipment qualification. Södra and Stora Enso mills deploy rotary dryers as thermal efficiency nodes within integrated biorefinery configurations.
Rotary Dryers Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with combustion technology heritage. Equipment fabrication concentrates among European and North American engineering groups that leverage thermal process expertise across adjacent capital goods categories. Three archetypes dominate: mining-integrated OEMs, sanitary-design specialists, and diversified process technology conglomerates. Consolidation through strategic partnerships and geographic expansion into Southeast Asian food processing markets represents the dominant competitive trajectory.
Among diversified process technology conglomerates, ANDRITZ AG and FLSmidth occupy positions that exemplify contrasting geographic anchoring strategies. ANDRITZ AG represents the European retrofit demand vector, while FLSmidth sits within the mining-sector integration archetype across Australasia. SPX Flow anchors the sanitary-design specialist tier, exemplifying premium positioning through pharmaceutical and food-grade certification capabilities.
| Leading Market Players |
|---|
| ALLGAIER |
| Carrier |
| ANDRITZ AG |
| Bühler |
| SPX Flow |
| FLSmidth |
| Metso |
| Hosokawa Micron |
| FEECO International |
| Others |
Pricing and Supply Chain Analysis
Captive refractory supply from Chinese and Indian lining manufacturers anchors both cost predictability and pricing power for European OEMs serving high-temperature mineral processing contracts. This backward integration into critical shell materials insulates established fabricators from spot price volatility while forcing smaller competitors toward premium sourcing premiums that compress their bid competitiveness against mining-sector procurement frameworks.
Pricing Analysis
Margin tightening in standard-configuration direct dryers reflects refractory cost pass-through and European carbon border adjustment exposure on combustion-heated units. Three-tier pricing structure across ATEX-certified, sanitary-design, and standard industrial levels segments buyers by contamination risk tolerance and validation burden. Cement and aggregate processors in Poland exhibit highest price sensitivity due to EU ETS compliance costs, while pharmaceutical manufacturers in Switzerland absorb premium positioning for IQ/OQ/PQ documentation packages.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining procurement in Western Australia and Chile, while distribution runs through engineering-procurement-construction contractors for brownfield retrofit projects in Germany and Poland. High-alumina brick, specialized alloy shell forgings, and precision burner assemblies draw from concentrated Chinese, Indian, and German supplier bases. Single-source vulnerability in refractory lining materials creates exposure to export licensing delays and maritime logistics chokepoints through Rotterdam and Singapore transshipment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
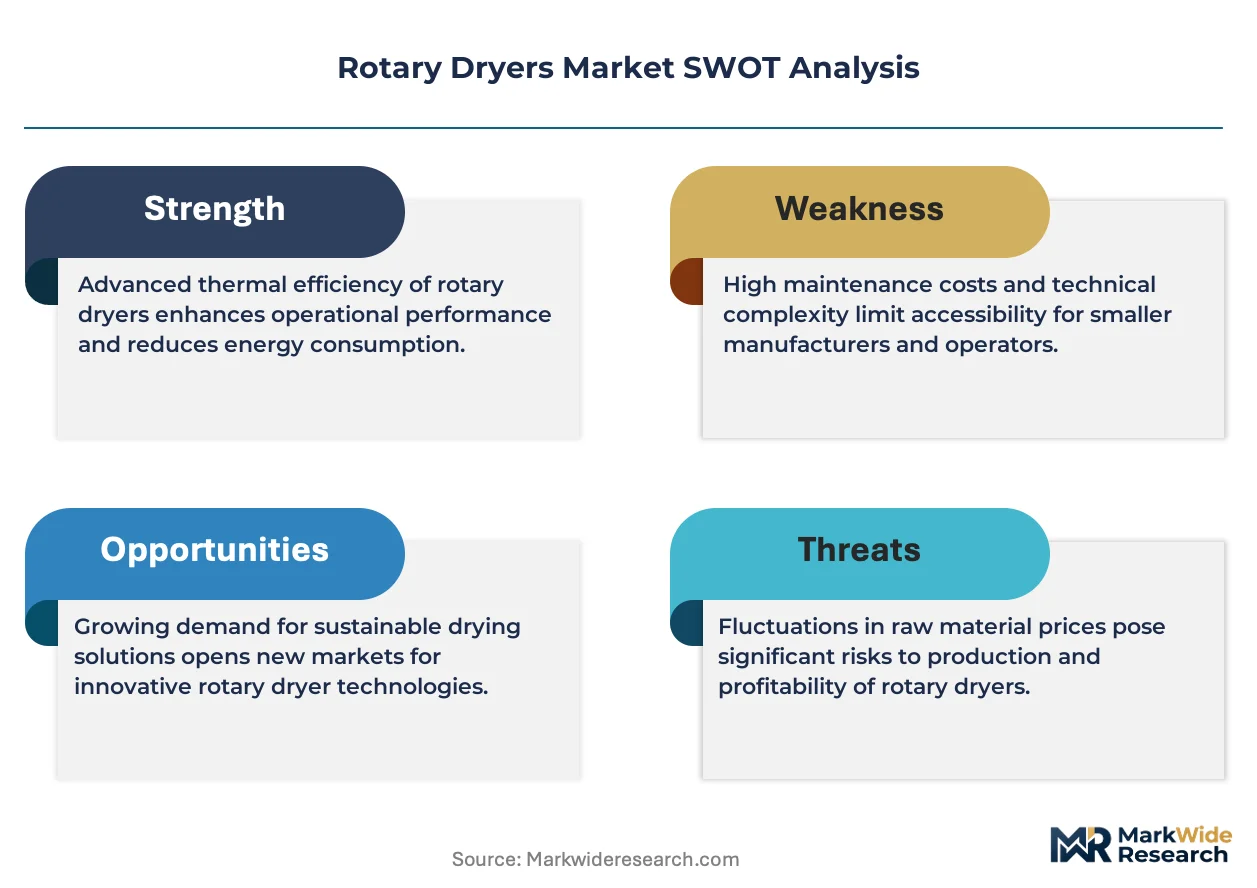
The Rotary Dryers Market functions as a cost-of-compliance arena where REACH chemical safety documentation and EU F-Gas refrigerant phasedown schedules erect qualification barriers that favor incumbents with established certification infrastructure.
For Market Incumbents: Anchor service revenue expansion through performance-based moisture-output contracts that displace traditional equipment sale economics in Australian and Chilean mining corridors. Defend against electromagnetic heating disruptors by accelerating electric-heating pilot installations under EU Green Deal retrofit incentives. Prioritize combustion engineering talent retention through vocational pipeline partnerships in Germany and Austria. For New Entrants and Emerging Players: Begin with sanitary-design indirect dryer penetration in Indonesia's palm oil and copra processing zones where modern continuous systems remain underdeployed. Target modular electric-heating configurations for agricultural cooperatives in Spain and Greece with favorable solar insolation profiles. Pursue qualification partnerships with Dutch and German engineering firms to fast-track EFSA hygiene protocol compliance. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified process technology conglomerates seeking mining-sector integration or sanitary-design certification capabilities. Long-term viability hinges on electric-heating technology maturation beyond current thermal ceilings. Monitor EU carbon border adjustment implementation timelines as inflection signal for combustion-to-electric conversion capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Electric-Heating Retrofit Deployment | Positions vendors for EU Green Deal grant capture in German and Polish cement corridors. |
| Sanitary-Design Certification Investment | Unlocks pharmaceutical procurement frameworks at Novartis and Roche manufacturing networks. |
| Performance-Based Service Contracting | Concentrates vendor risk while opening decade-long revenue streams with BHP and Rio Tinto. |
| Refractory Supply Backward Integration | Insulates margin predictability against Chinese export licensing volatility. |
| Digital Twin Platform Development | Enables moisture-control-as-a-service offerings that bypass traditional shipment cycles. |
Research Methodology
Independent corroboration across thermal process engineers at ANDRITZ AG and FLSmidth, procurement leads at BHP and Rio Tinto, and aftermarket service heads at SPX Flow underwrites the qualitative findings. Secondary validation draws from EPA emissions filings, EU ETS compliance disclosures, SEC 10-K equipment revenue segmentations, and customs trade data on high-alumina refractory imports. Bottom-up installation tracking across Australian mining corridors and Indonesian agricultural processing zones triangulates against top-down OEM revenue aggregation.
Rate-of-change decomposition across the projection horizon segments volume and value trajectories by product architecture (direct, indirect, spray, flash), thermal source (combustion, electric, solar, fluidized bed, microwave), and end-use application (mineral processing, chemical processing, food processing, paper and pulp, biomass drying). CAGRs derive from regression analysis against mining throughput expansion in Western Australia, cement clinker production forecasts in Poland and Italy, and food processing infrastructure investment pipelines in Indonesia and the Netherlands.
Underlying measurement precision varies by segment; electric-heating technology deployment and Southeast Asian food processing whitespace carry wider confidence intervals than mature combustion installations in Australian iron ore corridors. Forecasts reflect assumptions regarding EU carbon border adjustment implementation pace, natural gas price volatility persistence, and refractory supply chain resilience. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Smart Crane Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Truck Crane Market
Construction Equipment
Refurbished Construction Equipment Market
Construction Equipment
Snow Removal Market
Construction Equipment
Collating Machinery Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Static Crane Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market