
 Construction Site Preparation Equipment Market | 2026-2036
Construction Site Preparation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Site Preparation Equipment Market Analysis
Tier 4 Final and Stage V compliance specification is collapsing the residual value of legacy diesel-only fleets while creating replacement pull. Caterpillar leverages its dealer network density to sustain aftermarket parts revenue through telematics-linked service contracts. Komatsu anchors its position in intelligent machine control, where factory-integrated GPS grading systems reduce survey labor on civil sites. SANY Group competes on manufacturing scale, occupying cost-sensitive segments in emerging Asian markets through localized component sourcing.
Construction site preparation equipment comprises heavy machinery engineered for earthmoving, surface leveling, and material transport with operating weights from 3 to 100-plus metric tons and engine outputs governed by regional emissions tiers. Hydraulic excavators with boom-mounted GPS receivers perform trenching and foundation excavation to sub-centimeter accuracy, while motor graders establish finished grade for pavement sub-bases through articulated frame steering and moldboard hydraulics. Excavators lead equipment type demand where urban utility tunneling and basement excavation volumes remain elevated, while autonomous technology represents the fastest-growing segment as OEMs validate remote-operated dozers in hazardous mining pre-strips. GPS-enabled systems command margin premiums by reducing staking crew requirements and rework cycles on linear infrastructure projects.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine after-treatment investments that inflate base machine pricing and compress margins for non-compliant imports. OSHA excavation safety standards and ISO 12117 operator protection protocols shape cab design and rollover protection specifications across export-bound product lines. China's MIIT dual carbon goals and GB 36886 non-road emissions standards are redirecting domestic OEM capacity toward electric powertrains for municipal construction zones. Stakeholders must monitor battery energy density trajectories and charging infrastructure buildouts to time fleet electrification commitments against total cost of ownership crossover points.
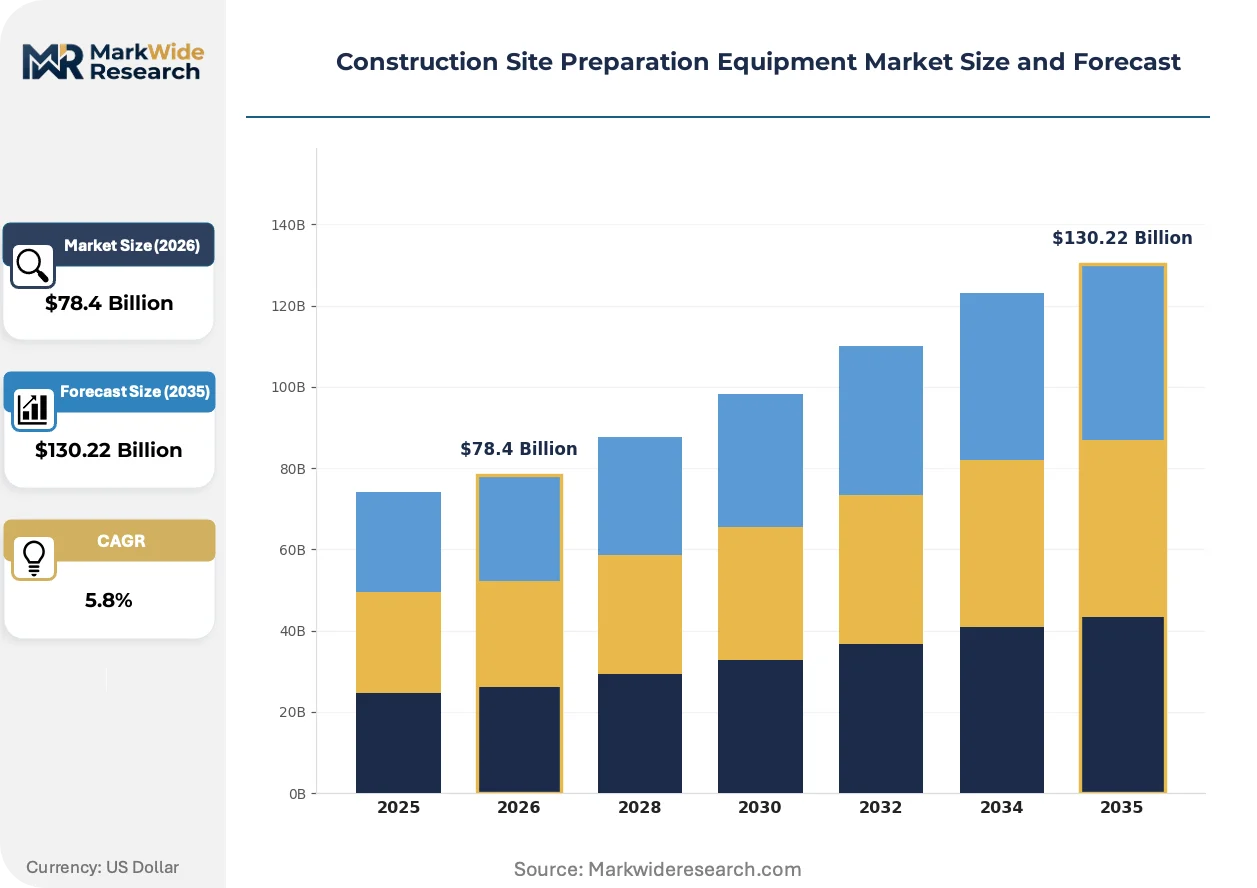
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are collapsing residual values for legacy diesel-only fleets while forcing accelerated replacement cycles across contractor operations. This regulatory compression is restructuring capital deployment patterns and OEM pricing power.
Growth Catalysts
- Intelligent machine control:Factory-integrated GPS grading systems reduce survey labor requirements on civil infrastructure projects. Municipal agencies in Germany are mandating precision excavation for utility tunneling contracts.
- China's MIIT dual carbon goals:Domestic OEM capacity is redirecting toward electric powertrains for municipal construction zones in Beijing and Shanghai. GB 36886 non-road emissions standards are accelerating fleet turnover.
- Suburban residential densification:Developers across the United States are expanding fleet orders for precision grading equipment to support basement excavation volumes in corridor markets.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add base machine pricing pressure. Tier 4 Final compliance compresses margins for non-compliant imports entering North American ports.
- Battery energy density limitations:Lithium-ion pack weights reduce operating payload capacity for electric excavators above 20 metric tons. Charging infrastructure gaps persist across remote construction sites.
- Steel and hydraulic component volatility:Boom cylinder and undercarriage steel pricing fluctuates with commodity cycles. Japanese and German hydraulic system suppliers concentrate critical component supply.
Strategic Opportunities
- Autonomous pre-strip operations:Remote-operated dozers in hazardous mining environments reduce operator exposure. Australian iron ore producers are validating fleet-scale deployments.
- Telematics-linked service contracts:Predictive maintenance platforms monetize machine health data through recurring revenue streams. Dealer networks in the United States are bundling uptime guarantees with equipment sales.
- India's urban infrastructure stimulus:Metro rail and logistics hub construction is concentrating demand for mid-size excavators. PLI scheme incentives support localized component sourcing for cost-sensitive segments.
Industry Challenges
- GPS systems integration:Legacy fleet retrofits require cab display upgrades and antenna mounting modifications. Survey-grade receiver calibration demands specialized technician training.
- OSHA excavation safety certification:Competent person training requirements extend project mobilization timelines. Trench protective system specification adds engineering review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Site Preparation Equipment Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Dump Trucks, Graders Technology: GPS, Hydraulic, Electric, Autonomous Application: Site Clearing, Grading, Excavation, Demolition End User: Contractors, Subcontractors, Developers, Public Sector |
| Companies Covered | Caterpillar, Komatsu, Volvo Group, Liebherr Group, Hitachi Construction Machinery, SANY Group, XCMG Group, CNH Industrial, Doosan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Site Preparation Equipment Market Emerging Trajectories
Diesel-electric hybrid architectures are advancing from prototype to production scale as emissions compliance costs reshape equipment economics. Three convergent developments are redirecting R&D investment and buyer evaluation criteria.
Machine-mounted 3D grade control is supplanting traditional staking crews on linear infrastructure projects. State transportation departments in Texas and California are specifying GPS-guided excavation for highway widening contracts. This displacement is compressing survey labor budgets while elevating equipment specification requirements.
EU Stage V particulate number limits are compelling exhaust after-treatment redesigns across engine supplier portfolios. SCR dosing strategies and DPF regeneration protocols now dominate engineering resource allocation. Compact excavator segments below 10 metric tons face the steepest compliance cost escalation relative to machine value.
Rental channel consolidation is redirecting fleet procurement toward standardized telematics platforms. National equipment lessors in the United States are mandating OEM-agnostic data protocols for mixed-fleet visibility. This interoperability requirement is pressuring proprietary system architectures while elevating third-party platform providers.
Construction Site Preparation Equipment Market Segmentation
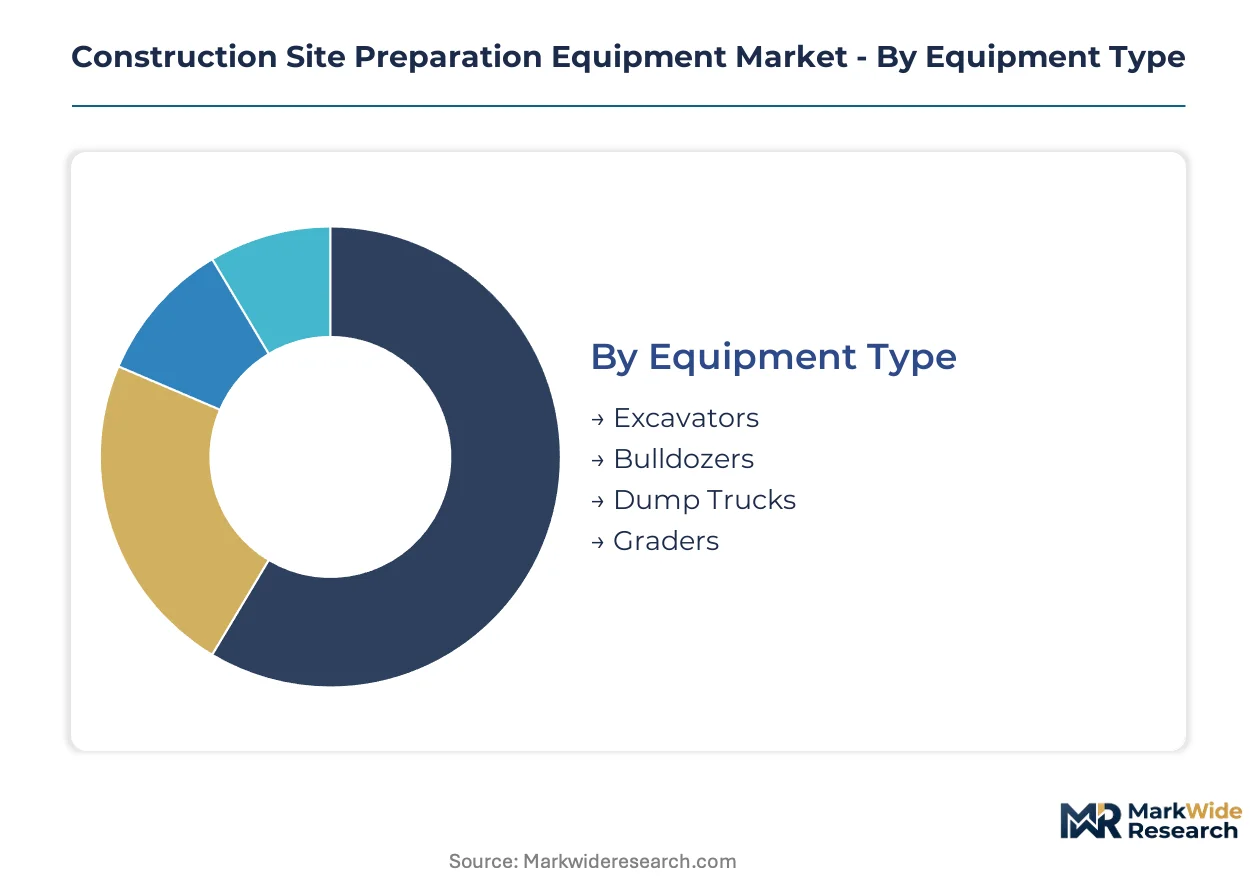
Equipment segmentation in construction site preparation reveals divergent capital deployment patterns across technology tiers and operator sophistication levels. Buyers sort across precision-enabled and conventional platforms based on project scale, labor availability, and regulatory compliance timelines.
Equipment Type:
Domestic fleet composition favors excavators and bulldozers for urban densification projects, while export demand concentrates in dump trucks and graders for resource extraction corridors in Australia and Chile.
- Excavators:Hydraulic models with boom-mounted GPS receivers perform trenching and basement excavation to sub-centimeter accuracy. Municipal utility tunneling contracts in Germany and highway widening projects in Texas are concentrating procurement of 20-35 metric ton units with factory-integrated machine control.
- Bulldozers:Track-type tractors with powertrain options spanning mechanical, hydrostatic, and electric drive configurations. Australian iron ore pre-strip operations are validating autonomous dozer fleets, displacing conventional operator-dependent models in hazardous terrain applications.
- Dump Trucks:Articulated and rigid-frame haulers for material transport across cut-and-fill operations.
- Graders:Motor graders with articulated frame steering and moldboard hydraulics for finished grade establishment.
Excavators command the established base. The steepest expansion runs through bulldozers as remote operation capabilities mature.
Technology:
Technology tiering separates premium-margin precision platforms from cost-optimized conventional equipment, with electrification creating a third cost trajectory between established diesel and emerging battery architectures.
- GPS:Survey-grade positioning systems with machine-mounted receivers and cab-integrated displays reduce staking crew requirements on linear infrastructure projects. State transportation departments in California mandate GPS-guided excavation for highway contracts, compressing survey labor budgets while elevating equipment specification thresholds.
- Hydraulic:Conventional fluid power systems dominate fleet composition below 10 metric tons where after-treatment cost escalation compresses margins for advanced technology adoption.
- Electric:Battery-electric powertrains for municipal construction zones in Beijing and Shanghai under China's MIIT dual carbon goals. Lithium-ion pack weights constrain operating payload above 20 metric tons.
- Autonomous:Remote-operated and fully autonomous platforms validated in Australian mining pre-strips.
Hydraulic systems anchor current fleet composition. Electric platforms are climbing the fastest as charging infrastructure buildouts advance in urban corridors.
Application:
Application segmentation tracks project phase sequencing, with early-stage clearing and grading preceding precision excavation and final demolition across typical construction lifecycles.
- Site Clearing:Vegetation removal and topsoil stripping operations using dozers and excavators with specialized attachments. Suburban residential densification across United States corridor markets is expanding fleet orders for precision clearing equipment.
- Grading:Surface leveling for pavement sub-bases and building pad preparation. GPS-enabled graders establish finished grade with reduced rework cycles.
- Excavation:Trenching, foundation digging, and basement construction.
- Demolition:Structure dismantling and debris processing.
Grading commands the established base. Excavation applications are gaining share fastest as basement excavation volumes remain elevated in urban densification projects.
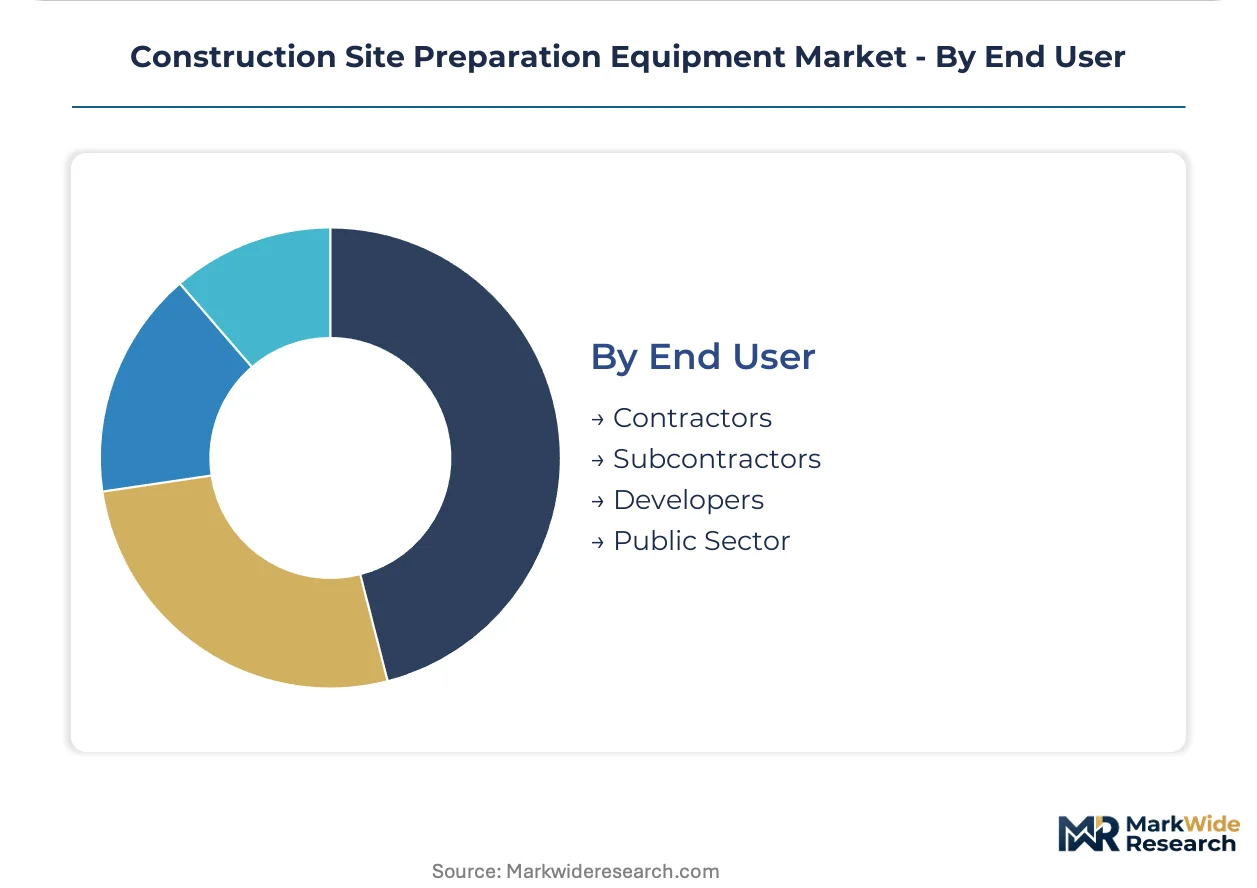
End User:
End user segmentation reflects capital access differentiation, with public sector procurement constrained by budget cycles and contractor fleets responding to equipment financing availability.
- Contractors:General construction firms operating mixed fleets across residential, commercial, and infrastructure projects. Tier 4 Final compliance is collapsing residual values for legacy diesel-only holdings while forcing accelerated replacement cycles.
- Subcontractors:Specialized earthmoving operators providing precision grading and excavation services.
- Developers:Real estate development firms with captive equipment fleets for large-scale master-planned communities.
- Public Sector:Municipal and state transportation departments specifying GPS-guided equipment for highway and utility contracts.
Contractors command the established base. Public sector procurement is expanding most quickly as infrastructure stimulus packages channel capital toward urban densification and logistics hub construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tilting toward regional self-sufficiency as emissions compliance costs reshape cross-border equipment flows. Domestic manufacturing capacity expansion in key markets is displacing traditional import dependency for contractor fleets.
United States
Suburban residential densification across Texas and Florida corridor markets is elevating precision grading equipment procurement. EPA Tier 4 Final enforcement is collapsing residual values for legacy diesel-only fleets held by regional contractors. Houston and Dallas-Fort Worth construction clusters are channeling capital toward GPS-enabled excavators for basement excavation volumes.
Germany
Municipal transportation departments in Bavaria and North Rhine-Westphalia are mandating GPS-guided excavation for highway widening and utility tunneling contracts. EU Stage V particulate number limits are compelling exhaust after-treatment redesigns across contractor fleet replacements. Stuttgart's industrial machinery corridor anchors precision equipment manufacturing for export-bound product lines.
China
MIIT dual carbon goals are redirecting domestic OEM capacity toward electric powertrains for municipal construction zones in Beijing and Shanghai. GB 36886 non-road emissions standards are accelerating fleet turnover in state-backed infrastructure projects. Yangtze River Delta manufacturing clusters are scaling localized component sourcing for cost-sensitive Asian markets.
Australia
Iron ore pre-strip operations in Western Australia's Pilbara region are validating autonomous dozer fleets for hazardous terrain applications. State mining safety regulators are specifying remote-operated equipment for slope stability management. Perth equipment distribution hubs are consolidating procurement for resource extraction corridors across the continent.
India
Metro rail and logistics hub construction in Maharashtra and Karnataka is concentrating demand for mid-size excavators. PLI scheme incentives support localized component sourcing for cost-sensitive earthmoving segments. Mumbai-Pune industrial corridor developers are expanding captive fleet orders for site preparation work.
Construction Site Preparation Equipment Market Vendor Landscape
Listed leaders compete with private specialists across capital access and technology integration dimensions. The vendor base stratifies into three tiers: integrated full-line manufacturers, component specialists, and regional assemblers. Strategic archetypes include telematics-enabled service bundlers, precision control technology licensors, and scale-driven cost optimizers. Dominant competitive moves encompass dealer network consolidation and factory-integrated GPS system partnerships.
Within the integrated manufacturing tier, Caterpillar and Komatsu occupy positions that exemplify divergent strategic emphases. Caterpillar anchors the North American service-contract model through dealer network density. Komatsu represents the intelligent machine control vector with factory-integrated GPS grading systems. SANY Group sits within the scale-driven archetype, leveraging manufacturing footprint for emerging market penetration.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Volvo Group |
| Liebherr Group |
| Hitachi Construction Machinery |
| SANY Group |
| XCMG Group |
| CNH Industrial |
| Doosan Corporation |
| Others |
Supply Flow & Price Mechanics
Battery-electric powertrain substitution for diesel-mechanical systems is redrawing component sourcing maps from Japanese hydraulic clusters toward Korean battery cell facilities while compressing margin structures across traditional engine supplier tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Factory-integrated GPS grading systems command tier-one positioning through reduced survey labor claims, while Tier 4 Final after-treatment compliance separates mid-tier diesel offerings from stripped economy configurations. Cost compression in compact excavator segments below 10 metric tons is intensifying because exhaust after-treatment investments inflate base machine pricing disproportionately. Subcontractor fleets exhibit acute price sensitivity due to project-based financing constraints, whereas public sector procurement demonstrates lower elasticity through infrastructure stimulus allocations.
Supply Chain Analysis
Port congestion on transpacific lanes from Shanghai to Long Beach has elevated inbound logistics costs for hydraulic system components manufactured in Japan and Germany. Critical supply draws from China for steel castings, Germany for precision hydraulics, and South Korea for battery cells. Single-source vulnerability concentrates in German hydraulic pump suppliers serving GPS-enabled grading equipment. Distribution runs through Caterpillar and Komatsu dealer networks with captive parts warehousing, supplemented by independent rental channel consolidation mandating OEM-agnostic telematics protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of technicians certified in survey-grade GPS receiver calibration and autonomous fleet management software is constraining adoption velocity and creating premium capture opportunities for capability holders.
For Market Incumbents: Fortify aftermarket revenue through telematics-linked service contracts bundling predictive maintenance with uptime guarantees. Deepen backward integration into battery pack assembly to offset Korean cell supplier pricing power. Defend against SANY Group scale threats by anchoring dealer network density in suburban U.S. corridor markets. For New Entrants and Emerging Players: Anchor in India's mid-size excavator segment where PLI scheme incentives reduce landed cost disadvantages against established OEMs. Target municipal electric fleet mandates in Beijing and Shanghai where charging infrastructure buildouts outpace legacy OEM capacity allocation. Pursue white-label GPS integration partnerships with German transportation departments specifying precision excavation contracts. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors OEMs with certified electric powertrain platforms and captive financing arms. Long-term viability hinges on battery energy density trajectories crossing total cost of ownership thresholds against diesel baselines. Monitor charging infrastructure deployment rates in urban construction zones as the inflection signal for fleet electrification commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Dealer networks in Texas bundle uptime guarantees with GPS-enabled excavator sales. |
| Battery Supply Agreement | Korean cell manufacturers anchor electric excavator production for Beijing municipal fleets. |
| Precision Control Licensing | Komatsu's factory-integrated GPS grading reduces survey crew requirements on German highway contracts. |
| Dealer Network Expansion | Caterpillar sustains parts revenue density through service-contract penetration in Houston construction clusters. |
| Autonomous Fleet Validation | Australian iron ore producers validate remote-operated dozers for hazardous pre-strip terrain applications. |
Methodological Framework
Operator-level perspectives from fleet maintenance directors, municipal procurement officers, OEM product managers, and rental channel operations heads anchored the qualitative base. Secondary validation drew from EPA enforcement disclosures, EU Stage V certification databases, China MIIT policy circulars, and SEC equipment manufacturer filings. Bottom-up equipment shipment tracking triangulated against top-down infrastructure spending allocation models.
Sensitivity analysis tested forecast outputs against battery cost decline trajectories and emissions compliance timeline shifts across the projection horizon. Segmentation modeling spanned equipment type, technology tier, application phase, and end-user capital access. CAGRs derived from historical replacement cycle analysis and stimulus package disbursement schedules. Industry-specific inputs included steel commodity pricing volatility and hydraulic component lead time fluctuations.
Material uncertainties — battery energy density breakthroughs, charging infrastructure buildout delays, and emissions standard enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory adherence and technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Grout Bags Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Blanking Machine Market
Construction Equipment
GCC Crane Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Boom Cranes Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market