
 LAMEA Water Pump Market | 2026-2036
LAMEA Water Pump Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Water Pump Market Insights
Aftermarket service revenue is fragmenting across the LAMEA Water Pump landscape as OEMs and independent providers compete for recurring maintenance contracts. Xylem leverages its digital monitoring platforms to capture long-term service agreements. KSB Group anchors its regional position through localized manufacturing and spare-part distribution networks. Grundfos differentiates via energy-efficient pump technologies tailored to intermittent grid conditions.
A water pump is a mechanical device that imparts kinetic energy to move fluids through piping systems, typically operating at pressures from 1 bar to over 100 bar depending on application requirements, and serves to transfer, circulate, or pressurize water in industrial, agricultural, and municipal settings. Centrifugal pumps occupy the dominant volume position due to their simplicity and broad flow-rate range across irrigation and water supply applications. Submersible pumps represent the fastest-expanding category as borehole irrigation deepens across drought-prone zones. Positive displacement pumps retain premium margins in wastewater treatment where precise sludge handling demands positive suction capabilities.
Brazil's ANA water-use regulations, Mexico's CONAGUA efficiency standards, and South Africa's SABS pressure-rating requirements collectively elevate minimum performance thresholds and restrict market access for non-compliant equipment. These frameworks push end-users toward higher-efficiency electric and solar-powered configurations, particularly in regions with tariff-sensitive agricultural operations. Stakeholders must monitor how distributed solar-hybrid pumping architectures reshape procurement criteria and service-model economics across the region.
Market Dynamics
ANA efficiency mandates are compressing equipment replacement cycles across Brazil's municipal utilities, forcing distributors to pivot toward higher-margin service contracts as hardware margins erode.
Growth Catalysts
- ANA water-use regulations:Brazil's tightening efficiency thresholds accelerate replacement of aging centrifugal infrastructure in São Paulo's water utility network.
- Borehole irrigation expansion:Submersible pump deployment deepens across Mexico's drought-prone northern states as groundwater access becomes critical for crop protection.
- CONAGUA efficiency standards:Mexico's federal water commission mandates minimum performance ratings that redirect procurement toward variable-frequency drive configurations.
Market Restraints
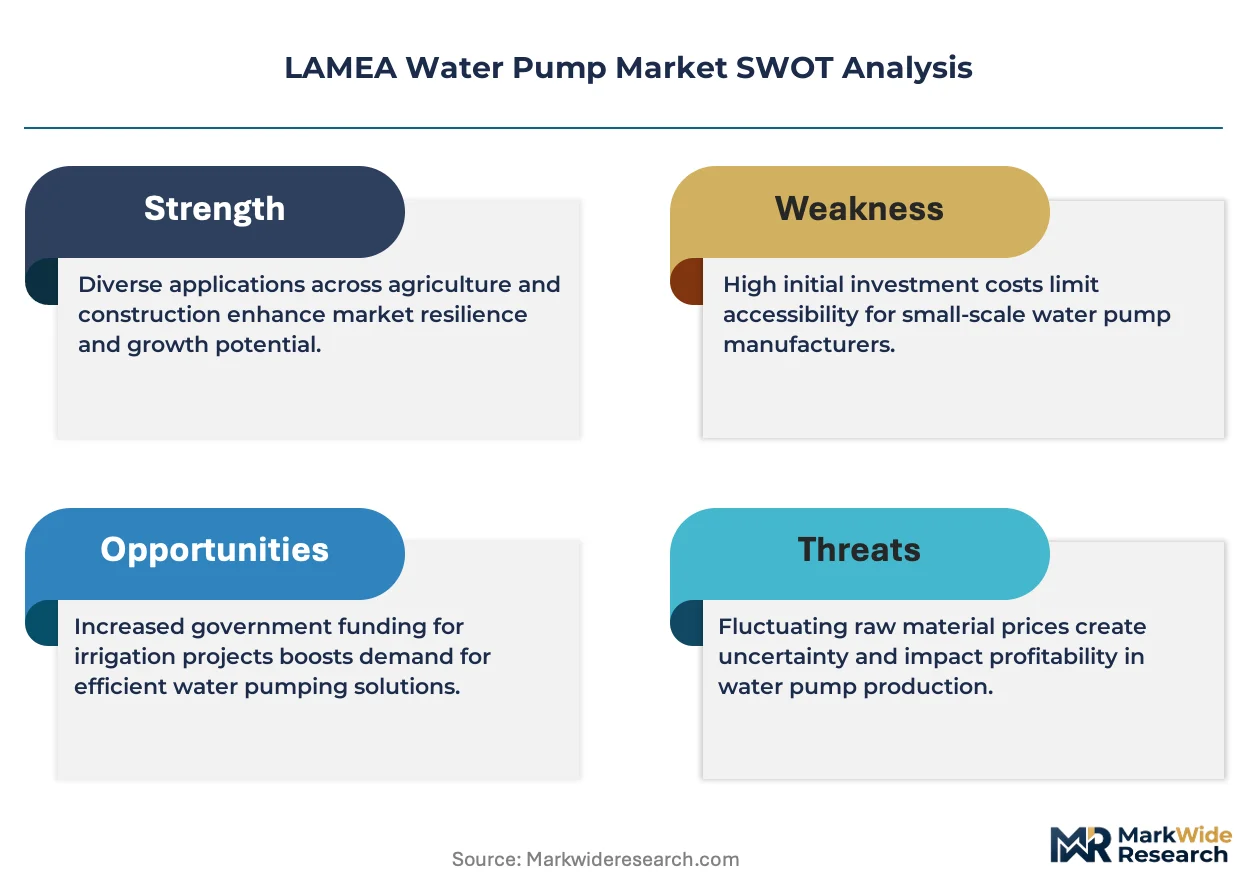
- Copper and rare-earth input volatility:Motor winding costs fluctuate with commodity indexes, squeezing margin predictability for Brazilian pump assemblers.
- Import dependency for precision bearings:LAMEA manufacturers rely on European and East Asian suppliers for submersible pump seal assemblies.
- Grid intermittency in rural zones:Unreliable electricity supply limits adoption of high-efficiency electric pumps in Argentina's remote agricultural belts.
Strategic Opportunities
- Solar-hybrid architectures:Distributed photovoltaic pumping systems unlock off-grid irrigation in South Africa's Northern Cape province.
- Wastewater treatment upgrades:Positive displacement sludge pumps capture premium positioning as Chile expands municipal tertiary treatment capacity.
- Digital monitoring platforms:IoT-enabled predictive maintenance contracts create recurring revenue streams beyond hardware sales.
Industry Challenges
- Certification timeline compression:SABS pressure-rating approvals in South Africa extend lead times for new product introductions.
- Retrofit integration complexity:Variable-speed drives must interface with legacy control systems in aging Brazilian industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Water Pump Market |
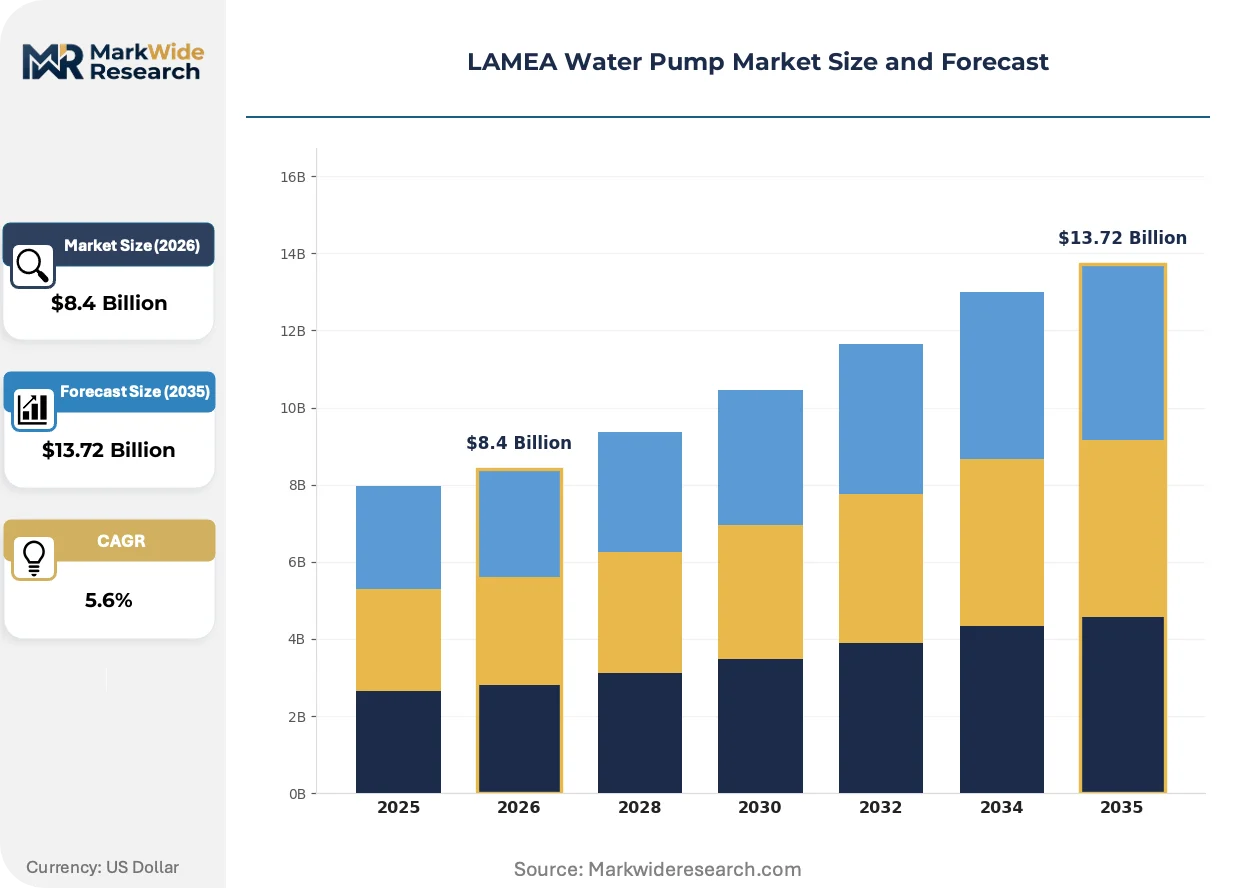
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Submersible Pumps, Positive Displacement Pumps, Peristaltic Pumps End User: Agriculture, Residential, Industrial, Commercial Power Source: Electric, Diesel, Solar, Hydraulic Application: Irrigation, Water Supply, Drainage, Wastewater Treatment |
| Companies Covered | Xylem, KSB Group, Grundfos, Sulzer Ltd, WILO SE, Flowserve, Dover Corporation, Ebara Corporation, Alfa Laval, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Water Pump Market Trends and Innovations
Digital instrumentation is rewriting equipment economics across the LAMEA water pump landscape, compressing maintenance intervals and shifting vendor relationships toward continuous monitoring arrangements.
Variable-frequency drive technology is virtualizing traditional fixed-speed pump architectures. Municipal utilities in Mexico City and São Paulo are retrofitting existing installations with VFD modules to modulate flow without throttling losses. This virtualization is collapsing the historical distinction between premium and standard equipment tiers.
CONAGUA efficiency standards and Brazil's ANA regulations are synchronizing minimum performance thresholds across the region. Equipment distributors must now maintain dual certification inventories or risk exclusion from public tender processes. Agricultural cooperatives in Mexico's Sonora region respond by consolidating procurement through certified dealer networks.
Service unbundling is fragmenting traditional supply relationships. End-users in South Africa's mining sector now separate hardware acquisition from installation and maintenance, awarding multi-year monitoring contracts to specialized providers. This pattern spreads fastest in water-intensive industrial corridors where downtime costs exceed capital expenditure premiums.
LAMEA Water Pump Market Segmentation
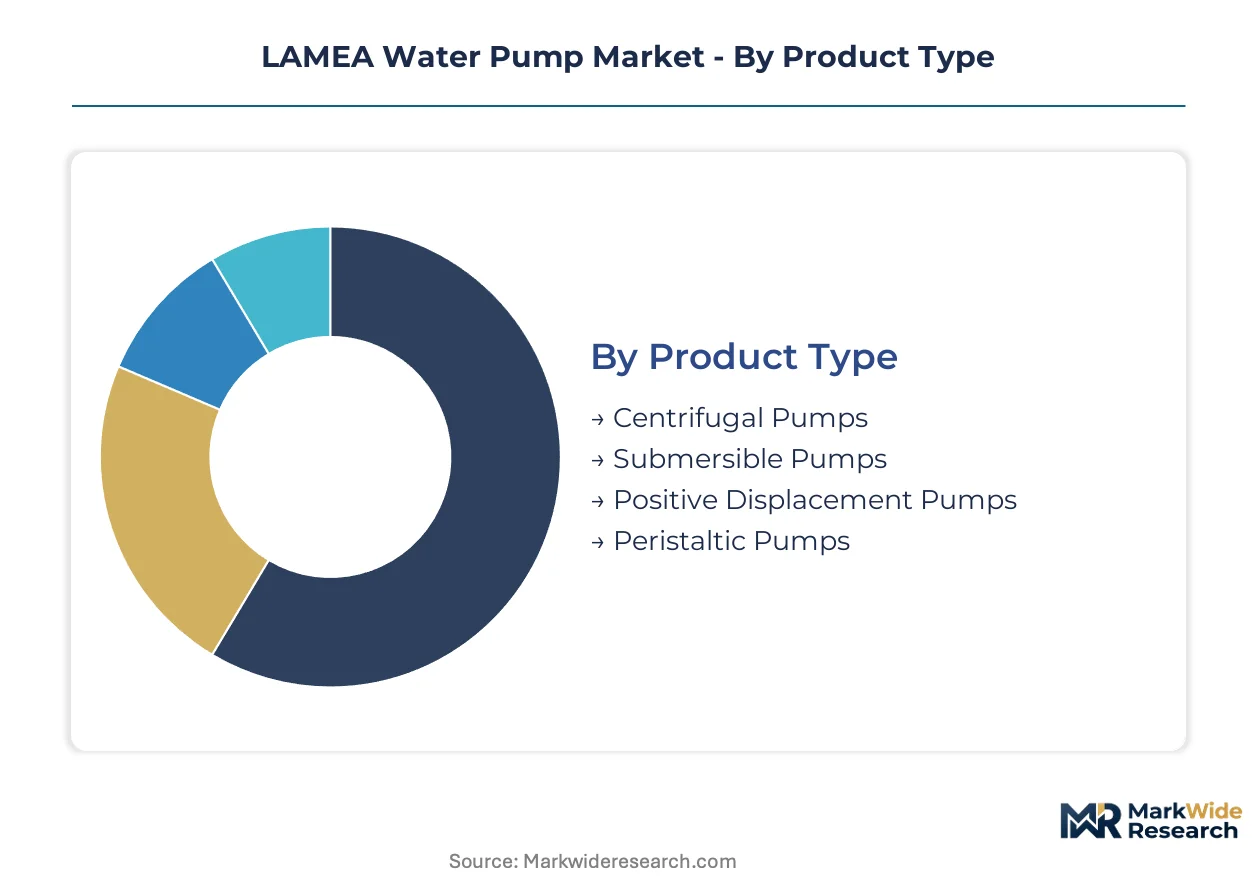
Water pump procurement across Latin America, Middle East, and Africa fragments across four intersecting dimensions. Product architecture, power configuration, and end-use intensity create divergent margin structures and service-model requirements for equipment suppliers.
Product Type:
The use-case spectrum spans high-volume fluid transfer in irrigation networks to precision sludge handling in municipal treatment plants, with each architecture optimizing for efficiency, pressure tolerance, or solids passage.
- Centrifugal Pumps:Impeller-driven kinetic energy transfer dominates irrigation and water supply infrastructure across Brazil's southeastern industrial corridor. ANA efficiency mandates accelerate replacement of aging fixed-speed installations in São Paulo's municipal utility network.
- Submersible Pumps:Sealed motor-housing assemblies operate submerged in boreholes, delivering pressurized lift from deep groundwater tables. Deployment deepens across Mexico's drought-prone northern states as agricultural cooperatives drill deeper for crop protection.
- Positive Displacement Pumps:Reciprocating or rotary mechanisms deliver precise volumetric flow for viscous fluids and sludge. Premium positioning in Chile's expanding tertiary wastewater treatment capacity.
- Peristaltic Pumps:Hose-compression design isolates fluid from mechanical components, enabling sterile or abrasive handling. Chemical dosing and mining leachate applications in South Africa's Northern Cape.
Established volume favors centrifugal infrastructure; emerging adoption favors submersible borehole systems.
End User:
Customer-type concentration varies sharply by margin tier and service-contract attach rates.
- Agriculture:Irrigation-dependent operations across Argentina's Pampas and Mexico's Sonora valley drive demand for solar-hybrid and diesel-backup configurations. Tariff-sensitive cooperatives consolidate procurement through certified dealer networks meeting CONAGUA standards.
- Industrial:Mining, pulp, and petrochemical operations require continuous-duty pumps with predictive maintenance integration. South African mining houses now unbundle hardware from multi-year monitoring contracts.
- Residential:Pressure-boosting and sump applications concentrate in urban peripheries with intermittent grid supply. Variable-frequency retrofits penetrate São Paulo's informal settlement upgrading programs.
- Commercial:HVAC circulation and fire-suppression systems in office and retail developments. SABS pressure-rating compliance extends lead times for new building certifications.
Volume leadership sits with agricultural procurement; margin expansion concentrates in industrial service agreements.
Power Source:
Energy architecture determines operational economics across grid-connected and off-grid deployment zones.
- Electric:Grid-tied AC motor drives dominate municipal and industrial installations where supply reliability permits. VFD retrofits in Mexico City and São Paulo modulate flow without throttling losses.
- Solar:Photovoltaic arrays with DC motors or battery-buffered AC systems unlock off-grid irrigation. Distributed solar-hybrid architectures reshape procurement criteria in South Africa's Northern Cape.
- Diesel:Internal combustion drives retain relevance in remote agricultural belts with unreliable electricity. Argentina's remote pumping stations depend on fuel logistics networks.
- Hydraulic:Fluid-power actuation serves mobile and explosion-risk environments. Specialized mining and construction dewatering applications.
Electric configurations anchor installed base; solar architectures gain share fastest in tariff-sensitive zones.
Application:
Functional deployment determines pump specification, duty cycle, and regulatory exposure.
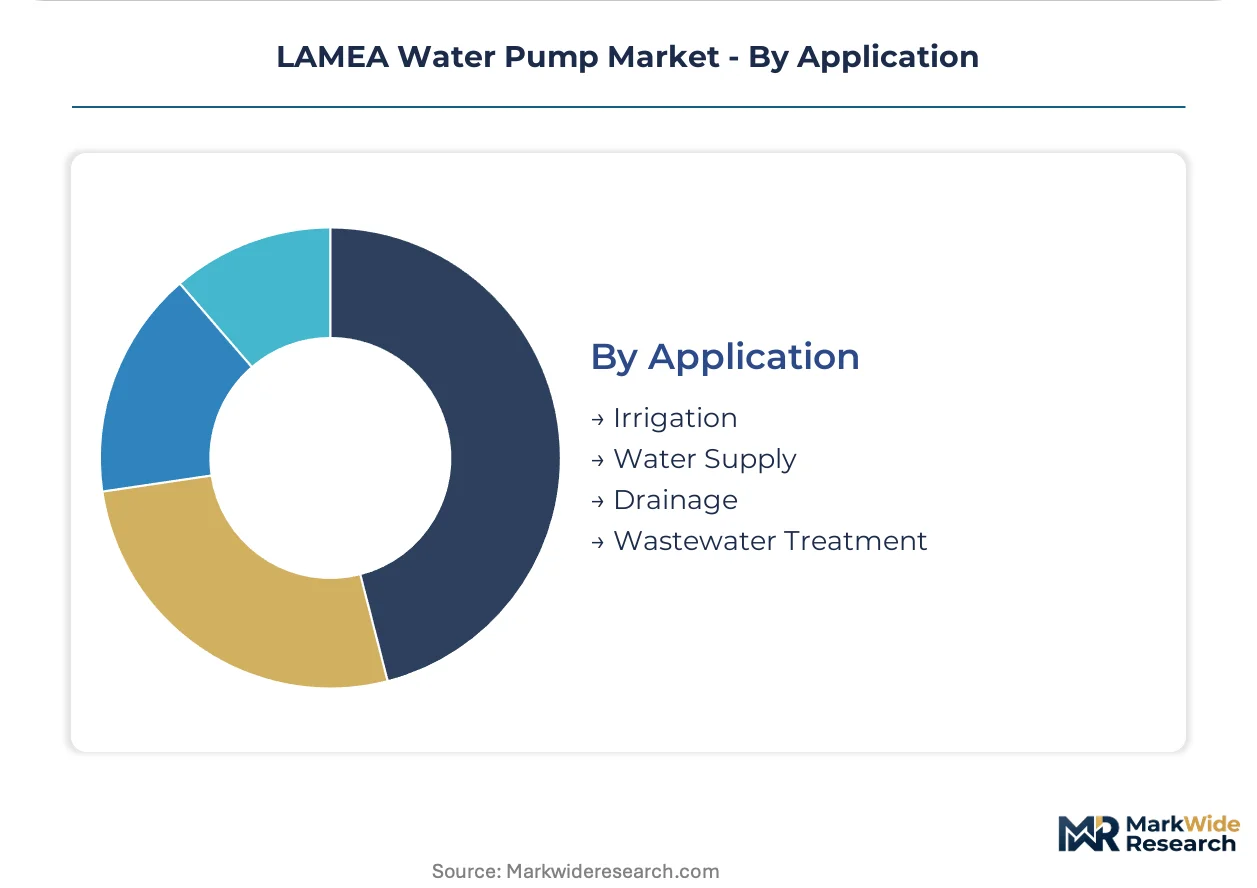
- Irrigation:Surface and pressurized distribution networks account for dominant flow-volume demand. Borehole deepening across drought-prone zones elevates submersible specifications.
- Water Supply:Potable distribution and pressure boosting in municipal networks. ANA regulations compress replacement cycles for efficiency-noncompliant centrifugal infrastructure.
- Drainage:Stormwater and groundwater removal in mining, construction, and low-lying urban zones. Seasonal demand spikes in Brazil's coastal cities.
- Wastewater Treatment:Sludge transfer, tertiary filtration, and effluent discharge. Positive displacement pumps capture premium positioning as Chile expands municipal treatment capacity.
Irrigation commands flow-volume dominance; wastewater treatment offers steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural cooperatives in Mexico's Sonora valley exhibit the sharpest price elasticity, while South African mining houses absorb premium service premiums with minimal procurement friction.
Brazil
São Paulo's municipal utility network drives centrifugal pump replacement cycles under ANA efficiency mandates. The national water regulator tightens performance thresholds quarterly, forcing distributors to pivot toward service contracts. Brazil's southeastern industrial corridor concentrates demand from pulp and petrochemical operations.
Mexico
Borehole irrigation deepens across drought-prone northern states as groundwater tables recede. CONAGUA efficiency standards redirect procurement toward variable-frequency drive configurations. Agricultural cooperatives in Sonora consolidate purchases through certified dealer networks meeting federal certification requirements.
South Africa
Mining houses in the Northern Cape unbundle hardware acquisition from multi-year monitoring contracts. SABS pressure-rating approvals extend lead times for new product introductions. Johannesburg-Pretoria industrial corridor anchors demand for predictive maintenance integration.
Argentina
Remote agricultural belts in the Pampas depend on diesel-backup configurations due to grid intermittency. The country's national water commission maintains fragmented regulatory oversight across provincial jurisdictions. Mendoza's wine-growing cooperatives deploy solar-hybrid architectures for tariff-sensitive irrigation.
Chile
Municipal tertiary treatment expansion drives premium positioning for positive displacement sludge pumps. The national environmental regulator enforces discharge standards tightening equipment specifications. Santiago-Valparaíso corridor concentrates wastewater infrastructure investment.
LAMEA Water Pump Market Competitive Landscape
Full-service OEMs and specialized component fabricators split the market along service-integration lines. European-headquartered multinationals anchor premium positioning through digital monitoring platforms. Asian manufacturers occupy mid-tier volume segments via standardized centrifugal configurations. Dominant competitive moves include backward integration into motor winding operations and geographic expansion through certified dealer networks.
Within the full-service OEM tier, Xylem and KSB Group exemplify divergent regional strategies. Xylem leverages its North American origins to anchor digital service agreements across Brazilian municipal utilities. KSB Group, structured as a German Aktiengesellschaft, reinforces its position through localized manufacturing presence. Grundfos occupies a distinct efficiency-specialist position, with its Danish corporate form signaling concentrated R&D investment in variable-speed architectures.
| Leading Market Players |
|---|
| Xylem |
| KSB Group |
| Grundfos |
| Sulzer Ltd |
| WILO SE |
| Flowserve |
| Dover Corporation |
| Ebara Corporation |
| Alfa Laval |
| Others |
Pricing and Supply Chain Analysis
Copper and rare-earth input volatility compresses margin predictability for Brazilian pump assemblers while simultaneously widening pricing spreads between certified and non-certified equipment tiers. This commodity-driven risk vector forces distributors to anchor profitability in after-sales service contracts rather than hardware margins alone.
Pricing Analysis
Aftermarket service revenue—spanning spare parts, preventive maintenance, and multi-year monitoring agreements—drives lifetime value capture across the LAMEA water pump landscape. Pricing stratifies across premium certified, standard compliant, and economy non-certified tiers, with ANA and CONAGUA certification levels serving as the primary differentiation driver. Cost compression in the economy tier is intensifying as Asian manufacturers push standardized centrifugal configurations into price-sensitive agricultural cooperatives. Municipal utilities in São Paulo and Mexico City exhibit the lowest price sensitivity, absorbing premium positioning for predictive maintenance integration.
Supply Chain Analysis
Extended payment terms from European and East Asian bearing suppliers strain working capital for LAMEA pump assemblers, particularly those serving Brazil's southeastern industrial corridor. Manufacturing concentrates in Germany, China, and Denmark for precision motor components and digital monitoring platforms. Supply chains draw from Chilean copper mines, Chinese rare-earth processors, and German precision engineering for submersible seal assemblies. Single-source vulnerability for submersible pump bearings creates exposure to logistics chokepoints at Rotterdam and Singapore transshipment hubs. Distribution runs through certified dealer networks in Mexico's Sonora valley and South Africa's Northern Cape mining belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA water pump market operates as a defensive-moat arena where regulatory certification entrenchment creates switching costs that lock municipal utilities into established service relationships. This structural advantage favors incumbents with localized spare-part distribution and ANA-compliant product portfolios.
For Market Incumbents: Build switching-cost moats by embedding IoT-enabled predictive maintenance platforms into São Paulo's municipal utility contracts, creating data-driven dependency that raises replacement costs. Anchor backward integration into motor winding operations to offset copper price volatility squeezing Brazilian assemblers. Threaten margin erosion from solar-hybrid entrants by pre-empting CONAGUA-certified dealer network expansion across Mexico's northern states. For New Entrants and Emerging Players: Build out solar-hybrid pumping architectures targeting Argentina's remote Pampas agricultural belts where grid intermittency limits incumbent electric pump penetration. Capture white-space in South Africa's Northern Cape off-grid irrigation through distributed photovoltaic configurations bypassing diesel logistics networks. Pursue certified dealer partnerships in Chile's tertiary wastewater treatment corridor where positive displacement pump margins remain elevated. For Investors and Strategic Acquirers: ANA's quarterly efficiency threshold tightening reshapes the acquisition landscape toward service-integrated OEMs with localized manufacturing footprints. Long-term viability centers on digital platform ownership rather than hardware volume across the projection horizon. Target mid-cap specialists with captive spare-part distribution in Brazil's southeastern industrial corridor. Monitor CONAGUA certification backlog clearance rates as the inflection indicator for Mexican market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Winding | Brazilian assemblers offset copper volatility through captive coil production. |
| Solar-Hybrid Architecture Certification | CONAGUA compliance unlocks tariff-sensitive agricultural procurement in Sonora. |
| Predictive Maintenance Platform Deployment | IoT contracts create recurring revenue beyond São Paulo hardware sales. |
| Certified Dealer Network Expansion | ANA-compliant distribution captures replacement cycle acceleration. |
| Submersible Seal Assembly Localization | Domestic bearing production reduces European import dependency exposure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANA regulatory filings, CONAGUA efficiency standard databases, and SABS pressure-rating documentation. The research program combined structured interviews with maintenance directors at Brazilian pulp operations, procurement leads at Mexican agricultural cooperatives, aftermarket service heads at South African mining houses, and plant engineers at Chilean municipal treatment facilities. Secondary validation drew from customs trade data, SEC 10-K disclosures of listed pump manufacturers, and utility capex budget filings. Bottom-up equipment shipment tracking and top-down infrastructure investment analysis were triangulated to establish market sizing.
Forecast inputs include product type segmentation across centrifugal, submersible, and positive displacement architectures; power source configuration spanning electric, solar, and diesel; end-use intensity differentiating agricultural, industrial, and municipal demand; and regional regulatory cluster alignment with ANA, CONAGUA, and SABS compliance tiers. CAGRs were derived through installed base replacement cycle modeling and infrastructure investment pipeline analysis. Industry-specific inputs incorporate borehole deepening rates across Mexico's northern states and solar-hybrid adoption elasticity in South Africa's Northern Cape.
Practitioners should monitor ANA efficiency threshold escalation, CONAGUA certification backlog clearance, and copper price index volatility for early signals of forecast revision pressure. The analysis reflects assumptions regarding regulatory enforcement continuity and commodity supply normalization. Macroeconomic deviation, regulatory enforcement suspension, or breakthrough solar pump cost reduction would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Suction Excavator Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Winch Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Global Excavators Market
Construction Equipment
United States Crane Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Baler Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
North America Construction Equipment Market