
 Industrial Nailers Market | 2026-2036
Industrial Nailers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Nailers Market Analysis
Specialty industrial distributors is reconfiguring how pneumatic and cordless fastening equipment reaches end users, with regional supply houses consolidating shelf space around high-velocity brands. Stanley Black & Decker leverages its DeWalt battery platform to cross-sell cordless nailers into existing contractor bases. Illinois Tool Works anchors professional-grade pneumatic lines through Paslode and Ramset channels that serve commercial framing crews. MAX Co., Ltd. competes in precision coil-nailer segments where Japanese manufacturing tolerances command premium placement in furniture and finish-carpentry outlets.
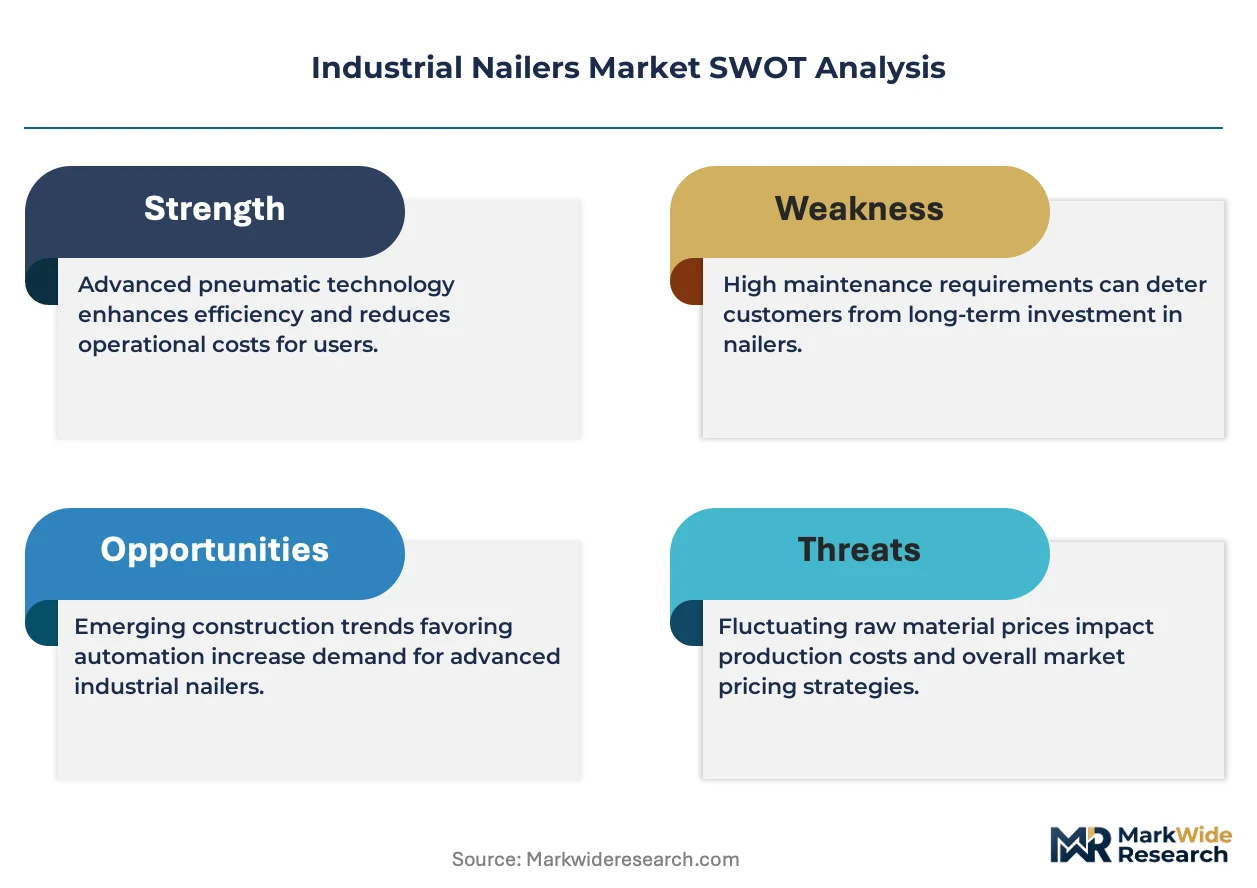
An industrial nailer is a powered fastening tool that drives metal nails into wood, composite, or concrete substrates using pneumatic pressure, explosive gas charges, or lithium-ion battery cells, typically operating at 70–120 PSI for pneumatic units or 18–20 volts for cordless variants. Its primary commercial purpose is to accelerate structural assembly and reduce manual hammer labor in high-volume construction, manufacturing, and packaging environments. Pneumatic nailers retain dominance in heavy framing and commercial concrete-forming where sustained air supply delivers consistent driving force, while cordless electric nailers capture share among renovation contractors and DIY enthusiasts seeking jobsite mobility without compressor logistics. Gas nailers occupy a narrowing niche in remote exterior finishing where neither compressed air nor electrical infrastructure proves practical.
OSHA noise and respirable silica standards shape product design by pushing manufacturers toward lower-decision cordless alternatives and integrated dust-collection compatibility on concrete-fastening tools. EPA emissions guidelines for small off-road gasoline engines indirectly constrain gas-nailer development, while ISO 11148 safety specifications for hand-held non-electric power tools govern international export certification requirements. Stakeholders must monitor battery-cell chemistry advances and regional energy-transition policies that could accelerate or impede cordless platform adoption against entrenched pneumatic infrastructure.
Market Dynamics
OSHA silica and noise exposure mandates are compressing pneumatic tool deployment timelines across US residential construction, forcing contractors to absorb cordless platform costs ahead of traditional replacement cycles.
Growth Catalysts
- OSHA Permissible Exposure Limits:The 2016 silica rule and ongoing noise enforcement push framing crews toward battery-powered alternatives that eliminate compressor noise and dust generation at the point of use.
- Housing starts concentration:Large-scale multifamily and single-family residential development in the United States absorbs high-velocity fastening equipment at volumes that sustain manufacturer R&D amortization.
- Lithium-ion cell energy density:Advances in 21700 and 4680 battery formats extend cordless nailer runtime to full-shift duration, removing the primary performance gap against pneumatic systems.
Market Restraints
- Pneumatic infrastructure sunk costs:Commercial framing operations with existing compressor fleets and reticulated air systems face capital inefficiency when switching to battery platforms.
- Neodymium and lithium supply concentration:Rare earth processing in China and lithium refining bottlenecks create input cost volatility for cordless motor and battery pack production.
- Gas-nailer EPA constraints:Small off-road engine emissions standards restrict development of combustion-powered fastening tools for remote exterior applications.
Strategic Opportunities
- Commercial retrofit acceleration:Building envelope upgrades and tenant improvement cycles in aging US office stock create demand for low-noise fastening in occupied structures.
- Integrated dust collection:Concrete-forming crews require OSHA-compliant silica capture on powder-actuated and gas-powered tools, opening premium attachment markets.
- Rental channel expansion:Tool rental centers are building cordless nailer fleets to serve renovation contractors who avoid capital ownership.
Industry Challenges
- Cross-platform battery incompatibility:Proprietary 18-20V battery ecosystems lock contractors into single-brand tool portfolios, complicating fleet standardization decisions.
- ISO 11148 certification timelines:International export requirements for hand-held non-electric power tools delay product launches in European and Asia-Pacific markets.
- Technician training gaps:Pneumatic troubleshooting expertise among service technicians does not transfer to battery management system diagnostics and cell replacement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Nailers Market |
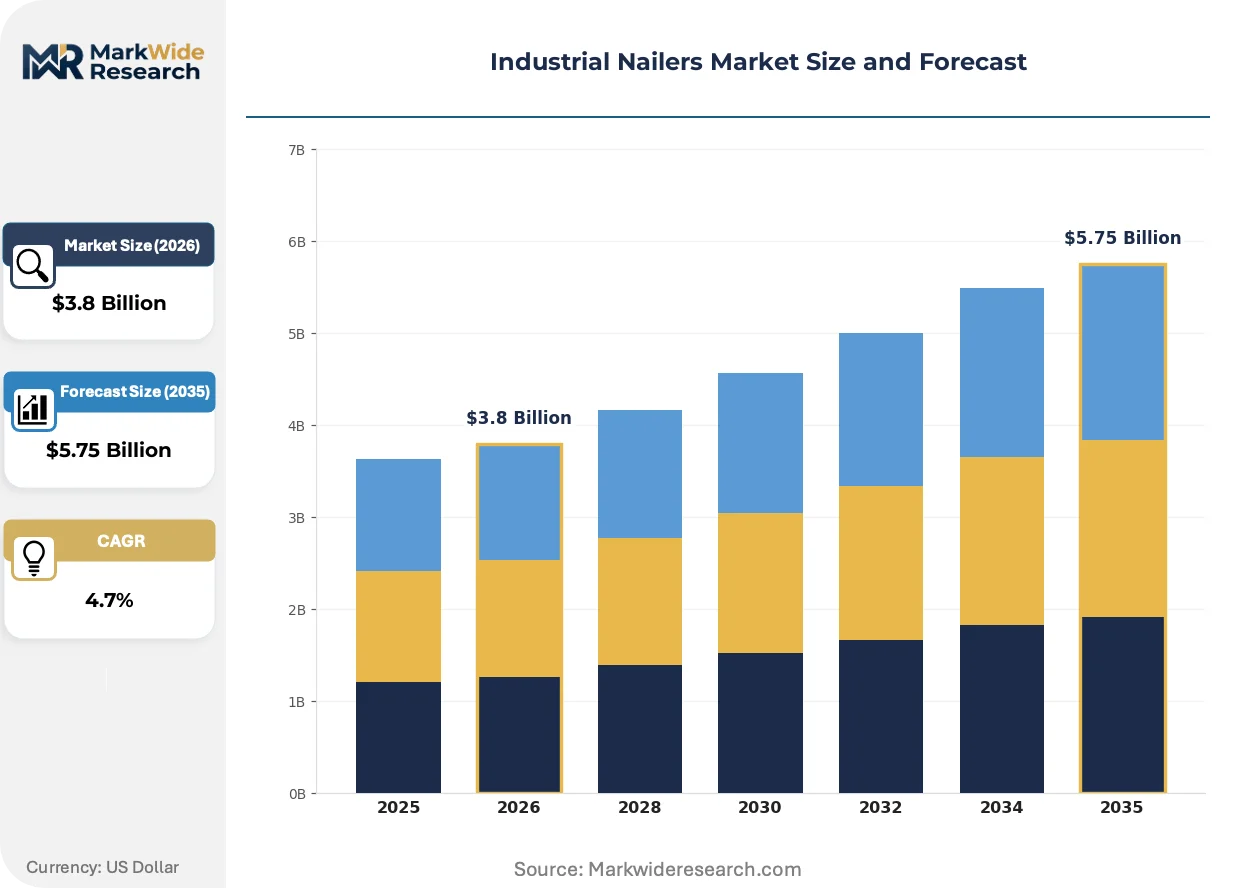
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric Nailers, Pneumatic Nailers, Cordless Nailers, Gas Nailers Application: Construction, Furniture Assembly, Woodworking, Packaging End User: Contractors, Manufacturers, DIY Enthusiasts, Builders Size: Small, Medium, Large, Extra-Large |
| Companies Covered | Stanley Black & Decker, Illinois Tool Works, MAX Co., Ltd., Techtronic Industries, Robert Bosch Power Tools, Apach Industrial Co., Ltd., Aerosmith Fastening, Kyocera Corporation, Raimund Beck KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Nailers Market Emerging Trajectories
Fastening technology is bifurcating between sustained-force pneumatic systems and intelligent battery platforms, with regulatory pressure accelerating the transition timeline beyond natural replacement cycles.
Brushless DC motor architecture is migrating from premium contractor-grade tools toward mid-tier professional segments. Finish carpentry and trim crews operating in occupied residential structures adopt these motors for reduced noise signatures and variable speed control. The technology is migrating from niche cabinet shops toward mainstream renovation contractors, compressing the price premium between pneumatic and cordless alternatives.
REACH substance restrictions and EU F-Gas Regulation are eliminating hydrofluorocarbon propellants in gas-actuated fastening cartridges. European manufacturers reformulate gas nailer chemistry around hydrocarbon alternatives, triggering recertification requirements across Paslode-compatible tool lines. Germany and France exhibit the fastest regulatory compliance transitions, with distributors clearing legacy inventory ahead of 2027 enforcement windows.
Service bundling is altering how contractors acquire fastening equipment. Rental centers and distributor finance programs now package nailers with consumables and maintenance agreements, displacing traditional capital purchase models. Specialty industrial distributors in the United States lead this shift, with regional supply houses consolidating shelf space around brands offering integrated fleet management platforms.
Industrial Nailers Market Segmentation
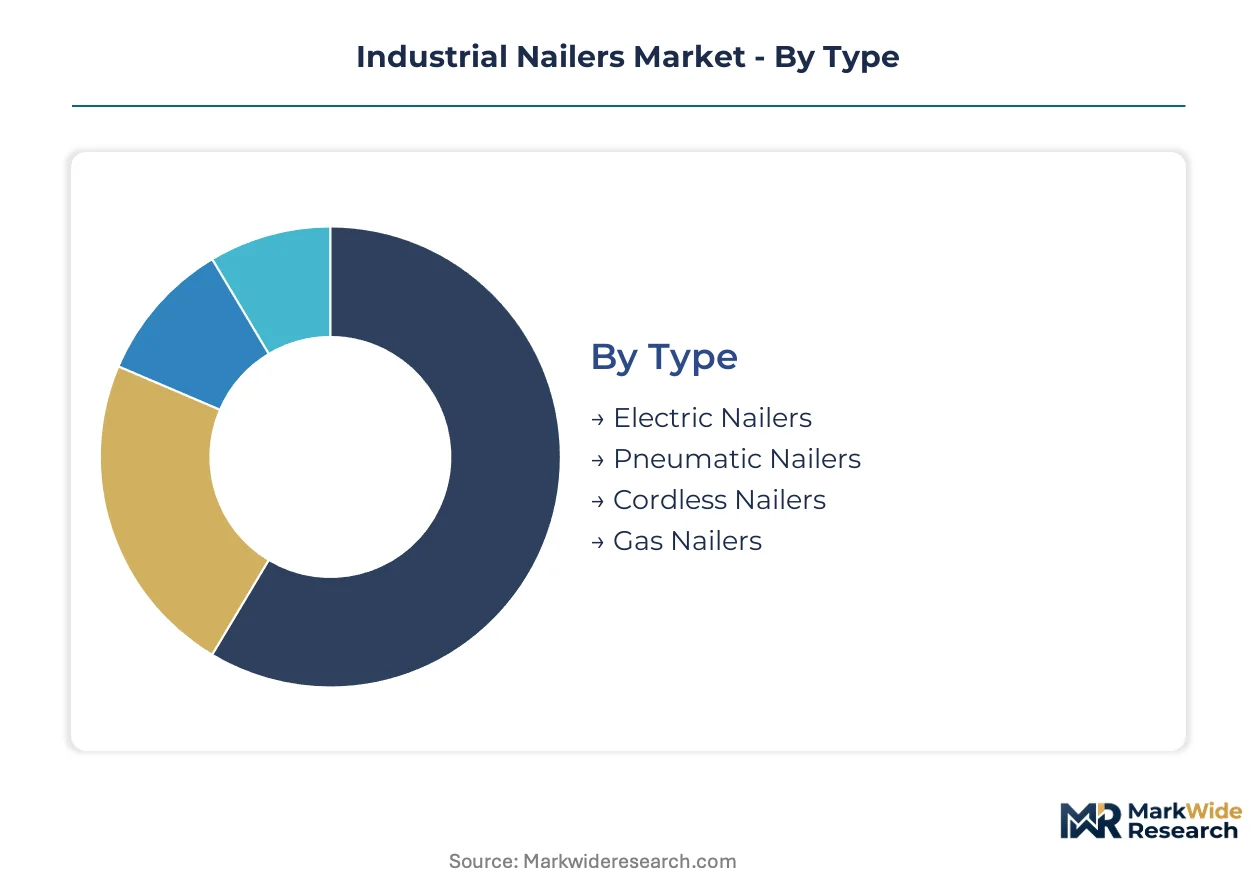
Industrial nailer segmentation reveals how power source preferences, application intensity, and operator sophistication fragment procurement patterns across construction and manufacturing verticals. Understanding these divides exposes where cordless platforms displace pneumatic infrastructure and where gas-actuated tools retain defensible niches.
Type:
The use-case spectrum spans from continuous-production framing crews to intermittent finish carpenters, with power delivery economics determining tool selection.
- Pneumatic Nailers:These compressed-air systems operate at 70–120 PSI and dominate heavy framing and commercial concrete-forming where sustained air supply delivers consistent driving force into dense substrates. Demand concentrates among US residential construction contractors running established compressor fleets, though OSHA silica and noise exposure mandates now compress deployment timelines and force premature fleet evaluations.
- Cordless Nailers:Lithium-ion battery platforms at 18–20 volts capture renovation contractors and DIY enthusiasts seeking jobsite mobility without compressor logistics. Advances in 21700 and 4680 cell formats extend runtime to full-shift duration, removing the primary performance gap against pneumatic systems in US multifamily housing starts.
- Electric Nailers:Corded electric variants serve stationary workshop applications where power consistency outweighs portability requirements.
- Gas Nailers:Combustion-powered tools occupy narrowing niches in remote exterior finishing where neither compressed air nor electrical infrastructure proves practical.
The dominant share belongs to Pneumatic Nailers, while Cordless Nailers is closing the gap fastest.
Application:
Cost tier separation distinguishes high-volume structural assembly from precision finish work.
- Construction:Structural framing, sheathing, and roofing operations in large-scale US housing developments absorb high-velocity fastening equipment at volumes that sustain manufacturer R&D amortization. OSHA compliance pressure accelerates cordless adoption in occupied-structure renovations.
- Furniture Assembly:Precision coil-nailer segments command premium placement in cabinet shops and upholstery operations where Japanese manufacturing tolerances drive specification requirements.
- Woodworking:Finish carpentry and trim crews operating in occupied residential structures adopt brushless DC motors for reduced noise signatures.
- Packaging:High-speed crate and pallet assembly lines in distribution centers utilize pneumatic stapling and nailing systems for throughput consistency.
Construction commands the installed base, yet Furniture Assembly climbs fastest on precision premiumization.
End User:
Customer type determines capital ownership versus rental utilization patterns.
- Contractors:Professional framing and renovation crews in the United States drive cordless platform adoption as OSHA enforcement tightens, absorbing battery ecosystem costs ahead of traditional replacement cycles.
- Builders:Large-scale residential developers standardize fleet procurement across multiple crews, consolidating around single-brand battery platforms to simplify inventory management.
- Manufacturers:Furniture and packaging producers prioritize pneumatic reliability for continuous-production environments.
- DIY Enthusiasts:Home improvement operators favor cordless convenience for intermittent project work, supporting rental channel expansion.
Contractors hold the largest segment, with Builders expanding most quickly on fleet standardization trends.
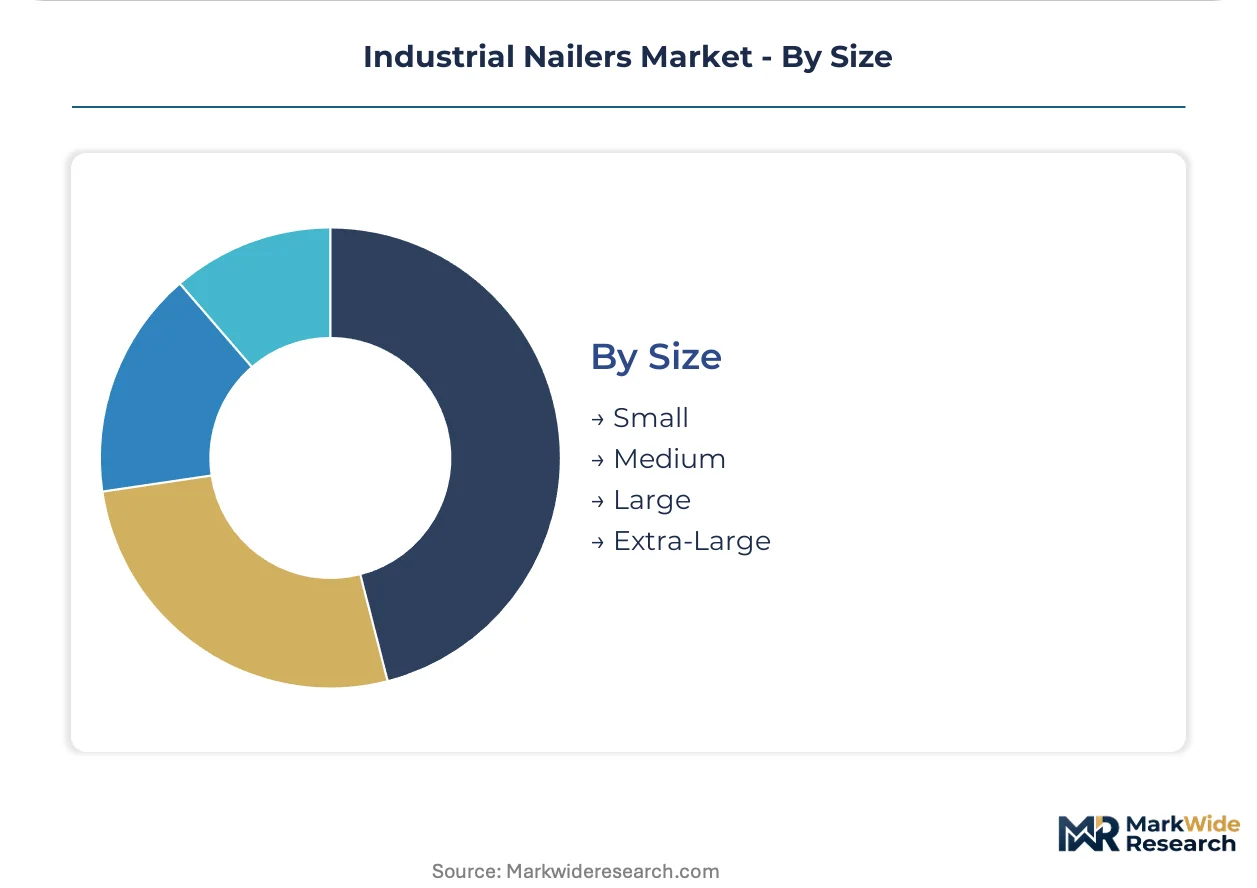
Size:
Volume and application intensity dictate tool scale requirements.
- Medium:Standard framing and finish applications balance maneuverability with driving power for general construction use.
- Large:Heavy-duty commercial applications require extended magazines and enhanced driving force for dense engineered lumber.
- Small:Precision trim and detail work in cabinetry and upholstery demand compact form factors.
- Extra-Large:Industrial packaging and heavy timber construction utilize specialized high-capacity systems.
Medium size leads procurement volumes, while Large formats gain share fastest on engineered lumber adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American tool distribution, channeling pneumatic and cordless fastening equipment into US residential construction corridors. German rail freight networks through the Rhine-Alpine corridor sustain just-in-time component flows to Central European manufacturing clusters.
United States
Large-scale multifamily housing starts in Texas and Florida absorb high-velocity fastening systems at volumes sustaining manufacturer R&D amortization. OSHA silica and noise exposure enforcement tightens across Sun Belt construction zones, compressing pneumatic tool replacement cycles. Dallas-Fort Worth contractors are consolidating cordless DeWalt and Milwaukee fleets ahead of traditional equipment refresh timelines.
Germany
Commercial retrofit activity in aging Ruhr Valley office stock generates demand for low-noise fastening in occupied structures. EU F-Gas Regulation and REACH substance restrictions eliminate hydrofluorocarbon propellants in gas-actuated cartridges, forcing chemistry reformulation. Stuttgart industrial distributors are clearing legacy Paslode-compatible inventory ahead of 2027 enforcement windows.
China
Domestic lithium refining and rare earth processing concentration creates input cost leverage for cordless motor and battery pack production. GB standards and MIIT industrial policy shape export certification requirements for pneumatic tool manufacturers. Shenzhen and Dongguan electronics clusters are scaling 21700 and 4680 cell formats for power tool OEM supply contracts.
Japan
Precision coil-nailer segments in furniture and finish-carpentry applications command premium placement through manufacturing tolerance advantages. METI energy-transition policies and JIS standards govern battery platform interoperability requirements. Nagoya industrial suburbs concentrate specialty fastening R&D for automated assembly line integration.
India
Urban housing shortfalls in Maharashtra and Karnataka drive informal construction sector tool demand through rental channel penetration. BIS certification requirements and PLI scheme incentives for domestic manufacturing reshape import dependency patterns. Mumbai-Pune industrial corridor distributors are building cordless tool fleets for renovation contractor segments.
Industrial Nailers Market Vendor Landscape
On the supply side, the industry is consolidating around battery platform ecosystems and pneumatic heritage brands with entrenched distribution. Tiered competition separates premium cordless innovators, mid-market pneumatic specialists, and regional fabrication houses serving price-sensitive segments. Strategic moves center on cross-selling battery platforms into existing contractor bases and consolidating shelf space at specialty industrial distributors.
Within the heritage pneumatic tier, Illinois Tool Works anchors professional-grade lines through Paslode and Ramset channels. Stanley Black & Decker occupies the cordless platform leadership position, leveraging DeWalt battery interoperability across contractor fleets. MAX Co., Ltd. represents precision manufacturing specialization, commanding premium placement in finish-carpentry and furniture assembly segments where Japanese tolerance standards drive specification.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Illinois Tool Works |
| MAX Co., Ltd. |
| Techtronic Industries |
| Robert Bosch Power Tools |
| Apach Industrial Co., Ltd. |
| Aerosmith Fastening |
| Kyocera Corporation |
| Raimund Beck KG |
| Others |
Supply Flow & Price Mechanics
The Port of Los Angeles-Long Beach complex channels pneumatic and cordless fastening equipment into US residential construction corridors, with freight cost volatility amplifying price differentiation between premium battery platforms and standard pneumatic tiers. Container rate swings from this gateway feed directly into landed costs for lithium-ion cells and rare earth magnets, compressing margins on cordless variants while reinforcing pneumatic incumbents' price positioning.
Pricing Analysis
Volume-discount tiering structures separate contractor fleet purchases from single-unit retail transactions, with three-tier pricing stratification across premium brushless cordless, standard brushed motor, and economy pneumatic levels. Brand premium differentiation hinges on OSHA compliance certification and battery platform interoperability, while price erosion runs through economy pneumatic tiers as Chinese imports flood rental channel replenishment. Professional framing crews exhibit lowest price sensitivity due to productivity-linked ROI calculations, whereas DIY enthusiasts and intermittent renovators drive volume at entry price points.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for cordless motor and battery pack inputs. Manufacturing concentration in China, South Korea, and Japan anchors rare earth processing and lithium refining, with neodymium magnet and 21700 cell formats feeding from these nodes. Single-source vulnerability in Chinese rare earth separation creates input cost volatility, while distribution runs through specialty industrial distributors consolidating shelf space around high-velocity brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial nailer procurement is shifting toward service-attach models where maintenance agreements and consumables subscriptions expand faster than hardware unit sales. Fleet management platforms that bundle battery monitoring, tool tracking, and predictive maintenance are capturing contractor loyalty beyond product specifications.
For Market Incumbents: Build battery platform moats through proprietary 18-20V ecosystem lock-in that complicates competitor cross-selling. Deepen backward integration into lithium cell supply through offtake agreements with Shenzhen and Dongguan producers to hedge against Chinese export restriction risks. Anchor distribution control by consolidating shelf space at regional supply houses before Paslode-compatible inventory clears.
For New Entrants and Emerging Players: Pursue commercial retrofit segments in occupied US office structures where low-noise cordless requirements outpace incumbent response timelines. Target rental channel fleet building as the most penetrable entry vector, bypassing capital ownership resistance among renovation contractors. Lead with brushless DC motor architectures at mid-tier price points to exploit the technology migration from niche cabinet shops toward mainstream finish carpentry.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates where fastening tool divisions represent non-core revenue pools with stranded distribution assets. Five-to-ten year viability hinges on cordless platform conversion rates against pneumatic installed base erosion. Monitor OSHA enforcement intensity in Sun Belt construction zones as the inflection signal for accelerated replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | DeWalt and Milwaukee interoperability locks contractors into single-brand fleets, raising switching costs. |
| Backward Integration into Cell Supply | Captive lithium sourcing from Shenzhen producers insulates against Chinese export restriction volatility. |
| Integrated Dust Collection Development | OSHA silica compliance attachments open premium pricing on powder-actuated concrete fastening tools. |
| Rental Channel Fleet Expansion | United Rentals and Sunbelt buildup of cordless nailer pools captures renovation contractor demand. |
| REACH-Compliant Gas Cartridge Reformulation | Hydrocarbon propellant chemistry recertification clears legacy Paslode inventory ahead of EU enforcement. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with tool fleet managers, aftermarket service heads, OEM procurement teams, and specialty distributor category buyers; and secondary validation through SEC 10-K filings, customs trade records, OSHA enforcement databases, and power tool industry association shipment data. Bottom-up triangulation against top-down macroeconomic overlays anchored volume and value estimates.
Forecast inputs considered power source migration rates, housing start permit velocity, and lithium-ion cell cost curves across the projection horizon. Segmentation dimensions modeled include power source type, application intensity, end-user ownership pattern, and regional regulatory cluster. CAGRs derived from S-curve adoption modeling for cordless displacement against pneumatic installed base decay, with OSHA compliance timelines and battery energy density advances as key industry-specific variables.
Macroeconomic conditions sit as an overlay; deviation in residential construction lending rates, lithium commodity prices, or China-US trade policy would shift the trajectory. Forecasts reflect documented assumptions on technology substitution elasticities and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Trenchers Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Blanking Machine Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
India Heavy Construction Equipment Rental Market