
 Pressure Washer Market | 2026-2036
Pressure Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Washer Market Analysis
A capital-intensity divergence between integrated pump manufacturers and assembly-only brands is reorganizing competitive tiers in the pressure washer industry. Kärcher leverages in-house axial pump production to command premium positioning in professional hot-water systems. Simpson Cleaning anchors its position through strategic control over gasoline engine sourcing partnerships with Briggs & Stratton. Nilfisk competes by sustaining European regulatory compliance as a baseline design requirement rather than a market-entry cost.
Pressure washers are mechanical cleaning devices that pressurize water through positive-displacement pumps to deliver concentrated jets at ratings from 1,300 PSI for residential electric units to over 4,000 PSI for industrial gas-powered systems, primarily serving surface preparation, debris removal, and sanitization tasks across commercial and industrial environments. Electric product types now capture the fastest expansion as lithium-ion battery platforms displace corded architectures in residential and light-commercial segments. High-pressure and ultra-high-pressure ratings concentrate margin pools where specialized ceramic plunger pumps and hardened steel frames support oil-field, shipyard, and manufacturing equipment maintenance applications.
EPA small-engine emission regulations and EU F-Gas restrictions on refrigerant-based heating systems in hot-water pressure washers are reshaping product design requirements and cross-border certification costs for manufacturers. OSHA workplace safety standards governing high-pressure water jet exposure further define industrial segment specifications and operator training protocols. Stakeholders must monitor how battery energy density improvements and evolving carbon-border adjustment mechanisms will alter the cost structure of electric versus gas-powered platform decisions.
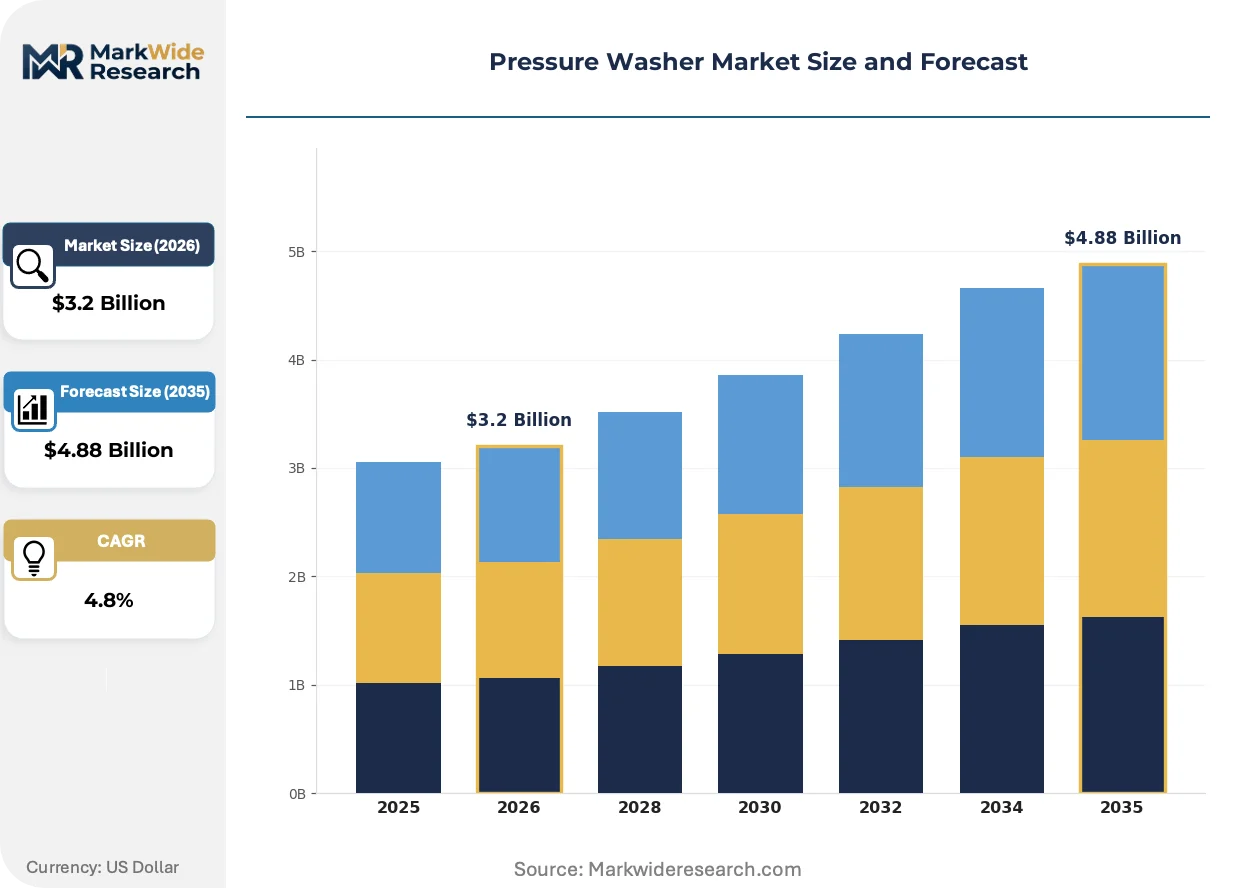
Market Dynamics
EPA small-engine emission standards are compressing gasoline-powered platform viability while lithium-ion battery energy density improvements unlock cordless professional-grade performance. This regulatory-technology intersection is reconfiguring manufacturer R&D allocation and procurement specifications across commercial cleaning fleets.
Growth Catalysts
- Commercial cleaning service expansion:Professional fleet operators in the United States are standardizing hot-water pressure washer specifications for municipal sanitation contracts, driving equipment refresh cycles.
- EU F-Gas Regulation:Restrictions on refrigerant-based heating systems are accelerating electric boiler integration in European hot-water units, creating compliant product differentiation.
- Ceramic plunger pump adoption:Oil-field maintenance operators are specifying ultra-high-pressure ratings above 4,000 PSI for manufacturing equipment descaling applications.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input costs fluctuate with cathode material spot prices, compressing margin on cordless residential platforms.
- Gasoline engine supplier concentration:Small-engine manufacturing clusters in specific Midwestern US states create single-source vulnerability for assembly-only brands.
- OSHA exposure limits:Workplace safety standards governing high-pressure water jet contact impose operator training mandates that extend sales cycles for industrial units.
Strategic Opportunities
- German municipal fleet electrification:Federal procurement guidelines favoring zero-emission equipment create compliant product entry points for battery-powered hot-water systems.
- Shipyard surface preparation automation:Robotic arm integration with ultra-high-pressure units is opening unmanned cleaning contracts in maritime maintenance.
- China dual carbon policy:Provincial clean equipment subsidies for professional cleaning services are redirecting procurement toward electric architectures in coastal manufacturing zones.
Industry Challenges
- Axial pump machining specialist scarcity:In-house production of hardened steel pump components requires CNC operator skill sets concentrated among legacy industrial equipment manufacturers.
- Cross-border certification fragmentation:EPA, EU F-Gas, and OSHA compliance documentation must be maintained in parallel, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Washer Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Hot Water, Cold Water End User: Residential, Commercial, Industrial, Agricultural Pressure Rating: Low Pressure, Medium Pressure, High Pressure, Ultra High Pressure Application: Car Wash, Building Cleaning, Equipment Maintenance, Deck Cleaning |
| Companies Covered | Bosch, Stanley Black & Decker, Kärcher, Techtronic Industries, Simpson Cleaning, Nilfisk, Briggs & Stratton, BE Pressure, Generac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Washer Market Emerging Trajectories
Battery platform maturation is collapsing the performance gap between corded electric and cordless professional units. Regulatory emission deadlines are forcing synchronous redesign of heating systems and power trains. Procurement specifications are converging on total cost-of-ownership metrics rather than capital expenditure alone.
Brushless DC motor controllers paired with 21700-format lithium-ion cells are miniaturizing high-voltage battery packs without sacrificing duty-cycle duration. Light-commercial cleaning contractors in Germany and the United States are specifying these platforms for four-hour continuous operation. The technology is miniaturizing frame dimensions and enabling backpack-portable professional units previously restricted to residential segments.
EPA Phase 3 small spark-ignition engine standards are mandating evaporative emission controls and catalytic converter integration on gasoline-powered pressure washers. Manufacturers serving the US market are absorbing certification costs through platform consolidation rather than model proliferation. Hot-water system producers are most affected, as combined engine-boiler compliance testing extends development cycles by eight to fourteen months.
Rental and lease-to-own arrangements are displacing outright purchase in North American commercial cleaning fleet procurement. Equipment distributors are unbundling after-sales service contracts from hardware margins to capture recurring revenue. This shift is most visible among multi-location facility management operators in the United States seeking to convert capital expenditures to operational budget lines.
Pressure Washer Market Segmentation
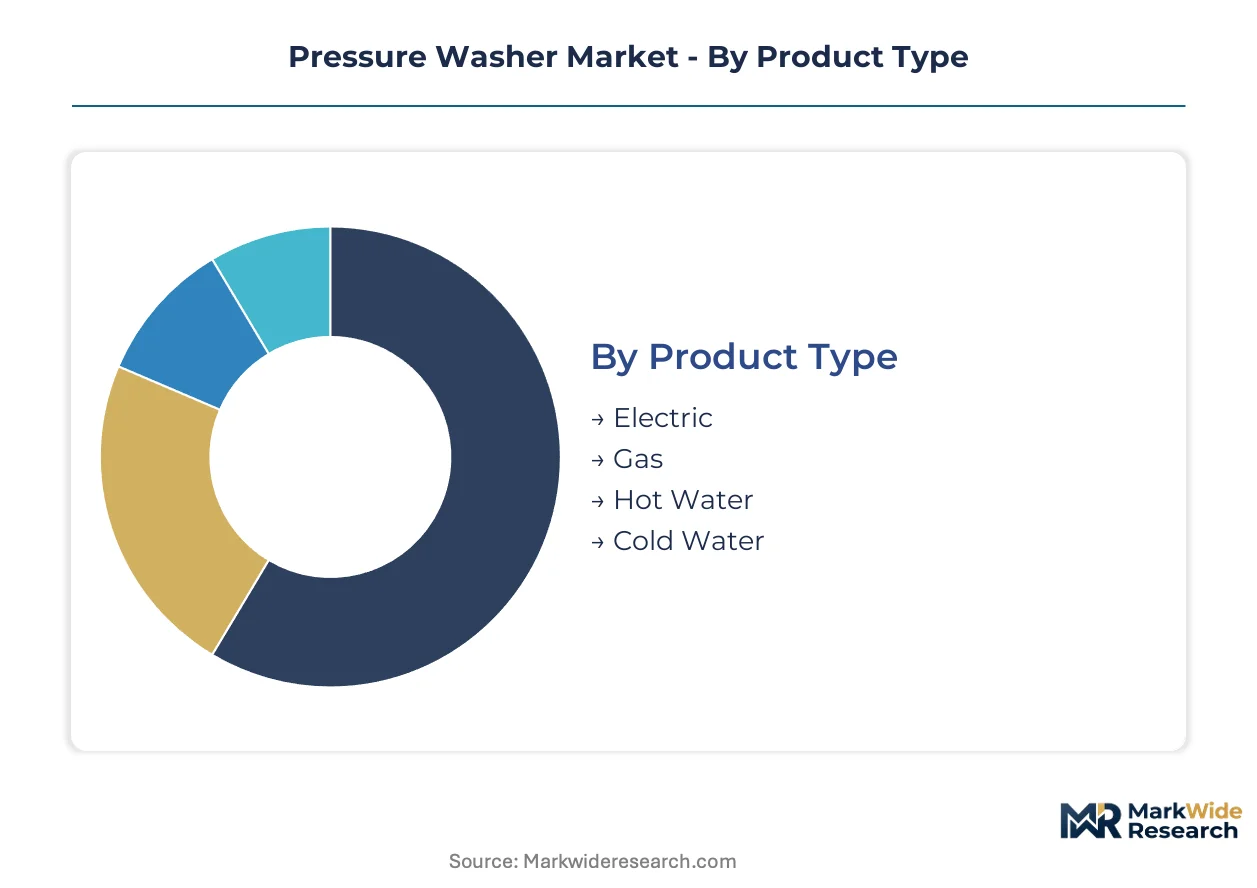
Pressure washer procurement specifications diverge sharply across power architectures and pressure ratings, creating distinct margin pools that reward specialized component integration. Fleet operators now segment purchases by total cost-of-ownership metrics rather than capital expenditure alone, compressing assembly-only brands in high-performance tiers.
Product Type:
Margin concentration follows powertrain architecture, with battery-electric platforms capturing premium positioning as emission regulations tighten.
- Electric:Corded residential units dominate volume through retail channels, while lithium-ion battery platforms are displacing corded architectures in light-commercial segments across Germany and the United States. Brushless DC motor controllers paired with 21700-format cells now enable four-hour continuous operation, miniaturizing frame dimensions for backpack-portable professional units.
- Gas:Gasoline-powered systems retain installed capacity in industrial ratings above 3,000 PSI, though EPA Phase 3 small spark-ignition engine standards are mandating evaporative emission controls and catalytic converter integration. Combined engine-boiler compliance testing extends development cycles for hot-water system producers.
- Hot Water:Integrated boiler architectures command premium positioning in professional cleaning fleets, with EU F-Gas restrictions accelerating electric boiler differentiation.
- Cold Water:Simpler pump-motor configurations serve price-sensitive residential and agricultural segments where heating system complexity adds unjustified cost.
Electric holds installed capacity. Gas is rotating up the share rankings in ultra-high-pressure industrial applications.
End User:
Customer type determines specification rigor, with commercial fleet procurement driving standardization around hot-water performance metrics.
- Residential:Corded electric units rated 1,300-2,000 PSI serve surface preparation and deck cleaning through retail and e-commerce channels. Price sensitivity dominates, with lithium-ion battery cost volatility compressing margins on cordless platforms.
- Commercial:Professional cleaning services in the United States are standardizing hot-water pressure washer specifications for municipal sanitation contracts, driving equipment refresh cycles. Rental and lease-to-own arrangements are displacing outright purchase among multi-location facility management operators.
- Industrial:Ultra-high-pressure ratings above 4,000 PSI concentrate margin pools where ceramic plunger pumps and hardened steel frames support oil-field, shipyard, and manufacturing equipment maintenance. OSHA workplace safety standards governing high-pressure water jet exposure impose operator training mandates.
- Agricultural:Cold-water gas-powered units serve debris removal and equipment washing where portability outweighs heating system integration.
Commercial dominates procurement volume. Industrial is climbing the fastest on specialized ceramic pump specifications.
Pressure Rating:
Specification intensity escalates nonlinearly with pressure, creating tiered margin structures that reward in-house pump production.
- Low Pressure:Residential electric units rated below 2,000 PSI serve light-duty surface cleaning with minimal pump specialization requirements.
- Medium Pressure:Light-commercial contractors in Germany specify these platforms for four-hour continuous operation on battery architectures.
- High Pressure:Professional fleet operators deploy 3,000-4,000 PSI systems for building cleaning and municipal sanitation contracts.
- Ultra High Pressure:Oil-field maintenance operators specify ratings above 4,000 PSI for manufacturing equipment descaling, with specialized ceramic plunger pumps and hardened steel frames supporting premium positioning. Robotic arm integration is opening unmanned cleaning contracts in maritime maintenance.
Ultra High Pressure commands the steepest expansion trajectory. Medium Pressure is rotating up the share rankings as battery platforms mature.
Application:
Use-case specificity determines heating system integration and duty-cycle requirements, with automated surface preparation reshaping industrial procurement.
- Car Wash:Fixed-bay and self-service installations favor hot-water electric systems with continuous-duty pumps.
- Building Cleaning:Municipal contracts in the United States drive standardization around mobile hot-water units with trailer-mounted configurations.
- Equipment Maintenance:Oil-field and manufacturing descaling applications specify ultra-high-pressure ceramic plunger pump systems. Robotic integration is gaining traction in shipyard surface preparation automation.
- Deck Cleaning:Residential and light-commercial segments favor portable cold-water electric or battery platforms for intermittent duty cycles.
Equipment Maintenance holds installed capacity in ultra-high-pressure tiers. Building Cleaning is expanding most quickly on municipal fleet electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across manufacturing clusters, with integrated pump producers in Germany and China running trade surpluses while assembly-dependent markets in North America import specialized components. Regional procurement patterns diverge around emission compliance timelines and fleet electrification mandates.
United States
Commercial cleaning services in Texas and Florida drive equipment refresh cycles for municipal sanitation contracts. EPA Phase 3 small spark-ignition engine standards mandate evaporative emission controls and catalytic converter integration on gasoline-powered systems. Midwestern engine manufacturing clusters in Wisconsin and Missouri create single-source vulnerability for assembly-only brands dependent on Briggs & Stratton supply.
Germany
Federal procurement guidelines favoring zero-emission equipment accelerate battery-powered hot-water system adoption among municipal fleets. EU F-Gas Regulation restricts refrigerant-based heating systems, forcing electric boiler integration in professional units. Manufacturing concentration in Baden-Württemberg and North Rhine-Westphalia hosts specialized axial pump machining capabilities for ultra-high-pressure ceramic plunger systems.
China
Provincial clean equipment subsidies in coastal manufacturing zones redirect professional cleaning procurement toward electric architectures. Dual carbon policy targets compress gasoline-powered platform viability in municipal maintenance operations. Yangtze River Delta clusters around Shanghai and Suzhou concentrate lithium-ion battery pack assembly for export-oriented pressure washer manufacturers.
Japan
Light-commercial contractors in Osaka and Nagoya specify brushless DC motor controllers paired with 21700-format cells for four-hour continuous operation. METI efficiency standards shape battery platform certification requirements for professional-grade cordless units. Kanto region distributors are unbundling after-sales service contracts from hardware margins to capture recurring revenue from facility management operators.
United Kingdom
Multi-location facility management operators in Greater London seek lease-to-own arrangements converting capital expenditures to operational budget lines. REACH compliance documentation extends product launch timelines for hot-water system producers serving continental European export markets. Midlands manufacturing bases concentrate cold-water pump assembly for price-sensitive agricultural segments.
Pressure Washer Market Vendor Landscape
Concentration sits with integrated pump manufacturers who command premium positioning through in-house axial and ceramic plunger production. Assembly-only brands anchor volume tiers through strategic engine sourcing partnerships and distributor network scale. Three archetypes dominate: vertically integrated European specialists, North American engine-assembly platforms, and Asian battery-electric scale producers. Competitive moves center on platform consolidation to absorb compliance certification costs and rental-service model expansion to capture recurring revenue.
Among German-origin integrated manufacturers, Kärcher GmbH exemplifies the premium-tier specialist archetype through captive pump production capabilities. Stanley Black & Decker, Inc. and Techtronic Industries Co., Ltd. represent scale-driven assembly platforms leveraging global distribution infrastructure and brand portfolio breadth. These three anchors illustrate the structural divergence between component-integrated and assembly-dependent competitive positions.
| Leading Market Players |
|---|
| Bosch |
| Stanley Black & Decker |
| Kärcher |
| Techtronic Industries |
| Simpson Cleaning |
| Nilfisk |
| Briggs & Stratton |
| BE Pressure |
| Generac |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for specialized ceramic plunger pumps concentrate pricing power with German and Chinese integrated manufacturers while compressing margins for assembly-only brands dependent on spot-market engine sourcing. This inventory-to-pricing dynamic rewards backward integration into axial pump machining capabilities and penalizes brands without captive component production.
Pricing Analysis
The configured-to-order premium spread separates integrated hot-water systems from standard cold-water platforms by fifteen to twenty-five percent across professional fleet procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling rather than raw performance specifications alone. Price erosion runs through residential cordless segments as lithium-ion cell cost volatility compresses margins on battery-electric architectures. Commercial fleet operators exhibit lowest price sensitivity, prioritizing total cost-of-ownership metrics and EPA compliance documentation over capital expenditure minimization.
Supply Chain Analysis
Just-in-time inventory strategies dominate residential electric assembly while strategic stockpiling of hardened steel pump components prevails among ultra-high-pressure system producers facing eighteen-month machining backlogs. Manufacturing gravity centers on Germany for axial pump machining, China for lithium-ion battery pack assembly, and the United States Midwest for small gasoline engine production. Raw material dependencies span 21700-format lithium-ion cells, hardened steel forgings, and catalytic converter substrates. Single-source vulnerability concentrates in Briggs & Stratton engine supply chains for assembly-only North American brands. Distribution runs through specialized industrial equipment distributors and rental fleet operators rather than retail channels for professional-grade tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EPA Phase 3 certification timelines and EU F-Gas compliance documentation create eighteen-month barriers that favor incumbents with established testing relationships.
For Market Incumbents: Secure captive supply of ceramic plunger pump machining capacity through acquisition of specialized German or Japanese CNC operators. Lock long-term lithium-ion cell offtake agreements with Yangtze River Delta producers before battery platform standardization crystallizes. These moves defend against emerging Asian battery-electric scale entrants and assembly-only brands seeking vertical repositioning. For New Entrants and Emerging Players: Differentiate on battery-electric hot-water system architectures targeting German municipal fleet electrification mandates where incumbent gasoline-platform portfolios face compliance obsolescence. White-space concentrates in backpack-portable professional units enabled by 21700-format cell miniaturization. Go-to-market through unbundled after-sales service contracts rather than hardware margin capture. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected pressure washer divisions lacking battery platform R&D investment. Long-term viability favors integrated pump producers with in-house axial and ceramic plunger capabilities over assembly-dependent brands. Watch lithium-ion cell energy density improvement curves as inflection indicator for cordless professional-grade performance parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Machining | In-house axial pump production secures eighteen-month lead time advantage over assembly-only competitors sourcing from German specialists. |
| Battery Platform Standardization | 21700-format lithium-ion cell adoption enables four-hour continuous operation for cordless professional units in German municipal fleets. |
| EPA Phase 3 Certification Investment | Combined engine-boiler compliance testing extends development cycles and filters out capital-constrained assembly brands. |
| Rental Fleet Service Unbundling | After-sales service contracts capture recurring revenue from multi-location facility management operators in Texas and Florida. |
| EU F-Gas Electric Boiler Transition | Electric heating system integration differentiates professional hot-water units for European regulatory compliance. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA certification databases, EU F-Gas regulatory filings, and customs trade records for pump component flows. Primary interviews engaged procurement directors at commercial cleaning fleet operators, aftermarket service heads at industrial equipment distributors, and plant engineers at axial pump machining facilities across Baden-Württemberg and North Rhine-Westphalia. Secondary validation drew from SEC 10-K disclosures of listed assembly platforms, OSHA workplace safety standard documentation, and METI efficiency certification registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across power architecture segments.
Segmentation dimensions modeled span powertrain architecture, pressure rating tier, end-user category, and application use-case across the projection horizon. Analytical framework incorporated battery energy density improvement trajectories, EPA emission compliance deadline phasing, and provincial clean equipment subsidy disbursement patterns in Chinese coastal manufacturing zones. CAGRs derived from logistic diffusion curves fitted to electric platform adoption rates and fleet refresh cycle observations.
Material uncertainties — lithium-ion cathode material spot price volatility, EPA enforcement intensity variations, and carbon-border adjustment mechanism implementation timing — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory deadline adherence and battery platform performance convergence. Revision becomes warranted when cordless professional-grade duty-cycle duration crosses four-hour thresholds at sub-premium price positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Global Excavators Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Industrial Grout Pumps Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Europe Ground Penetrating Radar Market
Construction Equipment
Electric Excavators Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Dust Suppression Fog Cannon Market