
 Fresh Mushroom Market | 2026-2036
Fresh Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Mushroom Market Analysis
Multi-source procurement from domestic farms and international suppliers is hardening across European and North American retail channels. Greenyard NV leverages its integrated cold-chain network to sustain year-round availability across multiple continents. Monaghan Mushrooms Limited anchors its competitive stance through specialized controlled-environment agriculture systems. Costa Group Holdings Limited dominates the Asia-Pacific supply base with large-scale automated growing operations in Australia.
Fresh mushrooms comprise the fruiting bodies of cultivated macrofungi, typically harvested before spore maturation at moisture contents between 85% and 95%, and serve as whole-food protein and umami flavor sources for foodservice and retail preparation. Button mushrooms occupy the mature volume position due to established consumer familiarity and processing compatibility, while shiitake varieties capture expanding demand in functional food and plant-based formulations. Clamshell packaging controls respiration rates and extends shelf stability, creating margin concentration for premium retail channels compared with bulk formats used by wholesale markets.
The European Commission's Farm to Fork Strategy and REACH chemical standards shape cultivation input compliance and cross-border trade certification requirements for EU member states. The FDA and USDA in the United States enforce hazard analysis protocols and organic labeling standards that determine market access for domestic and imported fresh mushroom supplies. China's SAMR and GB national standards govern domestic production quality benchmarks and import inspection procedures. Stakeholders must monitor evolving pesticide maximum residue limits and carbon-accounting disclosures as these frameworks tighten across major producing and consuming jurisdictions.
Market Dynamics
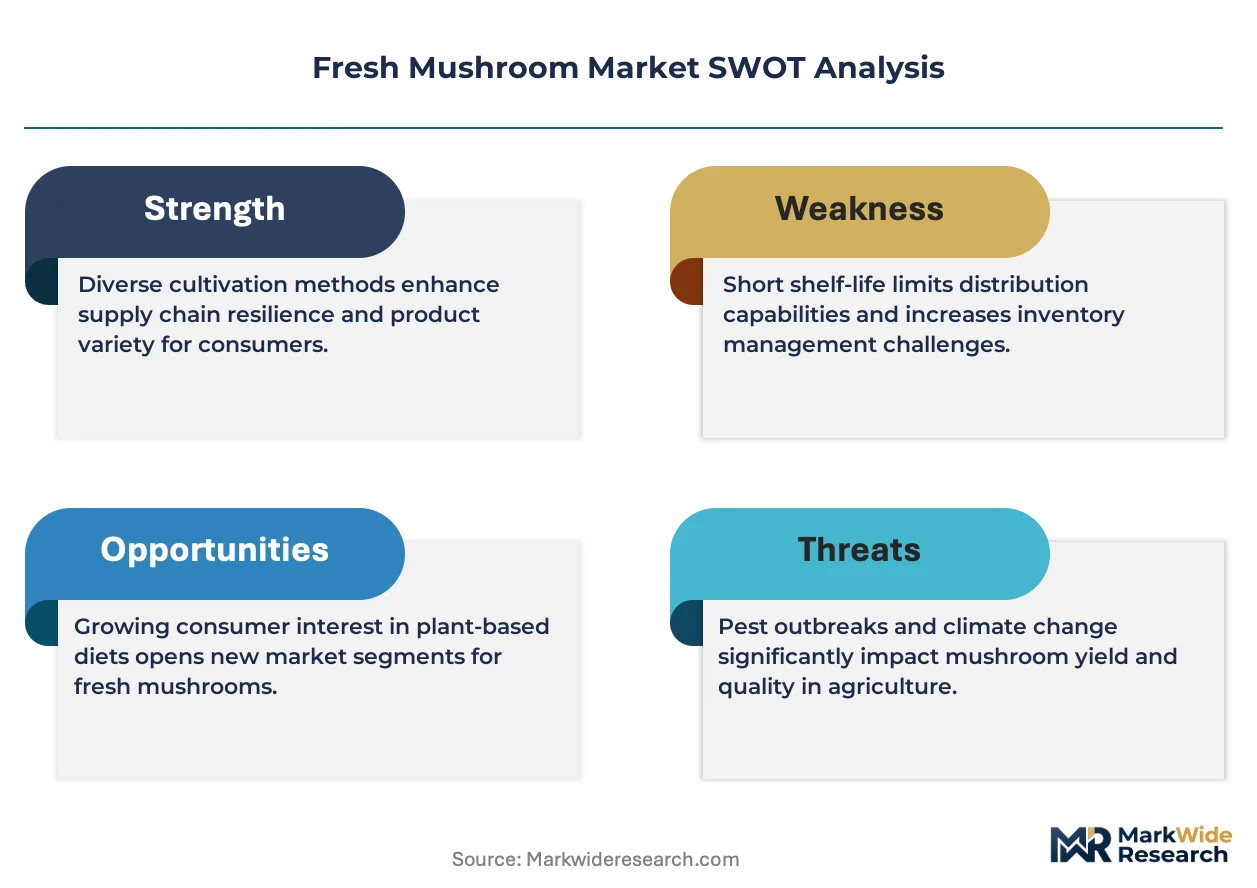
Controlled-environment agriculture is compressing traditional open-field cultivation economics, as substrate-based indoor systems deliver yield consistency that weather-dependent farming cannot match.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory pesticide residue reductions and carbon-accounting disclosures are accelerating certified organic acreage expansion across member states.
- Plant-based protein substitution:Foodservice operators in North America are reformulating center-plate items with umami-rich mushroom bases to reduce meat dependency.
- Shiitake functional food demand:Beta-glucan extraction protocols are driving pharmaceutical and nutraceutical offtake in East Asian processing hubs.
Market Restraints
- Input cost volatility:Wheat straw and sawdust substrate prices fluctuate with lumber and grain commodity cycles, squeezing margin predictability for substrate-dependent growers.
- Spore supply concentration:Commercial spawn production clusters in the Netherlands and China, creating single-source vulnerability for regional cultivation networks.
- Perishability constraints:Moisture content above 85 percent limits unbroken cold-chain distribution radius to approximately 48 hours from harvest.
Strategic Opportunities
- Medicinal extract verticals:Polysaccharide isolation for immunotherapy adjuvants offers price-realization multiples above fresh commodity sales.
- Direct-to-chef platforms:Bypassing wholesale intermediaries through subscription harvest-box services captures margin currently absorbed by foodservice distributors.
- China dual carbon alignment:Beijing's 2060 neutrality targets incentivize low-carbon cultivation certifications for export-oriented producers.
Industry Challenges
- Mycology technician scarcity:Specialized compost management and disease diagnostics expertise remains concentrated among aging cohorts in traditional producing regions.
- Organic certification timelines:Three-year land-history requirements delay premium-price access for conventional-to-organic conversion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Mushroom Market |
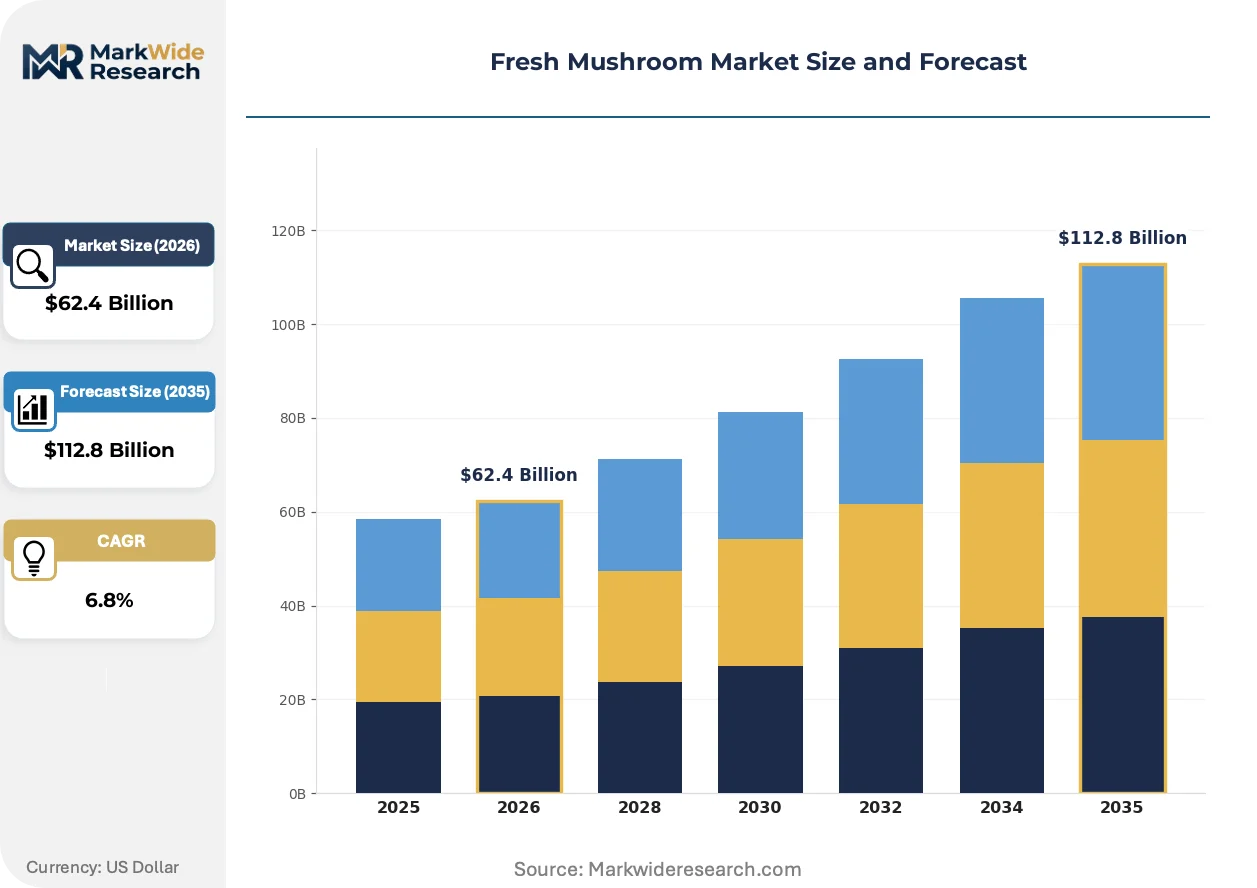
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Button, Shiitake, Oyster, Portobello Distribution Channel: Supermarkets, Online Retailers, Wholesale Markets, Specialty Stores Packaging Type: Bags, Clamshells, Trays, Bulk Containers End User: Restaurants, Food Processors, Grocery Stores, Households |
| Companies Covered | Highline Mushrooms Ltd., Greenyard NV, Monaghan Mushrooms Limited, Drinkwater Mushrooms Ltd., Costa Group Holdings Limited, Monterey Mushrooms, OKE Champ Holding GmbH, Shanghai Finc Bio-Tech Inc., Bonduelle SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Mushroom Market Emerging Trajectories
Biological efficiency metrics are replacing yield-per-acre as the dominant performance benchmark, rewarding substrate formulations and climate control precision over scale alone.
LED spectral tuning is overtaking high-pressure sodium and fluorescent systems in climate-controlled growing facilities. Tier-one operators in the Netherlands and Belgium have completed full conversion to tunable-spectrum arrays that accelerate pinning and reduce energy draw. The technology is overtaking legacy hardware so rapidly that equipment financing terms now assume three-year depreciation cycles rather than seven.
REACH chemical standards are extending registration requirements to novel biocides and sanitizers used in substrate preparation. ECHA's 2024 guidance on microbial pest control products forces reformulation of cleaning protocols across EU cultivation sites. Dutch and Polish operators are responding by consolidating into shared-service sterilization hubs to amortize compliance costs.
Chefs and institutional buyers are contracting directly with named farms for specific cap-size and stem-length specifications, bypassing graded commodity tiers. This specification-driven sourcing concentrates volume with growers who can guarantee harvest-to-delivery within 36 hours. The pattern is most visible in Scandinavian and Pacific Northwest foodservice markets where provenance labeling commands menu price premiums.
Fresh Mushroom Market Segmentation
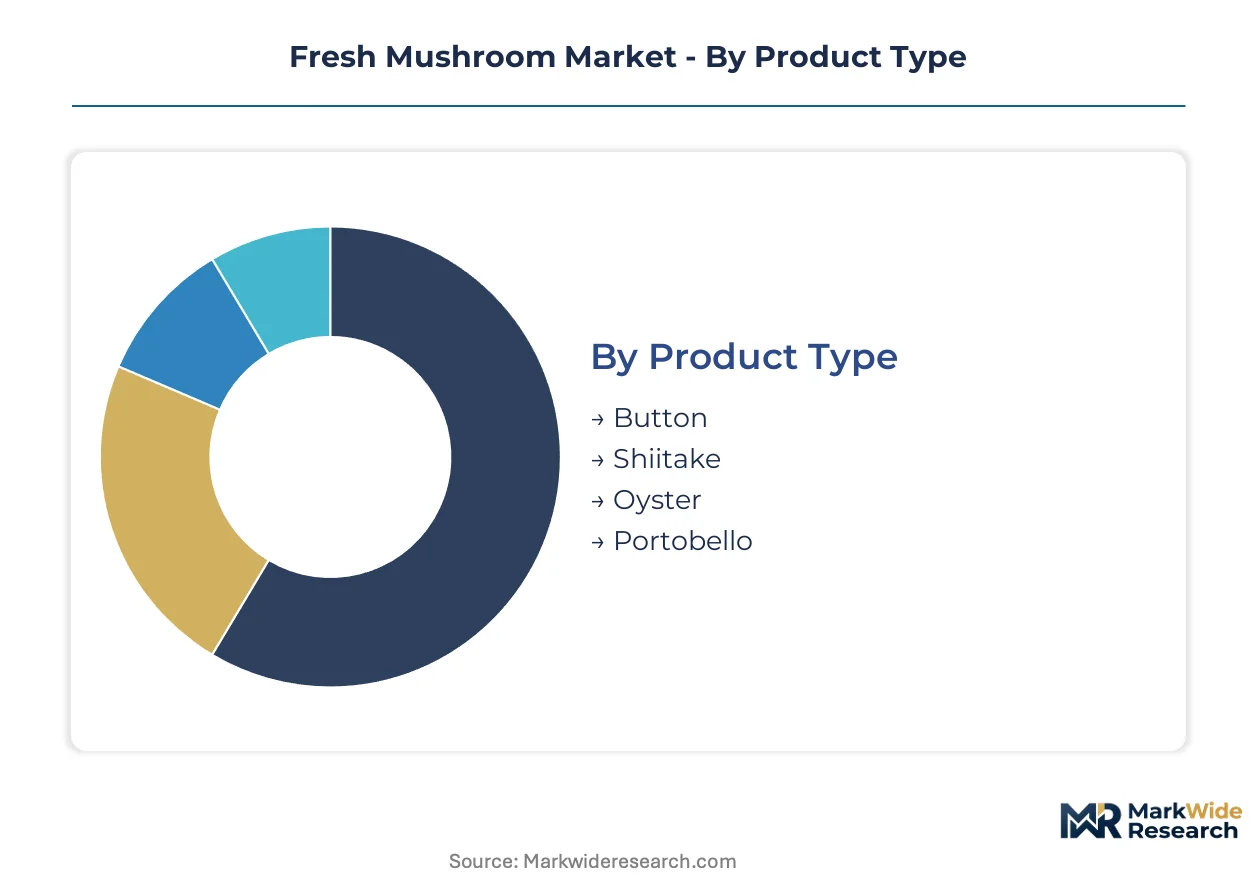
Fresh mushroom segmentation reveals how certification requirements, perishability constraints, and channel economics fragment supply strategies. Each dimension carries distinct regulatory burdens and margin structures that determine competitive positioning.
Product Type:
EU organic certification under EEC 834/2007 and USDA National Organic Program standards impose three-year conversion timelines on all varieties, with shiitake extraction protocols triggering additional pharmaceutical-grade GMP audits.
- Button:Standard white and brown Agaricus bisporus varieties dominate processing compatibility for frozen and canned applications. Food manufacturers in the Netherlands and Poland specify cap diameters of 40-60mm for consistent slicing yields.
- Shiitake:Lentinula edodes cultivation on oak and synthetic sawdust logs requires controlled humidity cycling. Beta-glucan extraction demand from South Korean nutraceutical processors is reshaping grower investment toward pharmaceutical-grade substrate protocols.
- Oyster:Pleurotus species thrive on agricultural waste streams including coffee grounds and cottonseed hulls. Urban vertical farms in Belgium leverage this substrate flexibility for zero-waste certification claims.
- Portobello:Mature Agaricus bisporus with expanded caps serves premium grilling applications. Direct-to-chef contracts in Copenhagen and Portland specify minimum 100g individual weight for menu presentation standards.
Leading the category by volume: Button. Growing fastest: Shiitake.
Distribution Channel:
Channel selection determines cold-chain investment intensity and traceability documentation depth, with wholesale markets absorbing the shortest shelf-life inventory and supermarkets demanding 14-day minimum remaining-life guarantees.
- Supermarkets:Clamshell packaging with modified atmosphere and barcode traceability dominates shelf placement. German retail chains Edeka and REWE enforce pesticide residue testing at receiving docks.
- Online Retailers:Subscription harvest-box services bypass wholesale intermediaries. Dutch platform HelloFresh contracts named farms for 36-hour harvest-to-delivery windows.
- Wholesale Markets:Rungis in Paris and New Covent Garden in London aggregate mixed-grade lots for foodservice redistribution. Bulk pricing reflects daily spot conditions rather than contracted premiums.
- Specialty Stores:Independent organic retailers in Stockholm and Vienna command 40-60% markups for local-provenance labeling. Certification documentation must display grower coordinates and harvest date.
Supermarkets capture the highest absolute volume. Online retailers are expanding most quickly.
Packaging Type:
Packaging economics concentrate margin in formats that extend shelf stability, with clamshell investments recovering through reduced shrinkage and premium placement fees.
- Clamshells:PET thermoformed containers with micro-perforations control respiration rates. Belgian packer Greenyard NV operates automated filling lines that grade by cap size and defect count.
- Bags:Perforated polyethylene suits high-turnover retail segments. French hypermarkets Carrefour and Auchan use bagged formats for promotional pricing tiers.
- Trays:EPS or molded pulp platforms with overwrap film serve foodservice prep-ready specifications. UK meal-kit providers specify tray formats for kitchen workflow efficiency.
- Bulk Containers:5kg and 10kg ventilated crates supply institutional kitchens and processors. Wholesale markets in Barcelona and Milan transact primarily in bulk with minimal branding.
Clamshells lead by revenue per kilogram. Bags dominate by absolute tonnage.
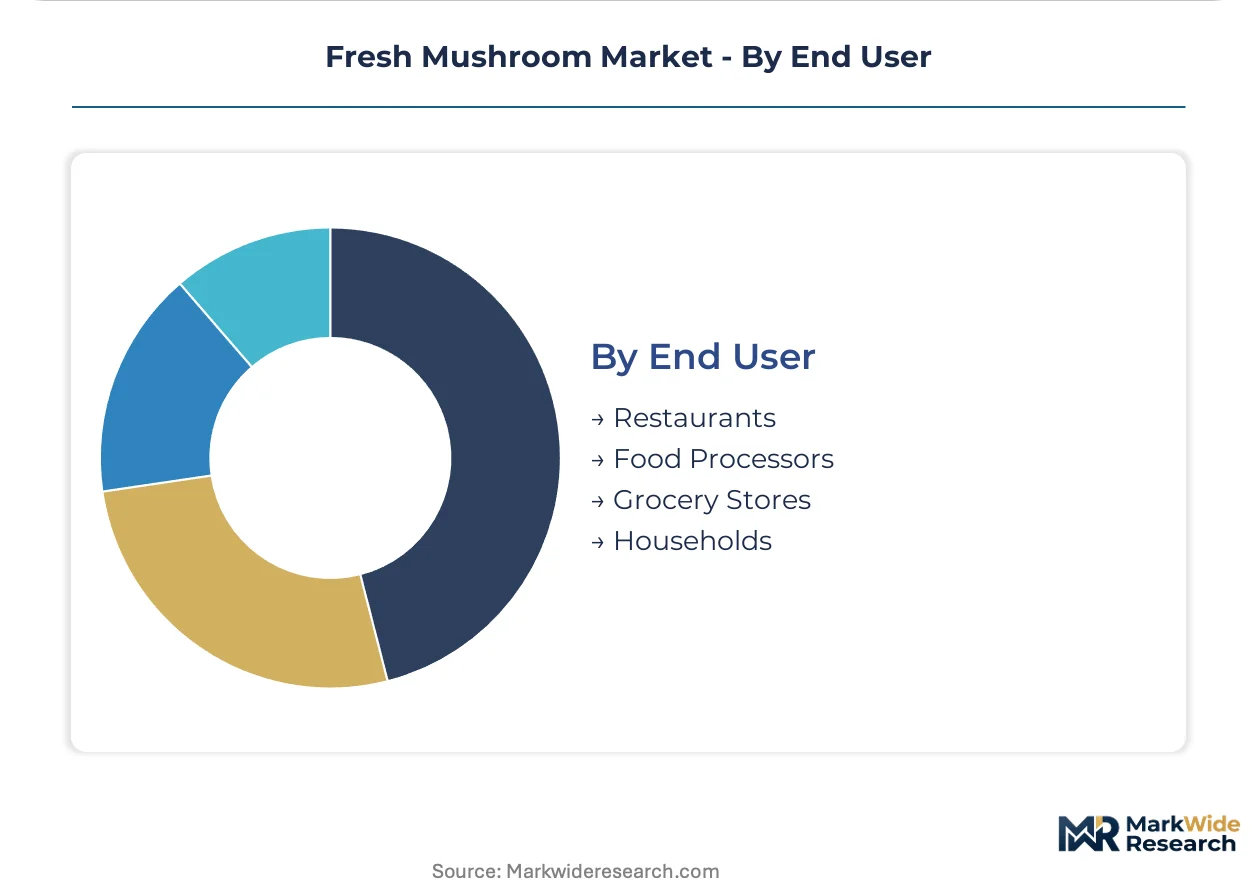
End User:
End-user specifications diverge sharply on traceability depth, with restaurants and processors driving the steepest expansion in named-farm contracting.
- Restaurants:Michelin-starred kitchens in Copenhagen and San Francisco specify stem length and cap curvature for plate architecture. Contracts include harvest-time windows and exclusion of irrigation additives.
- Food Processors:Frozen and dried mushroom manufacturers require consistent moisture content and absence of bruising. German processor Pilzland Group audits substrate sourcing for heavy metal compliance.
- Grocery Stores:Private-label programs at Albert Heijn and Waitrose demand exclusive variety rights and volume guarantees. Three-year supply agreements lock in organic premium spreads.
- Households:Direct farm-gate and farmers-market purchases concentrate in peri-urban zones around Berlin and Vienna. Cash transactions limit traceability documentation.
Restaurants command the highest price realization. Food processors absorb the largest absolute volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat straw and sawdust substrate clusters in Poland, the Netherlands, and China's Shandong Province anchor cultivation capacity. Climate-controlled indoor systems concentrate near these feedstock sources and major consumption corridors. Regulatory divergence on pesticide residues and carbon accounting is fragmenting cross-border supply strategies.
China
Domestic per-capita consumption exceeds all other national markets, with Shandong and Fujian provinces hosting the densest substrate-based growing operations. SAMR's GB national standards govern production quality benchmarks and import inspection procedures. Qingdao and Zhangzhou clusters supply both fresh retail channels and beta-glucan extraction facilities serving pharmaceutical processors.
United States
Foodservice operators reformulate center-plate items with mushroom bases to reduce meat dependency, concentrating demand in California and Pennsylvania growing regions. FDA and USDA enforce hazard analysis protocols and organic labeling standards that determine market access. Kennett Square, Pennsylvania anchors the largest Agaricus bisporus concentration outside Europe.
Netherlands
Commercial spawn production clusters here, creating single-source vulnerability for regional cultivation networks across Northern Europe. REACH chemical standards and ECHA's 2024 guidance on microbial pest control products force reformulation of cleaning protocols. Westland and Horst clusters operate shared-service sterilization hubs to amortize compliance costs.
Germany
Edeka and REWE enforce pesticide residue testing at receiving docks, concentrating procurement with certified organic suppliers. EU Farm to Fork Strategy mandatory pesticide residue reductions accelerate certified organic acreage expansion. Bavaria and Lower Saxony host the most advanced LED spectral tuning conversions in climate-controlled facilities.
Australia
Costa Group Holdings dominates Asia-Pacific supply with large-scale automated growing operations serving export-oriented fresh and processed channels. State-level food safety authorities align with FSANZ codes for domestic distribution. Monaro and Adelaide Plains clusters supply direct-to-chef contracts across Southeast Asian foodservice markets.
Fresh Mushroom Market Vendor Landscape
Capacity expansion dominates the current landscape as substrate-based indoor systems displace weather-dependent farming. The structure fragments between integrated cold-chain operators and specialized controlled-environment agriculture specialists. Two archetypes prevail: diversified produce conglomerates leveraging existing distribution infrastructure, and pure-play mushroom cultivators optimizing biological efficiency metrics. Geographic expansion and technology licensing represent the dominant competitive vectors as players seek spawn supply security and LED spectral tuning expertise.
Among European-based operators, Greenyard NV exemplifies the integrated cold-chain archetype, while Monaghan Mushrooms Limited anchors the controlled-environment specialization tier. Costa Group Holdings occupies the scale-driven Asia-Pacific position. These three represent distinct strategic postures: conglomerate diversification, technical cultivation excellence, and regional volume leadership.
| Leading Market Players |
|---|
| Highline Mushrooms Ltd. |
| Greenyard NV |
| Monaghan Mushrooms Limited |
| Drinkwater Mushrooms Ltd. |
| Costa Group Holdings Limited |
| Monterey Mushrooms |
| OKE Champ Holding GmbH |
| Shanghai Finc Bio-Tech Inc. |
| Bonduelle SA |
| Others |
Supply Flow & Price Mechanics
Wheat straw and sawdust substrate costs fluctuate with lumber and grain commodity cycles, transmitting volatility from upstream agriculture and forestry markets through to grower margins and downstream retail price tiers across European and North American channels.
Pricing Analysis
Harvest-to-delivery guarantees bundled with named-farm provenance command premium placement fees in Scandinavian and Pacific Northwest foodservice markets, while unbundled bulk formats trade at spot discounts in wholesale channels. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified clamshell retail from conventional supermarket bags and institutional bulk crates. Cost compression in substrate-dependent tiers is intensifying because wheat straw and sawdust prices track volatile grain and lumber futures. Food processors absorbing the largest absolute volume exhibit the highest price sensitivity, while Michelin-starred kitchens specifying stem length and cap curvature show the least.
Supply Chain Analysis
Single-source vulnerability sits with commercial spawn production clustering in the Netherlands and China, creating concentrated dependency for regional cultivation networks across Northern Europe and East Asia. Geographic supply concentration centers on Poland, the Netherlands, and China's Shandong Province, where climate-controlled indoor systems cluster near substrate sources. Raw material dependencies rest on wheat straw, hardwood sawdust, and agricultural waste streams including coffee grounds and cottonseed hulls. Regulatory restriction risk from tightening EU REACH chemical standards and pesticide residue limits threatens cross-border trade certification. Distribution runs through integrated cold-chain operators for retail clamshell formats and wholesale market aggregation for bulk foodservice redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fresh mushroom sector is becoming a vertical-integration race as players pursue captive supply of commercial spawn to escape single-source vulnerability in Netherlands and China clusters.
For Market Incumbents: Anticipate margin compression from LED spectral tuning capital cycles compressing from seven-year to three-year depreciation horizons by consolidating into shared-service sterilization hubs that amortize REACH compliance costs across multiple cultivation sites. Defensive moves should prioritize backward integration into substrate formulation to hedge wheat straw and sawdust commodity volatility, while securing exclusive variety rights through three-year supply agreements with German retail chains Edeka and REWE. For New Entrants and Emerging Players: Direct-to-chef subscription harvest-box services represent the most penetrable white-space target, bypassing wholesale intermediaries to capture margin currently absorbed by foodservice distributors in Scandinavian and Pacific Northwest markets. Urban vertical farms leveraging oyster mushroom substrate flexibility on coffee grounds and cottonseed hulls can secure zero-waste certification claims that command 40-60% markups in independent organic retail channels. Go-to-market execution should emphasize 36-hour harvest-to-delivery windows with named-farm provenance labeling. For Investors and Strategic Acquirers: Accelerating consolidation into shared-service sterilization hubs across Dutch and Polish cultivation sites is the leading indicator that biological efficiency metrics are replacing yield-per-acre as the dominant performance benchmark, rewarding substrate formulations and climate control precision over scale alone. Long-term viability over the next decade favors acquisition targets with demonstrated LED spectral tuning expertise and established relationships with pharmaceutical-grade beta-glucan extraction facilities in South Korea. Monitor spawn supply security arrangements as the critical inflection signal for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spawn Production | Captive supply of commercial spawn eliminates Netherlands-China single-source vulnerability for regional networks. |
| LED Spectral Tuning Conversion | Full conversion to tunable-spectrum arrays accelerates pinning and reduces energy draw below legacy hardware economics. |
| Shared-Service Sterilization Hub Consolidation | Amortizes ECHA 2024 microbial pest control compliance costs across multiple EU cultivation sites. |
| Direct-to-Chef Platform Launch | Bypasses wholesale intermediaries to capture margin currently absorbed by foodservice distributors in premium markets. |
| Pharmaceutical-Grade Substrate Certification | Unlocks beta-glucan extraction demand from South Korean nutraceutical processors at price-realization multiples above fresh commodity sales. |
Methodological Framework
Multi-period observation of substrate cost volatility, LED depreciation cycles, and organic certification conversion timelines anchored the trend analysis, supplemented by interviews with cultivation operations managers, substrate procurement leads at agricultural waste processors, cold-chain logistics coordinators, retail category buyers at German and Dutch supermarket chains, and pharmaceutical extraction facility technical directors. Secondary validation drew from EU Farm to Fork Strategy documentation, ECHA guidance on microbial pest control products, SAMR GB national standards, FDA hazard analysis protocols, and customs trade data for spawn and substrate cross-border flows. Bottom-up grower capacity modeling and top-down retail channel volume estimates were triangulated against consumption corridor analysis.
Input-output matrices structured the analytical framework across the projection horizon, modeling volume and value trajectories by product type (button, shiitake, oyster, portobello), distribution channel (supermarkets, online retailers, wholesale markets, specialty stores), packaging format (clamshells, bags, trays, bulk containers), and end user (restaurants, food processors, grocery stores, households). CAGRs were derived from biological efficiency metric progression and substrate-based indoor system adoption curves. Industry-specific forecast inputs included LED spectral tuning penetration rates and pharmaceutical-grade extraction facility capacity expansion.
Revisions become necessary when EU pesticide maximum residue limits tighten beyond current Farm to Fork Strategy trajectories, when carbon-accounting disclosure requirements extend to import inspection procedures, or when spawn supply concentration in the Netherlands and China experiences disruption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Spain Greenhouse Horticulture Market
Vegetables
Vegetable Chutney Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Sweet Potatoes Market
Vegetables
Fresh Vegetables Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Garden Cress Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Potato Market
Vegetables
Dried Vegetable Market
Vegetables
IQF Vegetables Market
Vegetables
Microgreens Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
United States Microgreens Market
Vegetables
Asia-Pacific Peas Market