
 Global Mushroom Market | 2026-2036
Global Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mushroom Market Outlook
Direct-to-restaurant distribution is reshaping how fresh mushroom volumes move from farm to kitchen. Monterey Mushrooms Inc. leverages its vertically integrated growing network across North America to secure consistent supply contracts with major foodservice chains. Bonduelle Group anchors its competitive stance through deep processing capabilities in canned and frozen mushroom lines. Costa Group specializes in premium fresh varieties, commanding strong shelf positioning in Australian and Asian retail channels.
Mushrooms comprise the fruiting bodies of fungi classified within Basidiomycota and Ascomycota phyla, cultivated on composted substrates under controlled temperature, humidity, and carbon dioxide conditions typically ranging between 15-24°C and 80-95% relative humidity. Their primary commercial purpose spans fresh culinary consumption, processed ingredient supply, and extraction of bioactive compounds for functional applications. Button mushrooms occupy the largest volume share due to established consumer familiarity and cost-efficient cultivation, while the nutraceuticals end-user category demonstrates the fastest structural expansion as extract demand for beta-glucan supplements accelerates. Dried and powdered forms capture concentrated margin pools where shelf stability permits premium export pricing.
The FDA governs food safety standards for mushroom products entering US commerce, while the EU Green Deal and REACH frameworks impose chemical input restrictions on European cultivation operations. China's SAMR enforces domestic food additive and labeling rules that constrain import eligibility for processed mushroom goods. Stakeholders must monitor evolving mycotoxin testing protocols and carbon accounting requirements as these regulatory layers increasingly determine market access eligibility.
Market Dynamics
Food processing buyers are consolidating supplier rosters around vertically integrated growers capable of meeting simultaneous EU Green Deal carbon accounting and FDA mycotoxin documentation requirements.
Growth Catalysts
- EU Green Deal carbon benchmarks:The EU Green Deal mandates progressive emissions reductions across agricultural inputs, forcing cultivation operations to adopt composted substrate recycling and renewable energy systems that lower lifecycle carbon intensity for export eligibility.
- Nutraceutical extraction demand:Beta-glucan supplement manufacturers in China are contracting directly with specialized growers for consistent polysaccharide concentrations, bypassing commodity spot markets and locking in multi-year supply agreements.
- Controlled-environment agriculture:Automated climate systems using sensor networks and AI-driven humidity modulation are cutting per-kilogram production costs while enabling year-round output in non-traditional growing regions.
Market Restraints
- Input cost volatility:Wheat straw and poultry manure prices fluctuate with grain commodity cycles and avian influenza outbreaks, compressing margins for compost-dependent growers without long-term substrate contracts.
- Supply concentration risk:Premium fresh variety propagation relies on a limited number of certified spawn laboratories in the Netherlands and China, creating genetic bottleneck vulnerability for shiitake and maitake producers.
- Regulatory friction:China's SAMR maintains divergent food additive approval lists from FDA and EFSA standards, forcing reformulation or dual-SKU strategies for processed mushroom ingredient exporters.
Strategic Opportunities
- Underpenetrated Indian retail:India's FSSAI has streamlined import clearance for dried mushroom products, opening shelf space in organized retail as domestic production remains insufficient for rising urban protein demand.
- Regulatory tailwind:Japan's METI bioeconomy incentives subsidize mycelium-based material research, creating offtake guarantees for growers supplying fermentation feedstock to packaging and textile innovators.
- Direct-to-restaurant channels:Fresh produce distributors in Australia and South Korea are building chef-facing platforms that bypass wholesale terminal markups, capturing margin through just-in-time harvest-to-kitchen logistics.
Industry Challenges
- Mycologist talent scarcity:Commercial spawn production and disease diagnostics require specialized fungal pathology expertise that agricultural universities have not scaled to match industry expansion.
- Certification timeline compression:Organic and regenerative agriculture certifications require multi-year field history documentation that conflicts with investor pressure for rapid capacity scaling.
- Legacy ERP integration:Batch-level traceability systems demanded by EU and US buyers require retrofitting decades-old farm management software with API-connected blockchain verification layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mushroom Market |
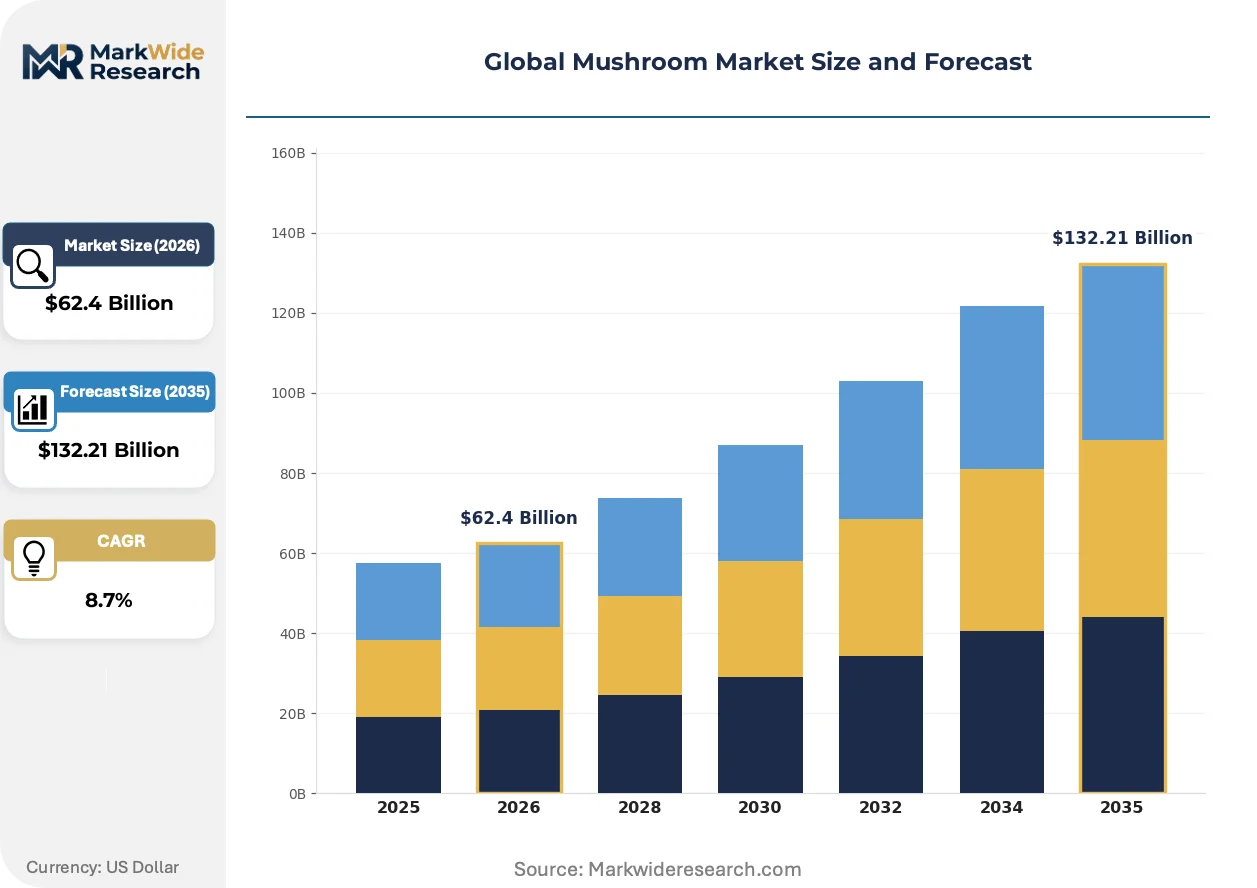
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Button, Shiitake, Oyster, Portabella End User: Food Service, Retail, Food Processing, Nutraceuticals Form: Fresh, Dried, Canned, Powdered Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Convenience Stores |
| Companies Covered | Monterey Mushrooms Inc., Bonduelle Group, Costa Group, CMP Mushroom, Monaghan Group, Greenyard, OKECHAMP S.A., Highline Mushrooms, Shanghai Finc Bio-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mushroom Market Strategic Shifts
Biotechnology and regulatory disclosure requirements are converging to transform how mushroom producers compete on transparency, yield consistency, and functional ingredient verification.
Precision fermentation using engineered yeast strains is rendering obsolete traditional mycelium biomass cultivation for chitin and beta-glucan extraction. Nutraceutical formulators in Germany and California are switching to fermentation-derived inputs that offer batch-to-batch molecular standardization impossible in agricultural harvests. This technology is compressing the addressable market for commodity mushroom powder processors while opening premium pricing tiers for precision-fermented isolates.
REACH chemical input restrictions are tightening allowable pesticide residues and sanitizing agents across European cultivation operations. The ECHA framework now requires substitution plans for quaternary ammonium compounds commonly used in fruiting room disinfection. Dutch and Polish growing cooperatives are responding by deploying UV-C surface treatment and competitive microbial inoculation protocols that satisfy audit requirements without synthetic chemistry.
Chef procurement teams are consolidating purchases through vertically integrated platforms that bundle fresh mushrooms with traceability data and recipe development support. Foodservice distributors in Melbourne, Seoul, and Toronto are disintermediating traditional wholesale terminals by offering harvest-date transparency and varietal substitution recommendations via mobile ordering interfaces. This channel shift is most visible in premium casual dining segments where menu storytelling around provenance commands price premiums.
Global Mushroom Market Segmentation
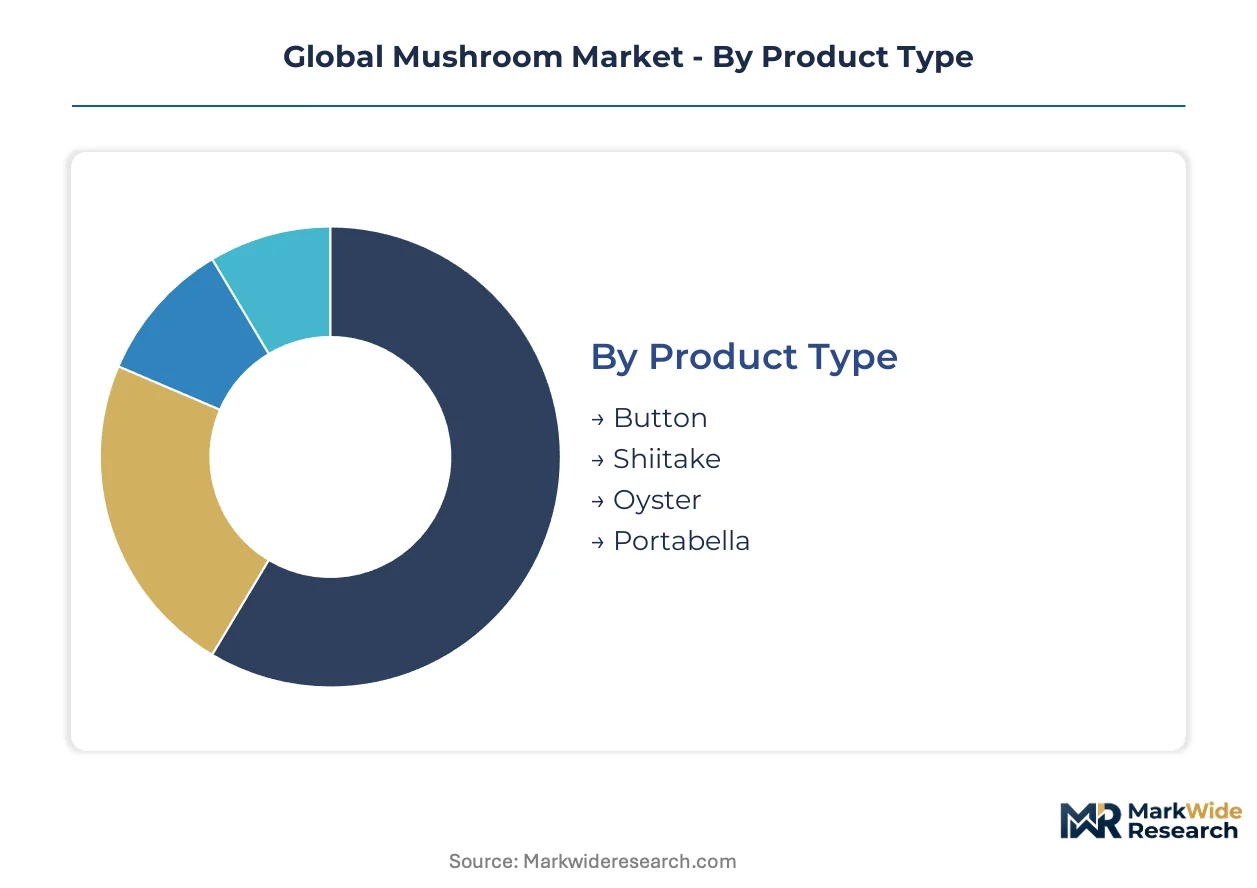
Mushroom market segmentation reveals divergent margin structures and service intensity requirements across product types and channels. Understanding these divisions enables producers to align cultivation investments with downstream buyer specifications and regulatory documentation burdens.
Product Type:
After-sales service intensity varies sharply across mushroom varieties, with premium specialty types demanding spawn technical support and disease diagnostics that commodity growers rarely provide.
- Button:Agaricus bisporus dominates commercial volumes through standardized compost-based cultivation protocols and established consumer familiarity in Western retail. Demand concentrates in US and European foodservice chains where consistent sizing and year-round availability outweigh varietal differentiation. Input cost pressures from wheat straw and poultry manure volatility compress margins for operators lacking long-term substrate contracts.
- Shiitake:Lentinula edodes requires hardwood substrate cultivation and extended spawn-run periods, creating technical barriers that filter out casual growers. Japanese and Chinese nutraceutical extractors contract directly with specialized growers for guaranteed lentinan polysaccharide concentrations, bypassing spot markets entirely. Genetic propagation bottlenecks at certified spawn laboratories in the Netherlands and China create supply vulnerability for premium fresh producers.
- Oyster:Pleurotus species tolerate wider temperature ranges and faster fruiting cycles, enabling low-capital entry in emerging production regions.
- Portabella:Mature Agaricus bisporus strains command grill-focused foodservice premiums through dense texture and umami concentration.
By volume, Button leads. By growth pace, Shiitake is ahead.
End User:
Customer procurement sophistication spans from price-taker retail chains to specification-heavy nutraceutical formulators with batch-level traceability mandates.
- Food Service:Restaurant and institutional buyers prioritize harvest-to-kitchen speed and varietal substitution flexibility over brand loyalty. Australian and South Korean distributors are building chef-facing digital platforms that bypass wholesale terminal markups through just-in-time logistics.
- Retail:Supermarket chains demand uniform sizing, extended shelf-life packaging, and organic certification documentation that favors scaled operators with integrated quality labs.
- Food Processing:Canned and frozen ingredient buyers consolidate supplier rosters around vertically integrated growers capable of simultaneous EU Green Deal carbon accounting and FDA mycotoxin documentation.
- Nutraceuticals:Beta-glucan supplement manufacturers in China are locking in multi-year supply agreements with specialized growers for consistent polysaccharide concentrations, representing the steepest expansion trajectory as functional ingredient demand accelerates.
Food Service captures the largest volume share. Nutraceuticals climbs fastest.
Form:
Processing depth determines margin capture and export radius, with concentrated forms enabling premium pricing where shelf stability permits long-distance trade.
- Fresh:Perishable fruiting bodies require cold-chain infrastructure and rapid turnover, favoring regional producers with direct retail or foodservice relationships. Costa Group commands strong shelf positioning in Australian and Asian retail channels through premium variety specialization.
- Dried:Dehydrated products concentrate flavor compounds and extend shelf life, opening export markets where fresh logistics fail. India's FSSAI streamlined import clearance creates organized retail opportunity as domestic production lags urban protein demand.
- Canned:Bonduelle Group anchors European market presence through deep processing capabilities in sterilized mushroom lines with multi-year shelf stability.
- Powdered:Fine-milled forms serve extractors and functional food formulators requiring standardized particle size and moisture content for downstream processing.
Fresh dominates volume. Powdered gains share fastest.
Distribution Channel:
Channel selection shapes price realization and brand control, with direct formats capturing margin that intermediated wholesale structures surrender.
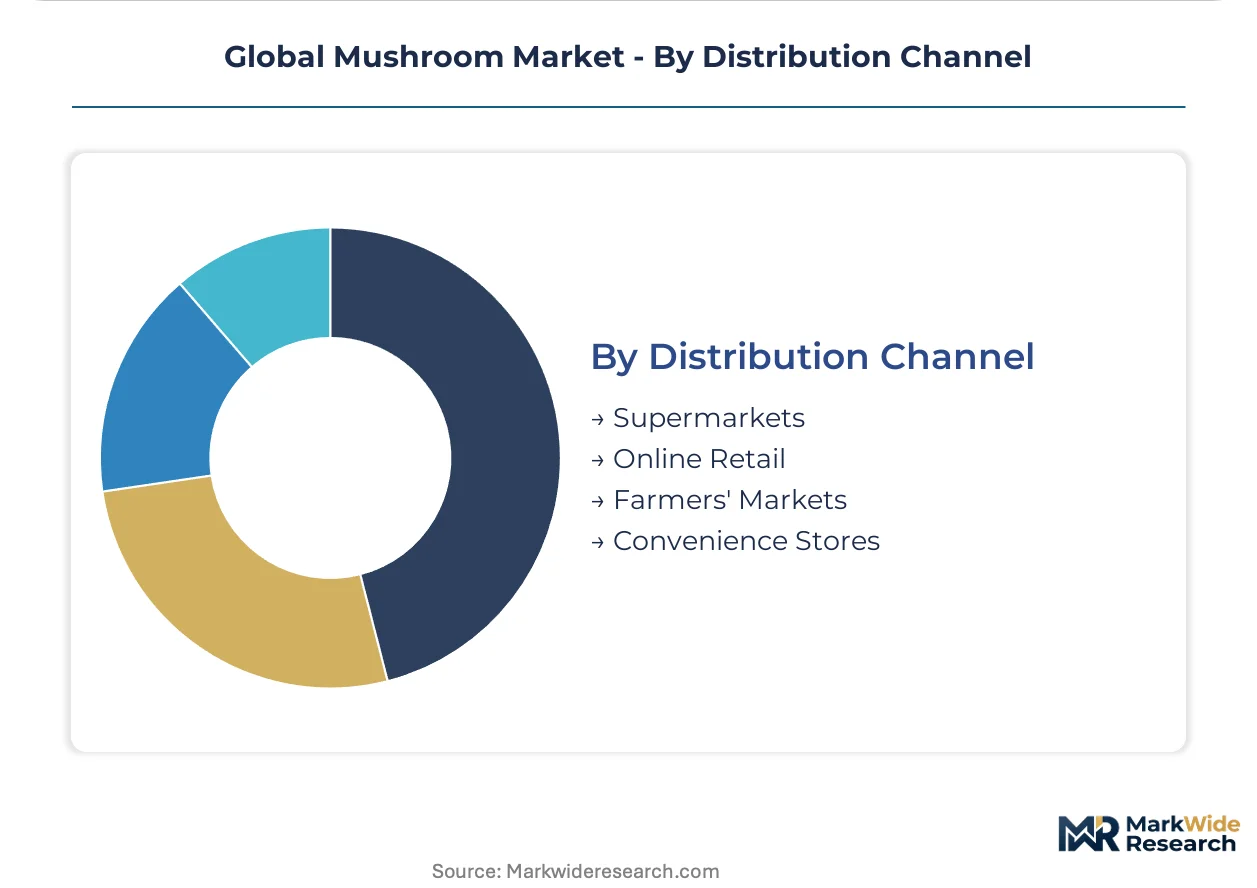
- Supermarkets:Organized retail chains in Germany, Japan, and Australia consolidate produce procurement through centralized buying desks that demand volume consistency and promotional support.
- Online Retail:E-commerce platforms enable dried and powdered specialty sales to dispersed consumers, with Chinese Tmall and JD.com channels scaling fastest for functional mushroom supplements.
- Farmers' Markets:Direct producer-consumer contact supports premium pricing for heritage varieties and organic certification storytelling in urban clusters.
- Convenience Stores:Limited assortment and high-turnover requirements favor pre-packaged dried snacks and ready-to-eat mushroom products in Japanese and South Korean urban formats.
Supermarkets lead by volume. Online Retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain terminals anchor European mushroom import flows, while China's high-speed rail network enables harvest-to-market speed for perishable fresh varieties across its interior provinces.
China
Domestic nutraceutical consumption drives shiitake and reishi extract demand as urban middle-class consumers prioritize immune-support supplements. SAMR enforces divergent food additive approval lists from Western regulators, forcing reformulation strategies for processed goods. Sichuan-Chongqing cultivation clusters are expanding controlled-environment capacity to serve coastal extractors.
United States
Foodservice chains consolidate procurement around vertically integrated growers capable of year-round button mushroom supply. FDA mycotoxin documentation requirements filter smaller operators from institutional buyer rosters. Pennsylvania's Chester County anchors North American Agaricus production through composting infrastructure and spawn laboratory concentration.
Germany
REACH chemical input restrictions tighten allowable pesticide residues across cultivation operations, accelerating substitution plans for quaternary ammonium disinfectants. ECHA frameworks now mandate UV-C surface treatment protocols. Bavarian growing cooperatives are deploying competitive microbial inoculation to satisfy audit requirements without synthetic chemistry.
Netherlands
EU Green Deal carbon accounting mandates force adoption of composted substrate recycling and renewable energy systems for export eligibility. Certified spawn laboratories in the southern provinces create genetic bottleneck vulnerability for European shiitake and maitake producers. Westland greenhouse clusters integrate mushroom cultivation into circular agriculture models.
Australia
Premium fresh variety demand concentrates in Sydney and Melbourne retail channels where provenance storytelling commands price premiums. Costa Group leverages shelf positioning strength across Asian export corridors. Direct-to-restaurant platforms in Victoria and New South Wales bypass wholesale terminal markups through just-in-time harvest-to-kitchen logistics.
Global Mushroom Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated operators capable of meeting simultaneous regulatory documentation and traceability mandates. Tiered competitive dynamics separate global-scale fresh producers from regional processing specialists and niche nutraceutical extractors. Dominant competitive moves include backward integration into spawn production and strategic partnerships with foodservice distributors for direct-to-kitchen channel access.
Within the scale-driven tier, Monterey Mushrooms Inc. and Bonduelle Group exemplify divergent strategic positions—Monterey leveraging North American vertical integration for foodservice consistency, Bonduelle anchoring European market presence through deep processing capabilities. Costa Group occupies a premium-fresh positioning that commands strong shelf placement in Australian and Asian retail channels. Specialists in spawn and substrate technology include Shanghai Finc Bio-Tech, representing the technical-input archetype that underpins cultivation output quality.
| Leading Market Players |
|---|
| Monterey Mushrooms Inc. |
| Bonduelle Group |
| Costa Group |
| CMP Mushroom |
| Monaghan Group |
| Greenyard |
| OKECHAMP S.A. |
| Highline Mushrooms |
| Shanghai Finc Bio-Tech |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's cold-chain terminals anchor European import flows where perishability premiums concentrate pricing power among Dutch and Polish growing cooperatives with EU Green Deal carbon documentation, while downstream buyers in Germany and France face tiered cost structures based on harvest-to-kitchen speed and organic certification tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic specialty varieties from conventional fresh grades and commodity dried powders. Price differentiation hinges on EU Green Deal compliance documentation and vertical integration depth, with integrated operators capturing margin through spawn-to-shelf control. Cost compression in standard-tier button mushrooms is intensifying because wheat straw and poultry manure input volatility squeezes non-contracted growers. Foodservice chains exhibit highest price sensitivity due to volume procurement scale, while Chinese nutraceutical extractors show lowest sensitivity when locking multi-year polysaccharide supply agreements.
Supply Chain Analysis
Genetic bottleneck vulnerability at certified spawn laboratories in the Netherlands and China dominates supply chain risk for shiitake and maitake producers dependent on limited propagation sources. Raw material flows draw from wheat straw in North America, hardwood substrates in East Asia, and poultry manure across European composting operations. Distribution runs through vertically integrated direct-to-restaurant platforms in Australia and South Korea alongside traditional wholesale terminals serving supermarket chains in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mushroom market is recovering from input cost cyclicality as grain commodity stabilization and controlled-environment agriculture adoption restore margin visibility for scaled operators.
For Market Incumbents: Pre-empt precision fermentation displacement by securing exclusive multi-year supply contracts with Chinese beta-glucan extractors before fermentation-derived isolates capture premium pricing tiers. Invest in backward integration into certified spawn production to eliminate genetic bottleneck vulnerability from Dutch and Chinese laboratory concentration. Prioritize EU Green Deal carbon accounting system deployment to maintain export eligibility as REACH chemical restrictions tighten.
For New Entrants and Emerging Players: Establish a beachhead in India's organized dried mushroom retail segment where FSSAI import streamlining has opened shelf space ahead of domestic production scaling. Target chef-facing direct-to-restaurant platforms in Melbourne and Seoul where just-in-time logistics capabilities remain underdeveloped relative to demand concentration. Lead with heritage variety organic certification storytelling to command premium positioning in urban farmers' market clusters.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underoptimized mushroom processing divisions lacking EU Green Deal compliance infrastructure or nutraceutical extraction capabilities. Frame long-term viability around functional ingredient demand acceleration as precision fermentation creates commodity powder compression but opens premium isolate pricing tiers. Monitor SAMR food additive approval list convergence with FDA and EFSA standards as inflection indicator for processed goods export eligibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spawn Production | Eliminates genetic bottleneck vulnerability from Netherlands and China laboratory concentration. |
| EU Green Deal Carbon Accounting Deployment | Secures export eligibility as ECHA REACH restrictions tighten on chemical inputs. |
| Direct-to-Restaurant Platform Partnership | Captures margin through harvest-to-kitchen speed in Australian and South Korean channels. |
| Multi-Year Polysaccharide Supply Contracts | Locks Chinese nutraceutical extractor demand before precision fermentation displaces agricultural biomass. |
| Controlled-Environment Capacity Expansion | Enables year-round output in non-traditional growing regions through AI-driven climate modulation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with spawn laboratory technicians, compost facility managers, nutraceutical procurement leads, and foodservice distribution executives. Secondary validation drew from EU ECHA REACH substance databases, FDA mycotoxin guidance documents, SAMR food additive registers, and customs trade flow records across the analysis window. Bottom-up cultivation capacity modeling and top-down end-use demand estimation were triangulated against reported operator throughput.
Calibration against historical volume and price trajectories informed projection mechanics across product type, end-user category, processing form, and distribution channel dimensions. CAGRs were derived from segmented growth rate reconciliation with macroeconomic drivers and regulatory phase-in schedules. Forecast inputs incorporated EU Green Deal carbon accounting adoption curves, precision fermentation technology diffusion patterns, and controlled-environment agriculture capital deployment cycles.
Stress conditions across wheat straw commodity cycles, avian influenza outbreak frequency, and SAMR regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding climate system automation adoption and spawn laboratory certification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Sweet Potatoes Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Tomato Market
Vegetables
Spain Greenhouse Horticulture Market
Vegetables
Peas Market
Vegetables
UAE Tomato Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
IQF Vegetables Market
Vegetables
Acorn Squash Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Sprouts Market
Vegetables
Squash Market
Vegetables
North America Peas Market
Vegetables
North America Microgreens Market
Vegetables
Turkey Greenhouse Horticulture Market