
 Fresh Vegetables Market | 2026-2036
Fresh Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Vegetables Market Intelligence
The European Union's updated pesticide Maximum Residue Levels (MRLs) regulation is restructuring the cost-of-entry calculus for global exporters. This compliance burden favors large-scale operators with sophisticated supply chain controls. Mastronardi Produce leverages its extensive greenhouse network to consistently meet these stringent standards across continents. BrightFarms specializes in localized, indoor farming, which inherently minimizes pesticide use and shortens complex supply chains.
Fresh vegetables encompass edible plant parts, including leaves, stems, and roots, consumed without significant industrial processing. Characterized by high moisture content and active post-harvest respiration, their shelf life depends on maintaining a controlled cold chain. This category serves as a primary source of vitamins and dietary fiber for households and commercial kitchens. Leafy greens, particularly those from vertical farms, command premium pricing, while the online retail channel is expanding rapidly, altering traditional distribution models.
The U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) enforce strict contaminant and pathogen limits, directly impacting import and export protocols. In China, the State Administration for Market Regulation (SAMR) governs food safety and labeling standards for both domestic and imported produce. Producers must now decide between investing in advanced cultivation technologies or optimizing logistics to serve disparate regional markets effectively.
Market Dynamics
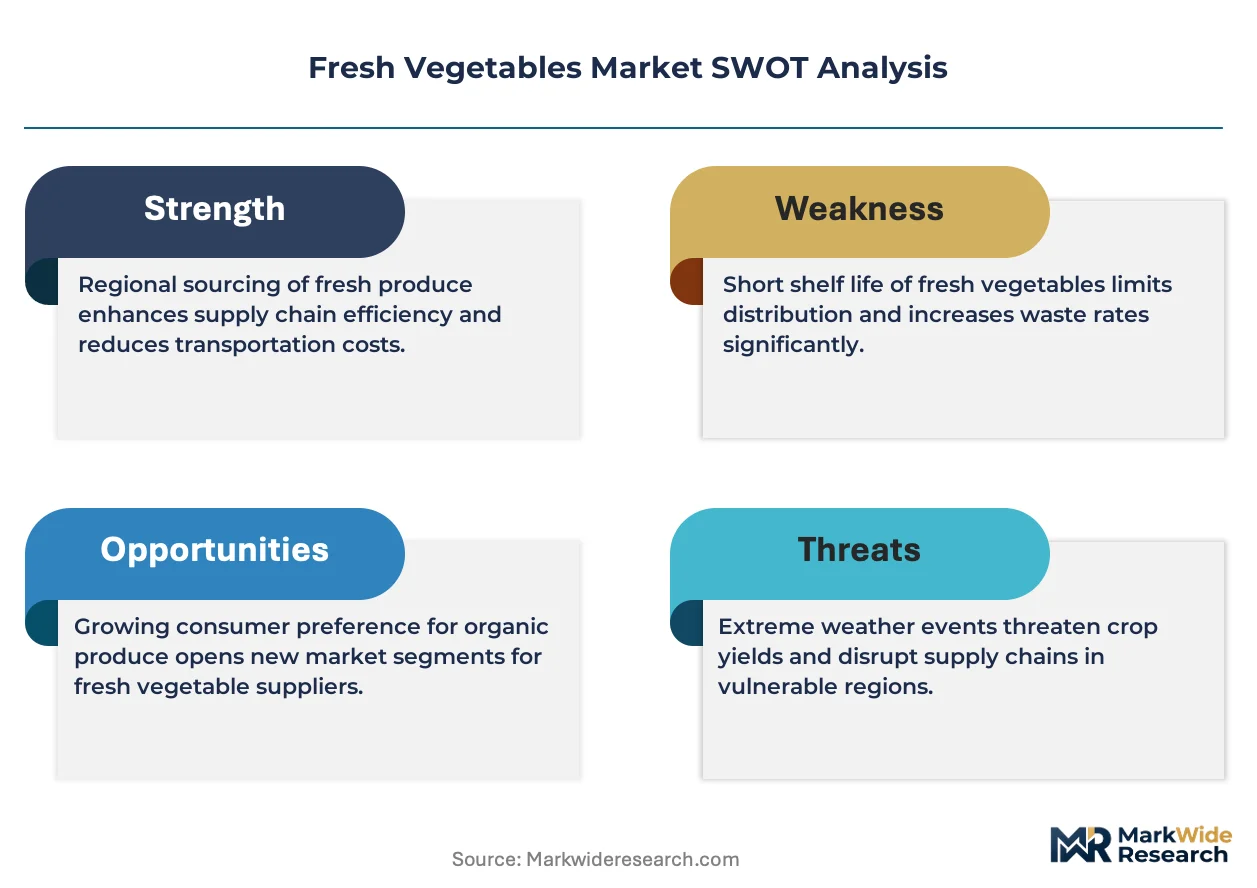
The central tension shaping the fresh vegetables market is the bifurcation of supply chains into highly localized, technology-driven controlled environment agriculture and globalized, logistics-intensive field production, forcing producers to choose a strategic path.
Growth Catalysts
- Evolving Dietary Patterns:A consumer shift towards plant-based diets and health-conscious eating, particularly in developed economies, elevates demand for a diverse range of fresh, nutrient-dense vegetables, including specialty leafy greens and organic varieties.
- Controlled Environment Agriculture:The expansion of vertical farming and advanced greenhouse technologies enables year-round, local production, reducing reliance on long-distance transport and seasonal availability, which is especially impactful for urban centers.
- Regulatory Support for Sustainability:Policies like the European Union's Farm to Fork Strategy encourage farming practices that reduce pesticide and fertilizer use, creating a favorable environment for producers of organic and sustainably certified vegetables.
Market Restraints
- Post-Harvest Losses:Inadequate cold chain infrastructure and logistical inefficiencies, particularly in parts of South Asia and Africa, lead to significant spoilage and value loss between the farm and the end consumer.
- Input Cost Volatility:Producers, especially in controlled environment agriculture, face exposure to fluctuating energy prices, which constitute a major operational cost for lighting and climate control systems, impacting profitability.
- Divergent International Standards:Conflicting Maximum Residue Levels (MRLs) for pesticides between major markets like the European Union, the United States, and Japan create complex compliance burdens and trade barriers for exporters.
Strategic Opportunities
- Direct-to-Consumer Channels:The growth of online platforms and subscription box services creates new avenues for small and medium-sized producers to access consumers directly, bypassing traditional retail intermediaries for specialty and heirloom varieties.
- Value-Added Processing:Opportunities exist in expanding the market for pre-cut, pre-washed, and ready-to-cook vegetable products that cater to consumer demand for convenience without sacrificing freshness or nutritional value.
- Genetic Innovation:Investment in advanced breeding and CRISPR gene-editing techniques can develop new vegetable varieties with enhanced traits such as drought resistance, longer shelf life, and improved nutritional profiles.
Industry Challenges
- Water Scarcity:Increasing water stress in key agricultural regions, including California in the US and the Mediterranean basin, poses a significant operational challenge to conventional field-grown vegetable production, requiring investment in efficient irrigation.
- Labor Shortages:A persistent shortage of agricultural labor for harvesting and processing impacts operational capacity and increases costs, accelerating the push toward automation and robotics in both field and indoor farming.
- Food Safety Compliance:Adhering to stringent pathogen and contaminant regulations from bodies like the FDA and EFSA requires continuous investment in testing, traceability systems, and sanitation protocols, adding to operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Vegetables Market |
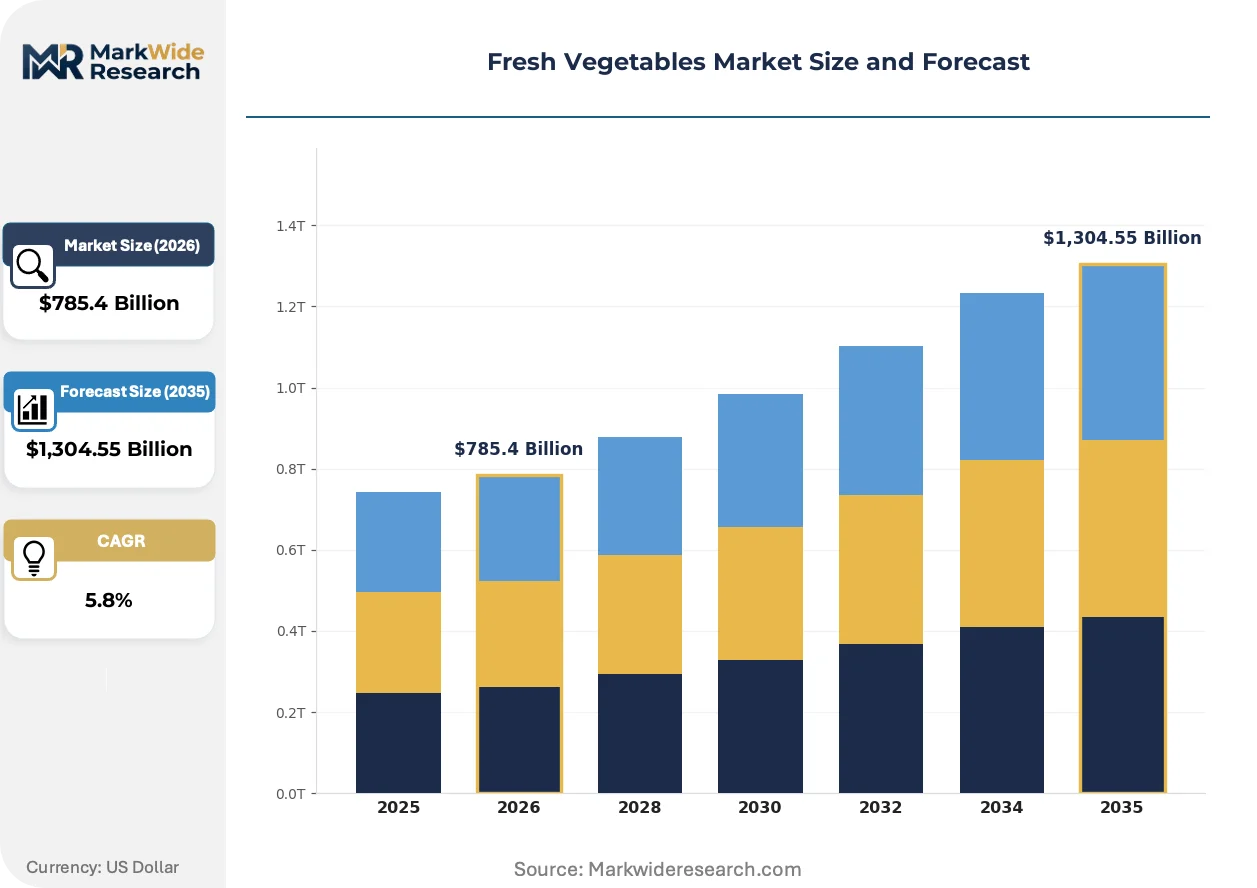
| Market Size in 2026 | $785.4 Billion |
| Market Size in 2035 | $1,304.55 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leafy Greens, Root Vegetables, Cruciferous, Nightshades Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Wholesalers End User: Households, Restaurants, Food Service Providers, Caterers Packaging Type: Bags, Boxes, Clamshells, Bulk Bins |
| Companies Covered | Nature Fresh Farms, Houweling’s Tomatoes, Mastronardi Produce, Little Leaf Farms, BrightFarms, Windset Farms, Mucci Farms, Revol Greens, Village Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Vegetables Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of data-driven technologies into cultivation and distribution. This digital layer is optimizing resource use, enhancing transparency, and altering traditional commercial relationships across the supply chain.
Precision agriculture technology combines IoT sensors, drones, and data analytics to monitor crop health and soil conditions in real time. Large-scale commercial farms are the primary adopters, seeking to optimize inputs like water and fertilizer. This data-centric management is overtaking traditional, calendar-based farming schedules to improve resource efficiency and crop yields.
Updated food safety regulations are mandating greater supply chain transparency. The FDA's Food Safety Modernization Act (FSMA) in the US, for instance, imposes strict record-keeping requirements for certain high-risk foods. This is forcing producers and distributors to adopt digital traceability solutions, such as blockchain or QR code-based systems, to track produce from farm to retail.
A notable behavioral shift is occurring in B2B sourcing, with food service operators and retailers increasingly using online marketplaces to procure produce. This model disrupts the role of traditional wholesale intermediaries, offering buyers direct access to a wider network of growers and more transparent pricing. The trend is most advanced in North America and Western Europe, where digital procurement platforms are gaining significant traction.
Fresh Vegetables Market Segmentation
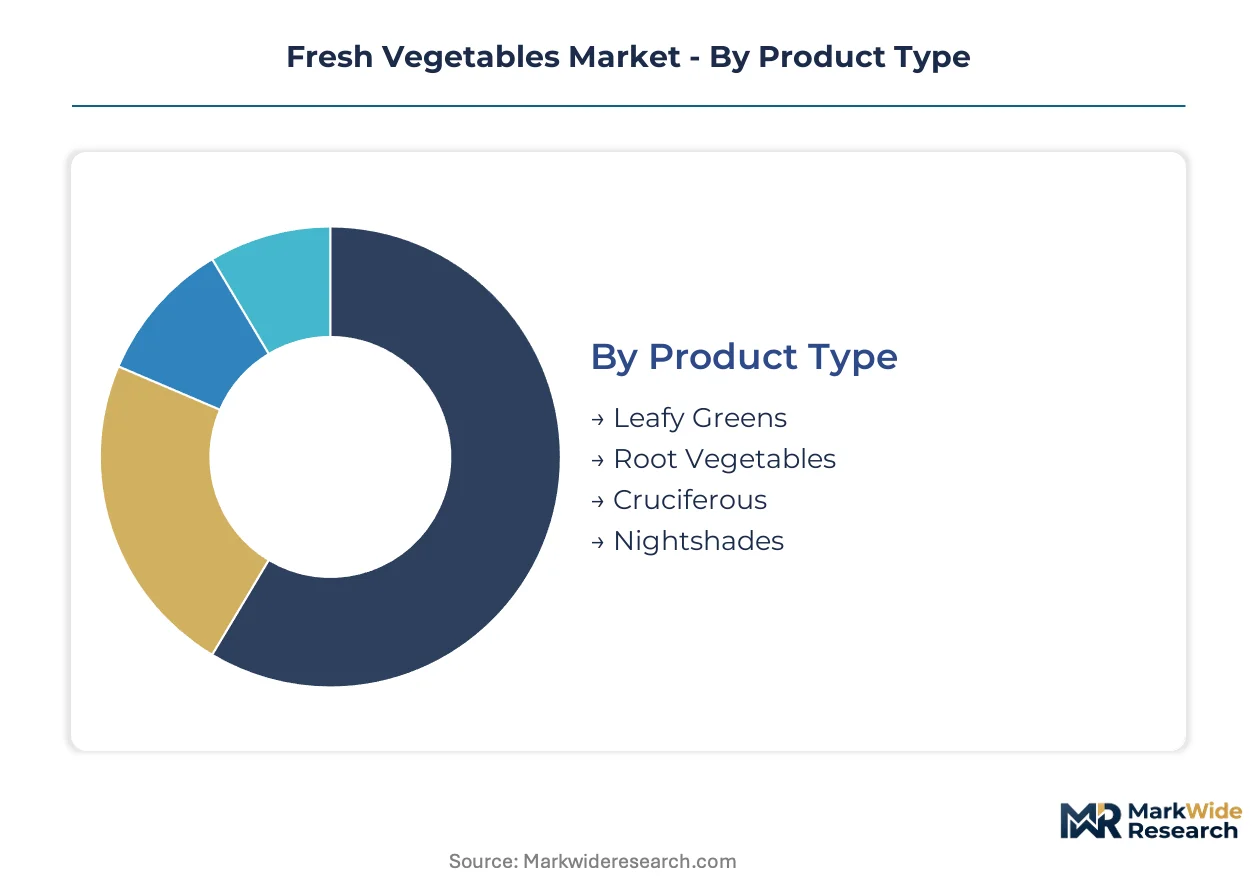
Understanding the Fresh Vegetables Market through segmentation reveals the diverse operational requirements and consumer preferences shaping supply and demand. Each market segment presents unique challenges and opportunities for producers and distributors navigating a complex regulatory and logistical landscape.
Product Type:
Compliance with varied food safety standards, such as those from the U.S. FDA and Europe's EFSA, dictates cultivation and handling protocols across different product types.
- Leafy Greens:These include spinach, lettuce, and kale, characterized by high moisture content and rapid respiration rates. Demand for these vegetables concentrates in urban centers, often supported by localized controlled environment agriculture.
- Root Vegetables:Carrots, potatoes, and onions possess lower respiration rates and extended storage capabilities. Demand for these staples is consistent across households and food service, particularly for bulk procurement and processing.
- Cruciferous:This category encompasses broccoli, cauliflower, and cabbage, valued for their nutritional density and versatility.
- Nightshades: Tomatoes, peppers, and eggplants fall into this group, requiring specific climate conditions for optimal growth and yield.
Root Vegetables sits at the top of the volume ranking, with Leafy Greens climbing the fastest.
Distribution Channel:
The choice of distribution channel reflects varying operational scales and consumer access points, influencing pricing and logistical complexity.
- Supermarkets:This channel represents the primary retail outlet for fresh vegetables, demanding consistent supply volumes and stringent quality control. Procurement emphasizes large-scale, often global, sourcing to meet consumer demand.
- Online Retail:This rapidly expanding channel offers consumers convenience and a broader selection, including specialty and organic produce. Direct-to-consumer models are gaining share, altering traditional wholesale dynamics.
- Farmers' Markets:These venues facilitate direct sales from growers to consumers, emphasizing local, seasonal, and often organic produce.
- Wholesalers:These intermediaries aggregate produce from various farms, supplying large commercial buyers like restaurants and food service providers.
This channel configuration reflects varying consumer priorities, from convenience to local sourcing.
End User:
Each end-user segment exhibits distinct purchasing behaviors, volume requirements, and preferences for fresh vegetable forms and packaging.
- Food Service Providers:This segment includes restaurants, cafeterias, and catering companies, requiring large, consistent volumes of fresh vegetables. Demand for pre-cut and ready-to-use forms is particularly high among commercial kitchens.
- Households:Individual consumers represent a significant demand segment, driven by evolving dietary habits and health-conscious eating. Procurement decisions are influenced by convenience, price, and perceived freshness.
- Restaurants:These establishments prioritize fresh, often specialty, vegetables for culinary innovation and menu differentiation.
- Caterers:Event-based food preparation drives demand for reliable and diverse vegetable supplies to meet specific client needs.
The demand landscape is bifurcated, with commercial kitchens driving bulk orders and households seeking convenience.
Packaging Type:
Packaging solutions are critical for maintaining freshness, extending shelf life, and meeting consumer expectations for convenience and product visibility.
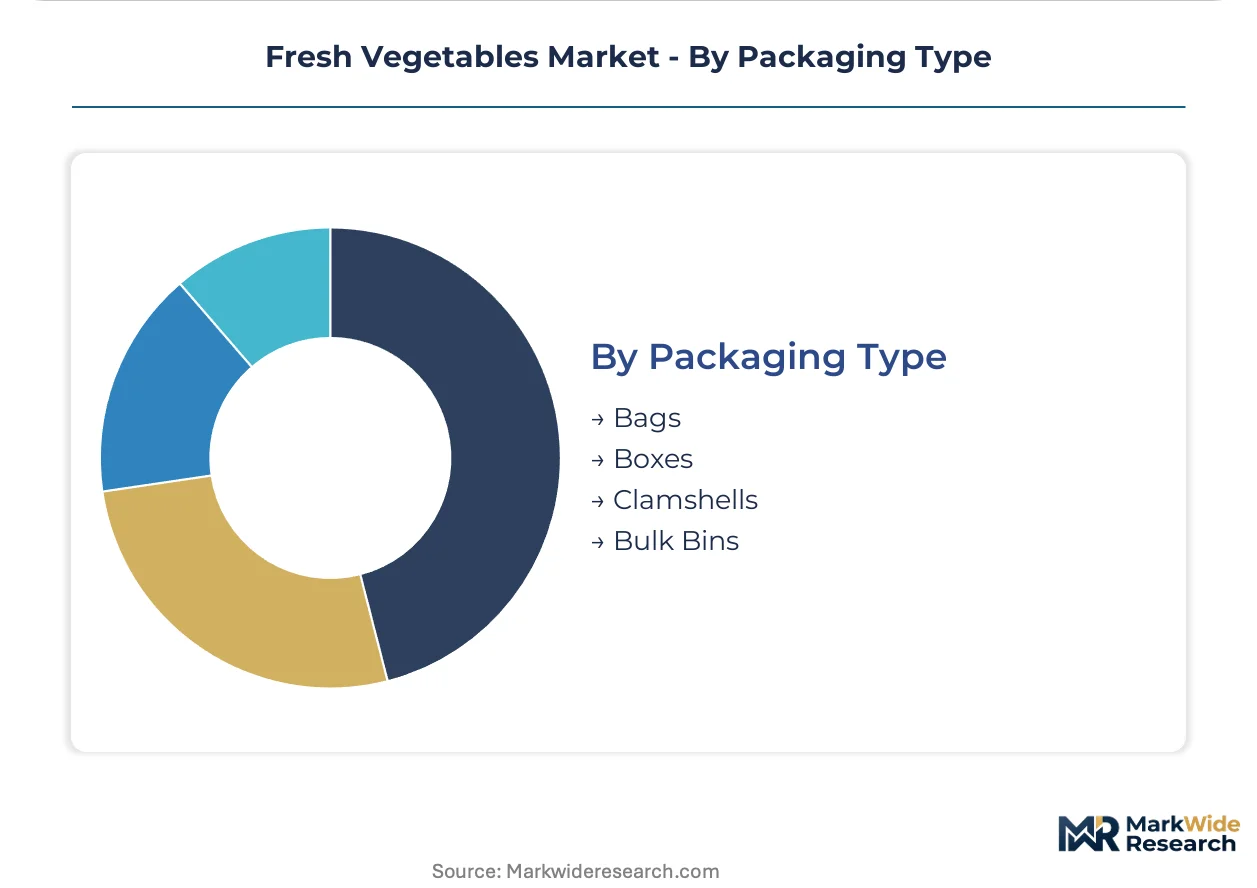
- Clamshells:These rigid, transparent containers protect delicate produce like berries and leafy greens, enhancing product visibility and reducing damage. This packaging type often supports premium pricing for specialty items.
- Bags:Used for a wide range of vegetables, bags offer a cost-effective packaging solution for both bulk and pre-portioned items. This type is prevalent for pre-washed and ready-to-cook vegetables.
- Boxes:Standard for bulk transport and display, boxes provide structural integrity for various produce items.
- Bulk Bins:Large containers facilitate efficient transport and storage of high-volume commodities, often used for food service distribution.
Packaging choices reflect a balance between product protection, consumer convenience, and cost considerations across the supply chain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cultivation of fresh vegetables traces its origins to early agricultural civilizations, with regions like the Fertile Crescent and ancient China pioneering systematic farming techniques. These foundational practices scaled globally, establishing diverse regional production centers. Today, various geopolitical factors and consumer demands shape fresh vegetable markets worldwide.
United States
Consumer demand for diverse fresh vegetables and organic varieties drives market growth in the United States. The FDA's Food Safety Modernization Act (FSMA) mandates stringent record-keeping for high-risk foods, impacting supply chains. California's Central Valley, a primary agricultural region, spearheads large-scale field production and water-efficient irrigation technologies.
China
Evolving dietary habits and a strong emphasis on food quality fuel significant demand for fresh vegetables in China. The State Administration for Market Regulation (SAMR) enforces strict food safety and labeling standards for both domestic and imported produce. Shandong province, a major agricultural hub, utilizes advanced greenhouse systems to ensure consistent vegetable supply to urban centers.
Germany
German consumers prioritize sustainably produced and organic vegetables, increasing demand for specialty items. The European Union's updated pesticide MRLs regulation creates a high compliance burden for exporters. The Rhine-Ruhr region, a major consumption area, sees growing investment in localized indoor farming to meet fresh produce needs.
India
India's large and growing population ensures consistent demand for staple fresh vegetables as a core dietary component. The FSSAI (Food Safety and Standards Authority of India) establishes national standards for food safety and quality. The Indo-Gangetic Plain, a vast agricultural region, contributes substantially to bulk vegetable output, though post-harvest infrastructure needs improvement.
Netherlands
The Netherlands exhibits strong demand for advanced horticulture solutions and high-quality produce for export markets. The EU's Farm to Fork Strategy promotes farming practices that reduce pesticide and fertilizer use. The Westland region, known as the 'Glass City,' excels in controlled environment agriculture, driving innovation in year-round vegetable production.
Fresh Vegetables Market Key Industry Players
The competitive structure tilts toward a dual-pronged model, featuring both large-scale, logistics-intensive field producers and technology-driven controlled environment agriculture specialists. This market is characterized by a fragmented base of regional growers alongside a consolidating tier of advanced greenhouse operators. Leading firms engage in significant capacity expansion, particularly in indoor farming, and form strategic partnerships to optimize distribution channels.
Within the advanced cultivation segment, companies like Mastronardi Produce exemplify large-scale greenhouse operations with extensive networks, enabling consistent supply and compliance with varied international standards. BrightFarms represents a localized, indoor farming archetype, specializing in controlled environments to minimize pesticide use and reduce transportation distances for fresh produce. Revol Greens further illustrates the expansion of technology-driven agriculture, occupying a position focused on sustainable, year-round production of leafy greens. These players collectively showcase the industry's strategic bifurcation towards either globalized scale or regional technological intensity.
| Leading Market Players |
|---|
| Nature Fresh Farms |
| Houweling’s Tomatoes |
| Mastronardi Produce |
| Little Leaf Farms |
| BrightFarms |
| Windset Farms |
| Mucci Farms |
| Revol Greens |
| Village Farms |
| Others |
Cost & Logistics Intelligence
Energy cost volatility, a critical input for controlled environment agriculture, directly influences production expenses and subsequent downstream pricing for premium fresh vegetables.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for bulk fresh vegetables supplied to food service providers, ensuring supply stability. Price differentiation stems from quality grade, with organic and specialty leafy greens commanding a premium due to certification and localized sourcing. Pricing pressure intensifies for conventional field-grown produce due to fluctuating input costs and intense competition. Households often exhibit higher price sensitivity for staple root vegetables compared to their willingness to pay for convenient, pre-packaged leafy greens.
Supply Chain Analysis
Compliance with varied food safety standards, such as the EU's updated pesticide MRLs and the FDA's FSMA, acts as a significant gating factor for market access. Geographic supply concentration for field-grown vegetables centers on regions like California in the US, Shandong province in China, and the Indo-Gangetic Plain in India. The supply chain draws from critical inputs including water, specialized seeds, and energy for climate control in advanced greenhouses. Post-harvest losses, particularly in regions with inadequate cold chain infrastructure, represent a significant structural risk. Distribution runs through a bifurcated model, with supermarkets handling large volumes and online retail expanding direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by consumer willingness to pay for premium, sustainably produced fresh vegetables.
For Market Incumbents: Anchor investment in advanced controlled environment agriculture technologies to ensure year-round supply and mitigate seasonality risks. Develop robust digital traceability systems to comply with stringent regulations like the FDA's FSMA, addressing the threat of divergent international standards. Expand logistics networks to optimize cold chain efficiency, reducing post-harvest losses and enhancing product freshness for consumers.
For New Entrants and Emerging Players: Localized indoor farming technology offers a primary wedge into urban markets, bypassing long-distance logistics for high-value leafy greens. Target the rapidly expanding online retail channel with direct-to-consumer models for specialty and organic varieties, leveraging convenience as a go-to-market angle. Focus on value-added processing for pre-cut and ready-to-cook vegetables, catering to household demand for convenience in busy lifestyles.
For Investors and Strategic Acquirers: Consolidation pressure builds where compliance burdens and technology investments create barriers to entry for smaller operators. The long-term viability of the fresh vegetables market is strong, supported by evolving dietary patterns and health-conscious eating. Acquisition targets should include large-scale greenhouse operators with established distribution networks or technology providers specializing in precision agriculture. Energy cost trends represent a critical signal to watch as an inflection indicator for CEA profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Controlled Environment Agriculture | Increases year-round production of high-value fresh vegetables, reducing reliance on seasonal field crops. |
| Investment in Advanced Cold Chain Logistics | Minimizes post-harvest losses and extends the shelf life of perishable produce across distribution networks. |
| Implementation of Digital Traceability Solutions | Ensures compliance with stringent food safety regulations like FDA FSMA, enhancing consumer trust and market access. |
| Diversification into Value-Added Vegetable Products | Captures consumer demand for convenience with pre-cut and ready-to-cook options, expanding revenue streams. |
| Strategic Partnerships with Online Retailers | Expands market reach and offers direct-to-consumer channels for specialty and organic fresh vegetables. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, validating market trends and forecasts. This involved primary interviews with agricultural technology developers, food service procurement managers, retail buyers, and logistics providers. Secondary validation drew from FDA records, EFSA reports, SAMR guidelines, and agricultural census data, triangulating insights from both bottom-up and top-down perspectives.
The segment-weighting approach informed the analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, distribution channel, end-user, and packaging type, alongside an industry-specific focus on cultivation method. Compound annual growth rates were derived by integrating historical data with projections based on consumer dietary shifts and controlled environment agriculture investment trends.
The model holds under current consumer preference and regulatory stability; deviation in energy prices or major climate events would shift forecasts. A model refresh is warranted upon material change in global trade policies or significant advancements in genetic innovation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Qatar Greenhouse Market
Vegetables
Europe Pea Market
Vegetables
Tomato Market
Vegetables
North America Peas Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
IQF Vegetables Market
Vegetables
Vegetable Chutney Market
Vegetables
South America Peas Market
Vegetables
North America Sweet Potatoes Market
Vegetables
Greenhouse Produce Market
Vegetables
Dried Mushroom Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Asparagus Market
Vegetables
Sprouts Market
Vegetables
Ghana Fruit and Vegetable Market