
 Microgreens Market | 2026-2036
Microgreens Market Size, Share, and Industry Trends Forecast 2026-2036
Microgreens Market Intelligence
The gap between premium living-tray microgreens and pre-cut commodity packs is expanding as restaurants demand root-intact freshness while retailers push shelf-stable clamshells. AeroFarms leverages vertical aeroponic systems to command price premiums in urban foodservice corridors. Fresh Origins anchors the premium tier through specialty varietal cultivation for white-tablecloth accounts. Gotham Greens competes on consistent year-round supply through greenhouse network density.
Microgreens are immature vegetable seedlings harvested at the cotyledon or first true-leaf stage, typically seven to twenty-one days after germination, containing concentrated phytonutrient profiles exceeding mature plant levels by four to forty times depending on species. Their primary commercial purpose centers on culinary garnish, flavor intensity, and nutritional density enhancement for prepared foods and beverages. Pea shoots and radish microgreens lead volume throughput due to rapid turnaround cycles and broad menu compatibility across restaurant and grocery channels. Online retail and direct sales to foodservice operators represent the fastest-growing distribution pathways as buyers prioritize harvest-to-door traceability. Clamshell packaging dominates retail shelf placement while bulk trays capture institutional and restaurant procurement flows.
The FDA's Produce Safety Rule mandates agricultural water testing and sanitation protocols for microgreen operations, while the EU's General Food Law and national hygiene packages impose parallel traceability and HACCP documentation burdens on importers. USDA organic certification and third-party food safety audits such as SQF shape buyer qualification thresholds and channel access for commercial growers. Stakeholders must monitor evolving soilless agriculture standards and carbon labeling requirements that will reshape sourcing decisions and facility investment priorities.
Market Dynamics
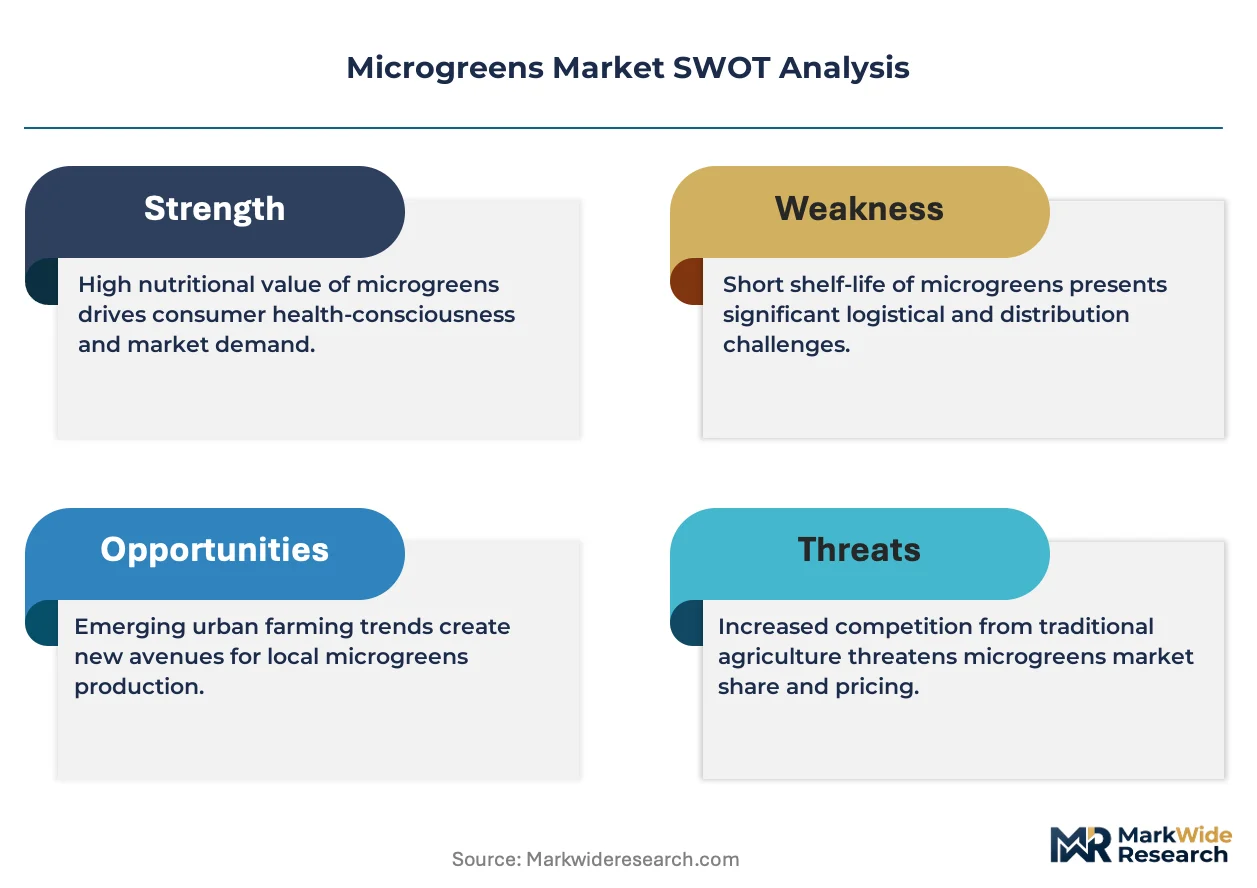
Fine-dining procurement of living microgreen trays is fragmenting supply relationships as restaurants bypass distributors for direct farm partnerships, compressing traditional wholesale margins while elevating traceability requirements across soilless agriculture operations.
Growth Catalysts
- EU General Food Law traceability mandates:HACCP documentation requirements for importers are qualifying professional growers for institutional contracts, channeling investment into climate-controlled greenhouse infrastructure.
- Pea shoot and radish varietal standardization:Rapid seven-to-fourteen-day harvest cycles enable inventory turnover rates that justify premium pricing in urban foodservice corridors.
- California Central Coast cluster concentration:Proximity to San Francisco and Los Angeles distribution hubs reduces harvest-to-door transit times below twenty-four hours for living-tray products.
Market Restraints
- Input cost volatility in LED lighting and climate control:Energy-intensive vertical farm operations face margin compression when electricity rates spike in metropolitan load zones.
- Geographic supply concentration in Netherlands Westland:Dependence on a single greenhouse corridor for European winter production creates weather-related disruption exposure.
- Substitution threat from mature baby greens:Pre-cut spinach and arugula clamshells compete on price-per-ounce in retail channels where freshness differentiation is muted.
Strategic Opportunities
- Underpenetrated direct-to-consumer subscription channels:Home chefs in secondary US metros represent untapped demand for harvest-to-door microgreen delivery with varietal customization.
- Carbon labeling tailwinds under EU Green Deal:Soilless cultivation's water efficiency metrics qualify products for preferential placement in sustainability-indexed retail assortments.
- Technology convergence of IoT sensors and automated nutrient dosing:Precision agriculture platforms reduce labor intensity while standardizing phytonutrient density across harvest batches.
Industry Challenges
- Horticultural technician skill scarcity:Soilless agriculture requires specialized expertise in hydroponic pathology and environmental control systems that outpaces vocational training pipeline output.
- USDA organic certification timeline compression:Three-year transition periods for conventional greenhouse conversions delay premium price capture for expanding operations.
- Legacy ERP integration with harvest-tracking software:Batch-level traceability systems demand middleware investment that strains mid-cap grower IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microgreens Market |
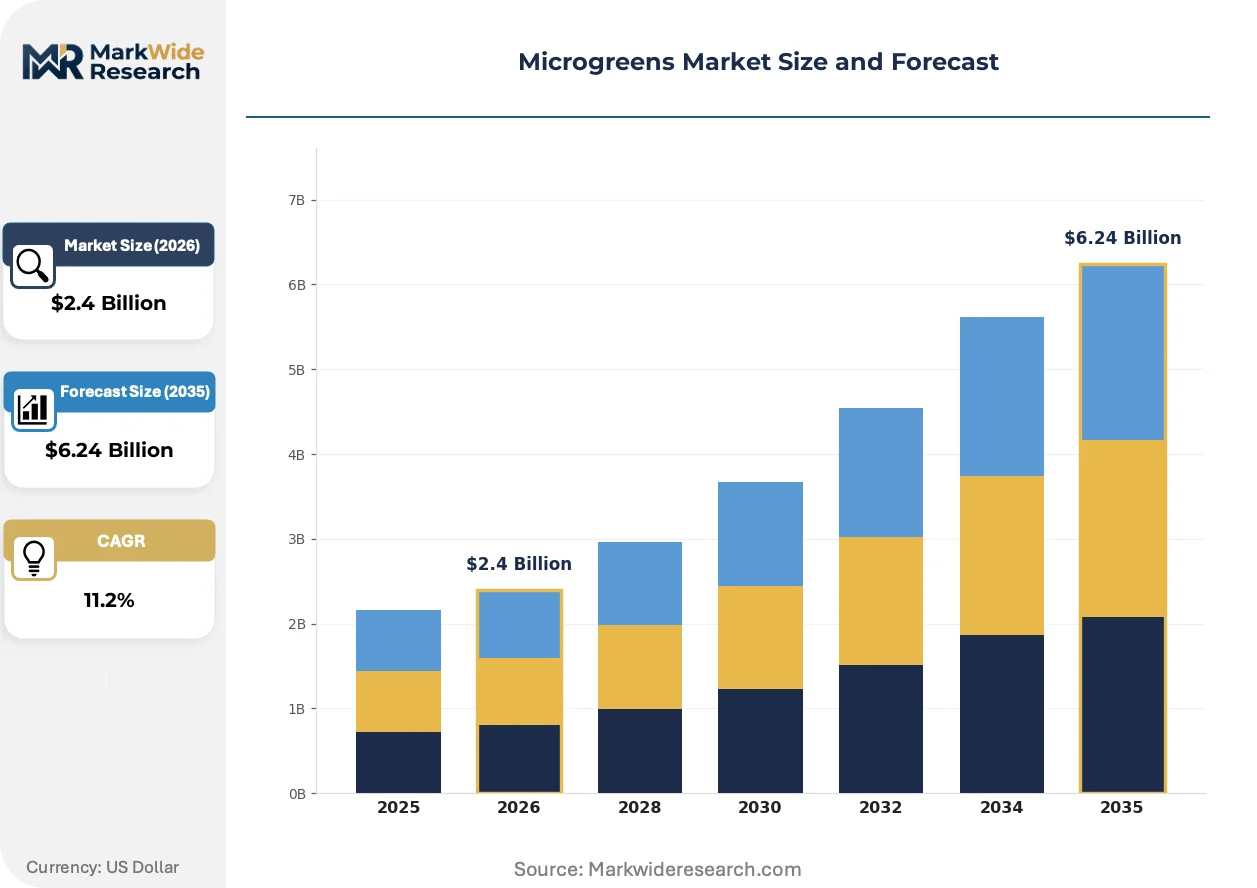
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basil, Mustard Greens, Pea Shoots, Radish End User: Restaurants, Grocery Stores, Home Cooks, Health Enthusiasts Distribution Channel: Online Retail, Wholesale, Direct Sales, Farmers' Markets Packaging Type: Clamshells, Bags, Trays, Bulk Packaging |
| Companies Covered | AeroFarms, Fresh Origins, Gotham Greens, GoodLeaf Farms, Farmbox Greens, 2BFresh, Bowery Farming, The Chef's Garden, Living Earth Farm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microgreens Market Strategic Shifts & Innovations
Aeroponic cultivation systems are compressing the cost-performance frontier for urban microgreen production, while regulatory carbon-accounting frameworks and procurement model fragmentation simultaneously reshape competitive positioning.
Closed-loop aeroponic towers are overtaking substrate-based tray systems in metropolitan vertical farms by eliminating soil-handling labor and reducing water consumption. Urban foodservice distributors in Chicago and New York are retrofitting warehouse facilities with modular tower arrays to capture living-tray premiums. This technology is overtaking traditional greenhouse bench systems in land-constrained markets where square-foot productivity determines facility viability.
REACH chemical registration requirements for hydroponic nutrient formulations are elevating compliance costs for European import-dependent supply chains. The regulation forces reformulation of proprietary fertilizer blends to exclude restricted compounds, compressing supplier margins. Dutch greenhouse operators are responding by consolidating backward into captive nutrient manufacturing to secure supply chain continuity.
White-tablecloth buyers are fragmenting procurement across multiple single-source farms rather than consolidating through broadline distributors. This pattern displaces traditional foodservice intermediaries in coastal metropolitan markets where chefs prioritize cultivar specificity over volume discounts. The shift is most visible in California's San Francisco Bay Area, where direct farm relationships now dominate fine-dining microgreen sourcing.
Microgreens Market Segmentation
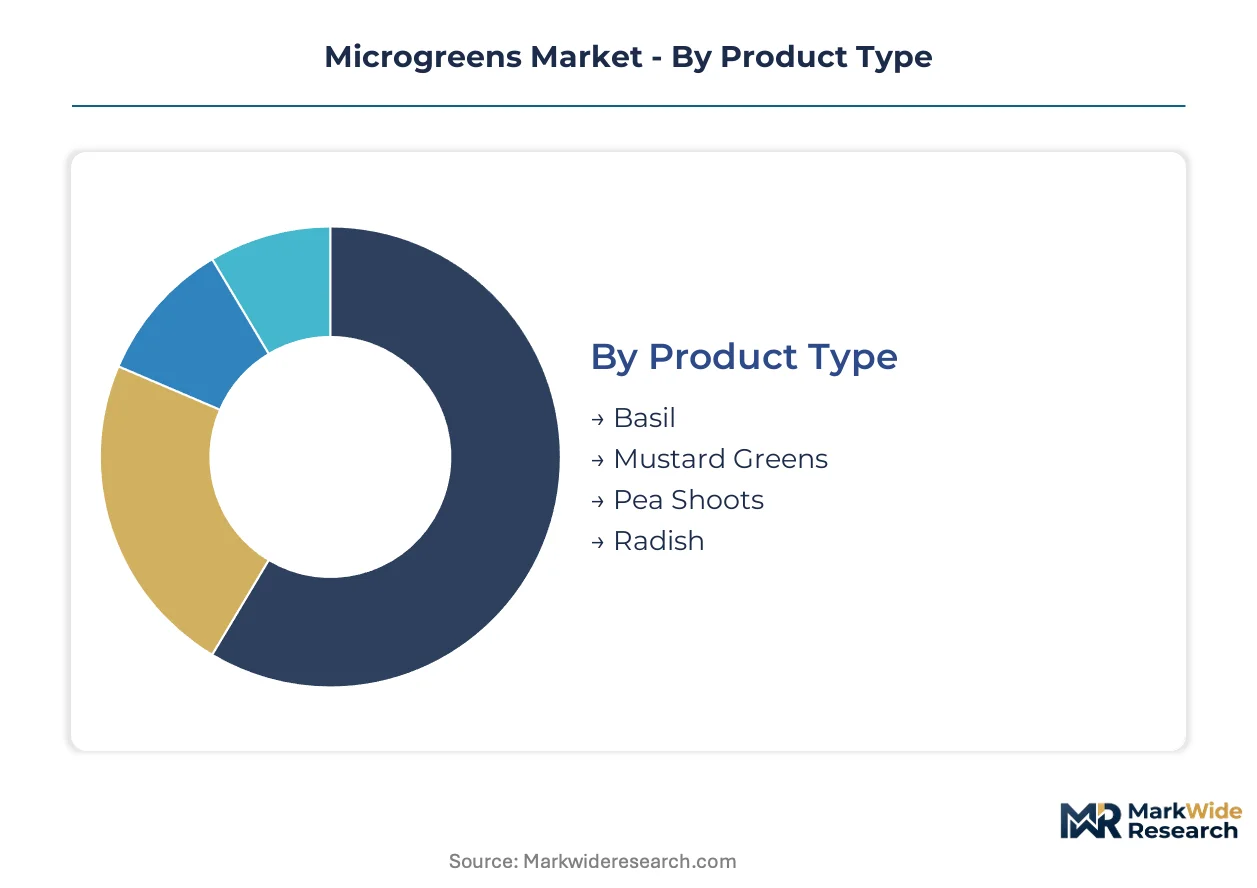
Microgreens producers face divergent buyer priorities across channels. Chefs demand living-tray freshness with cultivar specificity. Retail buyers prioritize shelf-stable packaging and consistent supply. Home cooks seek varietal customization with harvest-to-door speed.
Product Type:
Chefs and retailers select varietals based on harvest cycle speed, flavor intensity, and menu compatibility rather than nutritional claims alone.
- Pea Shoots:These tender tendrils deliver mild sweetness and rapid seven-to-fourteen-day turnaround cycles. California's Central Coast cluster supplies San Francisco and Los Angeles foodservice corridors within twenty-four hours of harvest, justifying premium living-tray pricing.
- Radish:Peppery cotyledons provide visual contrast and flavor intensity that commands plate placement in white-tablecloth accounts. Dutch Westland greenhouse operators standardize radish cultivars for year-round European supply, reducing weather-related disruption exposure.
- Basil:Aromatic microgreens with concentrated essential oil profiles suit Mediterranean and Asian fusion menus.
- Mustard Greens:Sharp, horseradish-like notes differentiate premium garnish applications from commodity alternatives.
Pea shoots lead volumes today; radish microgreens are gaining share fastest.
End User:
Procurement sophistication varies sharply across buyer categories, from direct farm relationships to distributor consolidation.
- Restaurants:Fine-dining operators bypass broadline distributors for single-source farm partnerships. San Francisco Bay Area chefs fragment procurement across multiple living-tray suppliers to secure cultivar specificity.
- Grocery Stores:Retail buyers prioritize clamshell shelf stability and consistent year-round supply through greenhouse network density.
- Home Cooks:Secondary US metro demand concentrates in subscription channels with varietal customization options.
- Health Enthusiasts:Phytonutrient density claims drive direct-to-consumer purchases through online platforms.
Restaurants dominate procurement value; home cooks are expanding most quickly.
Distribution Channel:
Traceability requirements and margin compression reshape how microgreens reach end buyers.
- Direct Sales:Farm-to-chef relationships eliminate distributor markups while satisfying FDA Produce Safety Rule documentation demands. This channel captures living-tray premiums in coastal metropolitan markets.
- Online Retail:E-commerce platforms enable harvest-to-door traceability for home chefs. Chicago and New York urban foodservice distributors retrofit warehouses with modular aeroponic towers to serve this channel.
- Wholesale:Traditional intermediaries face margin compression as restaurants consolidate direct relationships.
- Farmers' Markets:Local provenance appeals support premium pricing in community-supported agriculture networks.
Direct sales anchor revenue today; online retail shows the steepest expansion trajectory.
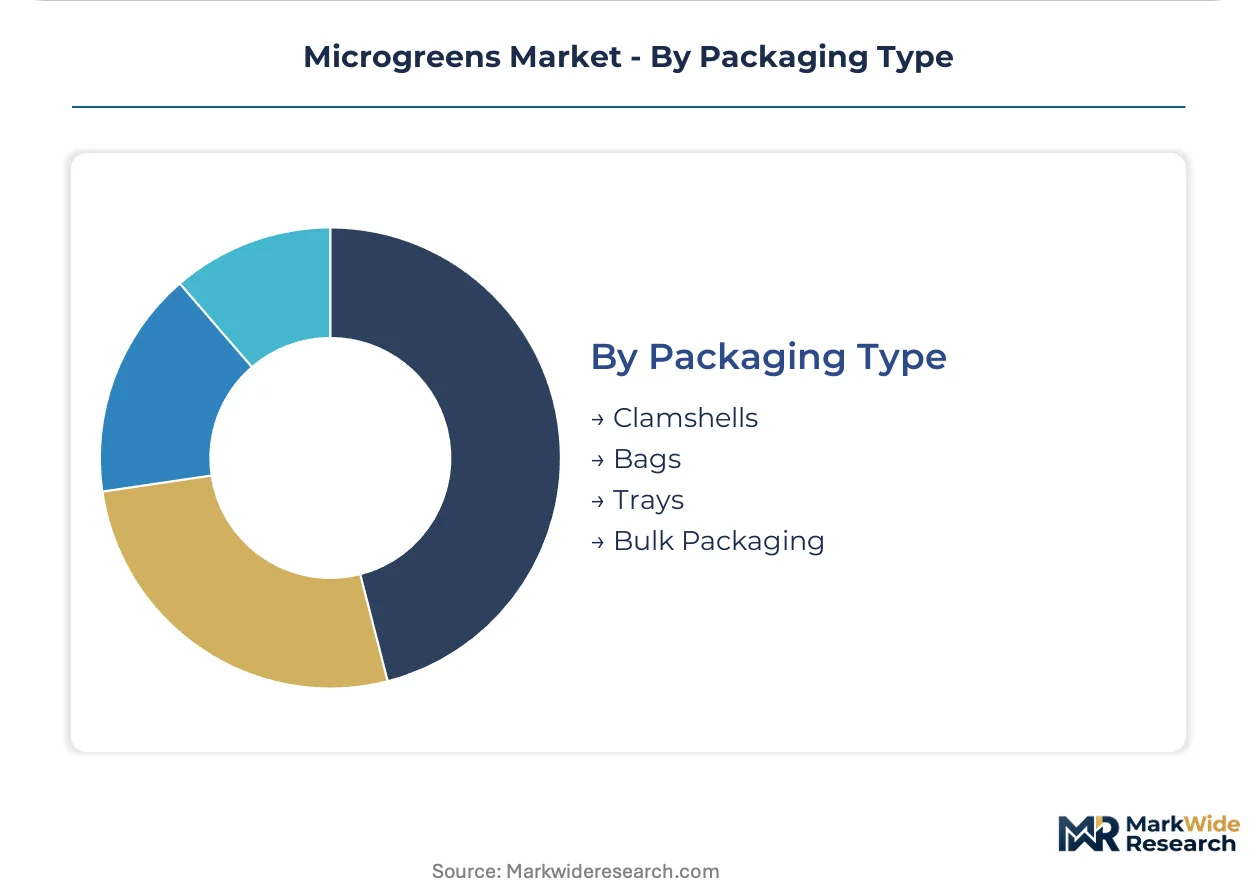
Packaging Type:
Packaging format determines shelf life, transport economics, and buyer category access.
- Trays:Root-intact living products deliver maximum freshness for restaurant plate presentation. Fine-dining procurement of these formats is fragmenting supply relationships across soilless agriculture operations.
- Clamshells:Sealed containers extend shelf life for retail grocery placement. This format competes with pre-cut baby greens on price-per-ounce where freshness differentiation is muted.
- Bulk Packaging:Institutional buyers in foodservice and hospitality capture volume discounts through large-format procurement.
- Bags:Flexible packaging reduces freight costs for direct-to-consumer subscription shipments.
Trays dominate foodservice procurement; clamshells capture retail shelf presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized horticultural technicians cluster in California's Central Coast and the Netherlands' Westland corridor, anchoring two distinct production ecosystems for soilless microgreen cultivation.
United States
Fine-dining procurement in San Francisco and Los Angeles drives living-tray demand with twenty-four-hour harvest-to-door requirements. The FDA's Produce Safety Rule mandates agricultural water testing and sanitation documentation for all commercial operations. California's Central Coast cluster supplies both coastal metropolitan corridors through dense greenhouse networks.
Netherlands
Year-round greenhouse production serves European foodservice and retail channels with standardized radish and pea shoot varietals. The EU's General Food Law imposes HACCP documentation burdens on all microgreen importers and domestic producers. Westland greenhouse operators consolidate backward into captive nutrient manufacturing to navigate REACH chemical registration requirements.
Germany
Retail buyers in Berlin and Munich prioritize clamshell shelf stability and carbon-labeled assortments under EU Green Deal frameworks. The country's national food safety regulator enforces strict traceability protocols for soilless-grown leafy greens. Bavarian greenhouse operators invest in climate-controlled infrastructure to qualify for institutional contracts.
United Kingdom
London's white-tablecloth restaurants fragment procurement across direct farm partnerships for cultivar specificity. Post-Brexit food safety regulations parallel EU hygiene packages with additional import documentation requirements. Southeast England greenhouse clusters serve the capital's foodservice corridor with compressed transit economics.
Canada
Urban vertical farms in Toronto and Vancouver retrofit warehouse facilities with modular aeroponic towers for foodservice distribution. Health Canada and the Pest Management Regulatory Agency oversee residue testing and facility sanitation standards. Ontario's greenhouse concentration supplies eastern Canadian retail and restaurant channels through distributor networks.
Microgreens Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent facility economics. The vendor base fragments between vertical aeroponic operators, greenhouse network consolidators, and specialty varietal cultivators. Three strategic archetypes dominate: urban vertical farms commanding metropolitan premiums, regional greenhouse networks optimizing year-round supply consistency, and single-source specialty growers serving white-tablecloth accounts. Competitive moves concentrate on direct farm partnerships that bypass distributors and modular facility expansion into secondary metros.
Within the vertical farming tier, AeroFarms and Bowery Farming exemplify asset-heavy metropolitan positioning through aeroponic tower density. Fresh Origins anchors the specialty varietal segment for premium foodservice accounts. Gotham Greens occupies a position between these vectors through greenhouse network scale that delivers consistent supply to retail and foodservice buyers.
| Leading Market Players |
|---|
| AeroFarms |
| Fresh Origins |
| Gotham Greens |
| GoodLeaf Farms |
| Farmbox Greens |
| 2BFresh |
| Bowery Farming |
| The Chef's Garden |
| Living Earth Farm |
| Others |
Cost & Logistics Intelligence
Horticultural technician clusters in California's Central Coast and the Netherlands' Westland corridor anchor labor-cost differentials that drive pricing-tier spreads across living-tray and clamshell formats. FDA Produce Safety Rule compliance investments and EU HACCP documentation burdens widen the gap between certified premium operations and uncertified commodity suppliers.
Pricing Analysis
Bundled harvest-to-door traceability services command premiums over unbundled commodity clamshells in coastal metropolitan markets. Three-tier pricing structure across premium living-tray, standard greenhouse-certified, and economy imported-clamshell levels separates root-intact freshness from shelf-stable alternatives. Pricing pressure stems from LED energy costs and climate-control inputs compressing vertical farm margins during electricity rate spikes. Retail buyers exhibit highest price sensitivity, while fine-dining chefs prioritize cultivar specificity over per-ounce economics.
Supply Chain Analysis
Workforce availability constraints in California, the Netherlands, and Canada limit expansion velocity for climate-controlled greenhouse operations. Supply draws from concentrated coastal clusters near San Francisco, Los Angeles, and Amsterdam distribution hubs. Raw material dependencies include LED lighting systems, hydroponic nutrient formulations, and climate-control equipment. Single-source vulnerability in the Westland corridor for European winter production creates weather-related disruption exposure. Distribution runs through direct farm-to-chef relationships, online retail platforms, and consolidating wholesale intermediaries facing margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA Produce Safety Rule enforcement and EU General Food Law traceability mandates continuously elevate compliance investment thresholds for commercial participation.
For Market Incumbents: Acquire captive nutrient manufacturing capabilities to secure supply chain continuity against REACH chemical registration reformulation costs. Consolidate backward into proprietary seed genetics and cultivar development to defend against specialty varietal entrants. Expand greenhouse network density in secondary US metros to capture direct-to-chef relationships before distributor margin compression accelerates. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels in secondary US metropolitan markets where living-tray penetration remains underdeveloped. Target home chefs seeking varietal customization with harvest-to-door speed guarantees. Exploit aeroponic tower modularity to retrofit urban warehouse facilities with lower capital intensity than greenhouse bench systems. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap greenhouse operators with USDA organic certification timelines already completed. Long-term viability favors facilities with demonstrated year-round supply consistency and established direct foodservice relationships. Watch carbon-labeling adoption velocity under EU Green Deal frameworks as the signal indicating sustainability-indexed retail placement premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nutrient Manufacturing | Dutch operators secure supply continuity against REACH reformulation mandates. |
| Direct-to-Consumer Subscription Launch | Secondary metro home chefs access harvest-to-door traceability with varietal choice. |
| Modular Aeroponic Tower Deployment | Urban distributors retrofit warehouses to capture living-tray premiums in Chicago and New York. |
| USDA Organic Certification Investment | Three-year transition periods lock in premium channel access before competitor conversions complete. |
| Carbon Labeling Program Adoption | Water-efficient soilless cultivation qualifies for EU Green Deal preferential retail placement. |
Research Approach
Coverage spans the United States, the Netherlands, Germany, the United Kingdom, and Canada, with primary inputs from each market cluster. The research combines structured interviews with greenhouse operations managers, fine-dining procurement chefs, retail category buyers, and foodservice distribution executives with secondary validation. Sources include FDA enforcement documentation, EU regulatory filings, greenhouse operator financial disclosures, and customs trade data. Bottom-up facility capacity assessments and top-down channel revenue estimates undergo triangulation for convergence.
Granularity-level modeling disaggregates volume and value across product type, end user, distribution channel, packaging format, and regional production cluster dimensions throughout the forecast period. CAGRs derive from trend extrapolation of harvest cycle speeds, facility expansion pipelines, and channel shift velocities. Industry-specific inputs include LED lighting cost curves, electricity rate trajectories in metropolitan load zones, and regulatory compliance timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather disruption in concentrated supply corridors or abrupt regulatory timeline acceleration. Projections reflect documented assumptions regarding technology adoption rates, certification penetration curves, and buyer preference evolution. Material deviation in carbon-labeling policy implementation or input cost volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dehydrated Vegetables Market
Vegetables
Dried Mushroom Market
Vegetables
Garden Cress Market
Vegetables
Fresh Vegetables Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Dried Vegetable Market
Vegetables
Europe Pea Market
Vegetables
Asia-Pacific Peas Market
Vegetables
Qatar Greenhouse Market
Vegetables
Garlic Market
Vegetables
Vegetable Grader Market
Vegetables
North America Peas Market
Vegetables
Global Mushroom Market
Vegetables
Spain Avocado Market
Vegetables
Canada Microgreens Market
Vegetables
South America Peas Market