
 Sweet Potatoes Market | 2026-2036
Sweet Potatoes Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Potatoes Market Outlook
The supermarket wholesale channel is fragmenting as regional grocers build direct farm relationships. Black Gold Farms leverages its Midwest processing footprint to secure year-round supply contracts. Scott Farms anchors its position through varietal specialization in Covington and Beauregard cultivars. Ham Farms competes via integrated storage and curing infrastructure that reduces post-harvest loss.
Sweet potatoes are storage roots of Ipomoea batatas, typically containing 20-25% carbohydrates and notable beta-carotene content, harvested after 90-150 growing days and cured at 29-32°C to heal skin wounds and convert starches to sugars for enhanced flavor and shelf stability. Fresh product dominates volume throughput, though frozen formats capture expanding share in quick-service restaurant supply chains. Ingredient-grade processing for flour and starch extracts commands premium positioning due to functional properties in gluten-free formulations. Retail bag packaging remains the standard for consumer-facing sales, while food service channels favor bulk crates for operational efficiency.
The USDA Agricultural Marketing Service administers voluntary grade standards that processors reference for size, shape, and defect tolerances, while the FDA oversees fresh-cut and processed sweet potato products under FSMA preventive controls. The EPA regulates agricultural chemical residues through tolerance limits that export-oriented growers must satisfy for market access. Stakeholders should monitor evolving consumer preference for purple-fleshed antioxidant varieties and the infrastructure investments required to handle differentiated cultivars at scale.
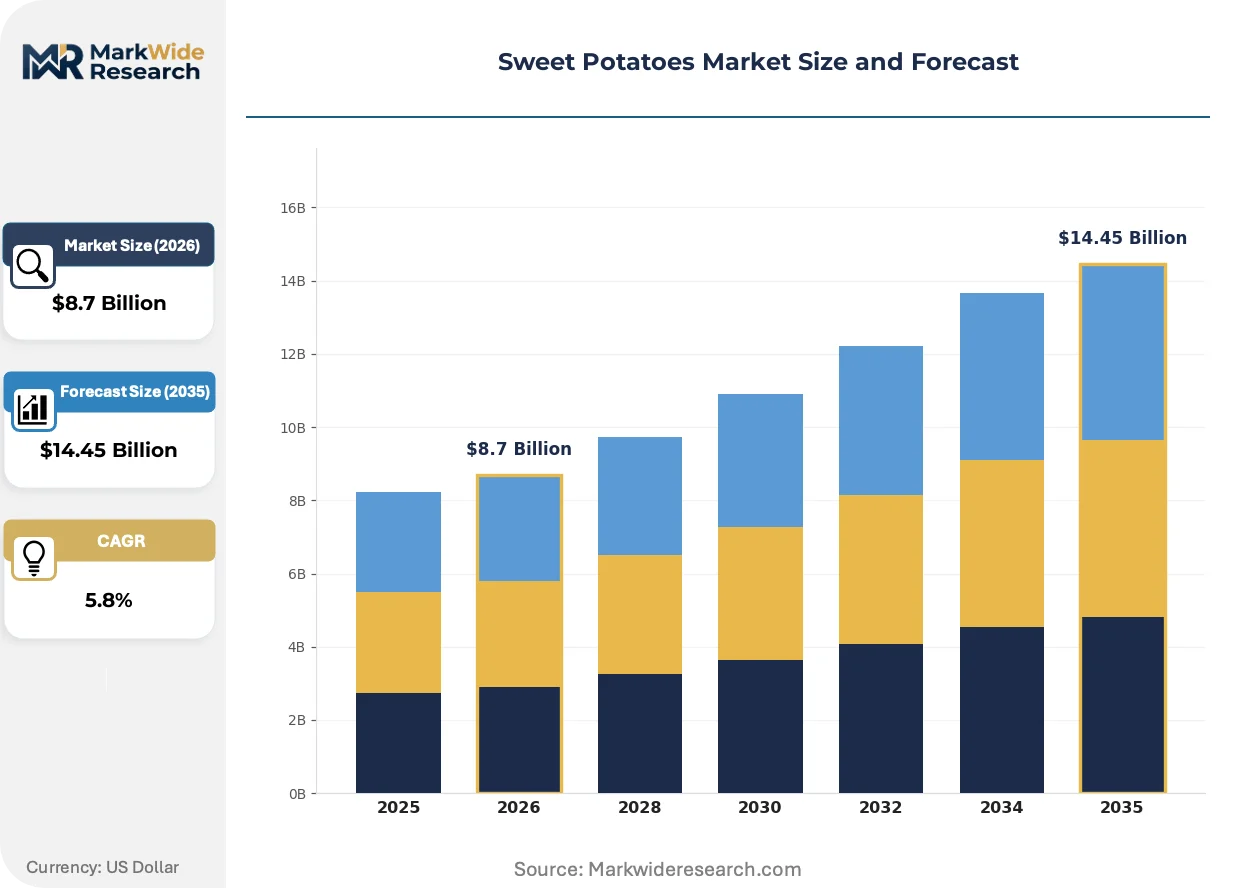
Market Dynamics
Food service procurement consolidation is compressing margins across the sweet potato value chain as national quick-service restaurant chains demand year-round supply guarantees that smaller growers cannot meet.
Growth Catalysts
- FSMA Preventive Controls:The FDA's hazard analysis requirements for fresh-cut processing are accelerating investment in controlled-atmosphere storage infrastructure that extends marketable shelf life.
- Gluten-free formulation demand:Ingredient manufacturers are expanding sweet potato flour capacity to serve bakery and snack applications seeking clean-label starch alternatives.
- North Carolina production belt concentration:Clustered curing and grading facilities in Johnston and Nash counties reduce per-unit logistics costs for export-oriented packers.
Market Restraints
- Input cost volatility:Propane-dependent curing operations face margin pressure from fuel price swings that growers cannot pass through on spot contracts.
- Single-origin supply risk:Hurricane exposure along the Atlantic seaboard creates harvest disruption vulnerability for processors lacking multi-state sourcing networks.
- Post-harvest perishability:Skinning damage during mechanical harvesting limits mechanical adoption rates and maintains labor dependency.
Strategic Opportunities
- Purple-fleshed cultivar expansion:Antioxidant-rich varieties command retail price premiums in Japanese and South Korean import markets.
- Direct-to-retailer channel development:Regional grocery chains are bypassing terminal markets to secure traceable supply with specified curing protocols.
- USDA BioPreferred program:Biobased certification for sweet potato starch derivatives opens federal procurement pathways for sustainable packaging applications.
Industry Challenges
- Certified food safety auditor scarcity:Third-party audit backlogs delay processor qualification for national chain supplier lists.
- Legacy curing barn retrofit costs:Converting ambient storage to precision climate control requires capital outlays that family operations struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Potatoes Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Canned, Frozen, Dried End Use: Food Service, Retail, Snacks, Ingredients Distribution Channel: Supermarkets, Online, Wholesalers, Farmers' Markets Packaging Type: Bags, Crates, Boxes, Cartons |
| Companies Covered | Black Gold Farms, Scott Farms, Ham Farms, Topashaw Farms, Vick Family Farms, A.V. Thomas Produce, Nash Produce, Edmondson Farms, Jackson Farming Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Potatoes Market Strategic Shifts
Digital traceability platforms and precision agriculture tools are rewiring how sweet potato quality is verified and valued from field to fryer.
Hyperspectral imaging for internal defect detection is virtualizing traditional hand-grading operations. Large fresh-cut processors are deploying inline optical sorting at receiving stations to cull internal black rot before value-add processing begins. This compression of quality assurance labor is enabling 24-hour receiving windows that were previously impractical.
The FDA's updated Agricultural Water Rule under FSMA is tightening microbial testing protocols for surface water used in field washing. Growers in the North Carolina production belt are responding by consolidating into shared well infrastructure to reduce surface water dependency. Small-scale operators without capital access face exclusion from supply chains requiring documented water quality compliance.
Chain restaurant procurement teams are unbundling specification compliance from volume commitments. Quick-service buyers now contract separately for certified organic, conventional, and value-tier product streams rather than accepting blended loads. This segmentation is most pronounced in the southeastern United States where regional chains compete directly on ingredient provenance claims.
Sweet Potatoes Market Segmentation
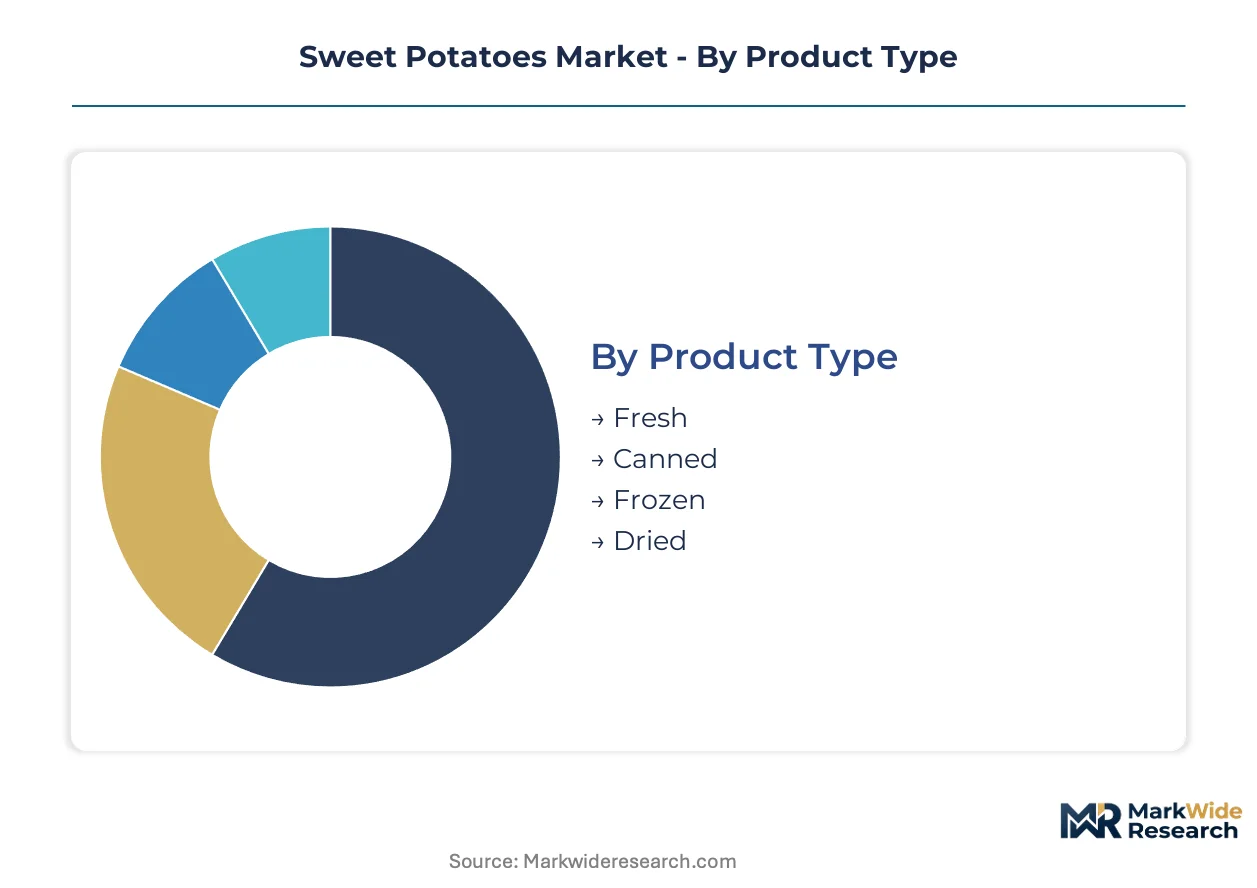
Sweet potato value chains segment across preservation state, buyer channel, and handling format. Each dimension carries distinct margin profiles and working capital requirements that shape processor investment priorities.
Product Type:
Fresh product turns inventory fastest with minimal processing overhead, while dried formats tie up capital longest through dehydration cycles and moisture-controlled storage.
- Fresh:Harvested roots undergo 5-7 day curing at controlled temperature to convert starches to sugars and heal surface wounds. North Carolina's Johnston County packers dominate this segment, supplying year-round contracts to quick-service restaurant chains that demand consistent sugar content and skin integrity.
- Frozen:Blanched and individually quick-frozen fries and cubes serve food service operators seeking labor reduction and portion consistency. This segment climbs fastest as regional chains expand sweet potato side-item placement and operators prioritize fryer-ready formats over raw prep.
- Canned:Syrup-packed and vacuum-sealed products target institutional buyers and holiday retail cycles with extended shelf stability.
- Dried:Dehydrated slices and flour command ingredient-grade premiums in gluten-free bakery applications, though volume throughput remains constrained by lengthy processing cycles.
Fresh anchors the volume base while frozen gains share at the steepest rate.
End Use:
Margin structures diverge sharply between specification-driven contract buyers and spot-market purchasers, with food service operators extracting the strictest quality compliance terms.
- Food Service:National quick-service chains and contract feeders specify cured sugar content, length grading, and defect tolerances that reject substantial receiving volumes. These buyers consolidate procurement through approved supplier lists that exclude uncertified packers.
- Retail:Grocery chains and club stores source bagged and bulk formats with variable grade acceptance depending on promotional calendar positioning. Regional grocers in the southeastern United States increasingly bypass terminal markets for direct farm relationships with specified curing protocols.
- Snacks:Chip and puff manufacturers process dehydrated sweet potato into value-added products with clean-label positioning.
- Ingredients:Starch and flour extractors serve gluten-free formulation demand from bakery and snack manufacturers seeking functional alternatives to wheat and corn derivatives.
Food service commands the tightest specifications while retail channels expand most quickly through direct sourcing relationships.
Distribution Channel:
Channel selection determines traceability requirements and payment terms, with terminal market intermediaries yielding ground to direct contracts.
- Supermarkets:Corporate produce buyers negotiate seasonal volume commitments with packers who maintain USDA grade certification and cold chain documentation. Category managers in southeastern chains now unbundle organic, conventional, and value-tier streams rather than accepting blended loads.
- Wholesalers:Terminal markets and produce distributors aggregate mixed-grade shipments for redistribution to independent retailers and food service accounts lacking direct farm access.
- Online:Direct-to-consumer platforms and meal kit services source specialty varieties with expedited fulfillment requirements.
- Farmers' Markets:Local producer sales capture retail price premiums for heritage and purple-fleshed cultivars with limited scale.
Supermarkets anchor procurement volume while online channels expand most quickly through specialty variety access.
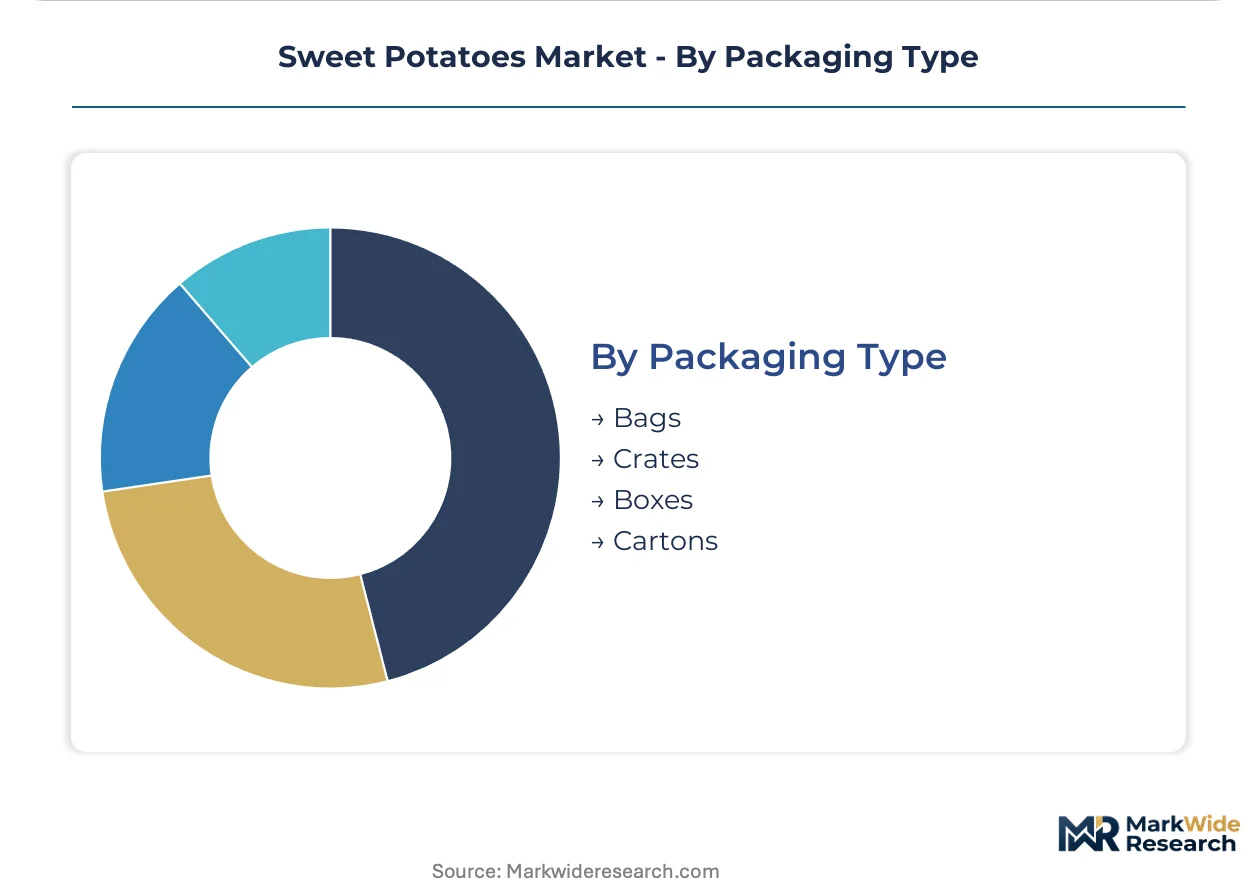
Packaging Type:
Handling format selection reflects downstream automation requirements and shelf-life extension needs.
- Bags:Consumer-facing poly and mesh bags dominate retail throughput with printed grade labeling and net weight standardization.
- Crates:Reusable plastic containers serve food service and processing facility receiving with forklift-compatible stacking and ventilation.
- Boxes:Corrugated master packs consolidate retail bags for distribution center handling.
- Cartons:Display-ready packaging serves club store and mass merchant shelf presentation requirements.
Crates anchor food service logistics while bags retain retail dominance through consumer familiarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Wilmington's refrigerated container terminal underwrites North Carolina's export dominance, while Mississippi River barge networks anchor Midwest distribution reach into Mexican processing facilities.
United States
Quick-service restaurant chains drive procurement consolidation across the Southeast, demanding year-round cured supply with documented sugar content. The USDA Agricultural Marketing Service administers voluntary grade standards that processors reference for size and defect tolerances. Johnston County packers cluster around Benson and Smithfield, operating integrated curing barns that supply national fry contracts.
China
Starch extraction facilities in Shandong Province process surplus roots into modified sweet potato starch for noodle and vermicelli production. The country's national food safety regulator enforces residue limits that export-oriented growers must satisfy for Japanese market access. Processing gravity centers on the Jiaodong Peninsula, where coastal humidity supports low-temperature dehydration cycles.
Japan
Confectionery manufacturers source satsumaimo varieties for traditional wagashi applications and modern snack formulations. METI's regional revitalization programs subsidize curing facility upgrades in Kagoshima Prefecture. The Kyushu production belt around Kanoya maintains heritage cultivation practices that command retail price premiums in Tokyo metropolitan markets.
South Korea
Health-conscious consumers drive demand for purple-fleshed antioxidant varieties in fresh-cut and dried formats. The Ministry of Food and Drug Safety oversees fresh-cut processing under hazard analysis requirements. Jeju Island growers exploit volcanic soil conditions to differentiate supply for premium retail channels in Seoul.
Indonesia
Street food vendors and informal processors constitute fragmented demand for orange-fleshed varieties in urban centers. The national agricultural ministry promotes sweet potato as a food security crop through subsidized seed distribution programs. Java's Central Highlands around Dieng Plateau supply Bogor and Bandung markets through established truck farming networks.
Sweet Potatoes Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, supplying raw cured roots to branded processors. The structure fragments across family-owned growing operations and consolidated packing entities with national distribution reach. Three archetypes dominate: varietal specialists cultivating proprietary cultivars, integrated operators controlling curing through retail, and regional packers aggregating spot-market supply. Competitive moves concentrate on backward integration into seed multiplication and geographic expansion through multi-state sourcing networks.
Among family-held growing operations, Black Gold Farms, Scott Farms, and Ham Farms exemplify the integrated archetype. Black Gold Farms leverages its Midwest processing footprint to secure year-round supply contracts. Scott Farms anchors its market position through varietal specialization in named cultivars. Ham Farms competes via controlled-atmosphere storage infrastructure that reduces post-harvest loss and extends shipping windows.
| Leading Market Players |
|---|
| Black Gold Farms |
| Scott Farms |
| Ham Farms |
| Topashaw Farms |
| Vick Family Farms |
| A.V. Thomas Produce |
| Nash Produce |
| Edmondson Farms |
| Jackson Farming Company |
| Others |
Value Chain & Pricing Dynamics
Propane price volatility in North Carolina's curing belt determines both the spread between spot and contract pricing tiers and the geographic shape of multi-state sourcing networks. Fuel cost swings that packers cannot pass through to quick-service buyers force margin absorption or infrastructure relocation, reshaping where integrated operators concentrate curing capacity versus where spot-market aggregators remain viable.
Pricing Analysis
Volume-discount tiering structures separate national quick-service contracts from regional grocery direct agreements and terminal-market spot sales. Three-tier pricing stratification across premium certified-organic, standard USDA-grade, and economy ungraded channels reflects curing-protocol compliance and documented sugar-content guarantees. Cost compression in the economy tier is intensifying because family operations lack capital to retrofit ambient barns to precision climate control. Quick-service chains show the least price sensitivity due to specification-locked supplier lists, while independent retailers and institutional buyers exhibit the highest elasticity.
Supply Chain Analysis
Export-control regimes on agricultural biotechnology germplasm limit proprietary cultivar flows between the United States and Asian breeding programs. Supply concentrates in North Carolina, Mississippi, and California, with raw material dependencies on propane for curing, certified seed stock for varietal purity, and sulfur-based fungicides for storage rot prevention. Single-source vulnerability runs through the Atlantic hurricane corridor, where concentrated Johnston County infrastructure faces seasonal disruption risk. Distribution runs through refrigerated container terminals at Wilmington for Asian export, barge networks via the Mississippi for Mexican processing, and direct truck contracts to southeastern quick-service distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: FSMA preventive control certification and USDA grade compliance create switching costs that lock national quick-service chains into approved supplier relationships.
For Market Incumbents: Entrench position by backward integration into proprietary seed multiplication for purple-fleshed antioxidant varieties, securing cultivar exclusivity against emerging varietal specialists. Expand controlled-atmosphere curing capacity in Louisiana and Mississippi to diversify hurricane exposure that threatens North Carolina concentration. Lock in multi-year propane supply agreements to neutralize fuel price volatility that compresses spot-contract margins. For New Entrants and Emerging Players: Establish a beachhead in direct-to-retailer channel development with southeastern regional grocers seeking traceable supply with specified curing protocols. Target the purple-fleshed cultivar segment for Japanese and South Korean import markets where antioxidant premiums remain underexploited by incumbent packers. Lead with digital traceability platform integration as a go-to-market differentiator for buyers unbundling organic, conventional, and value-tier streams. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated operators with multi-state sourcing networks and certified infrastructure over fragmented family holdings. Long-term viability hinges on climate-resilient geographic diversification and cultivar IP control rather than spot-market aggregation scale. Watch for inflection via FDA Agricultural Water Rule enforcement that excludes small-scale operators lacking documented well-water compliance, accelerating acquisition opportunities among capital-constrained curing barns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Multiplication | Proprietary cultivar control locks in premium positioning for antioxidant varieties in Asian export markets. |
| Multi-State Curing Infrastructure Expansion | Louisiana and Mississippi facilities reduce Atlantic hurricane concentration risk for national supply guarantees. |
| FSMA Preventive Control Certification Investment | Compliance documentation secures placement on quick-service approved supplier lists that exclude uncertified packers. |
| Digital Traceability Platform Deployment | Inline optical sorting and blockchain documentation meet unbundled procurement requirements for separated organic and conventional streams. |
| Direct-to-Retailer Channel Development | Bypassing terminal markets captures margin from southeastern grocery chains seeking specified curing protocol traceability. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service procurement directors, regional grocery category managers, curing facility operators, and USDA Agricultural Marketing Service grading supervisors. Secondary validation drew from FDA FSMA guidance documents, EPA agricultural chemical tolerance databases, USDA National Agricultural Statistics Service crop reports, and customs export records for sweet potato shipments through Wilmington and Norfolk ports. Bottom-up volume modeling triangulated against top-down value estimates across preservation state, buyer channel, and handling format dimensions.
Calibration approaches cross-referenced historical curing capacity utilization against quick-service contract expansion timelines and frozen format penetration rates in food service channels. Segmentation dimensions modeled include preservation state, end-use application, distribution channel, and packaging format, with regional production belt clustering as an industry-specific overlay. CAGRs were derived from trend extrapolation of food service procurement consolidation patterns and ingredient-grade processing capacity announcements, incorporating input cost sensitivity for propane-dependent curing operations and varietal switching costs for proprietary cultivar adoption.
Sensitivities concentrate around hurricane frequency affecting North Carolina harvest volumes, propane price trajectory reshaping curing economics, and FDA enforcement intensity for agricultural water quality compliance. Forecasts reflect documented assumptions regarding quick-service chain expansion rates and Asian import demand for purple-fleshed varieties. Material shifts in Atlantic seaboard climate patterns or rapid cultivar IP litigation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dried Vegetable Market
Vegetables
Yarrow Market
Vegetables
Fresh Vegetables Market
Vegetables
Asparagus Market
Vegetables
South America Peas Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Europe Christmas Tree Market
Vegetables
IQF Vegetables Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Potato Market
Vegetables
Garden Cress Market
Vegetables
Yam Products Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
North America Peas Market
Vegetables
Sprouts Market