
 Potato Market | 2026-2036
Potato Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Market Outlook
Food service buyers is collapsing away from whole fresh formats toward pre-cut frozen and dehydrated potato products that reduce kitchen labor and waste. McCain Foods Ltd leverages its North American processing footprint to anchor contract supply with major quick-service chains. Lamb Weston Holdings Inc competes through specialized fry production lines calibrated to distinct oil-temperature profiles across regional restaurant markets. J.R. Simplot Co. dominates integrated seed-to-table operations in the Pacific Northwest, controlling irrigation rights and storage infrastructure that buffer seasonal volatility.
The potato is a starchy tuber of Solanum tuberosum, typically harvested at 15-20% solids content and cured at 7-10°C to convert sucrose and extend storage life for industrial processing or direct consumption. Fresh potatoes retain the largest volume share but carry thin margins tied to commodity cycles and perishability risk. Frozen potatoes represents the fastest-growing value pool, as food service operators trade prep labor for finished fry and specialty cut formats. Dehydrated potatoes concentrates margin in institutional channels where shelf stability and reconstitution speed outweigh premium pricing sensitivity.
USDA grading standards and FDA food safety rules govern size classification and pathogen testing for interstate commerce, while EPA water quality permits constrain processing plant discharge in the Snake River Plain. The EU F-Gas Regulation and EFSA acrylamide benchmarks are forcing European processors to retool frying lines and reformulate products for reduced contaminant levels. Stakeholders must monitor how climate-driven irrigation restrictions in key growing basins reshape processing plant siting decisions and regional supply contracts.
Market Dynamics
Food service procurement is pivoting toward pre-processed formats as labor costs and kitchen throughput constraints reshape operator economics across commercial and institutional channels.
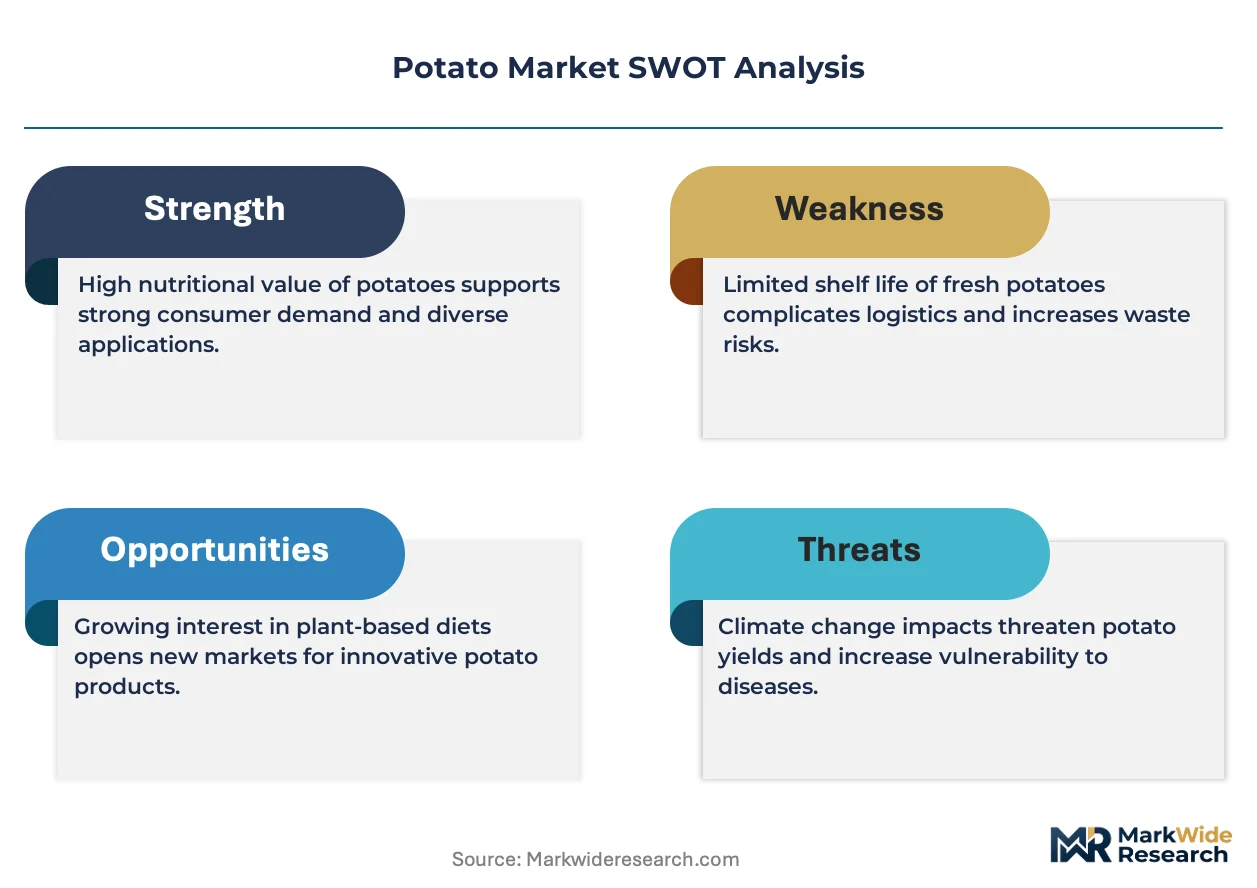
Growth Catalysts
- EU F-Gas Regulation:Cold chain emissions standards are forcing European processors to adopt lower-carbon freezing technologies, accelerating capital deployment into next-generation blast freezing and cryogenic systems.
- Quick-service restaurant chains:Menu engineering teams are specifying calibrated fry cuts and oil-temperature profiles that lock in contract volumes with specialized processing lines.
- Dehydration technology:Advances in drum-drying and air-lift systems are expanding shelf-stable format penetration into military, disaster relief, and remote institutional feeding channels.
Market Restraints
- Snake River Plain water rights:Irrigation permit constraints in Idaho are capping acreage expansion and forcing processors to absorb higher raw material transport costs from secondary growing basins.
- Acrylamide formation:Maillard reaction chemistry limits maximum frying temperatures, constraining throughput rates and requiring reformulation investments to meet EFSA contaminant benchmarks.
- Perishability of fresh formats:Thin margins on uncured tubers expose distributors to spoilage losses during temperature excursions in last-mile logistics.
Strategic Opportunities
- India institutional feeding:Mid-day meal programs and defense catering contracts present untapped demand for reconstituted mashed and granule formats that tolerate ambient storage.
- Carbon border adjustments:EU Green Deal compliance mechanisms reward processors with verified low-carbon freezing footprints, creating preference premiums in European food service procurement.
- Controlled-environment agriculture:Hybrid vertical farming of seed tubers near processing plants is shortening propagation cycles and reducing pathogen pressure in foundation stock.
Industry Challenges
- Refrigeration technician scarcity:Ammonia and CO2 cascade system expertise is concentrated among aging workforces, delaying plant maintenance windows and retrofit timelines.
- Legacy storage infrastructure:Subterranean bulk stores with natural ventilation lack precision climate control, causing sugar accumulation and fry-color defects that fail USDA grading standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Market |
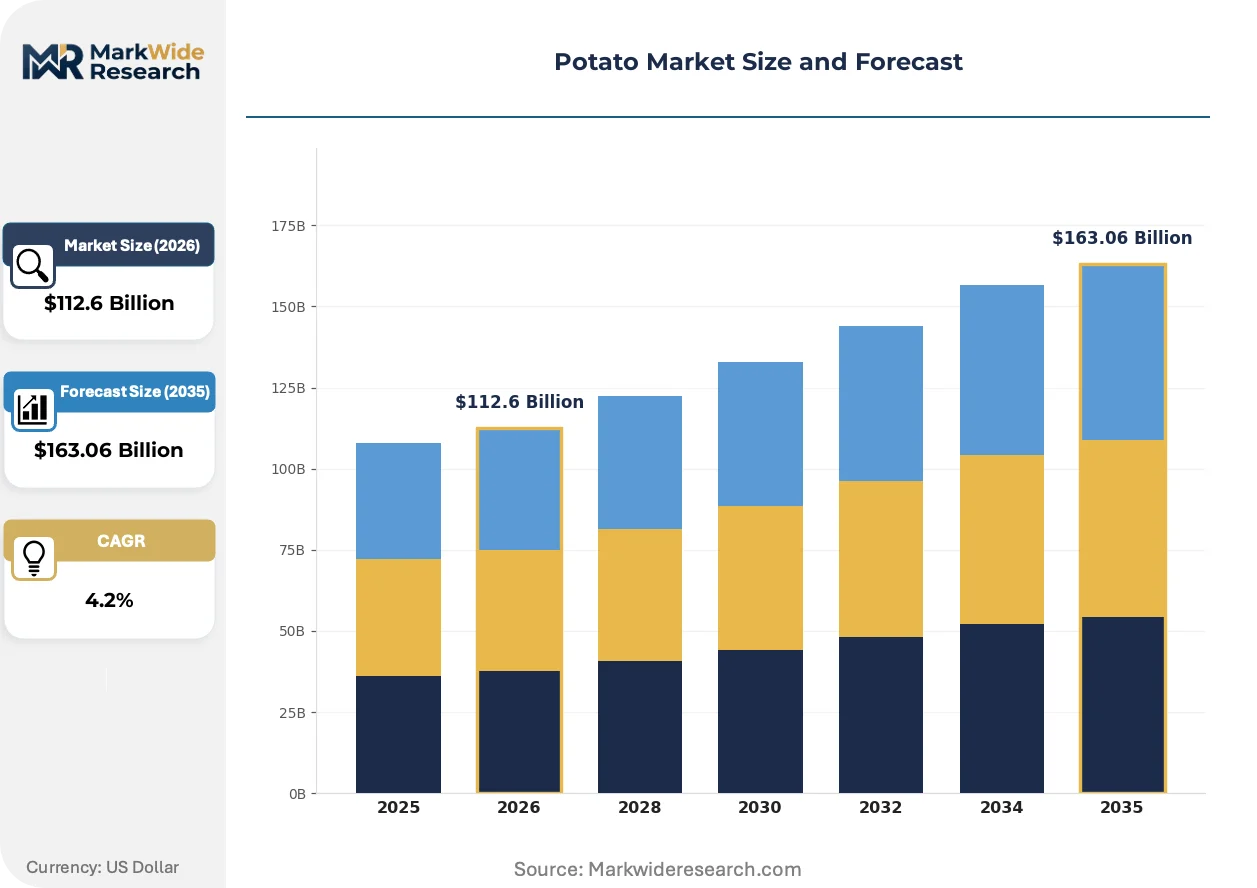
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $163.06 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Potatoes, Processed Potatoes, Dehydrated Potatoes, Frozen Potatoes End User: Food Service, Retail Consumers, Processing Industry, Exporters Form: Whole, Sliced, Mashed, Chips Packaging Type: Bags, Boxes, Bulk Containers, Retail Packs |
| Companies Covered | Cavendish Farms Corp, Idahoan Foods LLC, McCain Foods Ltd, PepsiCo Inc, Basic American Foods, Lamb Weston Holdings Inc, Aviko BV, The Kraft Heinz Co., J.R. Simplot Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Market Strategic Shifts
Processing technology is diverging along temperature and format axes as operators segment their asset bases between commodity-scale freezing and specialty dehydration. Equipment suppliers are responding with modular lines that retrofit between output modes.
Individually quick frozen (IQF) technology with fluidized bed architecture is fragmenting the traditional block-freeze paradigm. High-volume food service distributors are adopting IQF systems that preserve piece identity through mechanical separation. This capability is fragmenting procurement patterns, enabling operators to scale portions precisely without thawing entire cases.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in new cold storage installations. European processors are retrofitting ammonia-CO2 cascade systems or investing in air-cycle freezing to maintain operating permits. Frozen fry production lines in the Netherlands and Belgium face the steepest compliance costs due to concentrated capacity and dated equipment bases.
Contract specifications from multi-unit restaurant operators now mandate fry-performance consistency across oil degradation curves. Procurement teams are rejecting spot-market tubers in favor of varietal-forward supply agreements that specify solids content and reducing sugar ceilings. This specification tightening is most pronounced in the United States, where integrated processors with captive seed programs capture preferential allocation from quick-service chains.
Potato Market Segmentation
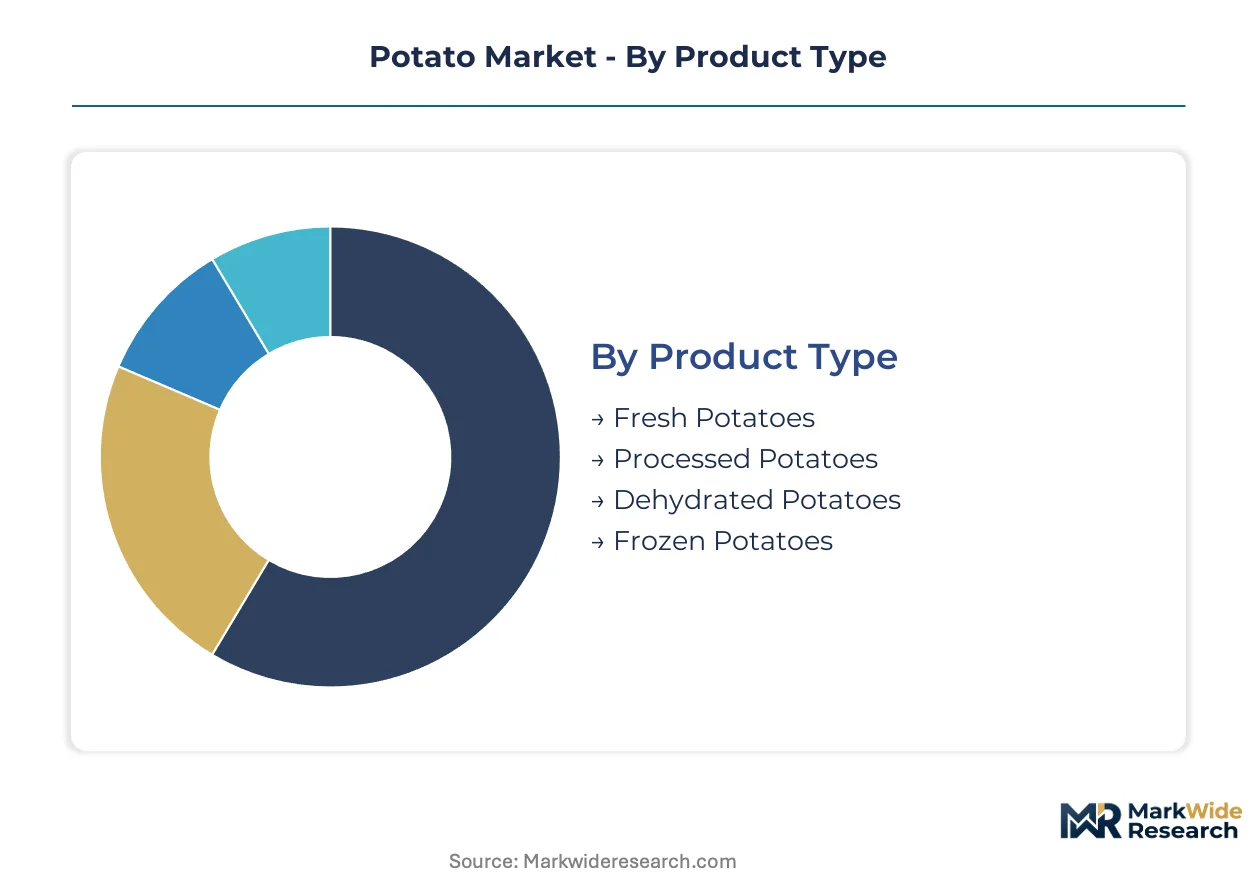
Segmentation in the potato market reveals where value migrates from commodity bulk toward precision-formatted products. Processors and distributors configure asset bases around specific product types, end-user channels, and packaging formats that command differentiated pricing.
Product Type:
Margin pools concentrate in value-added processing where labor substitution and shelf stability justify premium positioning over raw commodity formats.
- Fresh Potatoes:Harvested tubers at 15-20% solids content require curing at 7-10°C to manage sugar conversion. Thin margins and perishability risk dominate this segment, with USDA grading standards governing interstate commerce and constraining price recovery from spoilage losses.
- Frozen Potatoes:IQF fluidized bed systems preserve piece identity for precise portioning without case thawing. Quick-service chains in the United States are locking contract volumes through varietal-forward supply agreements specifying solids content and reducing sugar ceilings.
- Processed Potatoes:Pre-cut and partially prepared formats reduce kitchen labor for food service operators. EU F-Gas Regulation compliance is accelerating capital deployment into lower-carbon freezing technologies for this segment.
- Dehydrated Potatoes:Drum-dried and air-lift systems concentrate margin in institutional channels. Military and disaster relief procurement tolerates ambient storage requirements that fresh and frozen formats cannot match.
Fresh potatoes hold installed capacity across North American and European growing basins. Frozen potatoes is rotating up the share rankings as food service procurement pivots toward pre-processed formats.
End User:
Channel economics diverge sharply between price-sensitive retail bulk and specification-tight institutional contracts.
- Food Service:Commercial and institutional operators trade prep labor for finished formats calibrated to distinct oil-temperature profiles. Menu engineering teams specify fry cuts that lock processors into dedicated production lines.
- Processing Industry:Integrated networks in Idaho and Washington state demand varietal consistency for throughput optimization. Captive seed programs and irrigation rights buffer these operators against seasonal volatility.
- Retail Consumers:Supermarket and direct-to-consumer channels prioritize visual grading and bagged convenience. Perishability exposure in last-mile logistics compresses margins relative to food service contracts.
- Exporters:Ocean freight and phytosanitary certification requirements filter participation toward capitalized handlers. EFSA acrylamide benchmarks and destination-country MRL standards constrain product eligibility.
Food service channels anchor contract volume commitments. Processing industry offtake is climbing fastest as integrated seed-to-table operations expand.
Form:
Physical preparation state determines equipment compatibility and reconstitution speed for target use cases.
- Whole:Intact tubers suit fresh retail and seed propagation with minimal handling. Controlled-environment agriculture is shortening propagation cycles for foundation stock near processing plants.
- Sliced:Pre-cut formats align with food service frying and baking applications. Dehydration technology advances are expanding shelf-stable sliced penetration into remote institutional feeding.
- Mashed:Reconstituted formats dominate institutional channels where speed outweighs premium pricing. India's mid-day meal programs present untapped demand for granule formats.
- Chips:Thin-sliced and kettle-cooked variants target snack retail with flavor differentiation. Maillard reaction chemistry limits maximum frying temperatures, constraining throughput rates.
Whole form retains the largest volume footprint. Sliced preparation is gaining share fastest as quick-service specifications tighten.
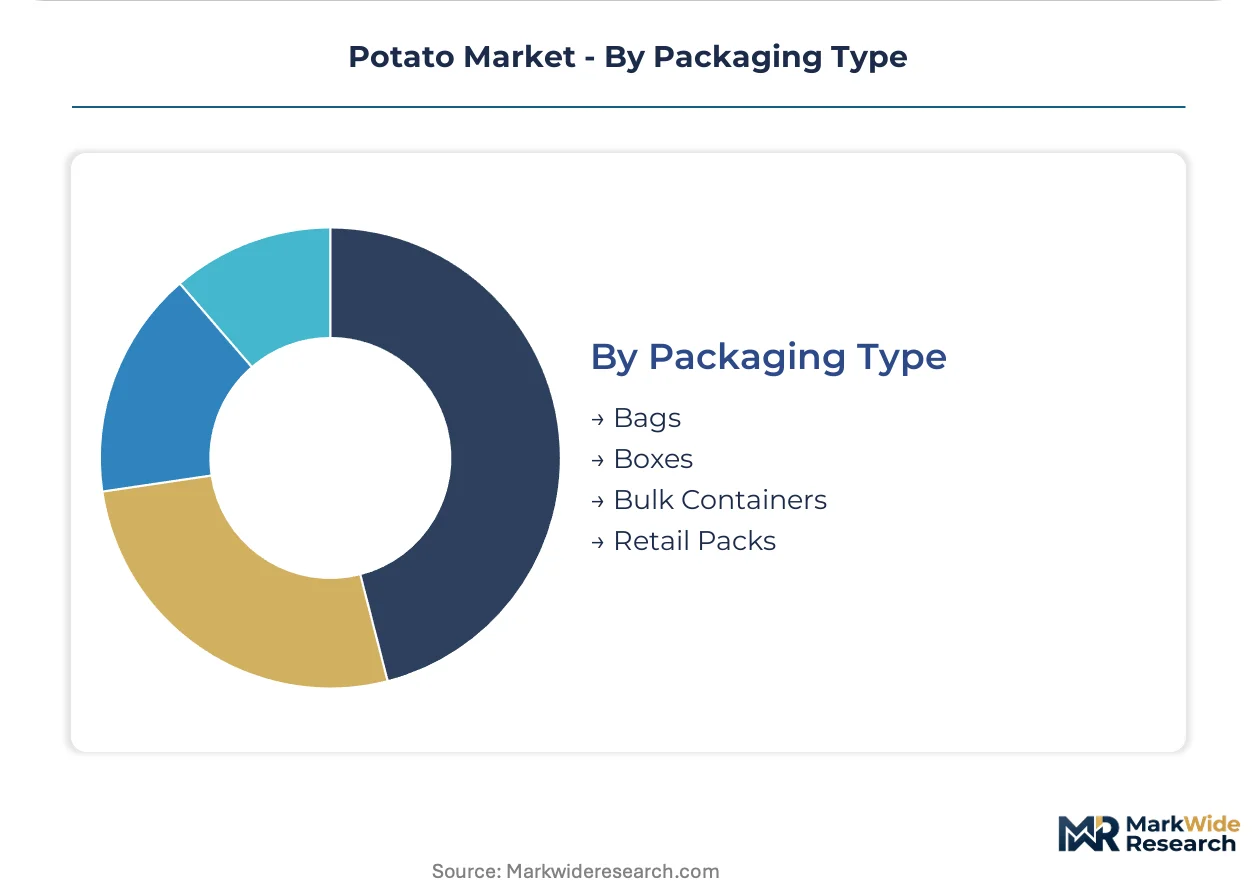
Packaging Type:
Unitization strategy reflects channel handling requirements and shelf-life extension needs.
- Bags:Woven polypropylene and paper sacks dominate fresh potato farm-to-wholesaler movement. Ventilation specifications balance moisture management against mechanical protection.
- Boxes:Corrugated containers with modified atmosphere lining extend retail shelf life for pre-cut formats. Stackability and printability support brand differentiation in supermarket produce sections.
- Bulk Containers:Returnable plastic bins and totes reduce packaging waste for processor-to-distributor flows. Cleaning and tracking infrastructure limits adoption to integrated supply chains.
- Retail Packs:Consumer-facing bags and trays with gas flushing target convenience-oriented household purchase. Unit economics favor high-throughput packing lines with automated weighing and sealing.
Bulk containers hold installed capacity in processor networks. Retail packs is rotating up the share rankings as supermarket format penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based processors ship frozen fry formats to quick-service chains across Germany and France, anchoring a trade corridor that handles substantial intra-European potato product volume annually.
United States
Idaho and Washington state production clusters supply integrated processing networks serving domestic quick-service chains. EPA water quality permits constrain discharge from Snake River Plain processing plants. Twin Falls, Idaho anchors McCain Foods Ltd and Lamb Weston Holdings Inc production capacity for national distribution.
Netherlands
Rotterdam-Antwerp port logistics enable frozen product export to German and French food service channels. EU F-Gas Regulation mandates ammonia-CO2 cascade retrofits in cold storage installations. Kempten and Lommel processing zones face steepest compliance costs due to concentrated legacy equipment bases.
Belgium
Specialized fry production lines serve quick-service specifications calibrated to distinct oil-temperature profiles. EFSA acrylamide benchmarks force reformulation investments and constrain maximum frying temperatures. Veurne and Poperinge growing districts supply varietal-forward contracts with reducing sugar ceilings.
Germany
Food service procurement from institutional caterers and commercial operators trades prep labor for pre-cut frozen formats. EU Green Deal compliance mechanisms reward verified low-carbon freezing footprints. Lower Saxony's seed propagation infrastructure supports varietal development for processing-grade tubers.
India
Mid-day meal programs and defense catering contracts generate institutional demand for reconstituted mashed and granule formats. FSSAI food safety standards govern interstate commerce and pathogen testing requirements. Gujarat and Maharashtra cold storage networks are expanding ambient-stable product handling capacity.
Potato Market Competitive Environment
Player mix skews toward integrated seed-to-table operators with captive irrigation rights and storage infrastructure. The vendor base concentrates around three archetypes: North American integrated processors controlling Pacific Northwest production basins, European specialists in calibrated fry formats for quick-service chains, and diversified food conglomerates with potato portfolios nested within broader snack and ingredient divisions. Competitive moves center on varietal-forward supply agreements that lock contract volumes and capacity expansion into lower-carbon freezing technologies for EU regulatory compliance.
Among North American integrated processors, McCain Foods Ltd, Lamb Weston Holdings Inc, and J.R. Simplot Co. occupy positions exemplifying the seed-to-table archetype with control over irrigation rights and storage infrastructure. McCain Foods Ltd represents the contract-volume anchor with major quick-service chains. Lamb Weston Holdings Inc exemplifies specialization in fry production lines calibrated to regional oil-temperature profiles. J.R. Simplot Co. sits within the Pacific Northwest concentration with integrated operations buffering seasonal volatility. European specialists include Aviko BV, while diversified conglomerates such as PepsiCo Inc and The Kraft Heinz Co. represent portfolio-based participation where potato products nest within broader snack and ingredient divisions.
| Leading Market Players |
|---|
| Cavendish Farms Corp |
| Idahoan Foods LLC |
| McCain Foods Ltd |
| PepsiCo Inc |
| Basic American Foods |
| Lamb Weston Holdings Inc |
| Aviko BV |
| The Kraft Heinz Co. |
| J.R. Simplot Co. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates both cold chain equipment qualification and carbon-footprint price premiums in European potato procurement. Buyers with verified low-carbon freezing credentials capture contract preference from quick-service chains, while non-compliant processors absorb cost penalties or forfeit market access.
Pricing Analysis
Legacy block-freezing equipment, current-generation IQF fluidized bed systems, and emerging cryogenic nitrogen tunnels stratify across premium, standard, and economy pricing tiers. Pricing pressure stems from acrylamide-limit reformulation investments and EFSA contaminant ceiling compliance. Food service chains with varietal-forward contracts show lowest price sensitivity, while spot-market fresh tuber traders face acute margin compression from spoilage losses.
Supply Chain Analysis
The United States anchors integrated seed-to-table processing through Idaho and Washington state production clusters. Raw material flows draw from Snake River Plain irrigation districts, Pacific Northwest seed propagation facilities, and secondary growing basins in North Dakota. Single-source vulnerability concentrates in Idaho water rights constraints. Distribution runs through processor-owned cold storage networks into quick-service chain distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quick-service chain consolidation into three national buyers with standardized fry specifications has inverted supplier power dynamics. Procurement teams now dictate varietal content and reducing sugar ceilings through captive contract structures.
For Market Incumbents: Compound defensive positioning through backward integration into controlled-environment seed propagation near processing plants. Lock irrigation rights in secondary growing basins before Snake River Plain permit caps harden. Prioritize ammonia-CO2 cascade retrofit completion ahead of EU F-Gas enforcement windows to preserve European market access.
For New Entrants and Emerging Players: FSSAI fast-track certification for dehydrated granule formats unlocks India's institutional feeding procurement. Target defense catering and mid-day meal channels where ambient storage tolerance outweighs brand premium requirements. Lead with drum-drying technology partnerships rather than capital-heavy freezing infrastructure.
For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment implementation reshapes the acquisition landscape toward processors with verified low-carbon footprints. Long-term viability centers on integrated operators with captive water rights and modular equipment capable of retrofit between freezing and dehydration modes. Monitor EFSA acrylamide benchmark tightening as the inflection signal for reformulation cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Propagation | Controlled-environment agriculture near Twin Falls shortens varietal development cycles for quick-service contract compliance. |
| Ammonia-CO2 Cascade Retrofit | EU F-Gas Regulation mandates lower-carbon freezing technology for continued Rotterdam-Antwerp corridor market access. |
| Dehydration Technology Partnership | Drum-drying capabilities penetrate India's defense catering procurement where ambient storage is mandatory. |
| Varietal-Forward Supply Agreement | Solids content and reducing sugar specifications lock contract volumes from consolidated quick-service chains. |
| Secondary Basin Irrigation Rights Acquisition | Snake River Plain water permit constraints force geographic diversification of raw material sourcing. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured interviews with food service procurement directors, potato processing plant managers, agricultural irrigation district administrators, cold chain equipment engineers, and quick-service chain menu engineering teams. Secondary validation drew from USDA grading standards documentation, EPA water quality permit filings, EU F-Gas Regulation implementation guidance, EFSA acrylamide benchmark studies, and FSSAI food safety compliance records. Bottom-up volume estimates triangulated against top-down value projections.
Across the projection horizon, the analytical framework modeled segmentation by product format, end-user channel, preparation state, and packaging type, with regional regulatory cluster as an additional dimension. CAGRs were derived from trend extrapolation of historical volume flows and value migration patterns. Industry-specific forecast inputs included irrigation permit issuance rates in the Snake River Plain and quick-service chain contract renewal cycles.
Decision-makers should treat outputs as directional under assumptions of continued EU regulatory enforcement and stable water rights adjudication in Idaho; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in F-Gas compliance deadlines and EPA discharge permit renewals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
IQF Vegetables Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Garden Cress Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Canada Microgreens Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Dried Vegetable Market
Vegetables
Europe Pea Market
Vegetables
Roselle Market
Vegetables
South America Peas Market
Vegetables
Sprouts Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
United States Microgreens Market