
 Canada Greenhouse Horticulture Market | 2026-2036
Canada Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Greenhouse Horticulture Market Insights
Capital-intensity divergence between automated climate-control specialists and basic-structure assemblers is rotating competitive advantage toward technology-integrated operators. Windset Farms leverages advanced environmental management systems to sustain premium vegetable output across multiple provinces. Harnois Industries anchors its position through engineered greenhouse structures designed for Canadian snow-load specifications. BW GLOBAL Structures Inc. differentiates via controlled-environment agriculture expertise tailored to northern latitudes.
Canada greenhouse horticulture encompasses soilless and soil-based cultivation within enclosed structures using climate regulation, supplemental lighting, and irrigation automation to produce vegetables, flowers, herbs, and fruits year-round despite subarctic exterior conditions. Structural glazing specifications typically require high light-transmission coefficients combined with thermal insulation values exceeding conventional agricultural buildings, enabling photosynthetically active radiation optimization while minimizing heating energy intensity. Vegetables dominate current output value, though vertical farming installations are capturing disproportionate capital allocation as urban proximity commands logistics savings. Hydroponics leads technology deployment by installed area, yet aeroponics segments attract margin concentration through pharmaceutical-grade herb production and seed propagation applications.
Health Canada PMRA governs pesticide maximum residue limits for edible greenhouse products, while provincial agricultural ministries enforce facility sanitation protocols under food safety modernization frameworks. Canadian Food Inspection Agency biosecurity standards shape import substitution incentives by restricting foreign plant material entry, directly stimulating domestic propagation infrastructure investment. Stakeholders must monitor evolving carbon pricing mechanisms and provincial renewable energy incentives, as electricity cost structures determine greenhouse operator viability against U.S. import competition.
Market Dynamics
Capital allocation in Canadian greenhouse horticulture is rotating toward climate-control automation as electricity pricing and carbon mechanisms intensify cost pressure on heating-intensive operations. This structural force compresses margins for basic-structure operators while rewarding technology-integrated producers with superior yield consistency and energy efficiency.
Growth Catalysts
- Carbon pricing mechanisms:Provincial carbon levy structures create competitive advantage for operators achieving heating efficiency through advanced glazing and thermal storage systems. British Columbia's carbon tax regime accelerates capital deployment toward low-emission greenhouse designs.
- Restaurant procurement reliability mandates:Foodservice buyers prioritize year-round supply contracts over seasonal spot markets, pulling investment toward climate-controlled production infrastructure capable of guaranteed delivery windows.
- CFIA biosecurity restrictions:Import substitution incentives from plant material entry controls stimulate domestic propagation infrastructure expansion, particularly for vegetable seedling and herb cutting production.
Market Restraints
- Natural gas price volatility:Heating cost exposure constrains operator viability in provinces lacking hydroelectric rate advantages, compressing operating margins during supply disruptions.
- Equipment supply concentration:Specialized glazing and climate-control hardware sourcing concentrates among European and Dutch suppliers, creating lead-time risk and currency exposure for Canadian capital projects.
- PMRA residue limit stringency:Health Canada's tightening maximum residue limits for edible crops restrict input chemistry options, elevating integrated pest management complexity and labor intensity.
Strategic Opportunities
- Alberta underpenetration:Southern Alberta's high solar irradiance and existing natural gas infrastructure remain underdeveloped relative to British Columbia and Ontario greenhouse density, offering greenfield expansion potential.
- Pharmaceutical-grade herb production:Aeroponic propagation systems for medicinal plant tissue culture command margin premiums through certification-driven supply contracts with nutraceutical processors.
- Provincial renewable energy incentives:Ontario's clean energy credit mechanisms and Quebec's hydro rate structures for agricultural users create locational arbitrage for electricity-intensive supplemental lighting operations.
Industry Challenges
- Horticultural automation engineering talent scarcity:Climate-control systems integration and sensor calibration expertise remains concentrated among a limited specialist workforce, constraining technology deployment velocity.
- Sanitation protocol compliance timelines:Provincial agricultural ministry facility certification under food safety modernization frameworks imposes extended pre-commercialization periods for new greenhouse constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Greenhouse Horticulture Market |
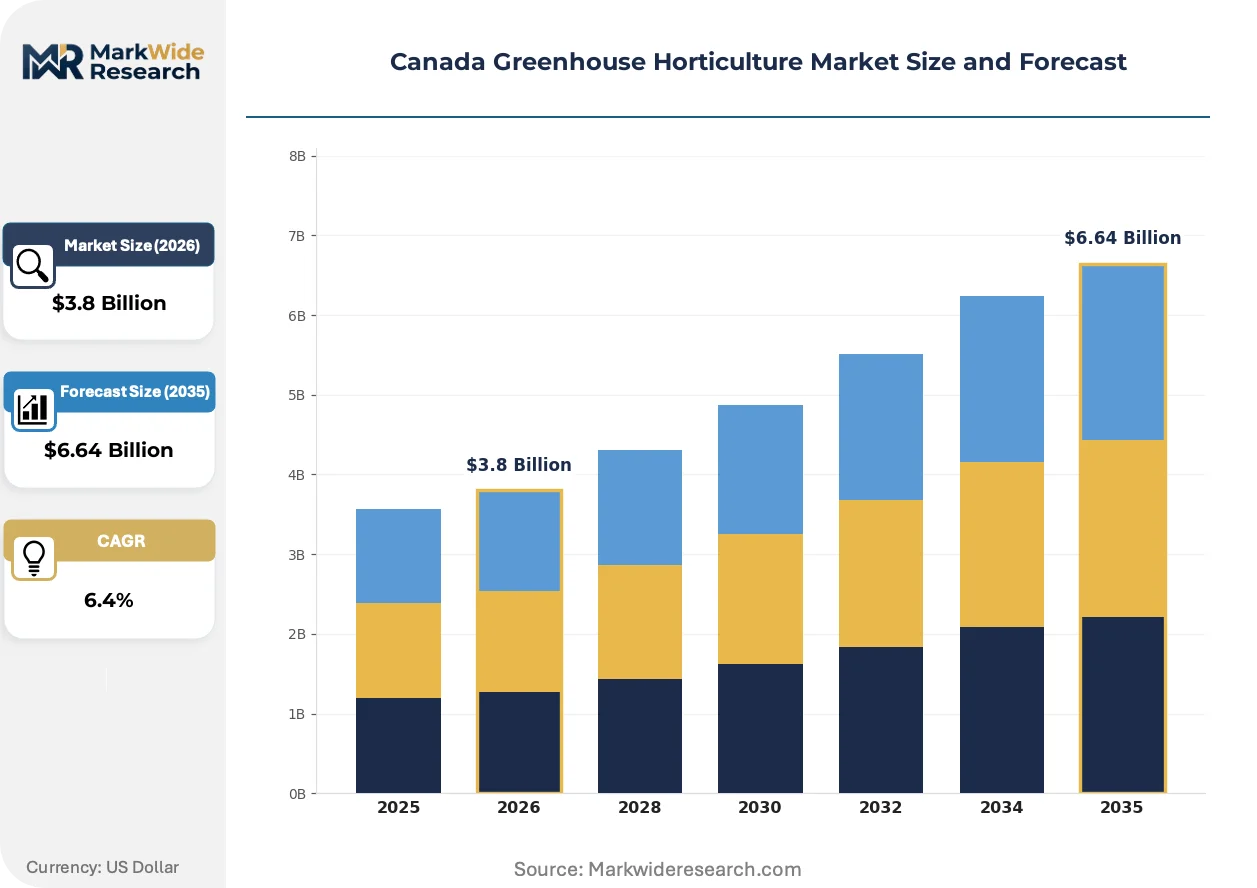
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Flowers, Herbs, Fruits Technology: Hydroponics, Aeroponics, Traditional Soil, Vertical Farming End User: Retailers, Wholesalers, Restaurants, Consumers Distribution Channel: Direct Sales, Online Marketplaces, Supermarkets, Farmers' Markets |
| Companies Covered | Planta Greenhouses Canada, Cedar-Built Greenhouses Ltd., BW GLOBAL Structures Inc., BC Greenhouse Builders Ltd., Harnois Industries Inc., Westbrook Group of Companies, Greenhouse Style Corporation, Lexis Greenhouses, Windset Farms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Greenhouse Horticulture Market Trends and Innovations
Technology convergence between environmental sensing and predictive analytics is restructuring competitive advantage around data-driven cultivation rather than experiential growing expertise alone. This shift elevates capital requirements while compressing returns for operators lacking digital infrastructure.
Supplemental LED lighting systems with spectral tuning capabilities are fragmenting the historical premium attached to high-transmission glazing investments. Large-scale vegetable producers in Ontario and Quebec are retrofitting existing structures with programmable light arrays to extend photosynthetic periods without proportional heating cost increases. The technology is fragmenting yield optimization strategies across geographic clusters with divergent solar profiles.
Health Canada PMRA is accelerating residue testing protocol harmonization with Codex Alimentarius international standards, elevating documentation burden for export-oriented producers. The regulatory convergence forces input chemistry requalification across product portfolios. Greenhouse operators supplying cross-border markets face compressed reformulation timelines to maintain US FDA-compliant supply chains.
Direct-to-restaurant distribution contracts are displacing traditional wholesale auction channels for premium vegetable categories. Chefs in Vancouver and Toronto metropolitan areas now specify cultivar varieties and harvest maturity windows through bilateral agreements with named greenhouse operations. This procurement evolution concentrates volume commitment among technology-capable producers with traceability systems.
Canada Greenhouse Horticulture Market Segmentation
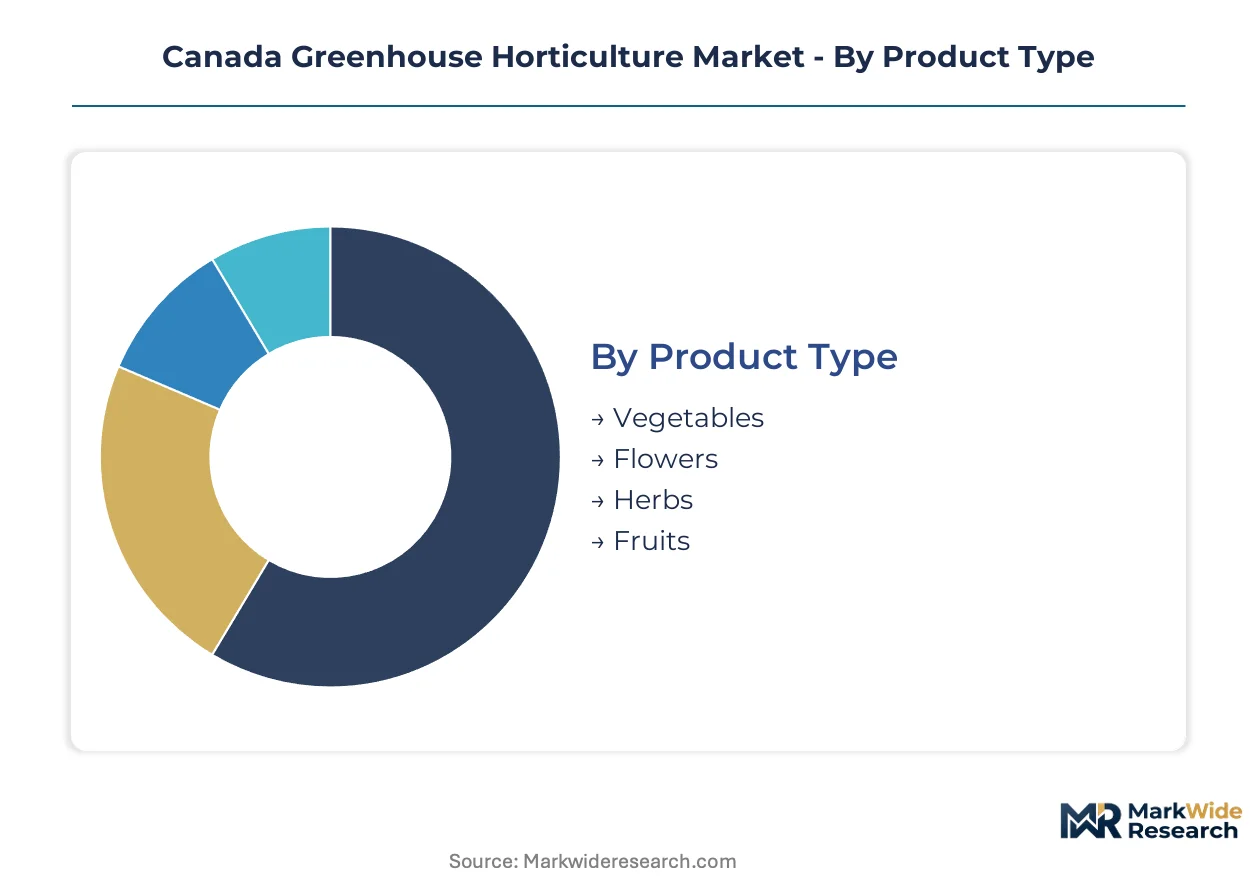
Segmentation in Canadian greenhouse horticulture reveals divergent margin profiles across cultivation technologies and buyer channels. Structural forces including carbon pricing, biosecurity regulation, and foodservice procurement reliability reshape which segments command capital allocation priority.
Product Type:
Margin pools concentrate in segments where year-round supply reliability commands premium pricing from institutional buyers.
- Vegetables:Tomatoes, peppers, and cucumbers dominate installed greenhouse area under climate-controlled production. Restaurant procurement contracts in Vancouver and Toronto metropolitan areas pull volume toward cultivar-specific, harvest-window-guaranteed supply agreements.
- Herbs:Basil, cilantro, and parsley cultivation concentrates in aeroponic propagation systems for pharmaceutical-grade certification. Nutraceutical processors in British Columbia's Fraser Valley cluster contract dedicated production lines, creating margin premiums through residue documentation protocols.
- Flowers:Ornamental production serves regional retail and event markets with lower capital intensity than edible crops.
- Fruits:Strawberries and selected berries occupy niche greenhouse installations, constrained by pollination labor requirements and perishability logistics.
Vegetables hold installed capacity. Herbs is rotating up the share rankings.
Technology:
Capital deployment velocity separates segments by engineering talent scarcity and equipment lead-time exposure.
- Hydroponics:Nutrient film technique and deep-water culture systems anchor current installed base across Ontario and Quebec vegetable operations. Dutch equipment suppliers concentrate sourcing risk, extending project timelines for new entrants.
- Aeroponics:Mist-based root delivery enables pharmaceutical-grade tissue culture with minimal water inputs. Health Canada PMRA residue documentation requirements elevate this segment's compliance burden into competitive moat territory.
- Traditional Soil:Container and raised-bed systems persist in flower and certain herb categories where substrate familiarity reduces technical risk.
- Vertical Farming:Stacked-layer installations with LED supplementation capture urban proximity logistics savings in Toronto and Montreal warehouse conversions.
Hydroponics retains operational scale. Vertical Farming is climbing the fastest as electricity rate arbitrage shapes locational decisions.
End User:
Procurement contract structures determine which segments absorb traceability and certification costs.
- Restaurants:Executive chefs in Vancouver and Toronto now specify cultivar varieties and harvest maturity windows through bilateral agreements. Direct contracts displace wholesale auction participation for premium vegetable categories.
- Retailers:Grocery chains demand consistent sizing, packaging, and organic certification documentation across provincial supply bases.
- Wholesalers:Traditional auction channels retain volume for commodity-grade produce lacking cultivar differentiation.
- Consumers:Farmers' market and community-supported agriculture participation concentrates in small-scale herb and flower operations.
Restaurants concentrate margin extraction capability. Retailers is gaining share fastest through private-label greenhouse programs.
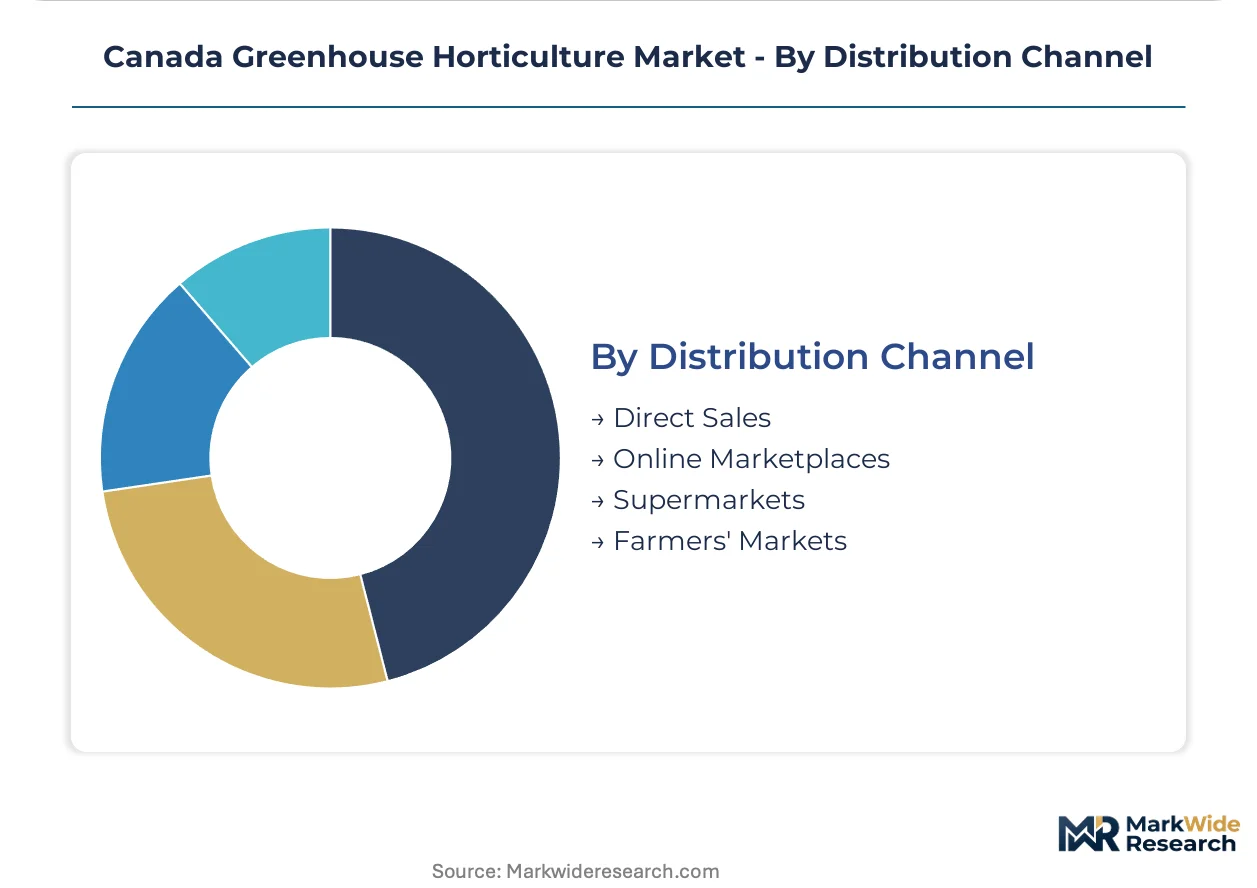
Distribution Channel:
Channel selection constrains operator investment recovery timelines through working capital intensity and shelf-life risk allocation.
- Direct Sales:Named greenhouse operations supply restaurants and retailers under bilateral contracts with specified delivery windows. Traceability systems and cultivar documentation requirements elevate operational overhead.
- Supermarkets:Chain produce departments demand year-round supply commitments with organic and pesticide-free certification tiers.
- Online Marketplaces:E-commerce platforms for local food systems aggregate small-scale herb and flower producers.
- Farmers' Markets:Seasonal direct-to-consumer channels serve peri-urban greenhouse operations with limited scale.
Direct Sales holds contractual volume. Online Marketplaces is rotating up the share rankings through platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Canadian provinces. British Columbia buyers absorb premium pricing for traceable local produce, while Prairie provinces remain price-sensitive to imported U.S. vegetables. Ontario and Quebec institutional procurement balances reliability requirements against budget constraints.
British Columbia
Metro Vancouver restaurants drive cultivar-specific contracting for greenhouse tomatoes and peppers. Health Canada PMRA residue documentation requirements elevate compliance costs for Fraser Valley operators. Delta and Surrey host dense clusters of technology-integrated vegetable producers supplying direct-to-chef distribution channels.
Ontario
Toronto metropolitan area grocery chains demand year-round organic certification tiers with specified harvest windows. Provincial renewable energy credit mechanisms reduce electricity cost exposure for LED supplemental lighting installations. Leamington and Kingsville anchor concentrated greenhouse vegetable production serving cross-border U.S. markets.
Quebec
Montreal foodservice buyers prioritize supply reliability over spot-market price minimization for herb categories. Hydro-Québec agricultural rate structures create electricity cost advantages for climate-control automation investments. Lanaudière and Montérégie regions concentrate hydroponic lettuce and specialty green production.
Alberta
Calgary and Edmonton retailers remain sensitive to price competition from U.S. imported produce during summer growing seasons. Provincial carbon levy structures accelerate capital deployment toward low-emission thermal storage designs. Southern Alberta's Medicine Hat region attracts greenfield greenhouse investment leveraging high solar irradiance and natural gas infrastructure.
Canada Greenhouse Horticulture Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Automated climate-control specialists command margin premiums through yield consistency and energy efficiency, while basic-structure assemblers compete on capital deployment speed and geographic proximity. Three archetypes dominate: integrated technology operators, engineered-structure fabricators, and regional installation specialists. Competitive moves concentrate on strategic partnerships with equipment suppliers and geographic expansion into underpenetrated provinces.
Among engineered-structure specialists, Harnois Industries and BW GLOBAL Structures occupy positions defined by Canadian snow-load engineering requirements and northern latitude climate-control expertise. Windset Farms represents the integrated technology operator archetype, spanning multiple provinces through advanced environmental management systems. These three companies exemplify how competitive advantage rotates toward technology-integrated production capabilities as carbon pricing and electricity cost structures intensify.
| Leading Market Players |
|---|
| Planta Greenhouses Canada |
| Cedar-Built Greenhouses Ltd. |
| BW GLOBAL Structures Inc. |
| BC Greenhouse Builders Ltd. |
| Harnois Industries Inc. |
| Westbrook Group of Companies |
| Greenhouse Style Corporation |
| Lexis Greenhouses |
| Windset Farms |
| Others |
Pricing and Supply Chain Analysis
LED supplemental lighting substitution for high-transmission glazing investments simultaneously redraws supply geography toward electricity-rate arbitrage zones and compresses pricing premiums previously attached to structural glazing specifications. Health Canada PMRA residue documentation requirements layer compliance cost differentiation across producer tiers, fragmenting price-setting power between technology-integrated operators and basic-structure assemblers.
Pricing Analysis
After-sales service contracts for climate-system maintenance and sensor calibration drive lifetime value capture for greenhouse automation vendors. Three-tier pricing structure across premium certified-organic, standard residue-documented, and economy wholesale-auction tiers dominates vegetable procurement. Price differentiation rests on Health Canada PMRA certification depth and cultivar traceability granularity. Cost compression in standard tiers is intensifying because Ontario grocery chains now mandate organic certification without proportional price premiums. Restaurant buyers exhibit lowest price sensitivity; Prairie retailers absorbing U.S. import competition show highest.
Supply Chain Analysis
Strategic stockpiling of specialized glazing and Dutch climate-control hardware dominates procurement strategy given extended equipment lead times. Supply concentrates in the Netherlands, China, and Germany for automation components, while domestic propagation infrastructure expands under CFIA biosecurity restrictions. Raw material dependencies span aluminum extrusions for snow-load structures, borosilicate glass for thermal glazing, and rare-earth phosphors for LED spectral tuning. Single-source vulnerability concentrates among European sensor suppliers. Distribution runs through direct-to-restaurant bilateral contracts displacing traditional wholesale auction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada greenhouse horticulture represents early-cycle expansion as carbon pricing mechanisms and restaurant procurement reliability mandates accelerate capital deployment toward climate-controlled production infrastructure.
For Market Incumbents: Shield margin position by deepening backward integration into domestic propagation infrastructure under CFIA biosecurity incentives and securing exclusive equipment supplier partnerships to constrain competitor access to Dutch climate-control hardware. Vertical integration into seedling production creates defensive moats against import substitution pressures.
For New Entrants and Emerging Players: Anchor in Southern Alberta's Medicine Hat corridor where high solar irradiance and existing natural gas infrastructure remain underdeveloped relative to British Columbia and Ontario density. Aeroponic pharmaceutical-grade herb production for Fraser Valley nutraceutical processors offers the most penetrable white-space target. Pursue direct-to-chef distribution contracts bypassing wholesale auction channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed integrated technology operators possessing multi-province environmental management system deployments but lacking scale to achieve electricity cost arbitrage. Five-to-ten year viability hinges on carbon pricing trajectory and provincial renewable incentive durability. Target acquisition profile encompasses operators with Health Canada PMRA residue documentation infrastructure and established restaurant procurement relationships. The signal to watch is Alberta carbon levy expansion accelerating greenfield investment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Control Automation Deployment | Health Canada PMRA compliance costs elevate technology-integrated operator margins above basic-structure competitors. |
| Domestic Propagation Infrastructure Expansion | CFIA biosecurity restrictions on foreign plant material entry stimulate captive seedling supply investments. |
| Direct-to-Restaurant Distribution Contracts | Vancouver and Toronto chefs now specify cultivar varieties through bilateral agreements with named greenhouse operations. |
| LED Supplemental Lighting Retrofit | Ontario renewable energy credit mechanisms reduce electricity cost exposure for photosynthetic period extension. |
| Alberta Greenfield Facility Development | Medicine Hat region leverages high solar irradiance and natural gas infrastructure for carbon levy-advantaged production. |
Research Methodology
Cross-validation between primary interviews with greenhouse operations managers, climate-system integration engineers, restaurant procurement directors, and provincial agricultural ministry officials anchors the qualitative findings against secondary validation from Health Canada PMRA residue limit documentation, CFIA biosecurity standards filings, provincial carbon pricing mechanism disclosures, and electricity rate tariff schedules. Bottom-up installation capacity estimates triangulate against top-down agricultural production value allocations.
Sensitivity analysis on natural gas price volatility and carbon levy escalation trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions span cultivation technology, product type, end-user procurement structure, and provincial regulatory cluster. CAGRs derive from installed capacity expansion rates, yield improvement curves, and price premium erosion assumptions. Industry-specific forecast inputs incorporate LED lighting adoption velocity and restaurant direct-contract penetration rates.
Material uncertainties — provincial election outcomes affecting carbon pricing continuity, Dutch equipment supplier consolidation, and Health Canada PMRA residue limit harmonization timing with Codex Alimentarius — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding electricity rate structures and biosecurity enforcement intensity. Revision becomes warranted when Alberta carbon levy expansion or federal carbon pricing mechanism modification crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Tomato Market
Vegetables
North America Christmas Tree Market
Vegetables
Artichokes Market
Vegetables
Fresh Mushroom Market
Vegetables
Yams Market
Vegetables
Dried Peas Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Dry Onion Market
Vegetables
North America Peas Market
Vegetables
Garden Cress Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Sweet Potatoes Market
Vegetables
UAE Tomato Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Global Mushroom Market
Vegetables
Australia Greenhouse Horticulture Market