
 Netherlands Greenhouse Horticulture Market | 2026-2036
Netherlands Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Greenhouse Horticulture Market Insights
Westland is reconfiguring its greenhouse density through precision climate infrastructure upgrades. Certhon leverages its high-tech greenhouse engineering to dominate export-oriented vegetable propagation systems. Van Der Hoeven anchors large-scale glasshouse projects across Dutch horticultural zones with integrated water management. Hoogendoorn competes through advanced process computer platforms that control irrigation and energy dosing.
Netherlands greenhouse horticulture denotes soilless crop cultivation under transparent or semi-transparent structures, typically employing glass or polymer coverings with computer-regulated temperature, humidity, and CO₂ enrichment between 800-1200 ppm to optimize photosynthetic rates. The sector primarily supplies fresh produce and ornamental products to retail and wholesale channels across Europe. Vegetables command the largest product type position due to sustained supermarket contract volumes, while greenhouse automation represents the fastest-expanding technology segment as labor costs escalate and energy efficiency mandates tighten. Hydroponics sustains mature margin pools among herb producers serving direct consumer channels.
The Dutch Ministry of Agriculture, Nature and Food Quality enforces strict nitrogen emission ceilings under EU Natura 2000 obligations, compelling growers to adopt closed-loop irrigation and geothermal heating retrofits. The EU Green Deal Farm to Fork strategy mandates pesticide reduction targets that accelerate biological crop protection adoption across Dutch glasshouse operations. Stakeholders must monitor geothermal energy concession allocations and carbon border adjustment mechanisms to secure long-term cost structures.
Market Dynamics
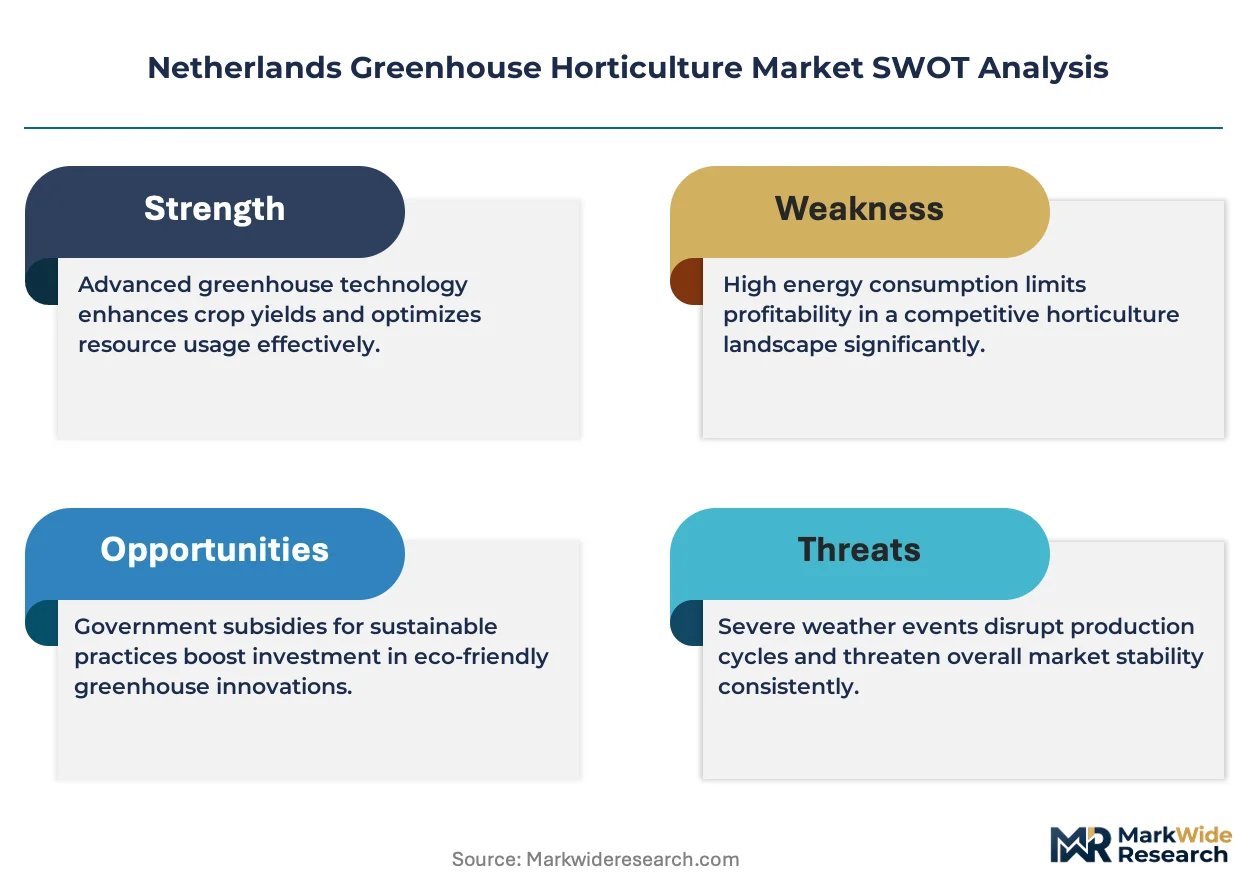
Geothermal concession allocations under the Dutch Ministry of Economic Affairs are compressing energy cost structures for Westland growers while EU Green Deal nitrogen ceilings force simultaneous irrigation and heating retrofits.
Growth Catalysts
- EU Green Deal Farm to Fork pesticide reduction targets:Dutch glasshouse operators accelerate biological crop protection adoption to meet mandatory reduction thresholds, expanding integrated pest management service demand.
- Westland municipality cluster concentration:Naaldwijk-to-Monster greenhouse density enables shared infrastructure for CO₂ enrichment distribution and waste heat recovery networks.
- Closed-loop irrigation systems:Recirculating hydroponic installations reduce water withdrawal volumes while maintaining yield consistency for supermarket contract fulfillment.
Market Restraints
- Natural gas price volatility:Dutch TTF benchmark fluctuations expose growers to heating cost spikes before geothermal connections reach operational scale.
- Glasshouse construction material concentration:Specialized coated glass and aluminum extrusion supply chains concentrate in German and Belgian manufacturing zones, creating import dependency.
- EU Natura 2000 nitrogen emission ceilings:Strict deposition limits constrain expansion permits for new acreage in Gelderland and Limburg growing zones.
Strategic Opportunities
- Carbon border adjustment mechanism alignment:Dutch growers with verified low-carbon production credentials capture premium positioning in German and French retail procurement.
- Vertical farming convergence with greenhouse automation:Layered cultivation robotics and climate computer integration enable year-round herb production for direct-to-consumer channels.
- Geothermal heating concession expansion:Ministry of Economic Affairs allocations in Limburg and Zeeland open new low-carbon production clusters beyond Westland saturation.
Industry Challenges
- Process computer integration complexity:Hoogendoorn and Priva platform migrations require specialized technician labor scarce in North Brabant and Overijssel rural zones.
- Biological crop protection certification timelines:Koppert Biological Systems product registrations face EFSA evaluation delays, disrupting pest management program planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Greenhouse Horticulture Market |
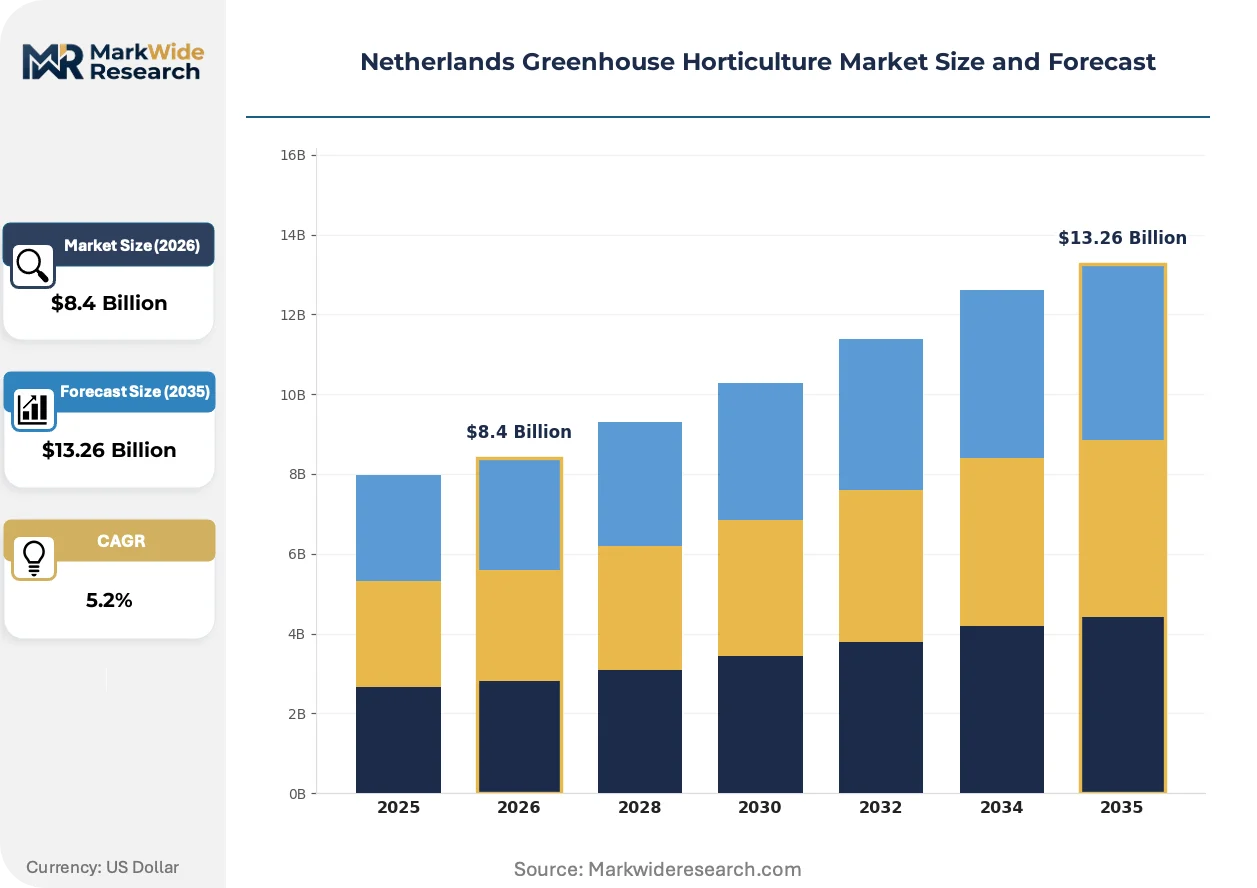
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Flowers, Herbs, Fruits Technology: Hydroponics, Aquaponics, Vertical Farming, Greenhouse Automation End User: Retailers, Wholesalers, Exporters, Direct Consumers Distribution Channel: Online, Supermarkets, Farmer Markets, Garden Centers |
| Companies Covered | Certhon, Van Der Hoeven, Hoogendoorn, KUBO Group, Ridder Group, Dalsem, HortiMaX, Bom Group, Priva, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Greenhouse Horticulture Market Trends and Innovations
Automation hardware and biological input systems are converging to reduce labor dependency while regulatory compliance software embeds directly into climate control infrastructure.
Supplemental LED lighting arrays is hybridizing with traditional high-pressure sodium installations in tomato and cucumber propagation facilities. Westland contract growers for Albert Heijn and Jumbo Supermarkten deploy hybrid systems to extend photosynthetic photon flux density during winter months without full HPS replacement capital burden. The technology is hybridizing energy sourcing strategies, allowing operators to arbitrage between grid electricity and on-site geothermal power.
EU Green Deal Farm to Fork pesticide reduction mandates tighten active substance approval criteria through EFSA hazard assessments. Dutch glasshouse vegetable producers face elimination of conventional chemical options for thrips and whitefly control, accelerating biocontrol agent procurement from Koppert and Biobest. Ornamental propagation segments in Aalsmeer auction zones experience the steepest compliance cost escalation due to zero-residue export requirements.
Supermarket chains now specify cultivation protocol transparency as a procurement prerequisite. Albert Heijn, Jumbo, and Lidl Nederland require blockchain-traceable input documentation and energy source verification for contracted tomato, pepper, and cucumber volumes. This specification pressure concentrates among Westland growers supplying Rotterdam distribution hubs, where real-time harvest data integration into retailer inventory systems determines contract renewal terms.
Netherlands Greenhouse Horticulture Market Segmentation
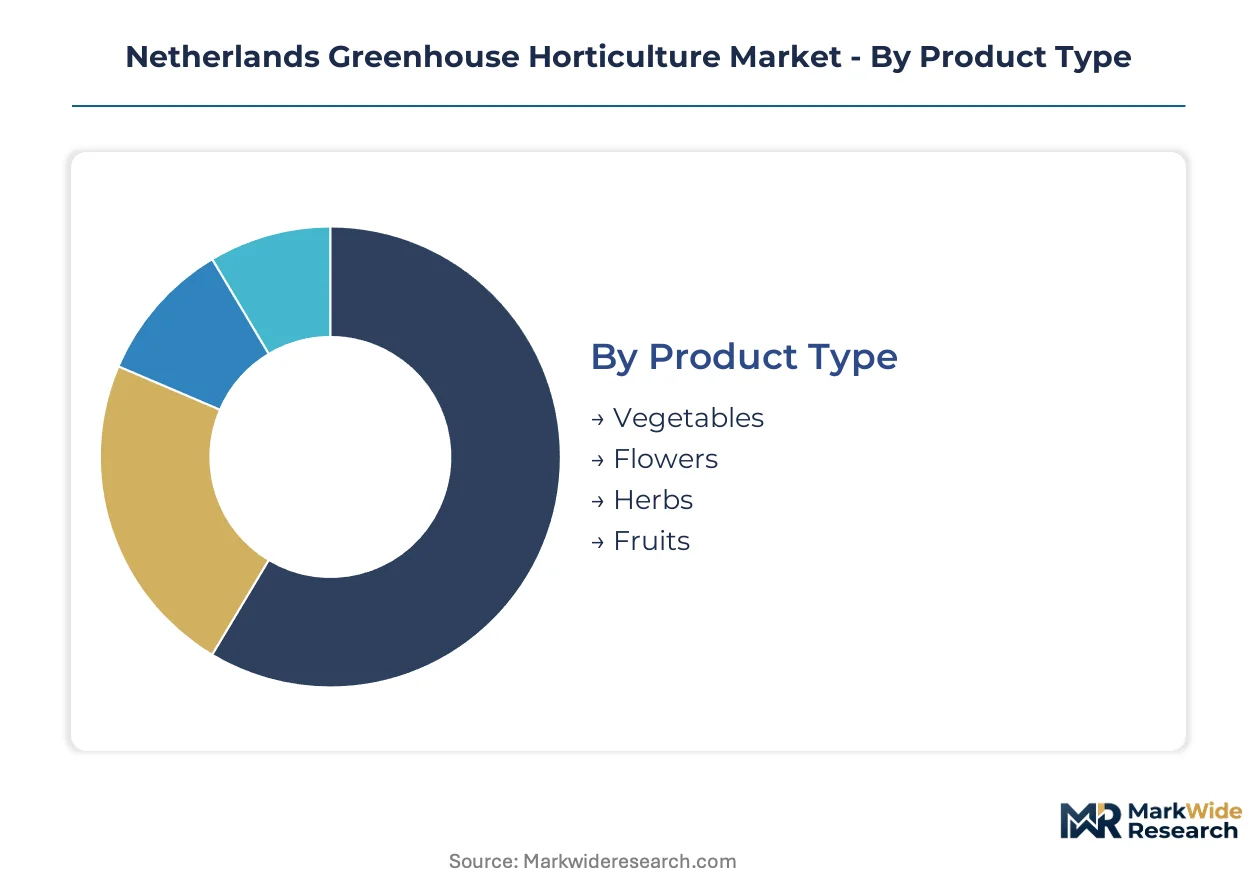
Segmentation in Dutch greenhouse horticulture reveals how production cycles, regulatory compliance burdens, and buyer procurement specifications vary dramatically across crop categories and technology platforms. Understanding these structural differences enables stakeholders to allocate capital efficiently across short-cycle herb operations versus long-cycle vegetable propagation systems.
Product Type:
Cycle times range from six-week herb rotations to nine-month tomato vine renewals, creating fundamentally different working capital and climate control requirements across Dutch glasshouse operations.
- Vegetables:Tomato, cucumber, and sweet pepper propagation dominates contracted acreage under Albert Heijn and Jumbo Supermarkten supply agreements. Westland growers prioritize CO₂ enrichment and supplemental LED arrays to meet year-round volume commitments to Rotterdam distribution hubs.
- Flowers:Ornamental propagation in Aalsmeer auction zones operates on longer production cycles with stringent zero-residue export protocols. EU Green Deal pesticide reduction mandates impose steeper compliance costs here than in vegetable segments due to phytosanitary requirements in German and French retail channels.
- Herbs:Basil, chives, and parsley rotations turn fastest among all product categories.
- Fruits:Strawberry and raspberry propagation under glass remains concentrated in Limburg geothermal concession zones.
Vegetables anchors the volume base while greenhouse automation gains share at the steepest rate across herb and vegetable propagation facilities.
Technology:
Capital intensity stratifies sharply, with entry-level hydroponic installations requiring one-tenth the investment of fully automated vertical farming modules.
- Hydroponics:Recirculating nutrient film systems sustain mature margin pools among herb producers serving direct consumer channels. Closed-loop irrigation retrofits comply with Dutch Ministry of Agriculture nitrogen emission ceilings while reducing water withdrawal volumes.
- Greenhouse Automation:Process computer platforms from Hoogendoorn and Priva control irrigation dosing, energy management, and climate regulation across Westland glasshouse clusters. Labor cost escalation and EU energy efficiency mandates accelerate deployment fastest among tomato and cucumber propagation facilities.
- Aquaponics:Integrated fish-horticulture systems remain experimental in Dutch commercial operations.
- Vertical Farming:Layered cultivation robotics enable year-round herb production for direct-to-consumer channels in urban proximity zones.
Hydroponics sustains the installed base while greenhouse automation climbs the fastest as energy and labor cost pressures intensify.
End User:
Procurement specifications tighten progressively from wholesale auction channels to supermarket contract systems.
- Retailers:Albert Heijn, Jumbo, and Lidl Nederland mandate blockchain-traceable input documentation and verified low-carbon production credentials. Contract renewal terms depend on real-time harvest data integration into retailer inventory systems.
- Exporters:German and French retail procurement prioritizes carbon border adjustment mechanism alignment for Dutch tomato and pepper volumes.
- Wholesalers:Aalsmeer auction intermediaries aggregate ornamental production from dispersed growers.
- Direct Consumers:Subscription herb box services and farm gate sales operate outside supermarket contract structures.
Retailers anchor the volume base while direct consumer channels expand most quickly through vertical farming convergence.
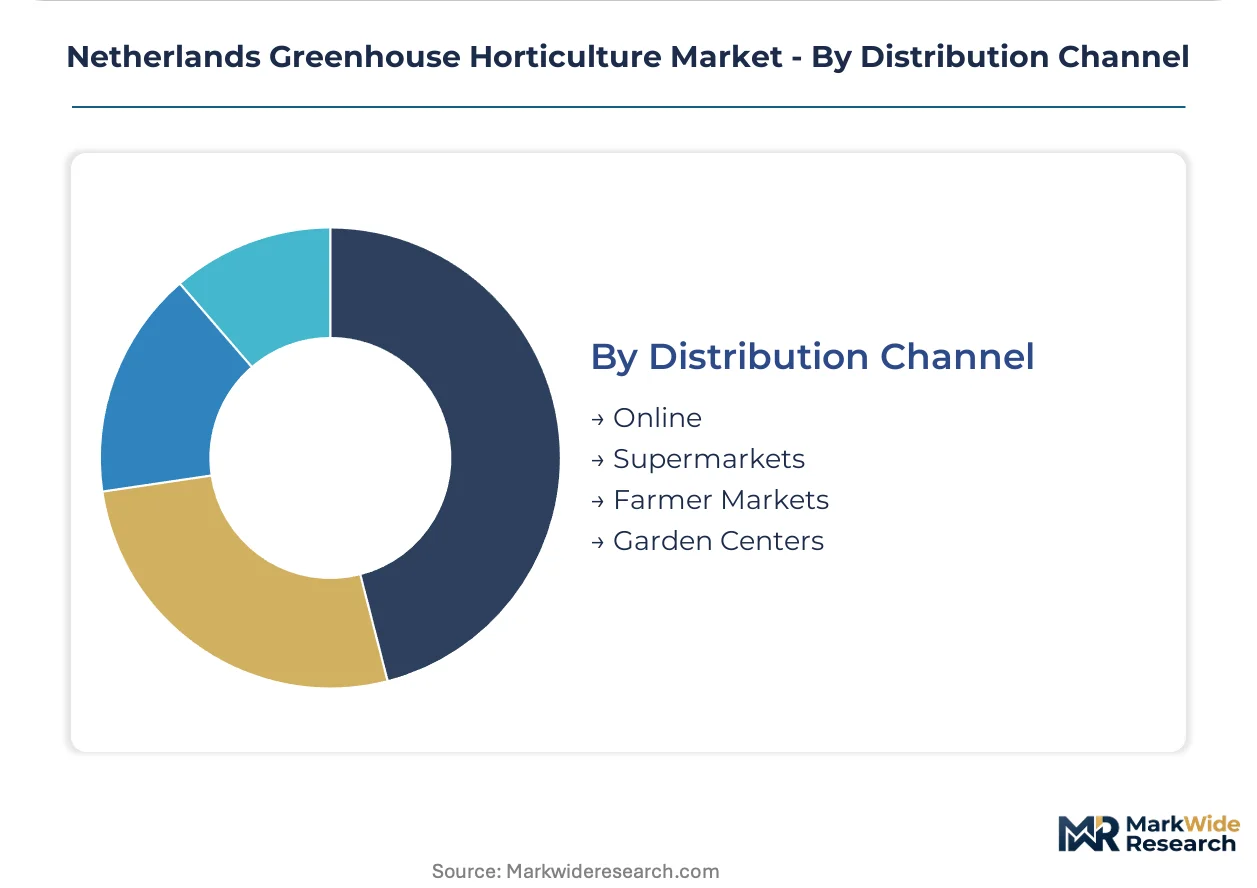
Distribution Channel:
Physical infrastructure concentration in Rotterdam distribution hubs advantages supermarket and wholesale channels over fragmented farmer market and garden center routes.
- Supermarkets:Centralized procurement through Albert Heijn and Jumbo distribution networks concentrates demand in Westland municipality clusters around Naaldwijk and Monster.
- Online:Direct-to-consumer herb subscriptions and specialty vegetable box services bypass traditional wholesale markups.
- Farmer Markets:Seasonal outdoor sales channels carry minimal share in Dutch greenhouse horticulture.
- Garden Centers:Ornamental plant retail concentrates in spring purchasing cycles.
Supermarkets anchor the volume base while online channels gain share at the steepest rate among herb and specialty vegetable segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Westland municipality clusters concentrate Dutch greenhouse density through shared CO₂ distribution and waste heat recovery infrastructure. Geothermal concession allocations under the Ministry of Economic Affairs now extend beyond saturated Westland zones into Limburg and Zeeland provinces.
Westland Municipality Cluster
Naaldwijk-to-Monster greenhouse density enables contracted vegetable supply to Albert Heijn and Jumbo Supermarkten distribution networks. EU Green Deal nitrogen emission ceilings compel closed-loop irrigation retrofits across this saturated production zone. Rotterdam distribution hub proximity anchors real-time harvest data integration requirements for contract renewal.
Limburg Province
Geothermal heating concessions from the Ministry of Economic Affairs attract strawberry and raspberry propagation facilities seeking lower carbon credentials. EU Natura 2000 deposition limits constrain new acreage permits, favoring technology-intensive retrofit projects over greenfield expansion. Venlo and Venray sub-regions host emerging glasshouse clusters with German export orientation.
Zeeland Province
Coastal wind energy integration supports electrically heated propagation facilities serving direct-to-consumer herb channels. The Dutch Ministry of Agriculture enforces strict water withdrawal limits, accelerating recirculating hydroponic adoption. Goes and Middelburg zones concentrate experimental vertical farming convergence with traditional greenhouse automation.
Aalsmeer Auction Zone
Ornamental propagation faces steepest EU Green Deal pesticide reduction compliance costs due to zero-residue German and French retail requirements. EFSA hazard assessment delays for biological crop protection agents disrupt pest management planning cycles. FloraHolland auction infrastructure concentrates exporter intermediaries serving cross-border wholesale channels.
Netherlands Greenhouse Horticulture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying climate computers, irrigation dosing modules, and sensor arrays. The vendor base stratifies between full-service greenhouse engineering firms and discrete automation technology providers. Two strategic archetypes dominate: integrated project developers bundling glasshouse construction with process control systems, and pure-play software-hardware vendors licensing climate management platforms. Competitive moves concentrate on geothermal heating concession partnerships and carbon credential verification services for supermarket procurement compliance.
Among Dutch integrated engineering specialists, Certhon and Van Der Hoeven occupy positions as full-service project developers, while Hoogendoorn represents the pure-play automation platform tier. These three entities exemplify the structural split between capital-intensive glasshouse construction and recurring-license climate control software. Their positioning reflects divergent margin profiles: project developers capture upfront engineering and construction value, while platform vendors extract ongoing service revenue from installed process computer bases. The competitive tension between these archetypes shapes partnership dynamics with Westland growers seeking bundled solutions versus modular upgrade paths.
| Leading Market Players |
|---|
| Certhon |
| Van Der Hoeven |
| Hoogendoorn |
| KUBO Group |
| Ridder Group |
| Dalsem |
| HortiMaX |
| Bom Group |
| Priva |
| Others |
Pricing and Supply Chain Analysis
Rotterdam port-to-Westland corridor freight dynamics compress logistics cost structures for German and Belgian glass imports while amplifying price differentiation between geothermal-connected growers and natural gas-dependent operations. This corridor concentration enables Westland clusters to arbitrage between spot energy markets and long-term supermarket contract pricing.
Pricing Analysis
EU Green Deal Farm to Fork pesticide reduction targets dictate the pricing tier structure across Dutch greenhouse horticulture. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified low-carbon producers from conventional operations and uncontracted spot-market sellers. Price differentiation hinges on carbon credential verification and real-time harvest data integration into retailer inventory systems. Pricing pressure stems from natural gas cost volatility before geothermal connections reach operational scale, with Albert Heijn and Jumbo contract growers least price-sensitive due to volume commitments while uncontracted herb producers face the steepest margin compression.
Supply Chain Analysis
Extended payment terms from Dutch greenhouse engineering firms to Belgian aluminum extrusion and German coated glass suppliers compress working capital cycles for Westland project developers. Specialized construction materials concentrate in Germany, Belgium, and the Netherlands, with recirculating hydroponic components, climate computer platforms, and supplemental LED arrays anchoring hardware procurement. Supply chain risk centers on single-source vulnerability for geothermal drilling equipment and EFSA evaluation delays for biological crop protection agents. Distribution runs through Rotterdam distribution hubs concentrating supermarket and export channels while online direct-to-consumer herb services bypass traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Netherlands greenhouse horticulture is reshaping as EU Green Deal mandates and geothermal infrastructure expansion converge to displace conventional energy-dependent operations. This regulatory-technological inflection compresses margins for laggards while rewarding early automation adopters.
For Market Incumbents: Entrench market position through closed-loop irrigation retrofits that satisfy Dutch Ministry of Agriculture nitrogen emission ceilings and secure contract renewals with Albert Heijn and Jumbo. Prioritize geothermal heating concession partnerships in Limburg and Zeeland to escape Westland saturation and natural gas price volatility. Deepen backward integration into biological crop protection agent procurement from Koppert and Biobest to circumvent EFSA registration delays disrupting pest management programs. For New Entrants and Emerging Players: Establish a beachhead in Zeeland Province vertical farming convergence zones where coastal wind energy integration supports electrically heated herb propagation for direct-to-consumer channels. Target subscription herb box services and specialty vegetable deliveries bypassing supermarket procurement concentration. Lead with climate computer platform licensing from Hoogendoorn or Priva rather than capital-intensive glasshouse construction to reduce entry barriers. For Investors and Strategic Acquirers: Pure-play automation software vendors with recurring license revenue streams present the most attractive acquisition profile in this sector. Long-term viability favors platform vendors over project developers as geothermal infrastructure matures and service revenue displaces upfront engineering value. Watch for carbon border adjustment mechanism implementation in German and French retail procurement as the inflection signal determining premium pricing capture for verified low-carbon Dutch producers.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Heating Concession Expansion | Ministry of Economic Affairs allocations in Limburg and Zeeland open low-carbon production clusters beyond saturated Westland zones. |
| Closed-Loop Irrigation Retrofit | Dutch Ministry of Agriculture nitrogen emission ceilings compel recirculating hydroponic adoption for permit compliance. |
| Biological Crop Protection Procurement | EFSA hazard assessment delays for conventional pesticides accelerate Koppert and Biobest biocontrol agent demand. |
| Blockchain Traceability Integration | Albert Heijn and Jumbo mandate input documentation transparency for contract renewal eligibility. |
| Hybrid LED Lighting Deployment | Supplemental LED arrays extend photosynthetic photon flux density during winter months without full HPS replacement capital burden. |
Research Methodology
Desk research of EU regulatory filings, Dutch Ministry of Agriculture policy documents, and FloraHolland auction transaction data preceded structured interviews with greenhouse operations managers, Certhon and Van Der Hoeven project engineers, Hoogendoorn platform integration specialists, and Albert Heijn procurement leads. Primary fieldwork with Westland growers and Aalsmeer ornamental exporters combined with secondary validation from geothermal concession registries and supermarket contract disclosure patterns. Bottom-up acreage and yield modeling triangulated against top-down retail procurement volume estimates.
Assumptions held fixed include EU Green Deal Farm to Fork pesticide reduction target enforcement timelines and Dutch Natura 2000 nitrogen deposition limits across the analysis window. Segmentation modeling incorporated product type cycle times, technology capital intensity tiers, and end-user procurement specification tightening. CAGRs derived from historical supermarket contract volume growth and projected geothermal connection ramp rates. Industry-specific forecast inputs included LED lighting adoption curves and biological crop protection substitution elasticities.
Sensitivities concentrate around natural gas price volatility duration, EFSA biological product registration timelines, and carbon border adjustment mechanism implementation scope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
UAE Tomato Market
Vegetables
Yam Products Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Microgreens Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Yams Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Field Peas Market
Vegetables
Tomato Market
Vegetables
Dried Peas Market
Vegetables
Vegetable Chutney Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Europe Christmas Tree Market
Vegetables
Fresh Mushroom Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Qatar Greenhouse Market