
 Greenhouse Bell Pepper Market | 2026-2036
Greenhouse Bell Pepper Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse Bell Pepper Market Insights
Rock wool substrate is restructuring greenhouse bell pepper economics by displacing traditional soil mixes in hydroponic systems. Nature Fresh Farms leverages integrated propagation and packing facilities across Ontario and Ohio to sustain year-round supply consistency. Mastronardi Produce anchors North American premium retail placement through its Sunset brand network. Houweling's Tomatoes competes via closed-loop water recirculation systems that cut input waste at its California and Delta, British Columbia sites.
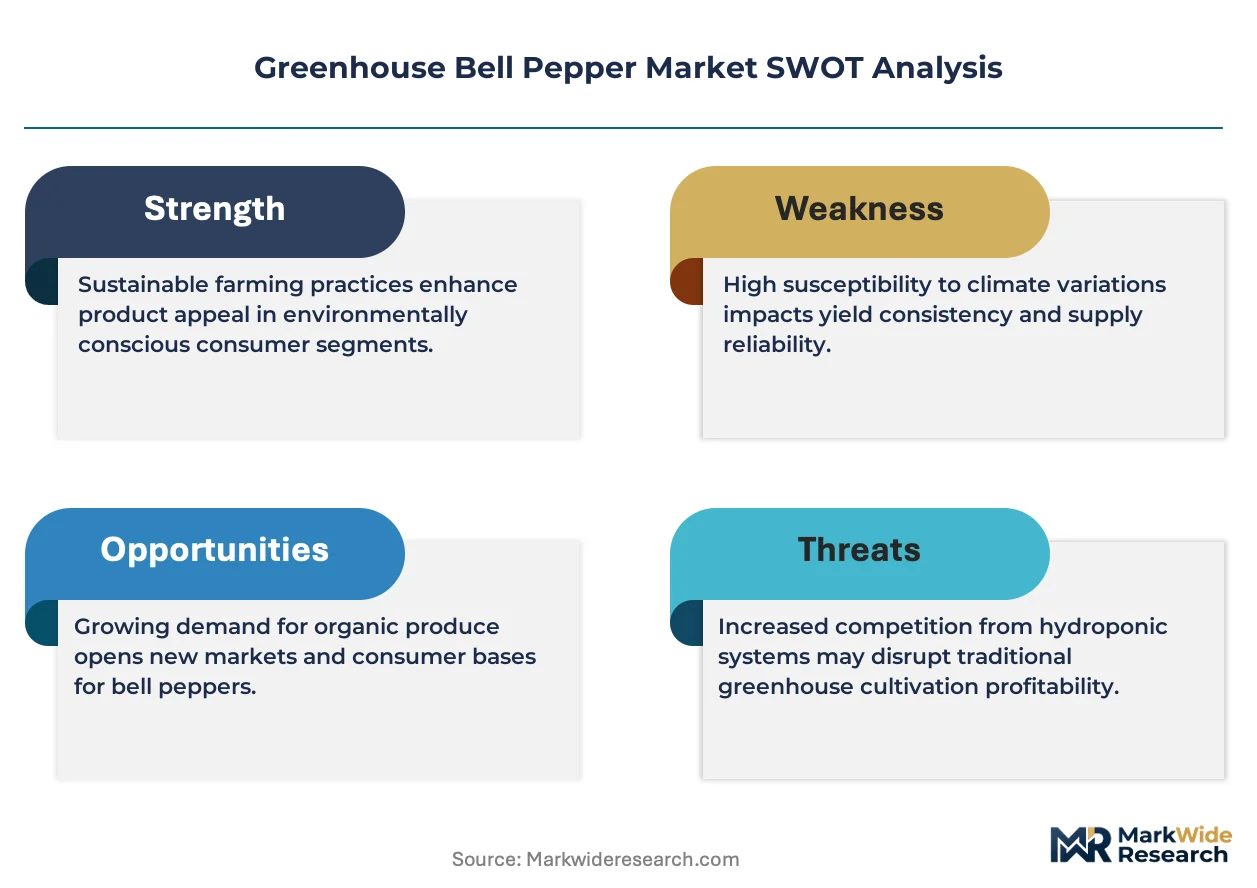
Greenhouse bell peppers are Capsicum annuum fruits cultivated under controlled-environment agriculture with managed temperature regimes between 18°C and 26°C, supplemental CO2 enrichment, and drip-irrigation nutrient delivery to achieve uniform fruit wall thickness and coloration for fresh market standards. Red bell peppers command premium shelf positioning due to extended maturity cycles and higher Brix content, while mini bell peppers represent the fastest-expanding product type as snack-format demand from retail and foodservice channels intensifies. Hydroponic growing technology dominates commercial scale operations for water-use efficiency, though organic methods capture escalating price premiums in European and North American specialty retail.
USDA organic certification and FDA Food Safety Modernization Act traceability requirements shape product standards and market access for greenhouse bell pepper imports into the United States. REACH chemical governance in the European Union and ECHA biocide regulations constrain pesticide residue thresholds and substrate treatment protocols for exporters. Mexico's national phytosanitary authority and Canada's CFIA impose parallel inspection regimes that stakeholders must navigate for cross-border shipment continuity. Buyers and growers should monitor evolving energy cost structures and carbon border adjustment mechanisms as determinants of competitive positioning in protected vegetable trade.
Market Dynamics
LED supplemental lighting and climate automation systems are compressing energy inputs per kilogram of yield, restructuring cost structures for protected cultivation operations across export-grade production clusters.
Growth Catalysts
- USDA Organic Certification:Price premiums for certified greenhouse bell peppers in North American specialty retail channels are expanding grower margins and incentivizing conversion from conventional hydroponic methods.
- Snack-format retail demand:Mini bell peppers are capturing expanded shelf space from fresh produce chains seeking higher-margin, ready-to-eat vegetable offerings for convenience-oriented consumers.
- CFIA harmonization with FDA:Streamlined phytosanitary inspection protocols between Canada and the United States are reducing border delays for cross-border greenhouse bell pepper shipments.
Market Restraints
- Natural gas price volatility:Heating costs for Dutch and Canadian greenhouse operations fluctuate with continental energy markets, compressing margins during winter production cycles.
- Rock wool substrate concentration:Supply of certified propagation media concentrates among limited European manufacturers, creating input bottleneck risks for expanding North American hydroponic capacity.
- Field-grown substitution:Open-field bell pepper production in Spain, Morocco, and California competes on price during seasonal windows, pressuring greenhouse premium positioning.
Strategic Opportunities
- US Inflation Reduction Act energy credits:Greenhouse operators installing solar-plus-battery systems qualify for investment tax credits that offset climate automation capital expenditures.
- Closed-loop water recirculation:Integration of nutrient film technique with biological filtration enables zero-discharge operations in water-stressed regions of California and Arizona.
- Foodservice pre-cut processing:Contract slicing and dicing for restaurant chains and institutional kitchens opens B2B volume channels beyond traditional retail whole-fruit distribution.
Industry Challenges
- CO2 enrichment technician scarcity:Operations managing supplemental carbon dioxide injection systems require specialized training that outpaces regional vocational program output in Ontario and Ohio growing clusters.
- Organic certification timeline:Three-year transition periods for soil-based greenhouse conversions to USDA organic standards delay revenue realization from premium price tiers.
- Legacy climate control integration:Retrofitting established greenhouse structures with IoT sensor networks and automated venting systems demands phased capital deployment that disrupts production continuity.
Report Scope
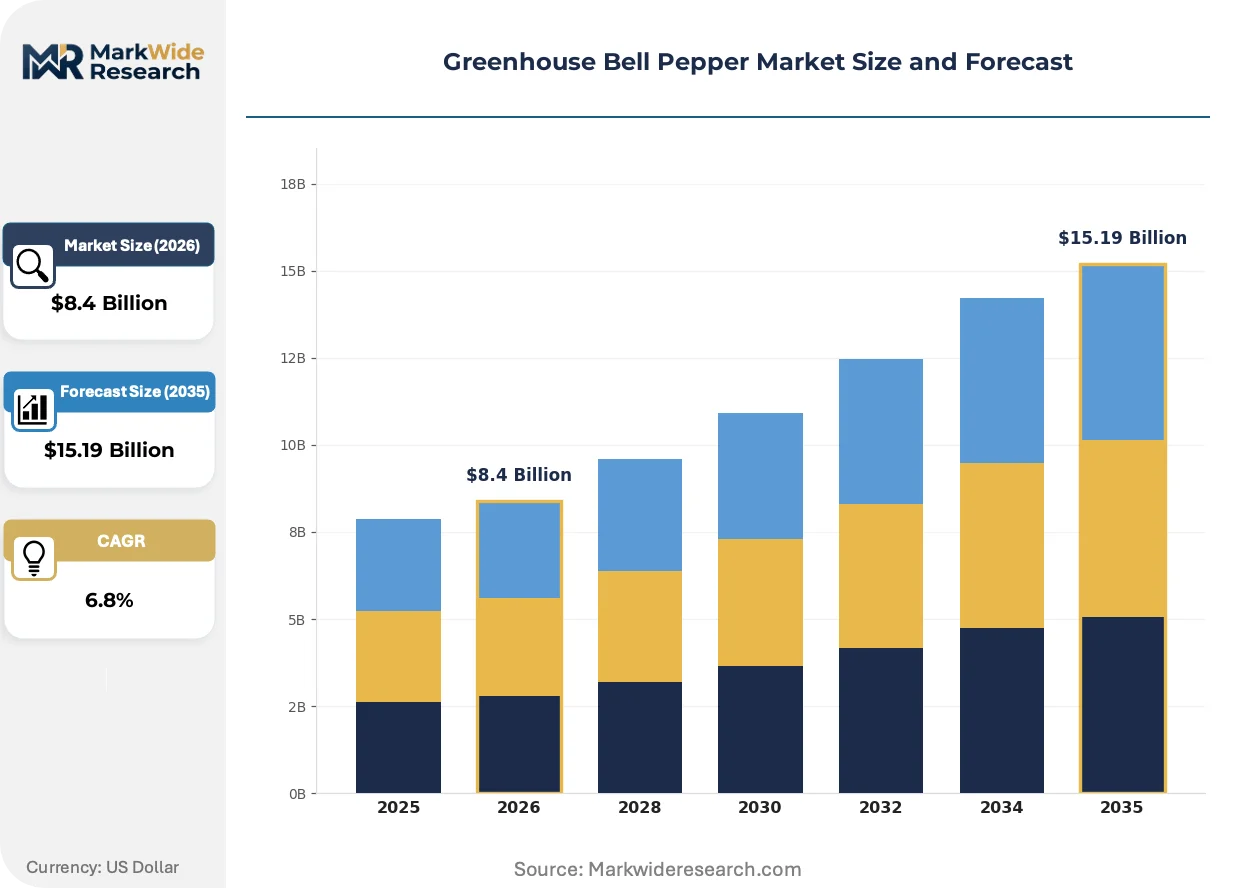
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse Bell Pepper Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Bell Pepper, Yellow Bell Pepper, Green Bell Pepper, Mini Bell Pepper Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Wholesale Distributors End User: Restaurants, Food Processors, Households, Catering Services Growing Technology: Hydroponics, Aeroponics, Soil-Based Cultivation, Organic Methods |
| Companies Covered | Nature Fresh Farms, Houweling's Tomatoes, Mastronardi Produce, Revol Greens, BrightFarms, Windset Farms, Mucci Farms, Bushel Boy Farms, Village Farms International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse Bell Pepper Market Trends and Innovations
Controlled-environment agriculture is converging with digital horticulture platforms, reshaping how greenhouse bell pepper operations manage propagation, harvest timing, and post-harvest quality retention.
Spectral LED arrays is integrating variable wavelength programming that matches light recipes to fruit color development stages. Large-scale operators in the Netherlands and Mexico are deploying tunable red-blue-white systems across multi-hectare facilities. This technology is integrating photomorphogenic control into standard cultivation protocols, enabling precise acceleration of red pigmentation without extending crop cycles.
REACH biocide restrictions are eliminating quaternary ammonium compounds from substrate sterilization workflows throughout European Union member states. Dutch exporters must now demonstrate alternative heat-treatment or biological control documentation for shipments entering Germany, France, and Belgium. Protected cultivation facilities are responding by adopting steam pasteurization and beneficial microorganism inoculation protocols that satisfy ECHA compliance without chemical residues.
Direct-store-delivery networks are displacing traditional produce auction and wholesale terminal channels for greenhouse bell pepper distribution. Retail chains including regional grocers in Texas, Illinois, and Pennsylvania are contracting dedicated truck capacity from Ontario and Ohio growing operations. This pattern concentrates most visibly in the Great Lakes corridor, where Nature Fresh Farms and similar integrated packers maintain captive logistics fleets for just-in-time replenishment of perimeter produce departments.
Greenhouse Bell Pepper Market Segmentation
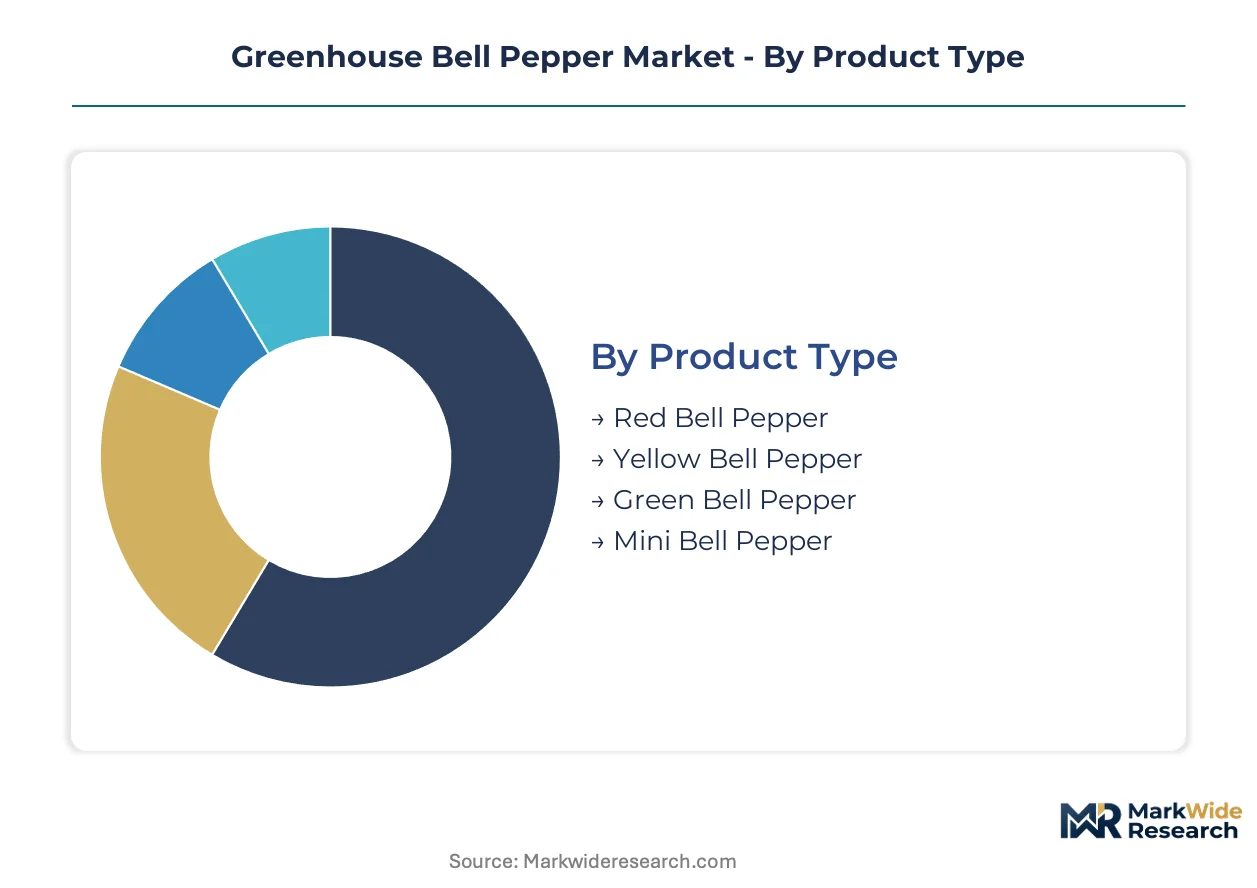
Greenhouse bell pepper segmentation reveals divergent margin structures across color maturity stages and cultivation methodologies. Product type stratification drives the deepest pricing spreads, while growing technology choices lock in capital intensity and certification pathways for multi-year operational cycles.
Product Type:
Red varieties command extended growing cycles and premium shelf positioning, while mini formats capture snack-format volume expansion.
- Red Bell Pepper:Extended maturity cycles of 70-90 days from flowering deliver thicker fruit walls and elevated Brix content. Dutch and Mexican operations concentrate supply for North American retail premium tiers, constrained by heating cost volatility during winter production windows.
- Mini Bell Pepper:Snack-format dimensions (5-7cm length) align with convenience-oriented retail and foodservice pre-pack demand. Ontario and Ohio growing clusters are expanding dedicated propagation lines to serve this segment's steepest expansion trajectory.
- Yellow Bell Pepper:Intermediate maturity positioning between green and red harvest windows captures mid-tier pricing.
- Green Bell Pepper:Early harvest at physiological immaturity minimizes input days and targets price-sensitive volume channels.
Today's leader: Red Bell Pepper. Tomorrow's challenger: Mini Bell Pepper.
Distribution Channel:
Direct-store-delivery networks are compressing traditional wholesale terminal margins through captive logistics integration.
- Supermarkets:Perimeter produce department placement drives volume concentration, with Great Lakes corridor retailers contracting dedicated truck capacity from integrated Ontario packers.
- Online Retail:E-commerce fresh produce penetration remains constrained by last-mile temperature control costs.
- Farmers' Markets:Local provenance premiums support small-scale greenhouse operators in bypassing wholesale margin extraction.
- Wholesale Distributors:Traditional auction and terminal channels face displacement from retail direct contracting.
Supermarkets anchor current volume. Online retail faces execution barriers.
End User:
Foodservice pre-processing requirements are splitting demand between whole-fruit retail and value-added institutional channels.
- Restaurants:Consistent sizing and color uniformity specifications dominate procurement from chain operators.
- Food Processors:Contract slicing and dicing for ready-meal manufacturers opens B2B volume beyond traditional retail.
- Households:Consumer selection prioritizes visual shelf appeal and organic certification badges.
- Catering Services:Bulk volume procurement with flexible grade tolerances.
Households drive retail premium capture. Food processors unlock B2B scale.
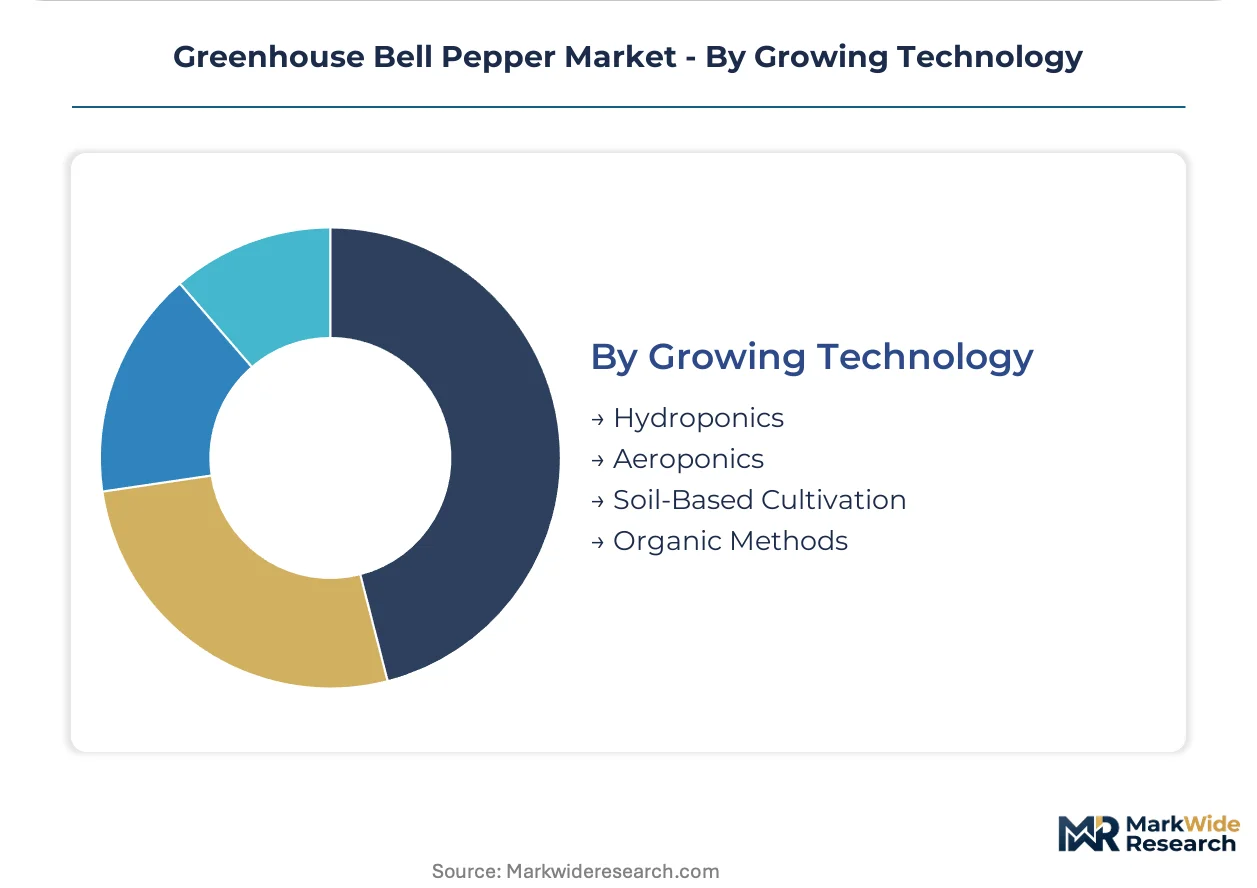
Growing Technology:
Water-use efficiency mandates and organic certification timelines are restructuring technology adoption curves across production clusters.
- Hydroponics:Rock wool substrate systems with drip-irrigation nutrient film technique dominate commercial scale operations for water efficiency. Netherlands and Mexico concentrate export-grade volume, though rock wool supply bottlenecks from limited European manufacturers constrain North American expansion.
- Organic Methods:Three-year USDA certification timelines delay premium revenue realization, but specialty retail price premiums in European and North American markets justify conversion investments for soil-based greenhouse operators.
- Aeroponics:Mist-based root delivery remains experimental at commercial bell pepper scale.
- Soil-Based Cultivation:Conventional substrate approaches face displacement from hydroponic efficiency gains.
Hydroponics commands commercial scale. Organic methods capture escalating price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands concentrates protected cultivation technology export and domestic production volume for greenhouse bell peppers. Dutch innovation in climate automation and LED spectral systems propagates through licensing agreements to North American and Mexican growing operations.
United States
Retail chains in Texas, Illinois, and Pennsylvania expand perimeter produce placement for greenhouse-grown varieties. FDA Food Safety Modernization Act traceability requirements shape import acceptance protocols at border inspection points. California's Central Valley hosts closed-loop water recirculation facilities that serve foodservice pre-processing contracts.
Mexico
Export-grade volume to North American retail concentrates in protected cultivation zones with year-round harvest capability. The national phytosanitary authority maintains inspection regimes parallel to USDA and CFIA standards for cross-border shipment continuity. Sinaloa and Baja California growing clusters deploy hydroponic systems licensed from Dutch technology providers.
Canada
Integrated propagation and packing facilities in Ontario sustain just-in-time replenishment contracts with Great Lakes corridor retailers. CFIA harmonization with FDA protocols reduces border delays for greenhouse bell pepper shipments to US markets. The Leamington-Kingsville growing cluster anchors North American winter production with supplemental CO2 enrichment systems.
Spain
Open-field bell pepper production in Almería and Murcia competes on price during seasonal windows against greenhouse-protected imports. REACH chemical governance constrains substrate treatment protocols for any Spanish greenhouse operators seeking German, French, or Belgian market access. Andalusian growing regions face margin pressure from Moroccan field-grown competition during peak harvest months.
Greenhouse Bell Pepper Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated packers add propagation lines and captive logistics fleets. The vendor base concentrates among North American integrated operators and Dutch technology-licensed Mexican exporters. Two strategic archetypes prevail: vertically integrated packer-shippers with direct-store-delivery networks, and technology-specialist greenhouse operators licensing climate automation systems. Competitive intensity manifests through M&A consolidation of regional growing operations and strategic partnerships between Dutch equipment suppliers and North American facility developers.
Within the integrated packer-shipper tier, Nature Fresh Farms and Mastronardi Produce occupy positions defined by captive retail relationships and year-round supply consistency. Houweling's Tomatoes exemplifies the water-efficiency specialist archetype through its closed-loop recirculation infrastructure. These three entities represent the dominant competitive anchors structuring premium retail placement and foodservice contract negotiations across North American distribution channels.
| Leading Market Players |
|---|
| Nature Fresh Farms |
| Houweling's Tomatoes |
| Mastronardi Produce |
| Revol Greens |
| BrightFarms |
| Windset Farms |
| Mucci Farms |
| Bushel Boy Farms |
| Village Farms International |
| Others |
Pricing and Supply Chain Analysis
Natural gas heating costs for Dutch and Canadian winter production cycles propagate downstream through three-tier pricing structure across premium, standard, and economy levels, with red varieties absorbing margin compression while mini formats capture snack-format premiums.
Pricing Analysis
Input-cost pass-through from rock wool substrate and LED energy systems stratifies pricing across certification tiers. USDA organic badges command shelf-price premiums over conventional hydroponic supply, while field-grown Spanish and Moroccan imports compress standard-tier margins during seasonal windows. Foodservice buyers exhibit highest price sensitivity on volume contracts, whereas specialty retail chains absorb premiums for year-round color consistency.
Supply Chain Analysis
Regional distribution centers in Ontario, Ohio, and Sinaloa anchor hub-and-spoke patterns serving Great Lakes and Texas retail chains. Production concentrates in the Netherlands, Mexico, and Canada, with Dutch climate-automation technology licensing dependencies creating single-source vulnerability for North American facility expansions. Distribution runs through direct-store-delivery networks displacing traditional wholesale terminals, while rock wool supply bottlenecks from limited European manufacturers constrain input security.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greenhouse bell pepper markets have entered a late-cycle quality phase where retail buyers prioritize Brix content and color uniformity specifications over volume discounts, rewarding operators with integrated propagation-to-packing infrastructure.
For Market Incumbents: Lock in retail shelf-space contracts through captive logistics fleets before emerging Mexican exporters complete Dutch-technology facility expansions. Prioritize backward integration into CO2 enrichment system maintenance capabilities to offset technician scarcity in Ontario and Ohio growing clusters. Organic certification investments defend margin position against conventional hydroponic price erosion.
For New Entrants and Emerging Players: Food processors seeking contract slicing and dicing capacity represent an underserved buyer archetype with lower brand-loyalty barriers than established retail channels. Target Arizona and California water-stressed regions with closed-loop recirculation value propositions. Pursue B2B pre-cut processing partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where integrated packer-shippers lack captive propagation facilities to guarantee year-round supply consistency. Five-to-ten year viability favors operators with direct-store-delivery network control and LED spectral technology deployment. Acquisition targets should demonstrate established retail relationships in the Great Lakes corridor. Watch CFIA-FDA harmonization progress as an inflection indicator for cross-border volume scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Water Recirculation Deployment | Enables zero-discharge operations in California's water-stressed Central Valley growing zones. |
| Direct-Store-Delivery Network Expansion | Captures perimeter produce placement from Texas and Illinois retail chains seeking just-in-time replenishment. |
| USDA Organic Certification Investment | Unlocks specialty retail price premiums that justify three-year soil-based conversion timelines. |
| Spectral LED Array Integration | Accelerates red pigmentation development without extending crop cycles in Dutch-licensed Mexican facilities. |
| Foodservice Pre-Processing Partnership | Opens B2B volume channels beyond traditional whole-fruit retail distribution for institutional kitchen contracts. |
Research Methodology
Bottom-up household and foodservice demand modeling reconciled against top-down protected cultivation capacity tracking forms the analytical core of this study. Primary interviews with greenhouse operations managers, retail produce buyers, and foodservice procurement directors were validated against secondary sources including USDA AMS price reports, CFIA import inspection data, and Dutch greenhouse technology licensing disclosures. Triangulation across these inputs ensures segmentation integrity across product type, distribution channel, and growing technology dimensions.
Historical trendline analysis of planted area under protected cultivation and yield-per-hectare improvements informed projection frameworks across the analysis window. Segmentation modeling incorporated color maturity stage, cultivation methodology certification pathway, and regional energy cost structure as core dimensions. CAGRs were derived from slope analysis of volume and value trajectories, with CO2 enrichment adoption curves and LED penetration rates serving as key forecast inputs.
Inputs from regulatory filing databases and industry association statistics were available through the study window; gaps in real-time energy cost volatility data introduce uncertainty bands around margin projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Acorn Squash Market
Vegetables
Field Peas Market
Vegetables
Tomato Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Vegetable Chutney Market
Vegetables
North America Christmas Tree Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Yam Products Market
Vegetables
UAE Tomato Market
Vegetables
Potato Market
Vegetables
Spain Avocado Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Dry Onion Market