
 France Ultrasound Devices Market | 2026-2036
France Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Ultrasound Devices Market Foresight
Equipment leasing and pay-per-use financing is reshaping competitive dynamics in France's ultrasound sector. GE Healthcare leverages its service infrastructure to anchor long-term hospital contracts. Koninklijke Philips NV competes through bundled software-hardware subscriptions that reduce capital barriers. Siemens Healthineers AG differentiates via remote diagnostics integration tied to leasing structures.
Ultrasound devices generate acoustic images through piezoelectric transducer arrays operating at frequencies between two and fifteen megahertz, enabling non-invasive visualization of soft tissue, blood flow, and fetal development for diagnostic and interventional guidance. Portable ultrasound systems are capturing expanded share in French emergency and point-of-care settings where mobility outweighs premium imaging depth. Color ultrasound technology sustains margin concentration in cardiology departments, while handheld formats occupy the fastest-expanding niche among general practitioners and rural clinics.
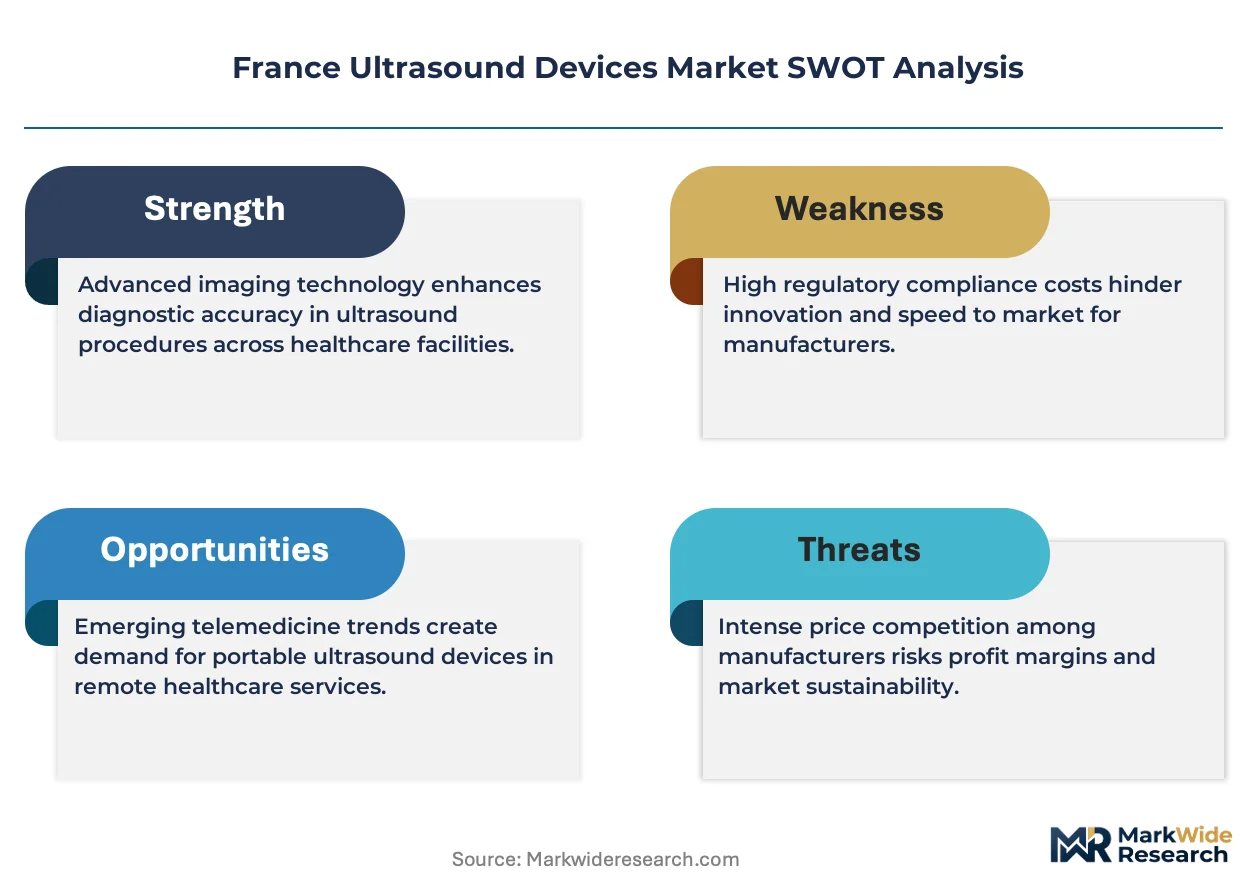
ANSM enforces post-market surveillance obligations under France's MDR transposition, compelling manufacturers to maintain clinical evidence registries for device recertification. CE marking requirements, supplemented by HAS evaluation for hospital reimbursement eligibility, shape product development priorities and market access timelines. Stakeholders must monitor evolving HTA criteria from HAS that increasingly weight cost-per-diagnostic-accuracy metrics over hardware specifications alone.
Market Dynamics
Leasing-based procurement models are restructuring capital deployment across French hospital networks, compressing replacement cycles while elevating service-contract stickiness as the primary competitive moat.
Growth Catalysts
- MDR Transposition:France's implementation of EU Medical Device Regulation mandates systematic clinical evidence registries, accelerating upgrade demand among manufacturers seeking sustained CE marking validity.
- Île-de-France Hospital Clusters:Parisian teaching hospitals operate as concentrated demand anchors, driving premium system replacement through consolidated procurement consortia.
- Handheld Point-of-Care Expansion:Emergency departments and rural general practitioners are adopting portable ultrasound formats where mobility supersedes imaging depth requirements.
Market Restraints
- Piezoelectric Crystal Supply Concentration:Transducer manufacturing depends on specialized ceramic suppliers concentrated in East Asian production corridors, exposing French OEMs to input volatility.
- HAS Evaluation Timelines:Haute Autorité de Santé cost-per-diagnostic-accuracy assessments extend reimbursement eligibility windows, delaying revenue recognition for novel imaging modalities.
- Computed Tomography Substitution:Cardiology departments retain CT angiography preference for coronary assessments, limiting ultrasound penetration in high-value diagnostic pathways.
Strategic Opportunities
- Auvergne-Rhône-Alpes Regional Expansion:Lyon-based hospital networks demonstrate underpenetrated leasing contract density relative to Parisian benchmarks, offering geographic whitespace.
- Remote Diagnostics Convergence:Cloud-native image transmission integrated with cart-based systems enables teleradiology service layering atop hardware subscriptions.
- ANSM Post-Market Surveillance Data Monetization:Mandatory clinical evidence registries create proprietary real-world evidence assets for outcomes-based contracting with regional health agencies.
Industry Challenges
- Sonographer Training Pipeline Constraints:Specialized ultrasound technician certification programs face enrollment shortfalls, creating operational bottlenecks for expanded point-of-care deployment.
- Legacy PACS Integration Complexity:Hospital information systems require costly middleware development to synchronize new ultrasound platforms with existing radiology archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Ultrasound Devices Market |
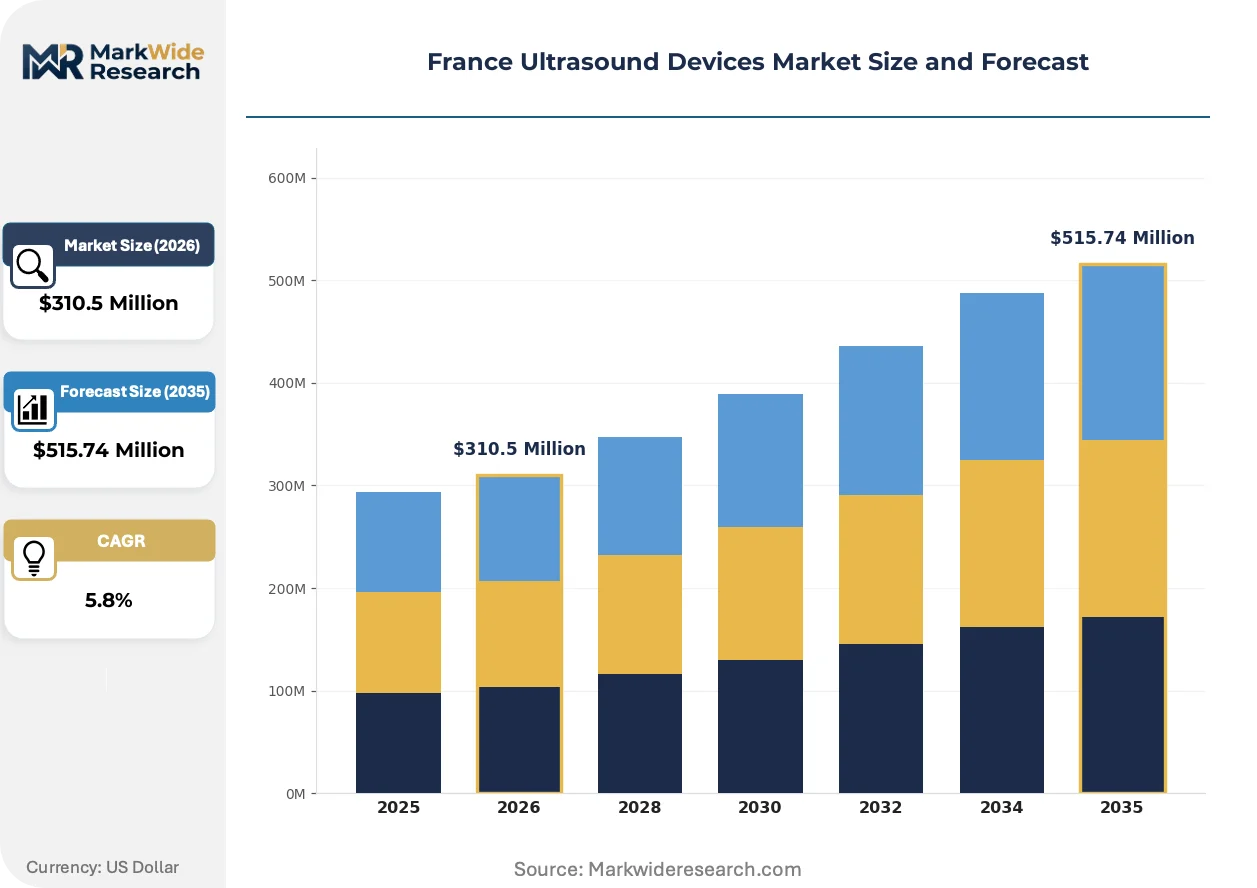
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $515.74 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Console Ultrasound, Portable Ultrasound, Handheld Ultrasound, Cart-Based Ultrasound Technology: Doppler Ultrasound, 3D Ultrasound, 4D Ultrasound, Color Ultrasound Application: Cardiology, Obstetrics & Gynecology, Urology, Musculoskeletal End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutes |
| Companies Covered | GE Healthcare, Koninklijke Philips NV, Siemens Healthineers AG, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Mindray Medical International Limited, Samsung Electronics Co. Ltd, Esaote SpA, Supersonic Imagine SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Ultrasound Devices Market Shifts & Advancements
Artificial intelligence inference engines are embedding directly into ultrasound hardware, compressing diagnostic interpretation timelines while shifting value capture from radiologists toward equipment vendors.
Shear wave elastography is hybridizing conventional B-mode imaging with quantitative tissue stiffness measurement, enabling non-invasive liver fibrosis staging that previously required biopsy. Gastroenterology departments in French university hospitals are adopting these systems at replacement-cycle velocity. The technology is hybridizing hardware specifications with software-defined diagnostic outputs, collapsing the distinction between imaging modality and laboratory assay.
France's ANSM enforcement of MDR post-market surveillance obligations tightens clinical evidence requirements for device recertification, compelling manufacturers to maintain active patient registries. Industrial consequence includes elongated product development timelines as pre-market clinical data must supplement technical documentation. Cardiology-focused systems face the steepest compliance burden given their higher-risk classification under MDR Annex VIII.
Hospital procurement consortia are consolidating vendor relationships around multi-year managed equipment service agreements that unbundle capital expenditure from operational budgets. Regional purchasing groups in Nouvelle-Aquitaine and Occitania are displacing transactional equipment sales with subscription-based utilization models. This transformation concentrates most visibly among public hospital networks where budget predictability outweighs ownership preferences.
France Ultrasound Devices Market Segmentation
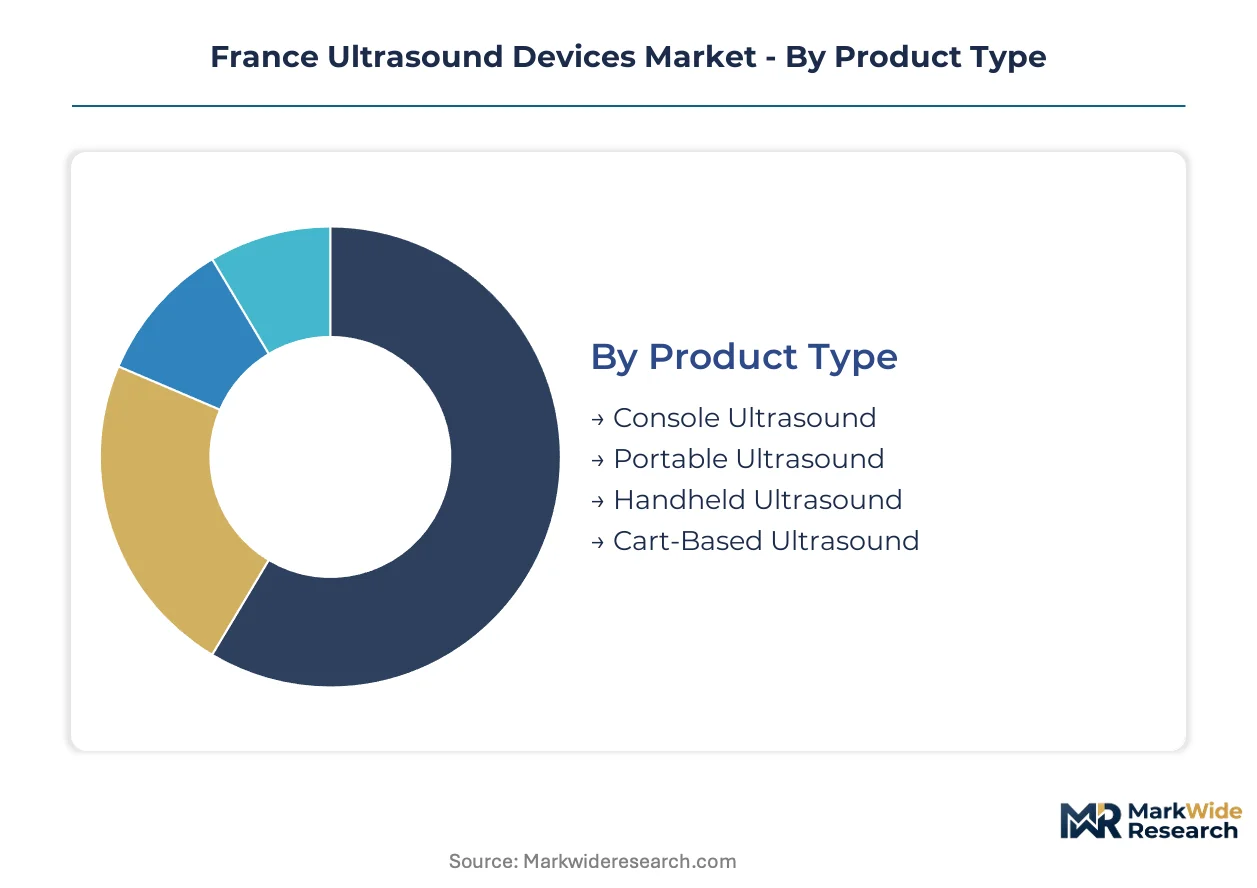
Segmentation in France's ultrasound market reveals how procurement consolidation and point-of-care decentralization operate as opposing forces. Each dimension—product format, imaging technology, clinical application, and care setting—carries distinct regulatory and reimbursement implications under ANSM and HAS frameworks.
Product Type:
Mature cart-based systems anchor hospital procurement while handheld formats represent the emerging frontier for primary care expansion.
- Console Ultrasound:Stationary systems integrate high-channel-count beamformers with specialized transducer arrays for deep abdominal and cardiac imaging. Parisian teaching hospitals in Île-de-France drive replacement demand through consolidated leasing consortia seeking service-contract predictability.
- Portable Ultrasound:Battery-powered units with cart-mount flexibility bridge emergency department workflows and bedside diagnostics. Auvergne-Rhône-Alpes hospital networks are expanding portable fleets faster than national averages as they close infrastructure gaps with Parisian benchmarks.
- Handheld Ultrasound:Smartphone-connected probes enable general practitioner examinations in rural Nouvelle-Aquitaine clinics where specialist access remains limited.
- Cart-Based Ultrasound:Full-featured mobile platforms with motorized height adjustment dominate high-throughput radiology departments requiring rapid room-to-room relocation.
Cart-based systems handle the majority of throughput; handheld ultrasound is gaining share fastest among general practitioners.
Technology:
Cost tier differentiation separates premium volumetric imaging from standard Doppler platforms, with reimbursement eligibility tightening at the top end.
- Doppler Ultrasound:Frequency-shift detection enables blood flow velocity mapping for vascular and cardiac assessment. Diagnostic centers in Occitania deploy Doppler systems for peripheral artery disease screening programs under regional health agency contracts.
- Color Ultrasound:Real-time flow overlay on B-mode images sustains margin concentration in cardiology departments despite CT angiography competition for coronary assessments.
- 3D Ultrasound:Volume reconstruction from sequential 2D slices supports fetal anomaly detection in obstetrics departments seeking HAS reimbursement qualification.
- 4D Ultrasound:Live volumetric rendering with temporal dimension commands premium positioning in private maternity clinics targeting expectant parents seeking enhanced visualization.
Color ultrasound maintains the installed base; 4D systems are climbing the fastest on share in private diagnostic settings.
Application:
Volume concentration in obstetrics contrasts with margin opportunity in musculoskeletal interventions where procedure coding supports equipment amortization.
- Cardiology:Echocardiography systems with phased-array transducers enable left ventricular function assessment and valvular evaluation. HAS cost-per-diagnostic-accuracy metrics increasingly weight functional output over hardware specifications alone.
- Obstetrics & Gynecology:Transabdominal and transvaginal imaging protocols dominate routine pregnancy monitoring across public hospital maternity networks.
- Urology:Transrectal ultrasound guides prostate biopsy procedures with elastography enhancement for lesion characterization in university hospital urology departments.
- Musculoskeletal:High-frequency linear arrays visualize tendon integrity and guide injection therapies, with sports medicine clinics in Provence-Alpes-Côte d'Azur driving handheld adoption.
Obstetrics handles the majority of throughput; musculoskeletal is expanding most quickly on procedure volume.
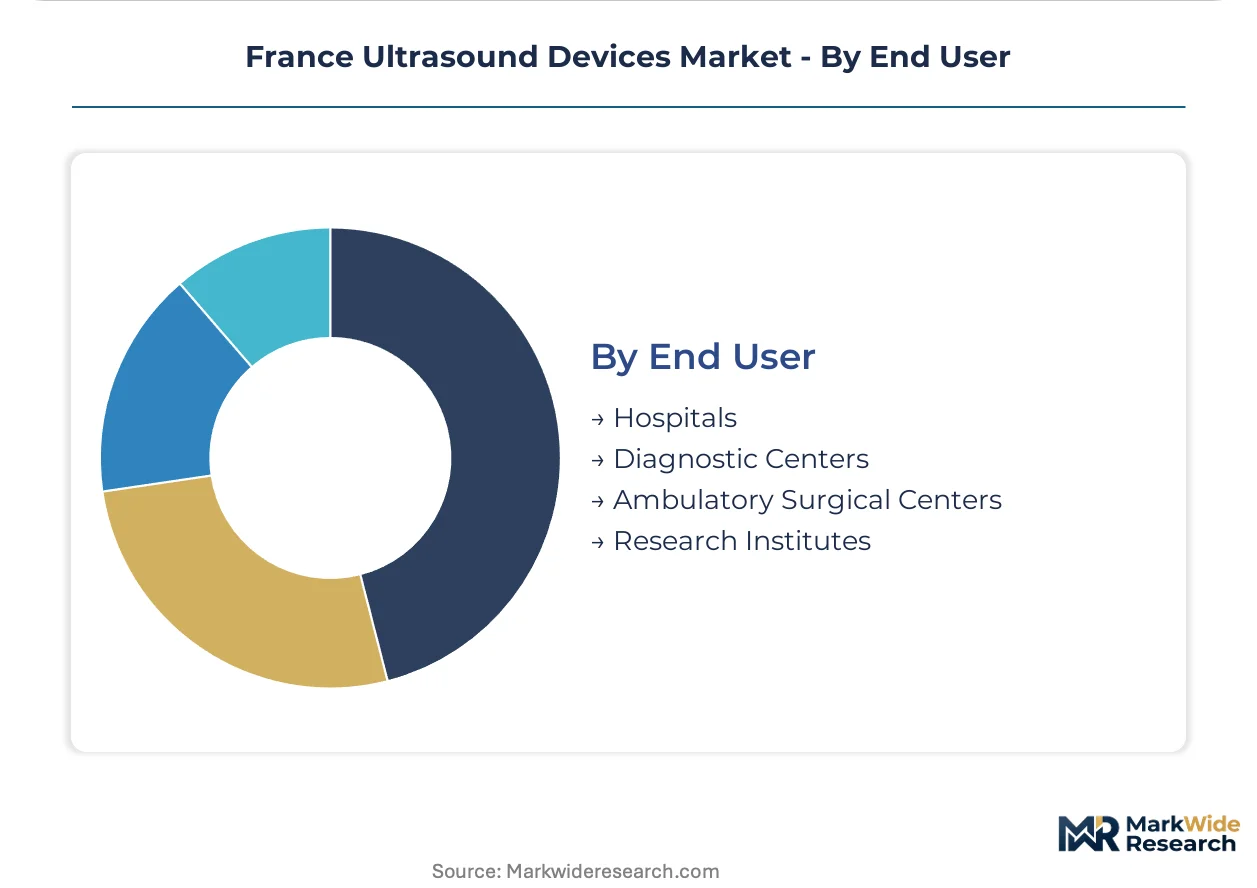
End User:
Customer type determines capital deployment models, with public hospitals favoring operational leases and ambulatory centers seeking ownership for tax depreciation.
- Hospitals:Public hospital networks in Île-de-France and Hauts-de-France operate as concentrated demand anchors through multi-year managed equipment service agreements that unbundle capital expenditure from operational budgets.
- Diagnostic Centers:Independent imaging facilities in Grand Est prioritize throughput velocity and rapid patient turnaround to maximize scanner utilization rates.
- Ambulatory Surgical Centers:Day-case facilities in Brittany adopt portable systems for preoperative assessment and postoperative monitoring where space constraints limit fixed installations.
- Research Institutes:Academic medical centers in Lyon and Marseille deploy experimental shear wave elastography configurations for liver fibrosis staging validation studies.
Hospitals command the majority of installed base; ambulatory surgical centers are the fastest mover on share as outpatient procedural volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's MDR transposition and regional hospital procurement consortia are redistributing ultrasound demand across metropolitan and peripheral health networks. Leasing penetration varies sharply between consolidated urban clusters and dispersed rural systems.
Île-de-France
Parisian teaching hospitals drive premium system replacement through multi-year managed equipment service agreements. ANSM post-market surveillance obligations accelerate upgrade cycles among manufacturers seeking sustained CE marking validity. The AP-HP consortium anchors procurement concentration in the capital region.
Auvergne-Rhône-Alpes
Lyon-based hospital networks demonstrate underpenetrated leasing contract density relative to Parisian benchmarks. HAS evaluation timelines for cost-per-diagnostic-accuracy metrics shape reimbursement eligibility for novel imaging modalities. Research institutes in Lyon deploy experimental shear wave elastography configurations for liver fibrosis validation studies.
Provence-Alpes-Côte d'Azur
Sports medicine clinics drive handheld ultrasound adoption for musculoskeletal interventions. Regional health agencies contract diagnostic centers for peripheral artery disease screening programs. Marseille academic medical centers participate in post-market clinical evidence registries mandated by ANSM.
Nouvelle-Aquitaine
Rural general practitioners adopt smartphone-connected probes where specialist access remains limited. Regional purchasing groups displace transactional equipment sales with subscription-based utilization models. Bordeaux hospital networks expand portable system fleets to close infrastructure gaps with northern benchmarks.
Occitanie
Diagnostic centers prioritize throughput velocity and rapid patient turnaround to maximize scanner utilization rates. Public hospital networks unbundle capital expenditure from operational budgets through consolidated leasing arrangements. Toulouse-based procurement consortia negotiate multi-year service contracts with embedded remote diagnostics integration.
France Ultrasound Devices Market Competitive Landscape
On the supply side, the industry is consolidated around diversified medical technology conglomerates with embedded service infrastructures. Three strategic archetypes dominate: integrated imaging platforms with leasing capabilities, handheld specialists targeting point-of-care decentralization, and regional European manufacturers with elastography differentiation. Competitive moves concentrate on long-term managed service agreements and cloud-native image transmission integration.
Within the integrated platform tier, GE Healthcare, Koninklijke Philips NV, and Siemens Healthineers AG exemplify the service-contract stickiness model reshaping French hospital procurement. These manufacturers occupy positions where hardware subscriptions reduce capital barriers while anchoring multi-year relationships with regional purchasing groups.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips NV |
| Siemens Healthineers AG |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Mindray Medical International Limited |
| Samsung Electronics Co. Ltd |
| Esaote SpA |
| Supersonic Imagine SA |
| Others |
Supply & Pricing Matrix
East Asian ceramic foundries in Jiangsu and Osaka prefectures constrain transducer array availability, concentrating upstream pricing power among three specialized piezoelectric suppliers and compressing margin buffers for French OEMs negotiating hospital leasing contracts.
Pricing Analysis
Certification level under MDR Annex VIII creates the primary spread between premium cardiology systems and standard radiology platforms. Three-tier pricing structure across premium, standard, and economy levels reflects HAS evaluation status, with CE-marked devices commanding lease premiums over transitional legacy equipment. Cost compression in the handheld segment is intensifying because smartphone-connected probes commoditize hardware while software subscriptions capture recurring value. Rural general practitioners in Nouvelle-Aquitaine exhibit highest price sensitivity, whereas Parisian teaching hospitals prioritize service-contract predictability over per-unit acquisition cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates procurement risk for French ultrasound manufacturers sourcing ceramic substrates and semiconductor beamformers. Manufacturing draws from specialized facilities in Japan, South Korea, and Germany for high-frequency transducer arrays, precision motors, and FPGA chipsets. Single-source vulnerability concentrates in lead zirconate titanate crystal supply from two Jiangsu-based producers. Distribution runs through regional hospital procurement consortia with embedded service technicians rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's ultrasound sector sits at an inflection where AI-embedded hardware and MDR-mandated clinical evidence registries are simultaneously elevating compliance burdens and opening subscription monetization pathways.
For Market Incumbents: Pre-empt handheld specialist encroachment by bundling cloud-native image transmission with cart-based leasing contracts. Anchor multi-year managed equipment service agreements with AP-HP and regional purchasing groups before emerging players establish teleradiology overlays. Invest in ANSM-compliant clinical evidence registries to defend CE marking validity against MDR recertification deadlines.
For New Entrants and Emerging Players: Pursue Auvergne-Rhône-Alpes hospital networks where leasing contract density trails Parisian benchmarks by substantial margins. Target musculoskeletal applications in Provence-Alpes-Côte d'Azur sports medicine clinics where procedure coding supports equipment amortization outside radiology department budgets. Deploy smartphone-connected probes through direct-to-practitioner subscription models bypassing consolidated procurement consortia.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified imaging conglomerates seeking to divest non-core ultrasound assets ahead of MDR compliance cost spikes. Long-term viability hinges on software-defined diagnostic outputs rather than hardware specifications alone. Monitor HAS cost-per-diagnostic-accuracy metric evolution as the signal indicating when outcomes-based contracting displaces capital equipment ownership.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Registry Investment | ANSM post-market surveillance obligations mandate active patient data collection for sustained CE marking validity. |
| Cloud-Native Image Transmission Integration | Remote diagnostics layering atop hardware subscriptions enables teleradiology service monetization in regional hospital networks. |
| Shear Wave Elastography Platform Development | Hybrid imaging-assay systems capture gastroenterology department replacement cycles for non-invasive liver fibrosis staging. |
| Handheld Point-of-Care Distribution Partnership | Rural general practitioner networks in Nouvelle-Aquitaine offer whitespace for smartphone-connected probe penetration. |
| Multi-Year Managed Equipment Service Agreement | Operational lease structures with embedded maintenance unbundle capital expenditure from public hospital operational budgets. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement directors, biomedical engineering leads, GPO contracts managers, and sonography department heads and refined through secondary validation against ANSM device registries, HAS reimbursement databases, EU MDR technical documentation, and hospital leasing contract disclosures. Bottom-up demand modeling triangulated with top-down market sizing across product format, imaging technology, clinical application, and care setting dimensions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type, technology tier, application area, and end-user category. CAGRs derived from replacement cycle velocity, leasing penetration trajectories, and point-of-care decentralization rates. Key inputs included MDR transposition timelines, HAS evaluation queue lengths, and regional hospital procurement consortium consolidation patterns.
Sensitivities concentrate around ANSM enforcement intensity, HAS cost-per-diagnostic-accuracy metric adoption speed, and East Asian ceramic supply disruption. Forecasts reflect documented assumptions regarding leasing model transition velocity and AI-embedded hardware adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Oxygen Conservers Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Spherical IOL Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market