
 Aortic Valve Replacement Devices Market | 2026-2036
Aortic Valve Replacement Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Aortic Valve Replacement Devices Market Analysis
Transcatheter delivery platforms is reconfiguring the aortic valve replacement technology stack by shifting procedures from open-heart surgery toward minimally invasive catheter-based interventions. Edwards Lifesciences Corporation dominates transcatheter valve innovation with sustained R&D investment in next-generation leaflet materials. Medtronic anchors global manufacturing scale across both surgical and transcatheter portfolios. Abbott Laboratories differentiates through its structural heart portfolio spanning repair and replacement technologies.
Aortic valve replacement devices are implantable prostheses designed to restore hemodynamic function in patients with stenotic or regurgitant native valves, typically constructed from bovine pericardium, porcine tissue, or polymer composites and manufactured to precise annular sizing tolerances. TAVI leads device type revenue as aging demographics and expanding indication labels broaden eligible patient pools. Transcatheter delivery mode captures the fastest growth trajectory while open-heart surgical valve replacement maintains volume in younger patients requiring durable long-term solutions. Material selection increasingly favors bovine pericardium for its tensile strength and biocompatibility profile in transcatheter applications.
FDA premarket approval pathways and EMA Medical Device Regulation (MDR) compliance requirements shape clinical trial design and market access timelines for manufacturers. ISO 5840 cardiovascular implant standards govern fatigue resistance and hydrodynamic performance testing protocols that determine product eligibility across major markets. Japan's PMDA adds distinct local clinical data requirements that filter which multinational firms establish direct commercial presence. Stakeholders must monitor evolving reimbursement decisions for TAVI expansion into intermediate-risk and asymptomatic patient categories.
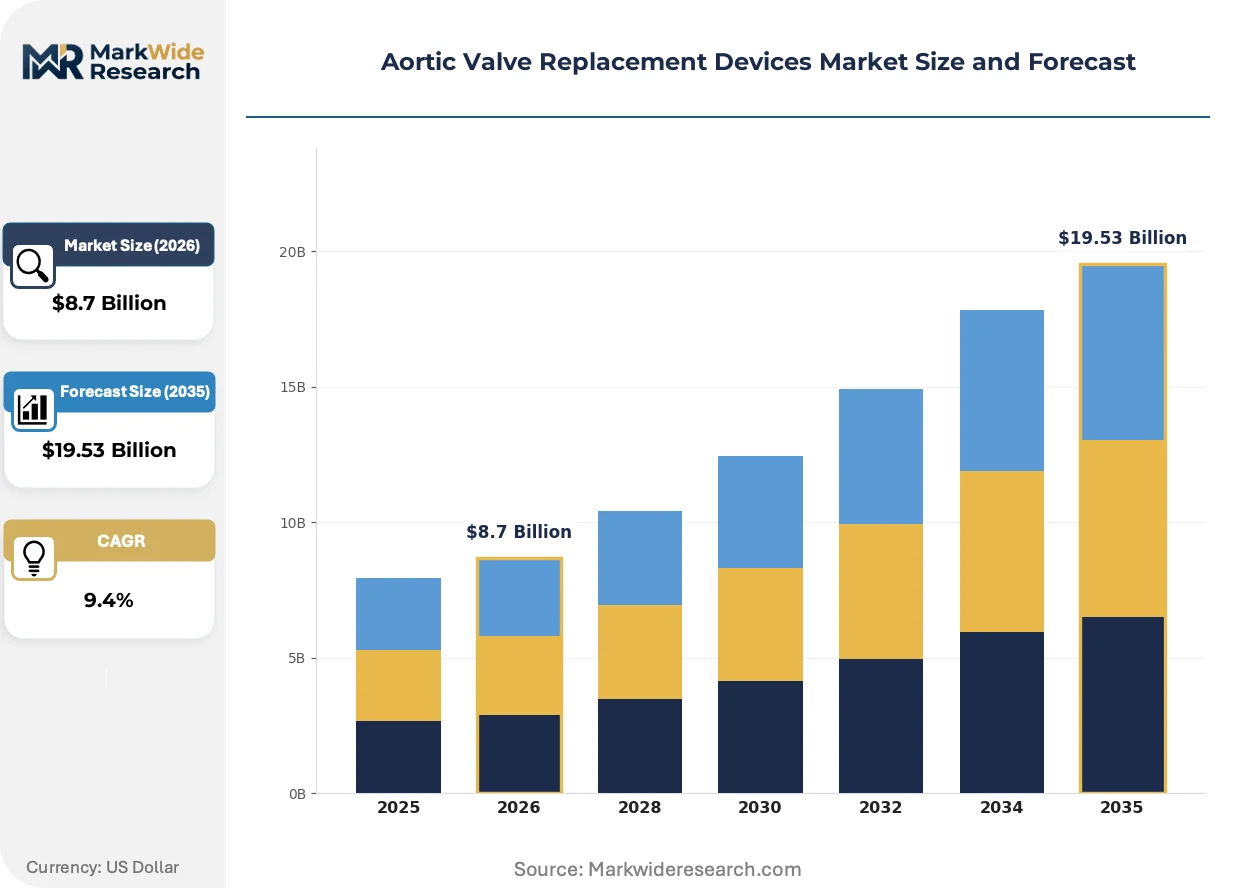
Market Dynamics
Transcatheter delivery platforms are compressing the treatment pathway from diagnosis to intervention, forcing manufacturers to reconfigure clinical evidence generation around real-world performance data rather than traditional surgical benchmarks. This shift demands new competencies in catheter engineering, imaging integration, and ambulatory care coordination.
Growth Catalysts
- Expanding TAVI Indications:FDA label expansions into intermediate-risk and asymptomatic patient categories are enlarging addressable populations beyond inoperable surgical candidates. Cardiac units in the United States and Germany are scaling catheterization lab capacity to capture this volume.
- EMA MDR Harmonization:Streamlined conformity assessment pathways for well-established device categories are reducing redundant testing burdens for manufacturers with existing CE-marked portfolios. This regulatory efficiency accelerates iterative product improvements.
- Bovine Pericardium Standardization:Superior tensile strength and calcification resistance in transcatheter leaflet materials are displacing porcine tissue in next-generation valve designs. Material suppliers are securing long-term tissue sourcing agreements with abattoir networks.
Market Restraints
- Clinical Evidence Escalation:FDA premarket approval pathways now mandate extended follow-up data that stretches development timelines and inflates trial costs for novel transcatheter designs.
- Supply Concentration Risk:Bovine pericardium sourcing depends on geographically concentrated abattoir processing in Argentina and Australia, exposing manufacturers to veterinary disease outbreaks and export restrictions.
- Surgical Valve Durability:Mechanical and stented bioprosthetic surgical valves retain superior long-term hemodynamic performance in patients under 65, limiting transcatheter penetration in younger demographics.
Strategic Opportunities
- Japan PMDA Localization:Distinct clinical data requirements create first-mover advantages for manufacturers establishing direct commercial infrastructure and domestic manufacturing partnerships.
- Convergent Imaging-Navigation:Integration of intra-procedural computed tomography planning with robotic catheter guidance is enabling precision deployment in anatomically complex valve morphologies previously excluded from transcatheter candidacy.
- Value-Based Reimbursement Pilots:Bundled payment models for complete episode-of-care management are creating incentives for manufacturers to expand training and technical support services beyond device provision.
Industry Challenges
- Interventional Cardiology Workforce Constraints:TAVI program expansion outpaces fellowship training pipeline output, creating procedural bottlenecks even where catheterization lab infrastructure exists.
- ISO 5840 Fatigue Testing Complexity:Accelerated wear simulation protocols for novel leaflet materials require specialized equipment and expertise that few contract research organizations possess.
- Legacy Electronic Health Record Integration:Structured data capture for transcatheter valve registries demands costly interoperability modifications to hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aortic Valve Replacement Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: TAVI, Surgical Valve, Balloon Valvuloplasty, Mechanical Valve End User: Hospitals, Outpatient Clinics, Specialty Centers, Cardiac Catheterization Labs Delivery Mode: Transcatheter, Open-Heart Surgery, Hybrid Procedure, Robotic-Assisted Surgery Material: Bovine Pericardium, Porcine Tissue, Polypropylene, Composite Materials |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic, Abbott Laboratories, Boston Scientific Corporation, LivaNova PLC, Artivion, Inc, JenaValve Technology Inc, Venus MedTech HangZhou Inc, Braile Biomedica Industry, Commerce and Representations Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aortic Valve Replacement Devices Market Emerging Trajectories
Computational modeling and advanced materials science are converging to compress development cycles while expanding treatable patient anatomies. These forces are reconfiguring how manufacturers generate clinical evidence and how hospitals organize structural heart programs.
Polymer-based leaflet materials with engineered surface chemistries are virtualizing the traditional tissue sourcing model for transcatheter valves. Early adopters in German and Japanese academic medical centers are integrating these devices into feasibility trials. This virtualization is collapsing the supply chain from abattoir-dependent tissue processing to controlled polymer synthesis, reducing batch variability and enabling precision customization of leaflet thickness and compliance profiles.
EU Medical Device Regulation (MDR) Article 117 requirements for notified body involvement in clinical evaluation are extending market access timelines for legacy device families seeking iterative modifications. Manufacturers with substantial European revenue exposure are front-loading quality management system investments to maintain certificate continuity. High-risk Class III implantable devices face the most pronounced documentation burdens, driving some firms to prioritize United States and Japan launches.
Hospital procurement committees are unbundling device selection from procedural service contracts, creating direct purchasing relationships with manufacturers rather than distributor-mediated transactions. This disintermediation concentrates negotiating leverage within integrated delivery networks possessing high TAVI volumes. The United States exhibits the most advanced manifestation of this pattern, with several regional health systems establishing sole-source arrangements contingent upon comprehensive training and outcomes reporting commitments.
Aortic Valve Replacement Devices Market Segmentation
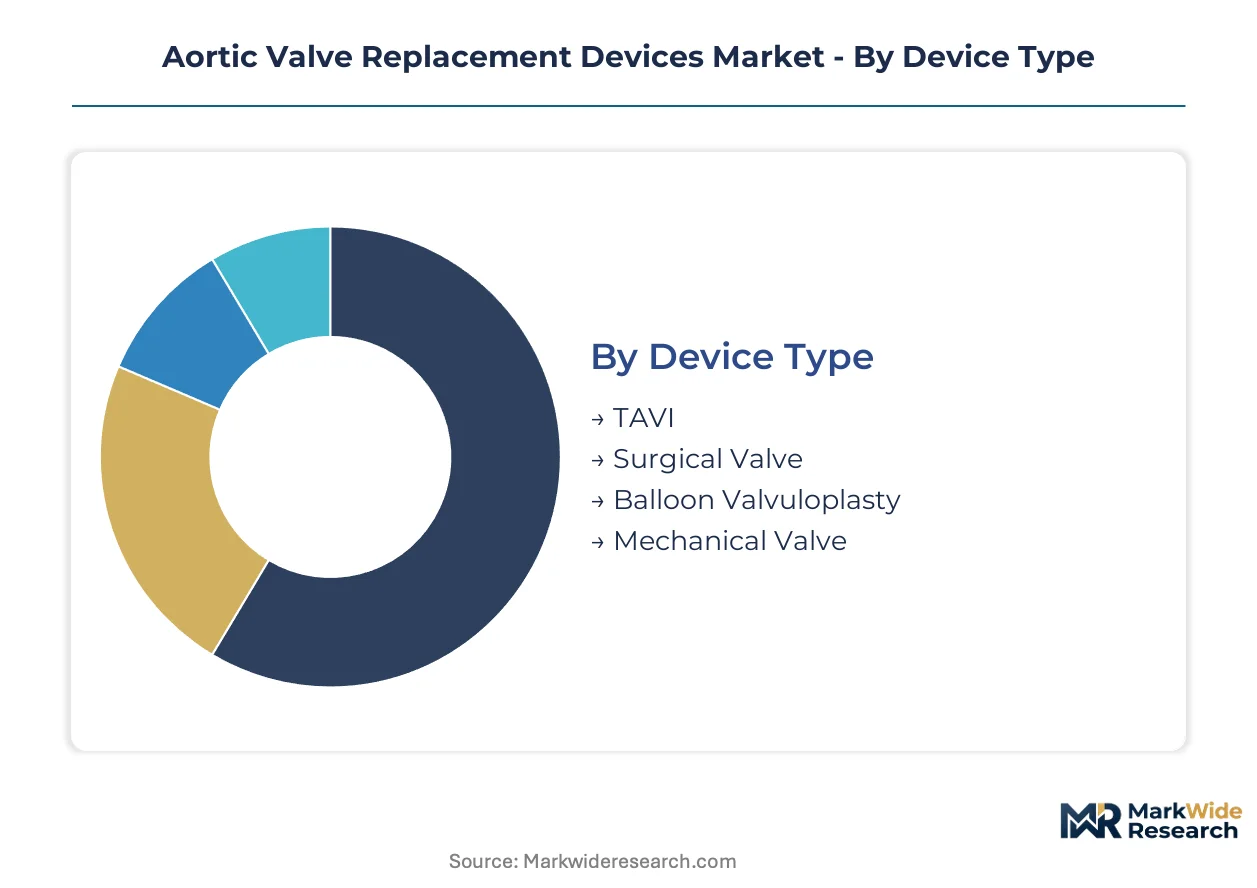
Segmentation in aortic valve replacement devices reveals how clinical decision-making splits across patient anatomy, procedural risk tolerance, and institutional capability. Manufacturers align product portfolios to these fracture lines, prioritizing catheter-based platforms for aging populations while maintaining surgical alternatives for durable long-term outcomes.
Device Type:
Clinical use-case spectrum spans from definitive valve replacement to palliative intervention, with reimbursement pathways determining which technologies achieve procedural scale.
- TAVI:Self-expanding or balloon-expandable bioprosthetic valves delivered via femoral or alternative vascular access. Demand concentrates in United States hospital cardiac units and German academic medical centers, where FDA label expansions into intermediate-risk patients and EMA MDR harmonization accelerate program buildout.
- Surgical Valve:Stented or stentless bioprosthetic and mechanical valves requiring sternotomy and cardiopulmonary bypass. Established volume in Japan and United States surgical centers serves patients under 65 requiring multi-decade durability, constrained by TAVI expansion into younger demographics.
- Balloon Valvuloplasty:Palliative dilation procedure without valve implantation, typically bridging to definitive therapy or treating high-surgical-risk acute presentations.
- Mechanical Valve:Pyrolytic carbon bileaflet designs offering lifelong durability with anticoagulation burden, retaining niche demand in pediatric and young adult populations.
Established volume favors Surgical Valve; emerging adoption favors TAVI.
End User:
Cost tier differentiation separates high-complexity inpatient infrastructure from ambulatory settings seeking lower fixed-cost deployment.
- Hospitals:Comprehensive cardiac surgery and catheterization capabilities supporting full spectrum of valve interventions, from emergency surgery to elective TAVI. United States integrated delivery networks and German university hospitals anchor procedural volume through bundled reimbursement contracts.
- Cardiac Catheterization Labs:Dedicated interventional suites within hospital systems or standalone facilities optimized for transcatheter procedures. Japan's PMDA regulatory pathway and United States outpatient prospective payment system revisions are expanding site-of-service flexibility.
- Outpatient Clinics:Limited diagnostic and follow-up capacity without interventional capability, serving post-procedural monitoring and anticoagulation management.
- Specialty Centers:Focused structural heart programs combining surgical and interventional expertise in concentrated referral patterns.
Margin concentration sits with Hospitals; volume expansion favors Cardiac Catheterization Labs.
Delivery Mode:
Application maturity separates decades-established surgical approaches from catheter platforms still accumulating long-term hemodynamic data.
- Transcatheter:Femoral, transapical, or alternative vascular access avoiding sternotomy and cardiopulmonary bypass. United States and Germany lead procedural scaling as imaging integration and operator training standardize.
- Open-Heart Surgery:Median sternotomy with cardiopulmonary bypass enabling direct valve visualization and secure anchoring. Retains dominance in Japan for younger patients and complex redo operations.
- Hybrid Procedure:Combined surgical and interventional approach in hybrid operating suites, enabling transcatheter deployment with surgical backup or concomitant procedures.
- Robotic-Assisted Surgery:Da Vinci and comparable platforms enabling minimally invasive surgical valve replacement through port access, limited by capital cost and learning curve constraints.
Technology leadership clusters around Transcatheter; durability validation favors Open-Heart Surgery.
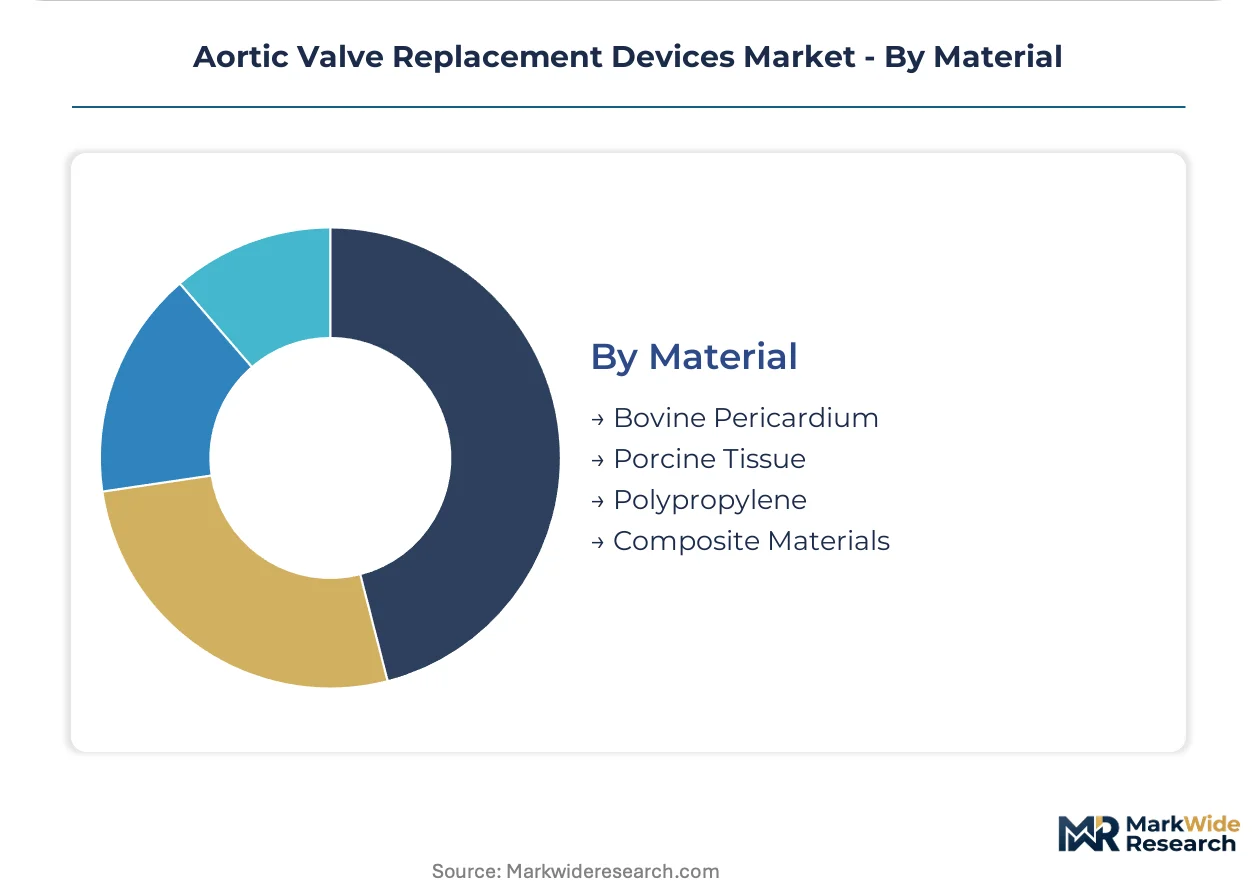
Material:
Supply concentration shapes competitive positioning, with biological sourcing constraints driving synthetic alternatives.
- Bovine Pericardium:Cross-linked bovine tissue providing tensile strength and calcification resistance for transcatheter leaflets. Argentina and Australia abattoir networks supply United States and European manufacturers, with long-term sourcing agreements securing batch consistency.
- Polypropylene:Synthetic polymer emerging in next-generation transcatheter designs, eliminating biological sourcing variability. Early adoption in German and Japanese feasibility trials tests fatigue resistance against ISO 5840 protocols.
- Porcine Tissue:Aortic or intestinal porcine valve leaflets with established surgical bioprosthetic track record, gradually displaced by bovine pericardium in transcatheter applications.
- Composite Materials:Engineered polymer-biological hybrids or surface-modified synthetics seeking optimized thrombogenicity and durability profiles.
Procurement security favors Bovine Pericardium; innovation investment flows toward Polypropylene.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for aortic valve replacement devices, with integrated delivery networks and academic medical centers filtering supplier access through bundled reimbursement contracts and outcomes-based selection criteria.
United States
FDA label expansions for intermediate-risk TAVI patients drive procedural volume growth in hospital cardiac units. The Centers for Medicare & Medicaid Services reimbursement pathways enable catheterization lab infrastructure investment. Cleveland Clinic and Mayo Clinic anchor structural heart program development, training interventional cardiologists for complex valve deployments.
Germany
EMA MDR harmonization streamlines conformity assessment for established device categories, reducing redundant testing burdens. Germany's statutory health insurance system covers TAVI procedures across risk stratifications. Berlin and Munich academic medical centers integrate polymer-based leaflet feasibility trials into clinical research programs.
Japan
PMDA distinct clinical data requirements filter multinational firm market entry, creating first-mover advantages for localized commercial infrastructure. Japan's aging population exceeds global averages for aortic stenosis prevalence. Tokyo and Osaka cardiac centers scale hybrid operating suites combining surgical backup with transcatheter deployment capabilities.
China
NMPA regulatory pathways for Class III cardiovascular implants mandate domestic clinical trials, extending market access timelines for foreign manufacturers. China's hospital tier system concentrates advanced cardiac procedures in tertiary facilities. Shanghai and Beijing medical centers pioneer robotic-assisted surgical valve replacement through port access techniques.
Australia
TGA approval alignment with FDA and EMA standards facilitates parallel market entry for multinational device portfolios. Australia's public hospital procurement consolidates purchasing through state health departments. Sydney and Melbourne cardiac institutes participate in international transcatheter valve registries, contributing real-world performance data.
Aortic Valve Replacement Devices Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidation concentrates among transcatheter platform innovators with integrated imaging-navigation capabilities, while mid-scale surgical valve manufacturers defend position through durability validation and long-term hemodynamic data. Strategic archetypes span catheter-engineering specialists, tissue-sourcing integrators, and convergent imaging-technology developers. Dominant competitive moves include backward integration into bovine pericardium supply chains and technology licensing partnerships for robotic deployment systems.
Among United States-based innovators, Edwards Lifesciences Corporation and Medtronic exemplify the scale-driven archetype with sustained investment in next-generation leaflet materials and global manufacturing footprint. Abbott Laboratories occupies a position spanning repair and replacement technologies within the structural heart portfolio tier. These three entities anchor competitive dynamics through differential emphasis on transcatheter delivery platform advancement, surgical valve durability validation, and convergent imaging-integration capabilities.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| LivaNova PLC |
| Artivion, Inc |
| JenaValve Technology Inc |
| Venus MedTech HangZhou Inc |
| Braile Biomedica Industry, Commerce and Representations Ltd |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Argentina and Australia abattoir networks for bovine pericardium determines both three-tier pricing spreads across premium, standard, and economy device tiers and the elongated supply chain shape tethered to veterinary health regulations and export licensing regimes.
Pricing Analysis
Cost-plus contracts with raw material indexation to cattle futures and processing labor rates dominate manufacturer-supplier agreements. Price differentiation rests on FDA premarket approval tier and ISO 5840 certification status, with premium tiers commanding substantial spreads for extended fatigue testing documentation. Pricing pressure stems from hospital procurement committee unbundling of device selection from service contracts. Integrated delivery networks exhibit lowest price sensitivity; standalone cardiac catheterization labs face acute margin compression.
Supply Chain Analysis
Export-control regimes for processed biological tissues under CITES and national veterinary health statutes limit cross-border flows of bovine pericardium. Manufacturing concentrates in United States, Ireland, and Singapore facilities proximate to major hospital markets. Raw material dependencies encompass cross-linked bovine tissue, nickel-titanium alloys for stent frames, and catheter delivery system polymers. Single-source vulnerability pervades the abattoir processing layer. Distribution runs through manufacturer-direct sales forces to hospital purchasing committees and group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aortic valve replacement devices market functions as a service-attach opportunity where technical training and outcomes reporting commitments expand faster than hardware revenue as hospital procurement committees demand comprehensive episode-of-care partnerships.
For Market Incumbents: Build a data moat through proprietary transcatheter valve registries capturing longitudinal hemodynamic performance. Backward integration into bovine pericardium supply chains secures batch consistency against Argentine veterinary export restrictions. Investment in ISO 5840 fatigue testing infrastructure creates certification barriers against emerging polymer-based competitors. For New Entrants and Emerging Players: Establish a beachhead in Japan's PMDA pathway where distinct clinical data requirements filter multinational presence and create first-mover advantages for localized partnerships. Polymer-based leaflet materials offer the most penetrable white-space as German and Japanese academic medical centers pioneer feasibility trials. A go-to-market angle centered on eliminating biological sourcing variability resonates with procurement committees facing supply concentration risk. For Investors and Strategic Acquirers: FDA label expansion into asymptomatic patient categories reshapes the acquisition landscape toward transcatheter platform innovators with integrated imaging-navigation capabilities. Long-term viability across a 5-10 year window favors firms with convergent robotic catheter guidance and computational modeling competencies. The signal to watch is CMS reimbursement decisions for outpatient TAVI site-of-service expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Extended follow-up data requirements stretch development timelines and inflate trial costs for novel designs. |
| CE Marking Pathway | EMA MDR Article 117 notified body involvement extends market access timelines for iterative modifications. |
| Hospital System Partnership | Sole-source arrangements contingent upon comprehensive training and outcomes reporting concentrate negotiating leverage. |
| Software Companion Development | Intra-procedural CT planning integration with robotic catheter guidance enables precision deployment in complex anatomies. |
| Reimbursement Strategy | Bundled payment models for complete episode-of-care management incentivize expanded technical support services. |
Methodological Framework
The analysis maps transcatheter delivery platforms, surgical valve portfolios, and polymer-based leaflet innovations, each validated through interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews combined with secondary validation from FDA PMA filings, EMA MDR submissions, CMS reimbursement databases, and ISO 5840 testing protocols. Bottom-up device shipment modeling and top-down hospital procedural volume estimates triangulate market sizing.
Assumptions held fixed include FDA and EMA regulatory frameworks, Japan PMDA clinical data requirements, and ISO 5840 cardiovascular implant standards; varied assumptions encompass TAVI indication label expansions, polymer leaflet fatigue resistance validation, and reimbursement pathway revisions across the projection horizon. Segmentation dimensions encompass device type, delivery mode, material composition, and end-user facility tier. CAGRs derive from procedural volume trajectories and average selling price evolution. Industry-specific inputs include catheterization lab capacity buildout rates and fellowship training pipeline output.
Stress conditions across bovine pericardium supply disruptions, FDA premarket approval timeline extensions, and CMS reimbursement rate adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and hospital infrastructure investment continuity. Material shifts in EMA MDR enforcement intensity or major veterinary disease outbreaks in Argentina would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Heart Closure Devices Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market