
 Continuous Bladder Irrigation Devices Market | 2026-2036
Continuous Bladder Irrigation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Bladder Irrigation Devices Market Analytics
Modular irrigation set configurations is decoupling hardware from disposable consumables, giving procurement departments flexibility to source components separately. B Braun Melsungen AG leverages its sterile manufacturing footprint to anchor European hospital supply contracts. Teleflex Incorporated competes through specialized triple-lumen catheter designs that integrate with multiple pump platforms. Cardinal Health Inc controls distribution scale across North American integrated delivery networks, sustaining volume leadership in gravity-fed system replenishment.
Continuous bladder irrigation devices are closed or open catheter systems that deliver sterile irrigant solution into the bladder via gravity or electromechanical pumping, typically operating at flow rates between 40-60 drops per minute to maintain catheter patency and prevent clot retention following urological surgery. These systems serve primarily to flush blood clots and debris from the bladder after transurethral resection of the prostate or bladder tumor procedures, reducing the risk of catheter obstruction and subsequent complications. Pump-driven systems are capturing margin pools through premium pricing of electromechanical flow control, while smart sensor-enabled devices represent the fastest-growing technology segment as wireless monitoring capabilities expand into outpatient settings. Gravity-fed systems remain the mature volume base in cost-sensitive clinics, though manual systems face displacement pressure from automated alternatives in hospital environments.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa irrigation systems entering European markets. Japan's PMDA maintains distinct pharmaceutical and medical device agency pathways that foreign manufacturers must navigate for market access, creating compliance complexity that favors established regional registrants. Stakeholders must monitor how evolving cybersecurity guidance for connected pump systems reshapes product development priorities and regulatory submission strategies across jurisdictions.
Market Dynamics
Closed-system irrigation architectures are displacing open gravity-fed configurations as tertiary hospitals prioritize catheter-associated urinary tract infection reduction, forcing manufacturers to revalidate entire product lines under stricter sterility assurance protocols.
Growth Catalysts
- Postoperative care expansion:Tertiary hospitals in the United States, Germany, and Japan are scaling dedicated urological recovery units that mandate continuous irrigation protocols.
- FDA 510(k) pathway acceleration:Streamlined premarket notification reviews for urological devices are compressing innovation-to-commercialization timelines for electromechanical pump systems.
- Aging demographic procedural volumes:Transurethral resection of the prostate and bladder tumor interventions are rising in populations over 65 across developed markets.
Market Restraints
- Medical-grade polymer cost volatility:Specialized PVC and silicone formulations for triple-lumen catheter construction face feedstock price instability from petrochemical supply disruptions.
- EU MDR clinical evidence burden:Class IIa irrigation systems now require expanded post-market surveillance documentation that extends European market entry timelines.
- Gravity-fed substitution resistance:Cost-sensitive outpatient clinics retain manual irrigation workflows that limit premium pump penetration.
Strategic Opportunities
- Ambulatory surgical center penetration:Same-day discharge protocols in the United States are creating demand for portable, battery-operated irrigation pumps.
- Smart sensor integration:Wireless flow monitoring and clot detection algorithms are converging with electromechanical platforms to enable remote patient surveillance.
- Japan PMDA harmonization pathways:Streamlined pharmaceutical and medical device agency registration for foreign manufacturers with existing FDA clearance.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 cytotoxicity and sensitization testing for new catheter materials extends product development cycles.
- Legacy EMR integration complexity:Smart irrigation pumps require HL7 FHIR interoperability development that strains hospital IT resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Bladder Irrigation Devices Market |
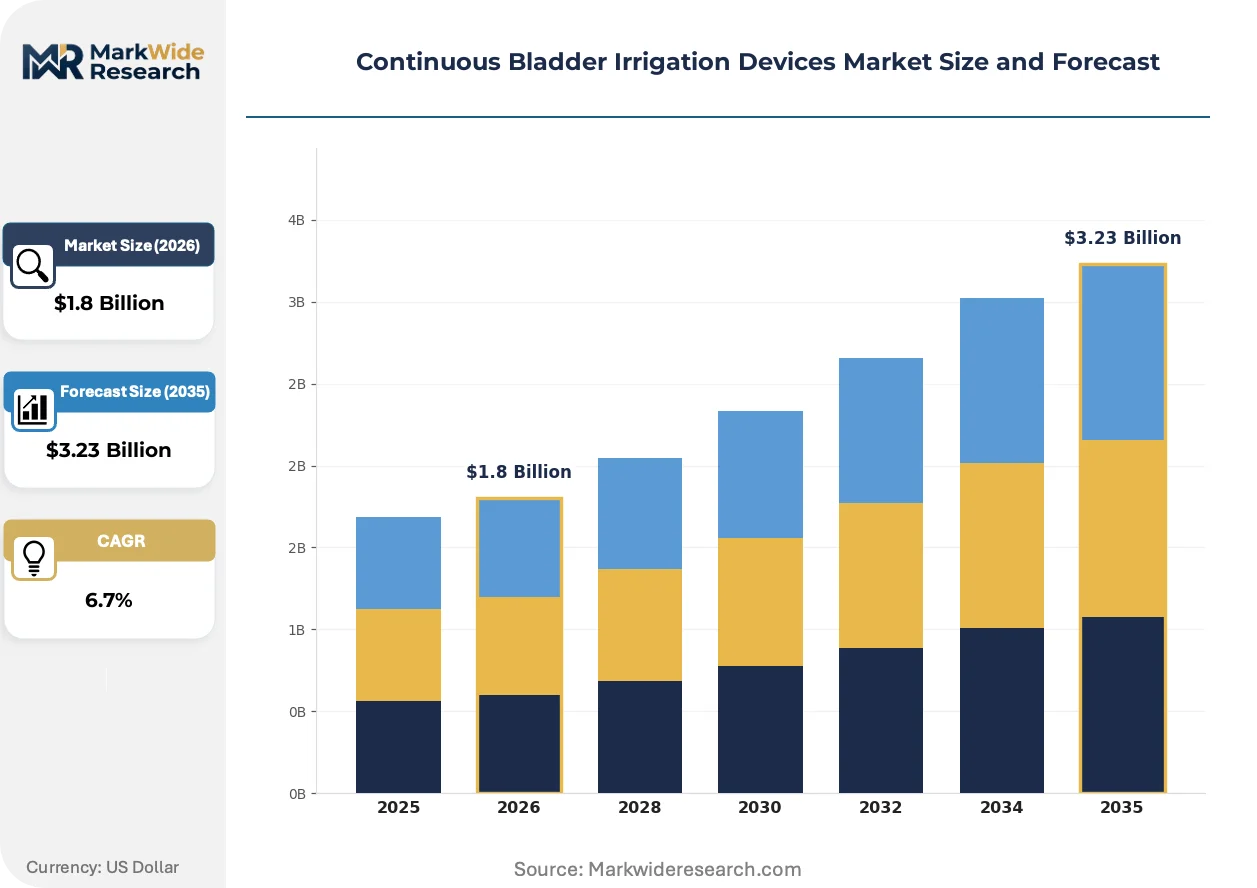
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity-fed Systems, Pump-driven Systems, Wall-mounted Systems, Portable Systems Technology: Electromechanical, Smart Sensors, Wireless Monitoring, Manual Systems End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Postoperative Care, Infection Control, Urinary Blockage, Hemorrhage Management |
| Companies Covered | Teleflex Incorporated, Hollister Incorporated, Cardinal Health Inc, Sterimed Group, B Braun Melsungen AG, Medline Industries LP, Cook Medical LLC, Angiplast Pvt Ltd, Coloplast AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Bladder Irrigation Devices Market Evolving Landscape
Wireless monitoring capabilities are migrating from critical care into postoperative urology, while regulatory frameworks harden sterility requirements and procurement models fragment across institutional tiers.
Sensor-enabled irrigation pumps with integrated flow-rate telemetry and automated clot-detection algorithms are electrifying competitive differentiation in the hospital segment. Academic medical centers in the United States and Japan are piloting these platforms for same-day discharge protocols. The technology is electrifying margin compression for gravity-fed system manufacturers as electromechanical units capture preference in integrated delivery networks.
The EU Medical Device Regulation's expanded clinical evidence requirements for Class IIa systems are forcing manufacturers to maintain post-market surveillance registries that track device-specific adverse events. European notified bodies have reduced capacity for urological device reviews, creating submission backlogs. German and Swiss hospital procurement departments are responding by demanding pre-submitted MDR technical documentation as a contract qualification prerequisite.
Hospital supply chain departments are unbundling hardware and disposable component purchasing, creating modular sourcing flexibility that fragments supplier relationships. Integrated delivery networks in the United States now run separate RFP processes for electromechanical pump platforms and sterile irrigation sets. This pattern is most visible in multi-hospital systems across the Midwest and Southeast, where standardized form-factor requirements are replacing single-vendor bundled contracts.
Continuous Bladder Irrigation Devices Market Segmentation
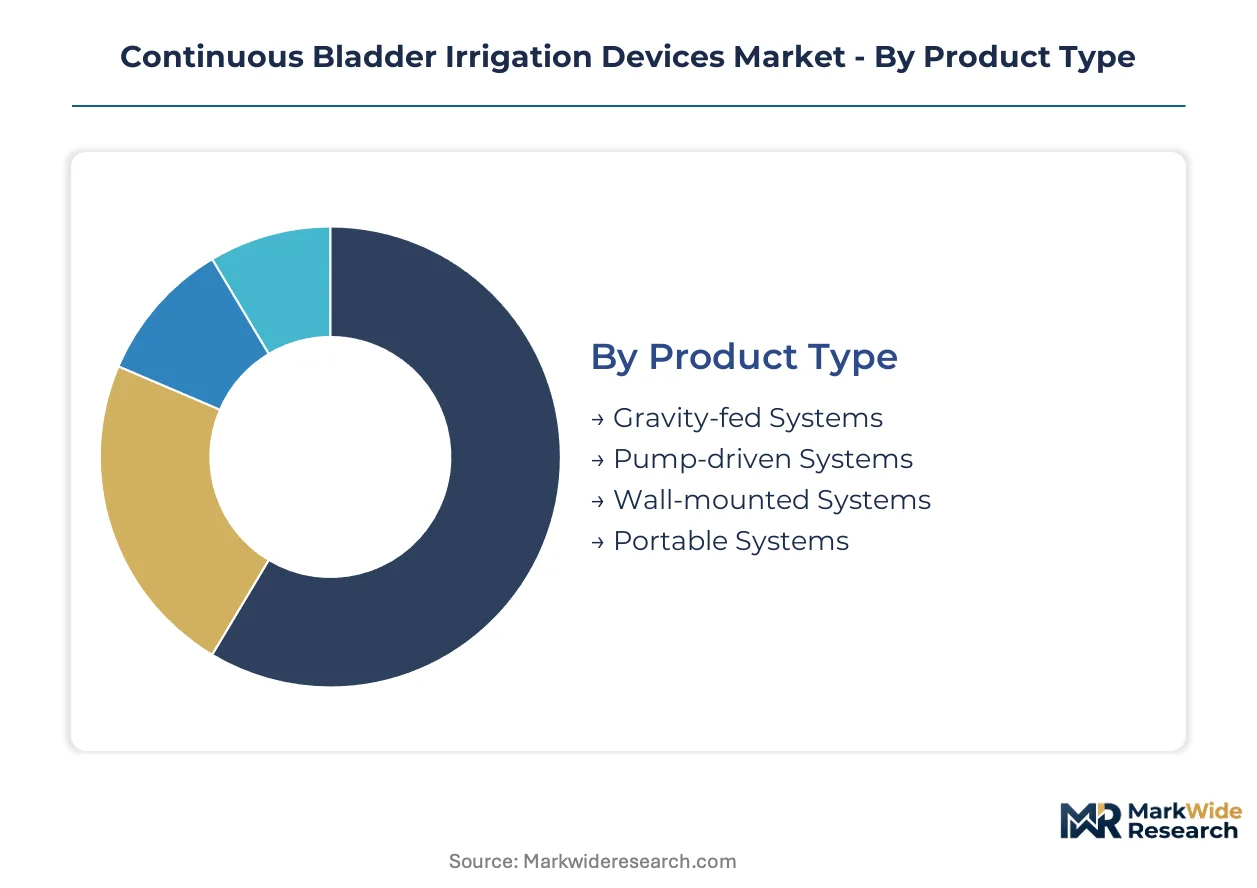
Segmentation in continuous bladder irrigation devices reveals how procurement priorities diverge across care settings and technology readiness. Cost sensitivity, infection control mandates, and discharge velocity requirements create distinct buyer profiles that reshape competitive positioning.
Product Type:
Hospital procurement departments differentiate primarily by capital commitment tolerance versus operational flexibility needs.
- Pump-driven Systems:Electromechanical flow control units deliver precise 40-60 drops per minute irrigation with automated pressure regulation. Tertiary hospitals in the United States prioritize these systems for transurethral resection recovery units where catheter patency automation reduces nursing labor intensity.
- Gravity-fed Systems:Open or closed sterile irrigation sets rely on height differential and manual roller clamp adjustment without electrical components. Cost-sensitive outpatient clinics in Germany retain these configurations where reimbursement constraints favor minimal capital expenditure.
- Wall-mounted Systems:Fixed installation units integrate with hospital utility infrastructure for permanent urology suite deployment.
- Portable Systems:Battery-operated mobile units enable intra-hospital transport and ambulatory surgical center adoption.
Pump-driven systems lead volumes today; portable systems are gaining share fastest.
Technology:
Technology selection tracks institutional digital maturity and remote monitoring infrastructure investment cycles.
- Smart Sensors:Integrated flow-rate telemetry and clot-detection algorithms enable automated alarm triggers and predictive maintenance scheduling. Academic medical centers in Japan pilot these platforms for same-day discharge protocols where remote surveillance reduces readmission exposure.
- Wireless Monitoring:Bluetooth and Wi-Fi enabled pumps transmit irrigation parameters to central nursing stations and electronic medical records. United States integrated delivery networks prioritize interoperability with existing HL7 FHIR infrastructure.
- Electromechanical:Motor-driven peristaltic or piston pumps with programmable flow profiles and battery backup.
- Manual Systems:Gravity-dependent configurations with no electronic components for lowest-cost deployment.
Electromechanical platforms anchor current revenue; smart sensors are climbing the fastest.
End User:
End-user segmentation reflects acuity levels and reimbursement pathway differentiation across the care continuum.
- Hospitals:Tertiary and community hospitals command the largest installed base with dedicated urology departments performing transurethral resection procedures. Postoperative care expansion in the United States, Germany, and Japan sustains closed-system irrigation set procurement at scale.
- Clinics:Outpatient urology practices and ambulatory surgical centers prioritize portable, battery-operated pumps for same-day discharge workflows. United States Medicare reimbursement shifts toward site-neutral payment favoring lower-acuity settings.
- Home Care:Patient or caregiver-administered irrigation for chronic catheter management.
- Rehabilitation Centers:Post-acute facilities managing neurogenic bladder and long-term catheter dependence.
Hospitals dominate absolute unit demand; clinics are expanding most quickly.
Application:
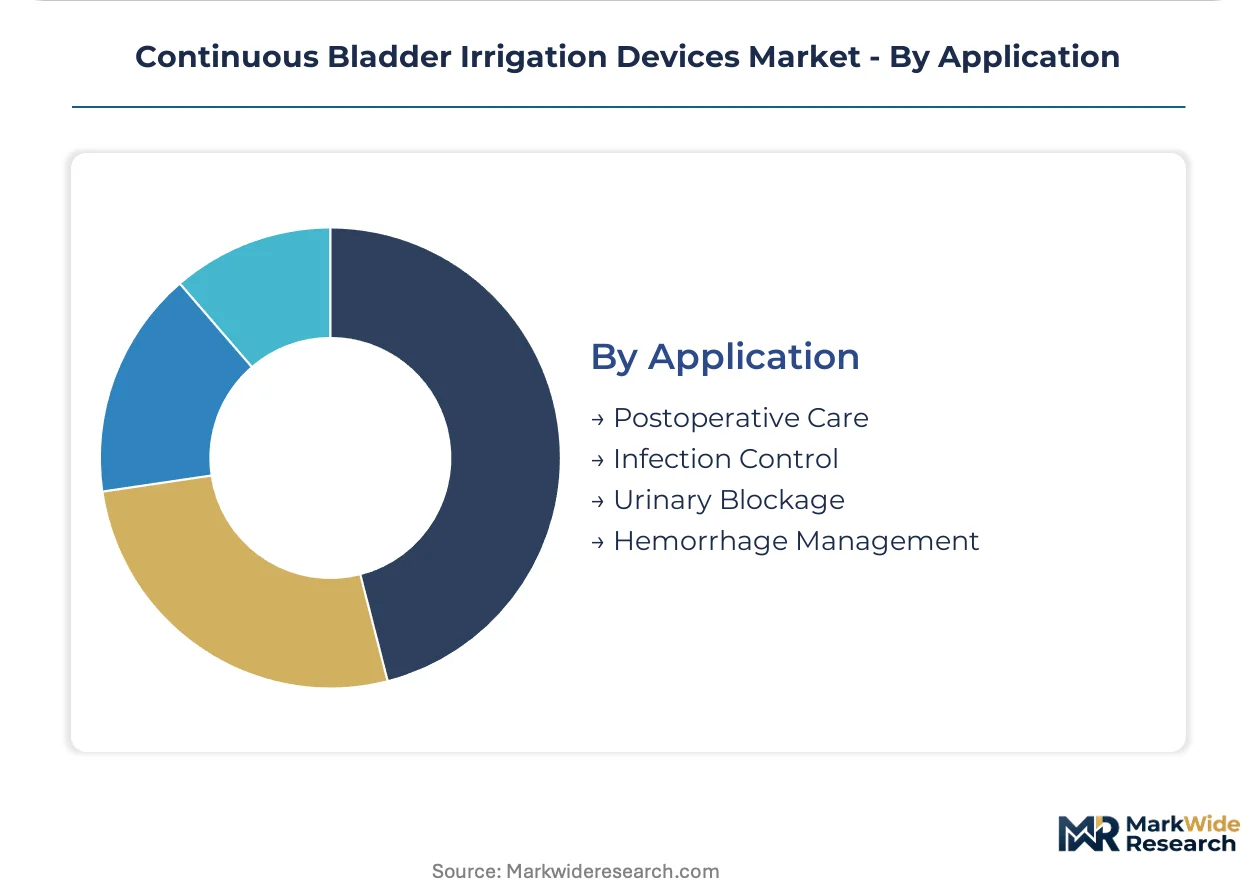
Application segmentation aligns with procedural reimbursement codes and complication risk stratification protocols.
- Postoperative Care:Continuous irrigation following transurethral resection of prostate or bladder tumor procedures to prevent clot retention and catheter obstruction. Aging demographic procedural volumes in developed markets sustain this segment's centrality.
- Infection Control:Closed-system architectures with sterile barrier properties reduce catheter-associated urinary tract infection incidence. FDA and EU MDR sterility assurance requirements are forcing product line revalidation toward this application.
- Urinary Blockage:Irrigation to relieve obstruction from hematuria, sediment, or mucus plugging.
- Hemorrhage Management:High-volume irrigation to dilute blood and maintain visibility during active bleeding episodes.
Postoperative care commands the largest addressable need; infection control is steepening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The continuous bladder irrigation devices industry traces its commercial scale to post-World War II urological surgery expansion in the United States and Germany, where closed-system catheter designs first achieved regulatory validation for postoperative care protocols.
United States
Tertiary hospitals in the Midwest and Southeast are scaling dedicated urological recovery units that mandate continuous irrigation protocols. FDA 510(k) premarket notification pathways for urological devices are compressing innovation-to-commercialization timelines for electromechanical pump systems. Academic medical centers in Boston and the Research Triangle pilot smart sensor-enabled platforms for same-day discharge workflows.
Germany
Hospital procurement departments in Bavaria and North Rhine-Westphalia are unbundling hardware and disposable component purchasing to create modular sourcing flexibility. EU Medical Device Regulation clinical evidence requirements for Class IIa irrigation systems are extending market entry timelines and forcing post-market surveillance registry maintenance. Sterile manufacturing clusters around Melsungen anchor European supply contracts for closed-system irrigation sets.
Japan
Aging populations over 65 are driving transurethral resection procedural volumes in Kanto and Kansai regions. PMDA maintains distinct pharmaceutical and medical device agency pathways that foreign manufacturers must navigate for market access, creating compliance complexity favoring established regional registrants. Tokyo academic medical centers are piloting wireless monitoring capabilities for remote patient surveillance in outpatient settings.
United Kingdom
Integrated care systems in London and the Midlands are consolidating urology service lines that standardize irrigation protocols across hospital networks. MHRA post-Brexit regulatory frameworks are maintaining alignment with EU MDR sterility assurance standards while streamlining domestic market entry. NHS procurement frameworks are demanding pre-submitted technical documentation as contract qualification prerequisites.
India
Private hospital chains in Maharashtra and Karnataka are expanding urology departments to capture rising procedural volumes among aging urban populations. CDSCO medical device regulations are tightening quality standards for imported irrigation systems while accelerating domestic manufacturing incentives. Medical device manufacturing clusters in Gujarat are scaling sterile component production for regional supply contracts.
Continuous Bladder Irrigation Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical device conglomerates with sterile manufacturing footprints and distribution scale across integrated delivery networks. Market concentration reflects procurement consolidation among hospital systems favoring multi-product vendors with regulatory compliance infrastructure across FDA, EU MDR, and PMDA jurisdictions. Three archetypes dominate: sterile manufacturing specialists with captive polymer processing, distribution-integrated conglomerates with IDN contracting scale, and catheter design specialists with triple-lumen platform versatility. Competitive moves center on modular unbundling of hardware and consumables and smart sensor integration for wireless telemetry capabilities.
Among diversified medical device conglomerates, B Braun Melsungen AG and Cardinal Health Inc exemplify contrasting scale advantages. Teleflex Incorporated occupies a position as a catheter design specialist with platform-agnostic pump integration capabilities. These three anchors illustrate how sterile manufacturing depth, distribution infrastructure, and specialized design expertise respectively command procurement preference across European, North American, and technology-advanced hospital segments.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Hollister Incorporated |
| Cardinal Health Inc |
| Sterimed Group |
| B Braun Melsungen AG |
| Medline Industries LP |
| Cook Medical LLC |
| Angiplast Pvt Ltd |
| Coloplast AS |
| Others |
Value Network & Pricing Analysis
Medical-grade polymer feedstock costs for triple-lumen catheter construction flow from petrochemical suppliers through sterile manufacturing clusters in Germany and the United States, ultimately stratifying into three-tier pricing structures across premium electromechanical pumps, standard closed-system sets, and economy gravity-fed configurations that cost-sensitive outpatient clinics in Germany favor.
Pricing Analysis
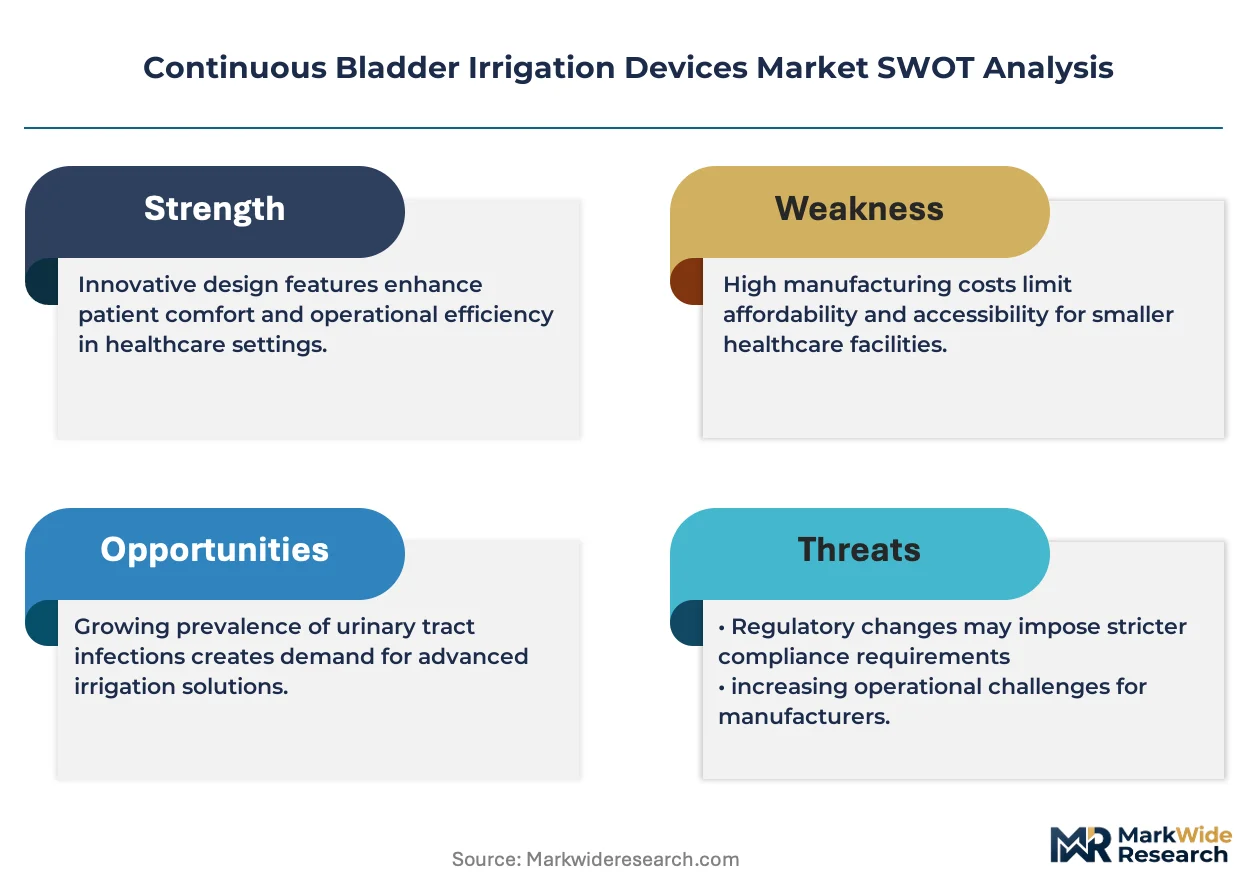
Three-tier pricing structure across premium, standard, and economy levels separates pump-driven systems with smart sensor integration from closed sterile sets and basic gravity-fed alternatives. Price differentiation hinges on FDA 510(k) clearance tier and sterile manufacturing certification grade, with academic medical centers absorbing premium tiers while ambulatory surgical centers drive cost compression in portable segments. Pricing pressure stems from EU MDR clinical evidence burdens that extend development timelines and inflate compliance overhead. Outpatient clinics exhibit highest price sensitivity; tertiary hospitals with dedicated urology units demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from United States integrated delivery networks and German hospital procurement departments mandate multi-supplier qualification for sterile irrigation sets and electromechanical pump platforms. Geographic supply concentration centers on Germany, the United States, and Switzerland for sterile manufacturing, with Japan anchoring regional assembly for PMDA-compliant devices. Raw material dependencies span medical-grade PVC, silicone formulations, and precision pump motors. Single-source vulnerability in specialized polymer feedstock creates exposure to petrochemical price volatility. Distribution runs through integrated delivery networks in North America and group purchasing organizations in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The continuous bladder irrigation devices market functions as a regulatory compounder where FDA 510(k) pathway acceleration and EU MDR sterility mandates simultaneously compress innovation timelines and elevate compliance barriers that favor incumbents with established multi-jurisdictional infrastructure.
For Market Incumbents: Lock in sterile manufacturing capacity expansion across Melsungen and Bavaria clusters to defend against modular procurement unbundling that fragments supplier relationships. Deepen backward integration into medical-grade polymer processing to offset feedstock volatility threatening margin stability in triple-lumen catheter production. Prioritize HL7 FHIR interoperability investment to secure academic medical center contracts where smart sensor integration determines procurement preference. For New Entrants and Emerging Players: Launch via ambulatory surgical center direct contracts in the United States Midwest and Southeast where site-neutral Medicare reimbursement shifts favor portable pump adoption over hospital-based care. Target battery-operated irrigation platforms for same-day discharge protocols as the most penetrable white space, exploiting incumbent blind spots in outpatient workflow optimization. Pursue Japan PMDA harmonization pathways for foreign manufacturers with existing FDA clearance as regulatory fast-track leverage. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile manufacturing footprints and multi-jurisdictional regulatory infrastructure concentrate among mid-cap specialists lacking distribution scale. Long-term viability over the projection horizon favors acquisition targets with captive polymer processing and established EU MDR technical documentation registries. Watch FDA cybersecurity guidance for connected pump systems as inflection indicator reshaping product development priorities and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks German hospital procurement contracts requiring pre-submitted technical documentation. |
| Hospital System Partnership | Integrated delivery network contracting secures volume replenishment for closed-system irrigation sets. |
| Software Companion Development | HL7 FHIR interoperability enables smart sensor telemetry integration with existing electronic medical records infrastructure. |
| Reimbursement Strategy | Site-neutral Medicare payment alignment captures ambulatory surgical center demand for portable battery-operated pumps. |
| Backward Integration | In-house medical-grade polymer processing insulates margin stability from petrochemical feedstock price volatility. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Data-stream reconciliation across product type, technology readiness, end-user acuity, and application-specific reimbursement pathways shaped the analytical framework over the projection horizon. CAGRs were derived from modeled procedure volume trajectories and technology substitution curves, incorporating aging demographic projections and regulatory pathway velocity as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body capacity constraints and cybersecurity guidance evolution for connected pump systems. Deviation in FDA 510(k) review velocity or polymer feedstock supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
C-Arms Devices Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Brachytherapy Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Cast Removal Devices Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
France Minimally Invasive Surgery Devices Market