
 Nerve Stimulators Market | 2026-2036
Nerve Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Stimulators Market Outlook
Market Context
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape into firms with notified body relationships and those without. Medtronic leverages its vertical integration across implantable pulse generators and leads to sustain manufacturing scale advantages. Boston Scientific Corporation anchors its position through specialized product portfolios in spinal cord stimulation, while Abbott competes via diversified neuromodulation platforms spanning chronic pain and movement disorders.
Technical Definition and Structural Segments
Nerve stimulators are electrotherapeutic devices that deliver controlled electrical, magnetic, optical, or ultrasound energy to modulate neural activity, typically operating at frequencies between 2-120 Hz with pulse widths of 60-450 microseconds for therapeutic effect. These systems treat chronic pain, neuropathy, depression, and stroke rehabilitation by interrupting or altering aberrant neural signaling pathways. Implantable devices command premium pricing and margin pools due to surgical placement requirements and long-term therapy management, while transcutaneous systems extend access through lower-cost homecare deployment. Electrical stimulation technology dominates current revenue, though magnetic stimulation is gaining traction in treatment-resistant depression applications.
Regulatory Framework and Outlook
FDA premarket notification and premarket approval pathways govern US market entry, while the EU MDR and CE marking framework reshape European commercialization timelines and clinical evidence requirements. Japan's PMDA and its QMS ordinance add another certification layer for Asia-Pacific access, with all three bodies intensifying scrutiny of cybersecurity and biocompatibility standards for connected implantable devices. Stakeholders must monitor evolving reimbursement coding decisions by Medicare and national health technology assessment bodies, as these determinations directly gate patient access and manufacturer revenue realization across key markets.
Market Dynamics
Implantable pulse generator miniaturization is compressing surgical footprints while expanding candidate pools for neuromodulation therapy, forcing manufacturers to recalibrate R&D roadmaps and manufacturing scale simultaneously.
Growth Catalysts
- EU MDR compliance frameworks:Stricter clinical evidence requirements under the Medical Device Regulation are filtering out marginal competitors, concentrating market share among firms with established notified body relationships and accelerating quality bar elevation across the sector.
- Chronic pain management clinics:Specialized neuromodulation centers in the United States, Germany, and Japan are expanding implantable device adoption through dedicated surgical teams and standardized patient selection protocols.
- Closed-loop stimulation algorithms:Real-time neural feedback systems are improving therapeutic consistency and reducing adverse events, broadening physician willingness to recommend devices for complex neuropathy cases.
Market Restraints
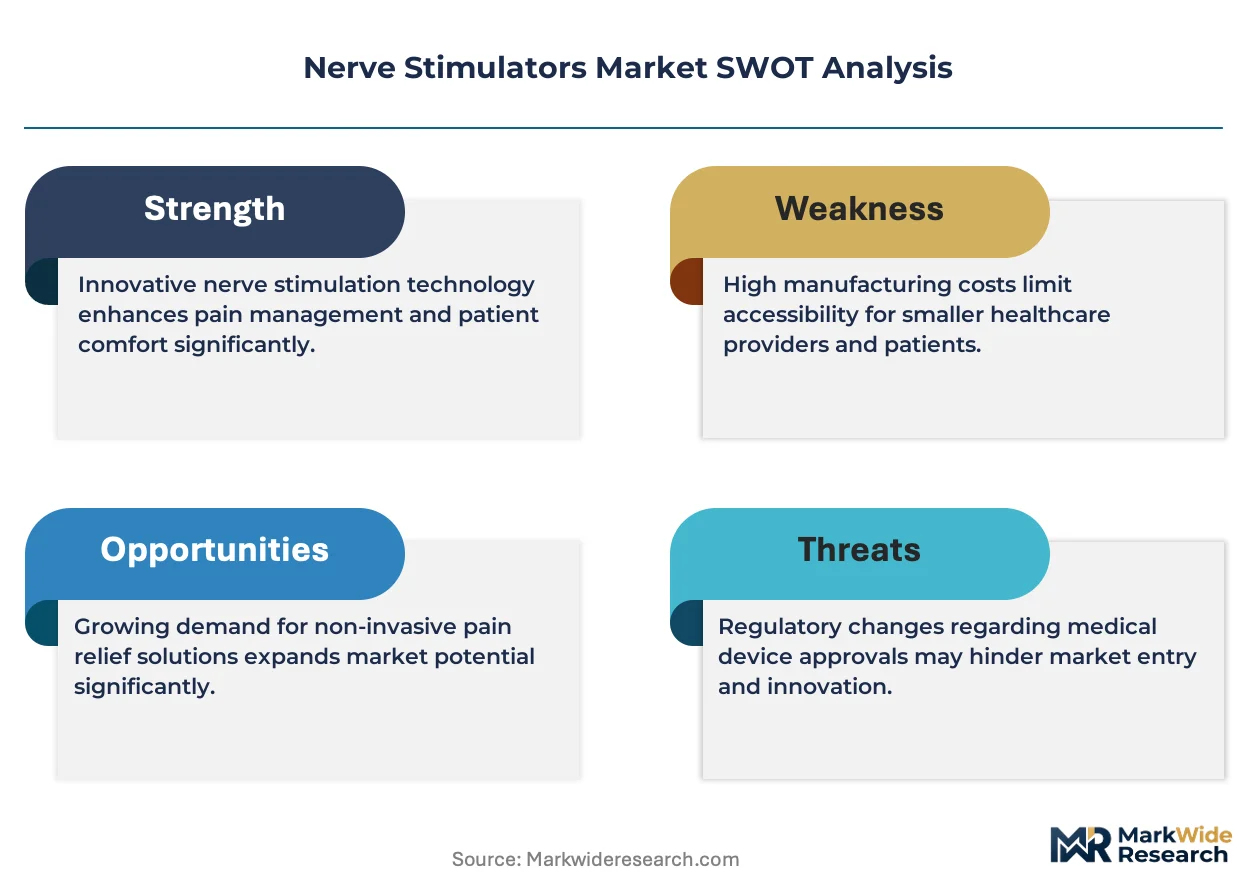
- Biocompatible lead materials:Platinum-iridium and specialized polymer feedstock costs fluctuate with precious metals markets, compressing gross margins on legacy product lines unable to pass through input volatility.
- Notified body capacity:EU MDR certification backlogs extend commercialization timelines by 12-18 months for firms without pre-existing technical documentation packages, advantaging incumbents with regulatory reserves.
- Transcutaneous alternatives:Non-invasive TENS and peripheral nerve stimulation devices capture price-sensitive segments and mild-to-moderate pain cases, capping premium pricing power for implantable systems at the market's lower boundary.
Strategic Opportunities
- India's neurology infrastructure:Underdeveloped chronic pain management access in tier-2 and tier-3 cities creates first-mover potential for transcutaneous device manufacturers establishing local distribution partnerships.
- Magnetic stimulation convergence:Transcranial magnetic stimulation platforms for treatment-resistant depression represent a parallel revenue stream requiring minimal surgical infrastructure, appealing to psychiatric service lines.
- Japan's PMDA fast-track pathways:Sakigake designation and conditional early approval mechanisms for breakthrough devices compress regulatory timelines, rewarding firms with robust Japanese clinical trial networks.
Industry Challenges
- Neurostimulation programming specialists:Shortage of trained clinical specialists capable of optimizing device parameters post-implantation limits patient outcomes and generates downstream support costs for manufacturers.
- Legacy EHR integration:Proprietary data formats from implantable devices resist seamless integration with hospital electronic health record systems, complicating remote monitoring deployment and reimbursement documentation.
- Cybersecurity certification timelines:FDA and PMDA intensified scrutiny of connected device vulnerabilities extends premarket review cycles, requiring dedicated security engineering resources unfamiliar to traditional hardware firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Stimulators Market |
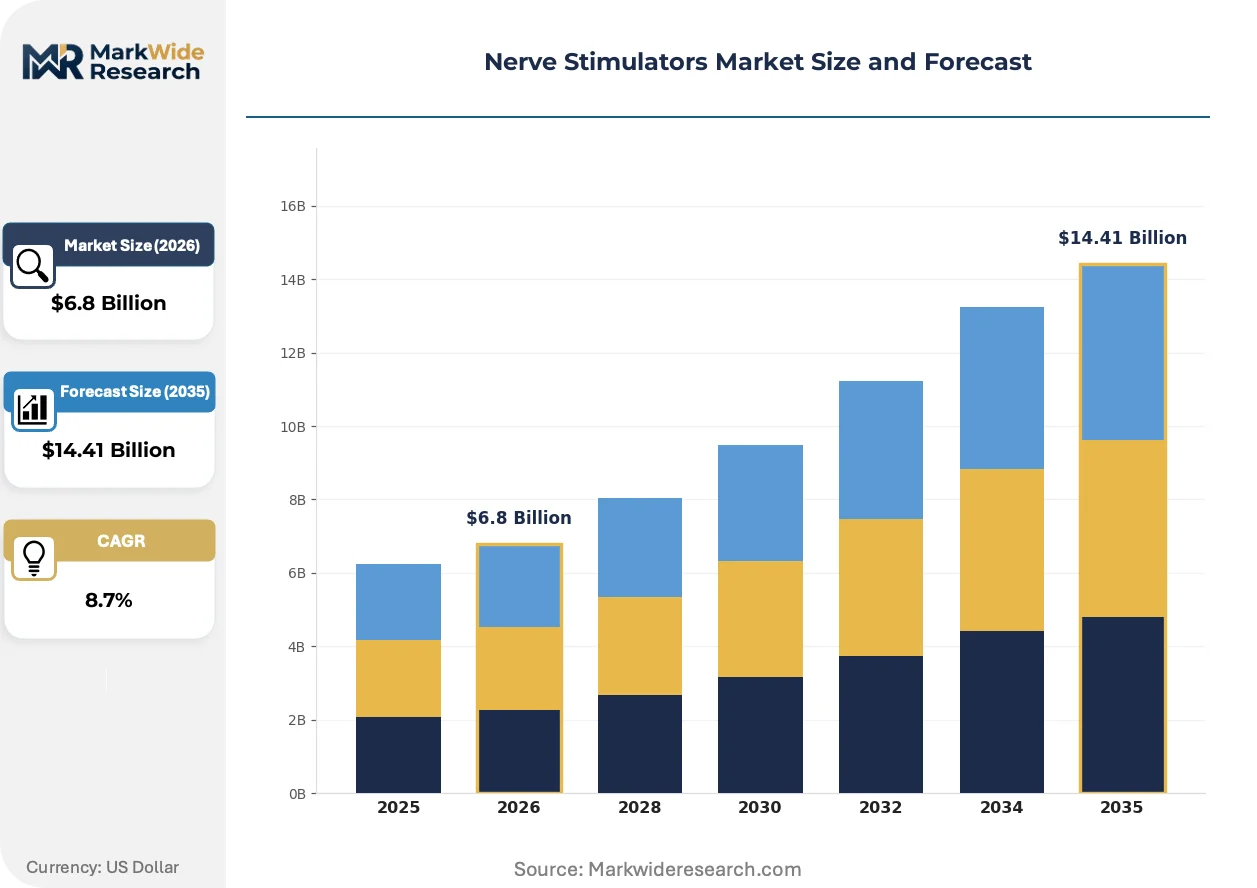
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcutaneous, Implantable, Peripheral, Central Therapy Area: Chronic Pain, Neuropathy, Depression, Stroke Rehabilitation End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Technology: Electrical Stimulation, Magnetic Stimulation, Optical Stimulation, Ultrasound Stimulation |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, LivaNova PLC, Nevro Corporation, NeuroPace, ElectroCore, Bioventus, B. Braun Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Stimulators Market Strategic Shifts
Digital health convergence is dissolving boundaries between implantable hardware and software-enabled therapy management, compelling manufacturers to build capabilities outside their historical engineering core.
Directional lead technology is decomposing the traditional spinal cord stimulation paradigm of simple dorsal column activation. Pain management specialists in the United States are adopting 32-electrode and 64-electrode arrays capable of targeted lateral branch stimulation within 18 months of commercial availability. This electrode density expansion is decomposing the one-size-fits-all programming model into patient-specific field steering protocols that compress trial-to-implant conversion timelines.
Japan's PMDA QMS ordinance amendments are tightening post-market surveillance requirements for active implantable medical devices. Manufacturers must now submit periodic safety update reports with real-world performance data, increasing compliance infrastructure costs but simultaneously building longitudinal evidence pools that support premium reimbursement negotiations. Implantable pulse generator segments with wireless connectivity features face the steepest documentation burdens under these revised frameworks.
After-sales service unbundling is fragmenting traditional device-vendor relationships in German and Japanese hospital systems. Procurement departments now separately negotiate hardware acquisition, programming support, and remote monitoring subscriptions, compressing bundled margin pools and forcing manufacturers to demonstrate standalone value at each contract layer. This unbundling is most pronounced in university hospital networks with centralized purchasing authority and dedicated neuromodulation service lines.
Nerve Stimulators Market Segmentation
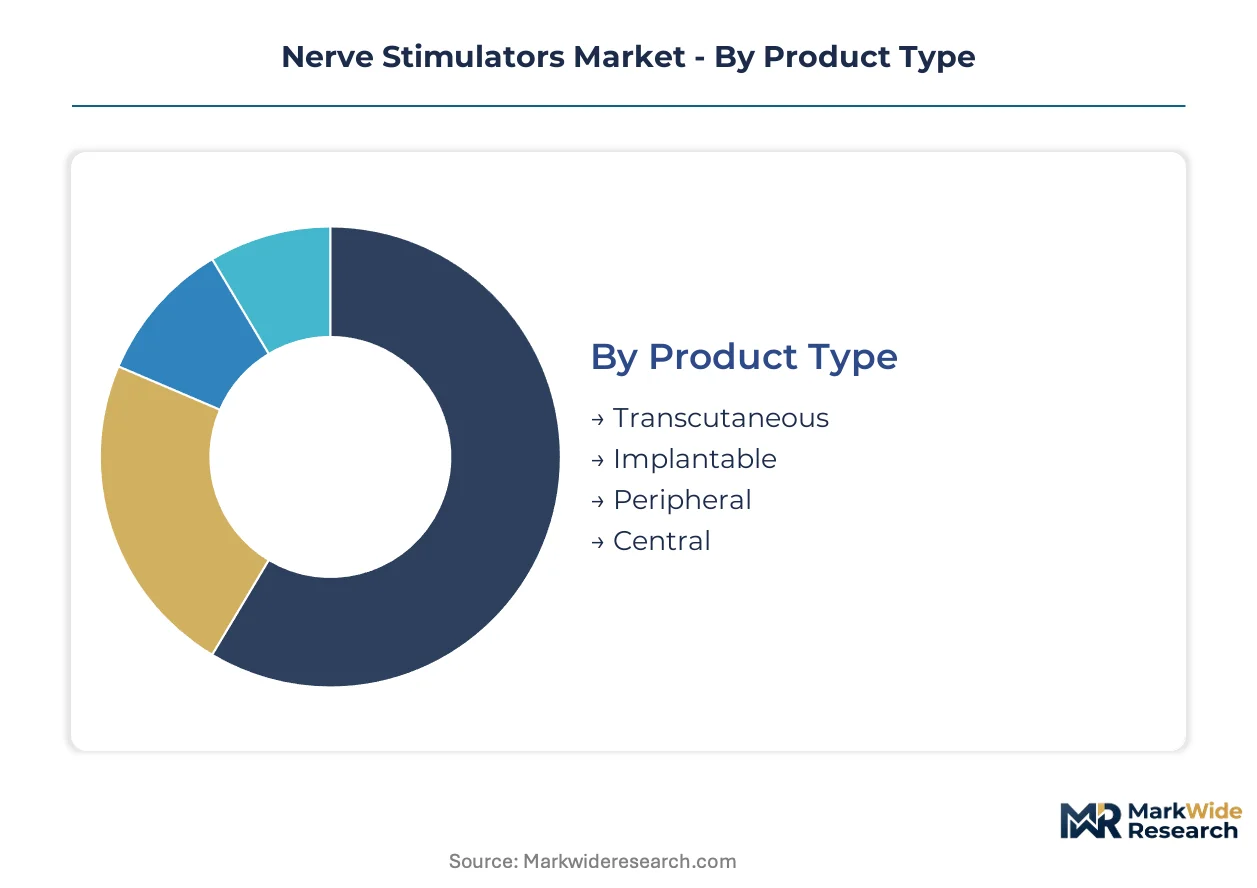
Nerve stimulators traverse sharply divergent commercial pathways depending on invasiveness and reimbursement coding. Product type and therapy area determine whether devices flow through hospital surgical suites, specialized neuromodulation clinics, or direct-to-patient retail channels.
Product Type:
Implantable systems command hospital procurement committees and specialized surgical centers, while transcutaneous variants distribute through durable medical equipment suppliers and pharmacy retail chains.
- Implantable:Pulse generators and lead systems requiring surgical placement under fluoroscopic guidance. United States academic medical centers with dedicated neuromodulation service lines concentrate demand, driven by Medicare reimbursement codes for spinal cord and deep brain stimulation.
- Transcutaneous:External TENS and NMES devices delivering surface electrical stimulation. German homecare providers and Japanese rehabilitation clinics are expanding procurement volumes for post-surgical pain management without implantation risks.
- Peripheral:Targeted nerve field stimulation systems for localized pain syndromes. Pain management specialists in ambulatory surgical centers favor these for focal neuropathy cases.
- Central:Cranial and vagus nerve stimulation platforms. Psychiatric service lines in university hospitals deploy these for treatment-resistant depression protocols.
Implantable devices dominate installed base value. Transcutaneous systems are where volume expansion concentrates.
Therapy Area:
Reimbursement intensity varies threefold across indications, with chronic pain commanding premium codes and stroke rehabilitation facing coverage gaps in multiple national health systems.
- Chronic Pain:Failed back surgery syndrome and complex regional pain syndrome drive spinal cord stimulation volumes. United States pain management clinics with dedicated implanting physicians generate the highest procedure density per center.
- Neuropathy:Diabetic peripheral neuropathy and chemotherapy-induced neural damage. Japanese diabetes centers are integrating peripheral nerve stimulation into multidisciplinary care pathways.
- Depression:Treatment-resistant major depressive disorder and obsessive-compulsive disorder. German psychiatric hospitals are adopting transcranial magnetic stimulation as an alternative to electroconvulsive therapy.
- Stroke Rehabilitation:Motor recovery and spasticity reduction through functional electrical stimulation. Rehabilitation centers in tier-2 Indian cities are piloting low-cost transcutaneous systems for post-stroke care.
Chronic pain captures the dominant revenue share. Depression applications are climbing the fastest.
End User:
Procurement authority is fragmenting as German and Japanese hospital systems unbundle hardware acquisition from programming support and remote monitoring subscriptions.
- Hospitals:Academic medical centers with electrophysiology labs and dedicated neuromodulation suites. United States university hospital networks with centralized purchasing authority negotiate multi-year device contracts.
- Clinics:Specialized chronic pain management and neurology outpatient facilities. These centers concentrate implantable device trials and conversions in Germany and Japan.
- Homecare:Post-acute care and long-term therapy management settings. Transcutaneous device utilization is expanding through Japanese home nursing agencies and German rehabilitation networks.
- Rehabilitation Centers:Stroke and spinal cord injury recovery facilities. Indian tier-2 cities are emerging as deployment points for cost-optimized peripheral stimulation systems.
Hospitals anchor capital equipment purchases. Clinics are where patient throughput expansion concentrates.
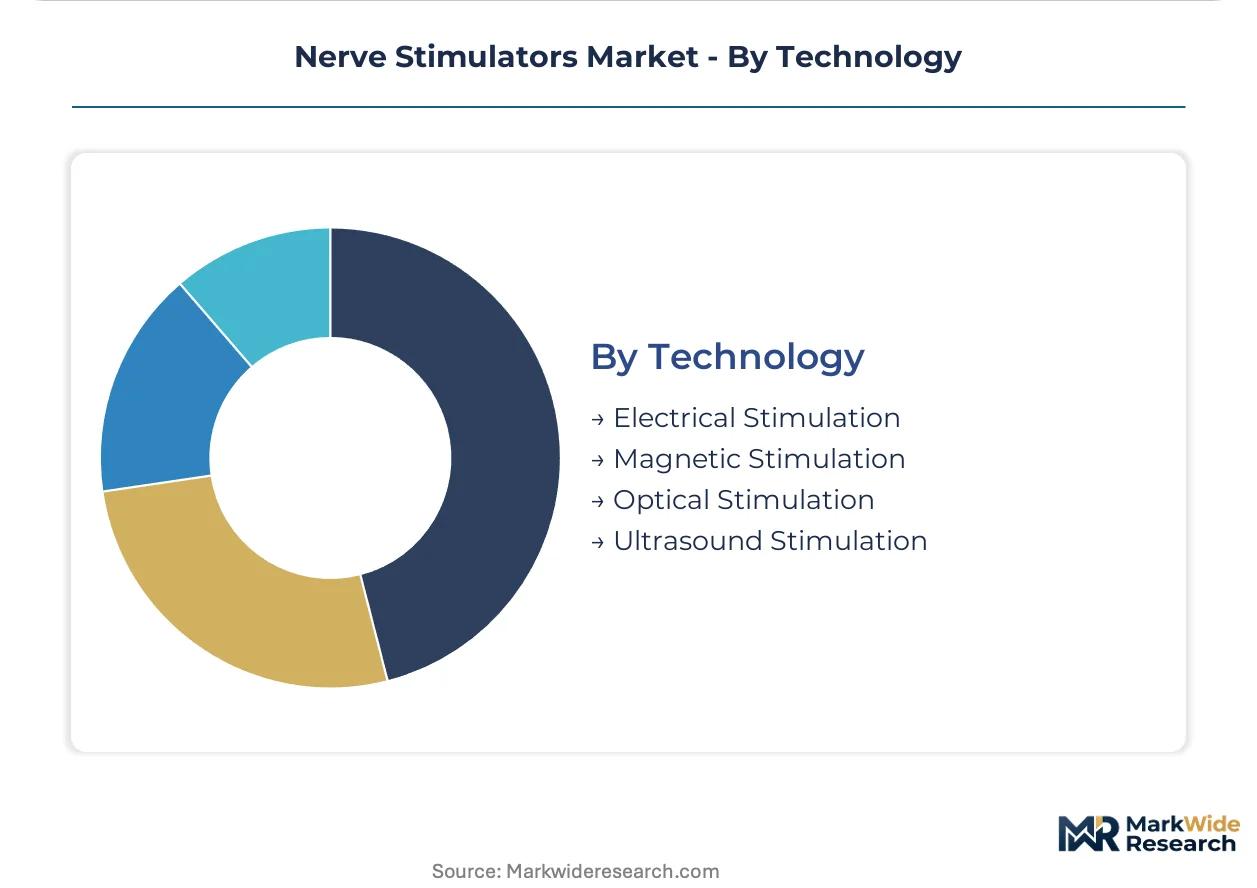
Technology:
Engineering complexity and regulatory evidence requirements create tiered margin structures, with electrical stimulation leveraging decades of clinical data and optical platforms facing biocompatibility validation hurdles.
- Electrical Stimulation:Established waveform delivery through implanted or surface electrodes. FDA premarket approval pathways and EU MDR technical documentation favor incumbents with longitudinal safety databases.
- Magnetic Stimulation:Transcranial magnetic induction for cortical neuromodulation. Psychiatric service lines in the United States and Germany are deploying these for depression protocols without surgical infrastructure requirements.
- Optical Stimulation:Optogenetic and infrared neural modulation. Preclinical and early clinical stages face PMDA and FDA scrutiny of long-term tissue interaction effects.
- Ultrasound Stimulation:Focused acoustic energy for peripheral and central neural targets. Emerging applications in stroke rehabilitation are attracting Japanese research hospital collaborations.
Electrical stimulation dominates commercial revenue. Magnetic platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's dedicated neuromodulation surgical suites anchor United States demand concentration, while Japan's Kobe biomedical manufacturing corridor underwrites Asia-Pacific supply chain integration for implantable pulse generators.
United States
Medicare reimbursement codes for spinal cord and deep brain stimulation drive hospital procurement volumes. FDA premarket approval pathways filter market entry through longitudinal safety databases. Academic medical centers in Minnesota and Massachusetts concentrate implantable device trials through dedicated electrophysiology labs.
Germany
Specialized chronic pain management clinics in Bavaria and North Rhine-Westphalia expand neuromodulation service lines. EU MDR CE marking requirements and notified body relationships reshape commercialization timelines. University hospital networks in Heidelberg and Berlin unbundle hardware acquisition from programming support contracts.
Japan
PMDA QMS ordinance amendments tighten post-market surveillance for active implantable devices. Sakigake designation fast-track pathways compress regulatory timelines for breakthrough neuromodulation platforms. Kobe and Osaka manufacturing clusters integrate precision electronics with biomedical device assembly.
India
Tier-2 and tier-3 city neurology infrastructure gaps create deployment opportunities for transcutaneous systems. CDSCO medical device regulations and quality management system requirements govern import and local manufacturing. Maharashtra and Karnataka rehabilitation centers pilot low-cost peripheral stimulation for post-stroke care.
United Kingdom
NHS England specialized commissioning frameworks gate access to implantable devices for treatment-resistant conditions. MHRA post-Brexit regulatory alignment with EU MDR technical standards extends certification complexity. London and Manchester academic health science centers concentrate deep brain stimulation expertise for movement disorders.
Nerve Stimulators Market Competitive Environment
Listed leaders compete with private specialists across regulatory reserves and notified body relationships. The vendor base stratifies into three tiers: diversified medical technology conglomerates with vertical manufacturing control, mid-cap neuromodulation pure-plays with specialized therapy portfolios, and emerging transcutaneous device manufacturers targeting price-sensitive access expansion. Dominant competitive moves include M&A activity to capture closed-loop algorithm capabilities and strategic partnerships with chronic pain management clinic networks to secure trial-to-implant conversion pathways.
Among diversified medical technology conglomerates, Medtronic, Boston Scientific Corporation, and Abbott exemplify archetypes spanning implantable pulse generator manufacturing through specialized neuromodulation service line partnerships. These entities occupy positions where manufacturing scale advantages intersect with regulatory reserves built across FDA, EU MDR, and PMDA certification frameworks. Their market presence anchors the premium-tier segment where surgical placement requirements and long-term therapy management sustain margin pools unavailable to transcutaneous competitors.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| LivaNova PLC |
| Nevro Corporation |
| NeuroPace |
| ElectroCore |
| Bioventus |
| B. Braun Medical |
| Others |
Value Chain & Pricing Dynamics
Platinum-iridium alloy substitution for pure platinum electrodes is compressing raw material costs while redrawing procurement geography toward Japanese and German metallurgical suppliers, simultaneously elevating pricing power for manufacturers with backward-integrated feedstock relationships.
Pricing Analysis
Volume-discount tiering structures separate academic medical centers with multi-year implantable device contracts from ambulatory surgical centers purchasing single-unit peripheral systems. Three-tier pricing stratifies across premium implantable pulse generators with closed-loop algorithms, standard spinal cord stimulation platforms, and economy transcutaneous TENS units. Pricing pressure stems from German hospital procurement departments unbundling hardware acquisition from programming support, forcing standalone margin demonstration. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement codes, while Indian tier-2 rehabilitation centers face acute budget constraints.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores the criticality of titanium feedstock flows from Russian and Chinese sponge producers to Kobe manufacturing clusters. Implantable pulse generator assembly draws from Japanese precision electronics, German polymer extrusion for lead insulation, and Swiss micro-machining for electrode arrays. Single-source vulnerability concentrates in platinum-group metal refining, where South African and Russian smelters anchor global supply. Distribution runs through specialized neuromodulation distributors in the United States, direct hospital contracts in Germany, and regional medical device wholesalers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated German university hospital networks with centralized purchasing authority, fragmenting traditional vendor relationships and demanding unbundled service pricing.
For Market Incumbents: Compound regulatory reserves across FDA premarket approval, EU MDR notified body relationships, and PMDA QMS certification to erect entry barriers against emerging transcutaneous competitors. Deepen backward integration into platinum-iridium electrode manufacturing to capture margin pools currently flowing to metallurgical suppliers. Prioritize closed-loop algorithm R&D to differentiate from commodity spinal cord stimulation platforms.
For New Entrants and Emerging Players: Differentiate on magnetic stimulation platforms for psychiatric service lines lacking surgical infrastructure, where reimbursement pathways are less entrenched. Target India's tier-2 and tier-3 rehabilitation centers with cost-optimized peripheral nerve stimulation systems. Deploy local distribution partnerships rather than direct sales to navigate CDSCO import complexity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neuromodulation pure-plays possessing FDA-approved spinal cord stimulation portfolios but limited EU MDR transition progress. Five-to-ten year viability hinges on successful migration to closed-loop systems and magnetic stimulation platforms. Monitor PMDA Sakigake designation velocity as an inflection indicator for breakthrough device premium pricing potential.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | CE marking under tightened clinical evidence requirements filters marginal competitors from German hospital procurement. |
| Closed-Loop Algorithm Development | Real-time neural feedback systems improve therapeutic consistency and expand physician willingness to recommend devices. |
| Magnetic Stimulation Platform Launch | Transcranial magnetic induction addresses treatment-resistant depression without surgical infrastructure requirements. |
| India Distribution Partnership | Local relationships with Maharashtra and Karnataka rehabilitation centers unlock tier-2 city access for transcutaneous systems. |
| Reimbursement Strategy Investment | Medicare coding decisions and German DRG negotiations directly gate patient access and manufacturer revenue realization. |
Study Parameters
A standing panel of implanting physicians, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement data, and EU MDR notified body public certificates. Bottom-up demand modeling from procedure volumes and device replacement cycles was cross-checked against top-down market sizing from manufacturer revenue disclosures and trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, therapy area, end user, and technology dimensions, with regional regulatory clusters and reimbursement intensity as cross-cutting variables. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns and policy shift timelines, incorporating implantable device miniaturization trajectories and magnetic stimulation clinical trial readouts as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement stability, EU MDR notified body capacity expansion, and Japanese QMS ordinance enforcement would require recalibration. Forecasts reflect documented assumptions regarding chronic pain prevalence trajectories and psychiatric service line adoption curves. Practitioners should keep alternative scenarios live as cybersecurity certification timelines and platinum-group metal price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electrotherapy System Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
External Defibrillator Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
Root Canal Irrigators Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Bone Cement Mixers Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market