
 Augmented Bone Graft Market | 2026-2036
Augmented Bone Graft Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Bone Graft Market Analysis
Spine surgery is repositioning augmented bone grafts from adjunctive use to primary graft selection in multi-level fusions. Medtronic leverages its integrated spine hardware portfolio to bundle graft delivery with interbody cages. Stryker Corporation sustains manufacturing scale across its biologics division through captive processing facilities in multiple states. Zimmer Biomet anchors its competitive stance via deep specialization in orthobiologics adjacent to its reconstructive joint franchise.
Augmented bone grafts comprise osteoconductive scaffolds, osteoinductive signaling proteins, and osteogenic cellular elements formulated to enhance bone regeneration beyond standard autograft performance. These grafts typically incorporate demineralized bone matrix combined with synthetic calcium phosphate ceramics or bioactive glasses, manufactured through lyophilization and terminal sterilization processes to preserve protein bioactivity while ensuring shelf stability. Synthetic grafts now command the fastest expansion trajectory as surgeons gain confidence in engineered substitutes with predictable resorption kinetics. Composite grafts that blend allograft particles with mineralized collagen occupy the premium tier, where margin pools concentrate due to differentiated handling characteristics and proprietary carrier formulations.
The FDA regulates these products through its Center for Devices and Radiological Health, with combination product determinations shifting regulatory pathways based on primary mode of action. EMA's Medical Device Regulation and the EU AI Act create parallel compliance burdens for European market access, while Health Canada and TGA maintain aligned but distinct biologics oversight frameworks. Stakeholders must monitor evolving reimbursement codes for hospital outpatient departments and ambulatory surgical centers, as site-of-service payment differentials increasingly dictate graft selection criteria and manufacturer channel strategy.
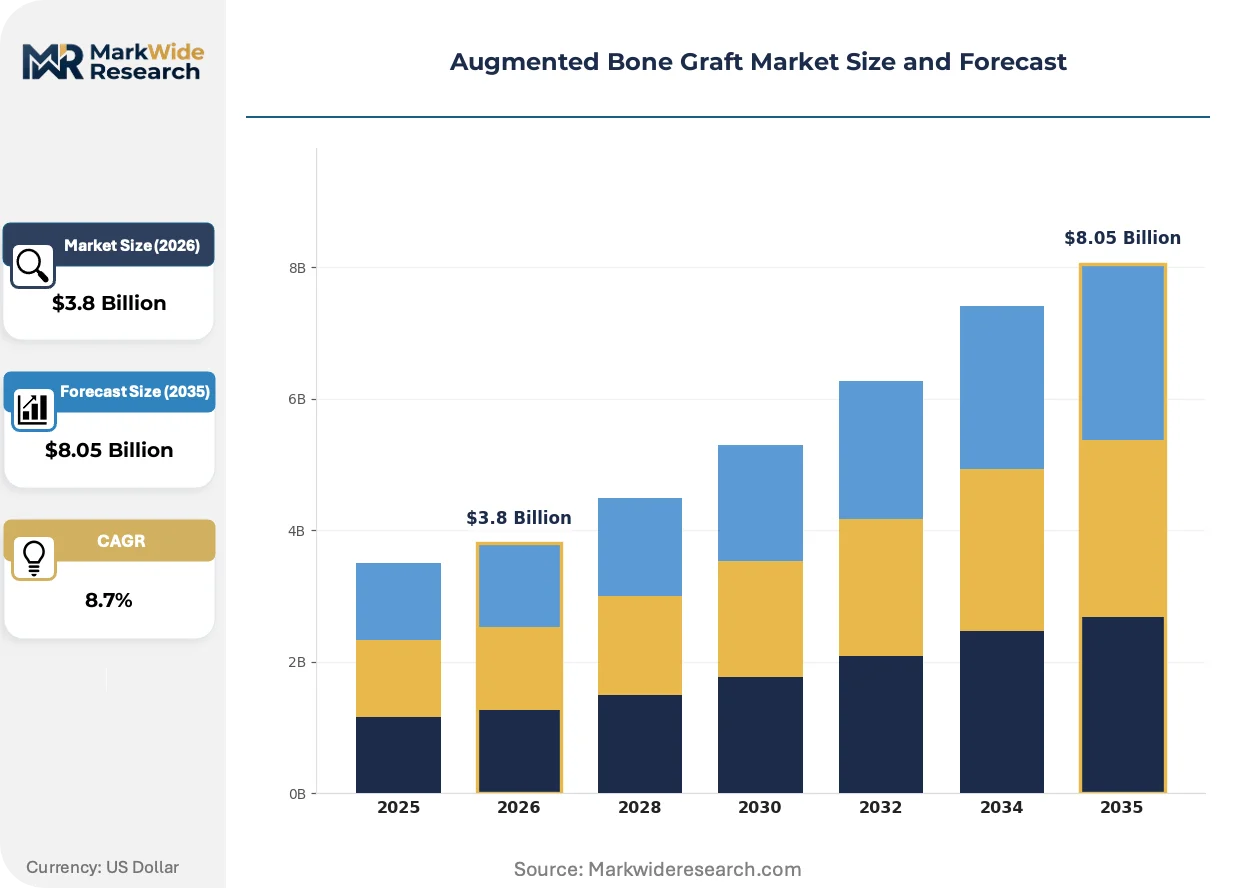
Market Dynamics
Surgeons at academic medical centers are repositioning augmented bone grafts as primary graft material in multi-level spinal fusions, compressing the historical role of iliac crest autograft harvesting and forcing manufacturers to recalibrate their clinical evidence portfolios.
Growth Catalysts
- MDR Compliance Burden:EMA's Medical Device Regulation has elevated the evidence threshold for allograft-derived products, advantaging synthetic ceramic manufacturers with cleaner regulatory pathways and accelerating hospital procurement shifts toward engineered substitutes.
- Outpatient Migration:Hospital outpatient departments in the United States now dominate high-value spinal fusion volume, creating concentrated demand for shelf-stable graft formats with simplified handling protocols.
- Lyophilization Advances:Terminal sterilization processes that preserve protein bioactivity now enable extended ambient storage, expanding distribution reach to ambulatory surgical centers previously constrained by cold-chain logistics.
Market Restraints
- Allograft Supply Concentration:Demineralized bone matrix sourcing depends on a limited network of accredited tissue banks, with procurement bottlenecks concentrated in southeastern United States processing facilities.
- Combination Product Friction:FDA's updated 510(k) guidance on primary mode of action determinations creates pathway uncertainty for composite grafts incorporating both structural scaffolds and biologic signaling elements.
- Synthetic Substitution Ceiling:Engineered calcium phosphates face residual surgeon skepticism in long-segment thoracolumbar fusions where autograft osteogenicity remains the clinical benchmark.
Strategic Opportunities
- Cervical Disc Adjacent:Motion-preserving cervical disc replacement creates adjacent demand for graft materials in salvage fusion procedures, an application segment with limited specialized product formulation.
- Health Canada Alignment:TGA and Health Canada biologics oversight frameworks are converging toward mutual recognition principles, simplifying multi-country registration for manufacturers with established US or EU dossiers.
- 3D-Printed Patient-Specific Scaffolds:Convergence of additive manufacturing with CT-based surgical planning enables anatomically matched graft geometries, opening premium positioning in complex deformity reconstruction.
Industry Challenges
- Biologics Processing Talent:Lyophilization and terminal sterilization operations require specialized technicians with GMP tissue experience, a skill set concentrated at a handful of contract manufacturing organizations.
- Legacy ERP Integration:Device-track-and-trace requirements under FDA UDI rules force graft manufacturers to reconfigure batch record systems originally designed for pharmaceutical rather than device workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Bone Graft Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Grafts, Synthetic Grafts, Demineralized Bone Matrix, Allografts Application: Orthopedic Surgery, Dental Procedures, Spine Surgery, Trauma Surgery End User: Hospitals, Outpatient Clinics, Surgical Centers, Dental Clinics Delivery Mode: Injectable Grafts, Pre-filled Devices, Sterile Packs, Custom Solutions |
| Companies Covered | Zimmer Biomet, Medtronic, Stryker Corporation, DePuy Synthes, NuVasive, Integra LifeSciences, Arthrex, RTI Surgical, Orthofix Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Bone Graft Market Emerging Trajectories
Formulation science is redefining competitive differentiation in bone regeneration, with engineered resorption kinetics and carrier rheology replacing simple osteoconductivity as the basis for clinical selection and procurement preference.
Bioactive glass-ceramic composites are absorbing the functional role previously served by mineralized allograft in posterior lumbar interbody fusion. Spine surgeons at high-volume centers are adopting these formulations for single-level procedures where predictable resorption timelines simplify postoperative imaging interpretation. The technology is absorbing margin compression in the standard-tier graft segment by eliminating tissue-bank dependency and associated supply variability.
EU AI Act provisions on machine-learning-enabled surgical planning tools are creating compliance precedents that spill into graft selection algorithms. Manufacturers integrating predictive fusion outcomes software with hardware-implant systems must now document algorithmic transparency under MDR-equivalent scrutiny. European notified bodies are prioritizing review capacity for these combination submissions, delaying pure-device graft clearances.
Hospital value-analysis committees have displaced individual surgeon preference as the dominant graft selection mechanism in US health systems. Bundled payment contracts for spinal episodes force standardization across previously autonomous orthopedic and neurosurgical service lines. California and Texas integrated delivery networks are most advanced in this consolidation, with graft formularies now locked for 24-36 month commitment periods.
Augmented Bone Graft Market Segmentation
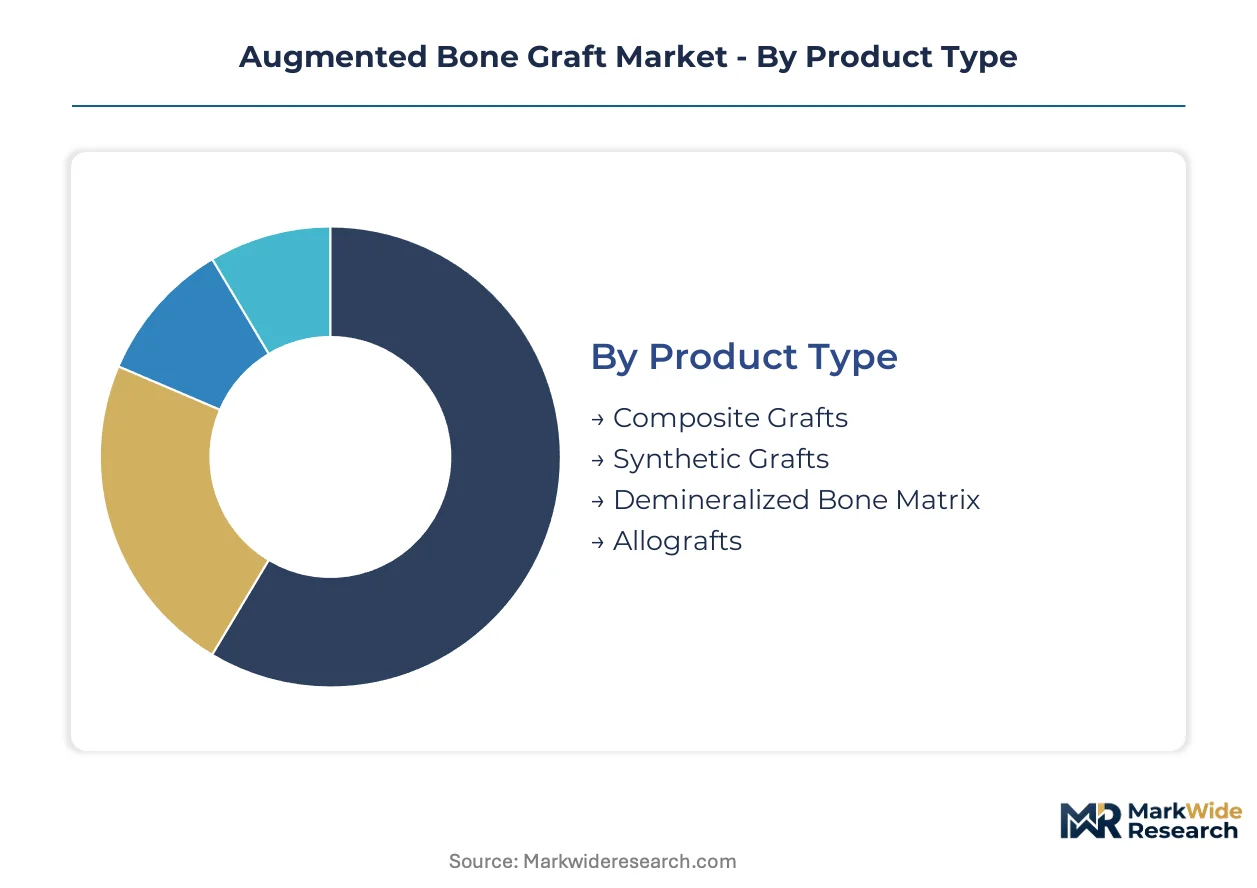
Segmentation in augmented bone grafts reveals how formulation chemistry, surgical workflow, and site-of-service economics intersect to determine procurement decisions. Each dimension carries distinct margin profiles and regulatory pathways that reshape competitive positioning across manufacturer portfolios.
Product Type:
Replacement cycles for graft materials accelerate as surgeons upgrade from autograft dependency to engineered substitutes with validated resorption timelines.
- Composite Grafts:Blends of allograft particles with mineralized collagen or synthetic ceramics deliver differentiated handling characteristics through proprietary carrier formulations. Hospital value-analysis committees in United States integrated delivery networks concentrate procurement volume here, drawn by predictable fusion outcomes that reduce revision liability under bundled payment contracts.
- Synthetic Grafts:Engineered calcium phosphate ceramics and bioactive glasses eliminate tissue-bank supply variability through manufactured consistency. Academic medical center spine departments in Texas and California drive adoption fastest, seeking shelf-stable formats that simplify inventory management across outpatient and inpatient settings.
- Demineralized Bone Matrix:Allograft-derived osteoinductive scaffold processed through controlled demineralization to expose bone morphogenetic proteins.
- Allografts:Mineralized cortical and cancellous bone from accredited tissue banks, processed through terminal sterilization.
Composite grafts sit at the top of the volume ranking, with synthetic grafts climbing the fastest as EMA MDR compliance burdens disadvantage allograft-reliant competitors.
Application:
Procedure-specific formulation requirements create tiered pricing stratification across surgical specialties, with spine applications commanding premium positioning due to fusion complexity.
- Spine Surgery:Multi-level thoracolumbar and cervical fusions demand grafts with load-bearing scaffold integrity and osteoinductive signaling. United States hospital outpatient departments now dominate procedure volume, forcing manufacturers to optimize packaging for same-day surgery logistics.
- Orthopedic Surgery:Long-bone nonunions and joint reconstruction applications prioritize moldable putty consistency and rapid vascularization. European trauma centers favor synthetic ceramics here, avoiding allograft sourcing complications under MDR traceability requirements.
- Dental Procedures:Ridge augmentation and sinus lift surgeries require particulate grafts with controlled particle size distribution.
- Trauma Surgery:Acute fracture management applications favor injectable formats for minimally invasive delivery.
Spine surgery captures the dominant revenue share, while dental procedures gain share fastest as implant dentistry expands in private practice settings.
End User:
Customer-type concentration determines channel strategy, with procurement centralization in health systems displacing individual surgeon preference as the primary selection mechanism.
- Hospitals:Academic medical centers and community hospitals with spine programs drive bulk purchasing through 24-36 month graft formularies. Value-analysis committees in California and Texas integrated delivery networks standardize across orthopedic and neurosurgical service lines, compressing vendor diversity.
- Surgical Centers:Ambulatory settings require ambient-storage formats with simplified handling protocols that reduce nursing training burden. Lyophilization advances enabling extended shelf stability have expanded synthetic graft distribution reach here.
- Outpatient Clinics:Orthopedic and pain management clinics with in-office procedure capabilities.
- Dental Clinics:Oral surgery and periodontal practices with implant placement services.
Hospitals anchor procurement volume, with surgical centers expanding most quickly as spinal fusion migrates to outpatient settings.
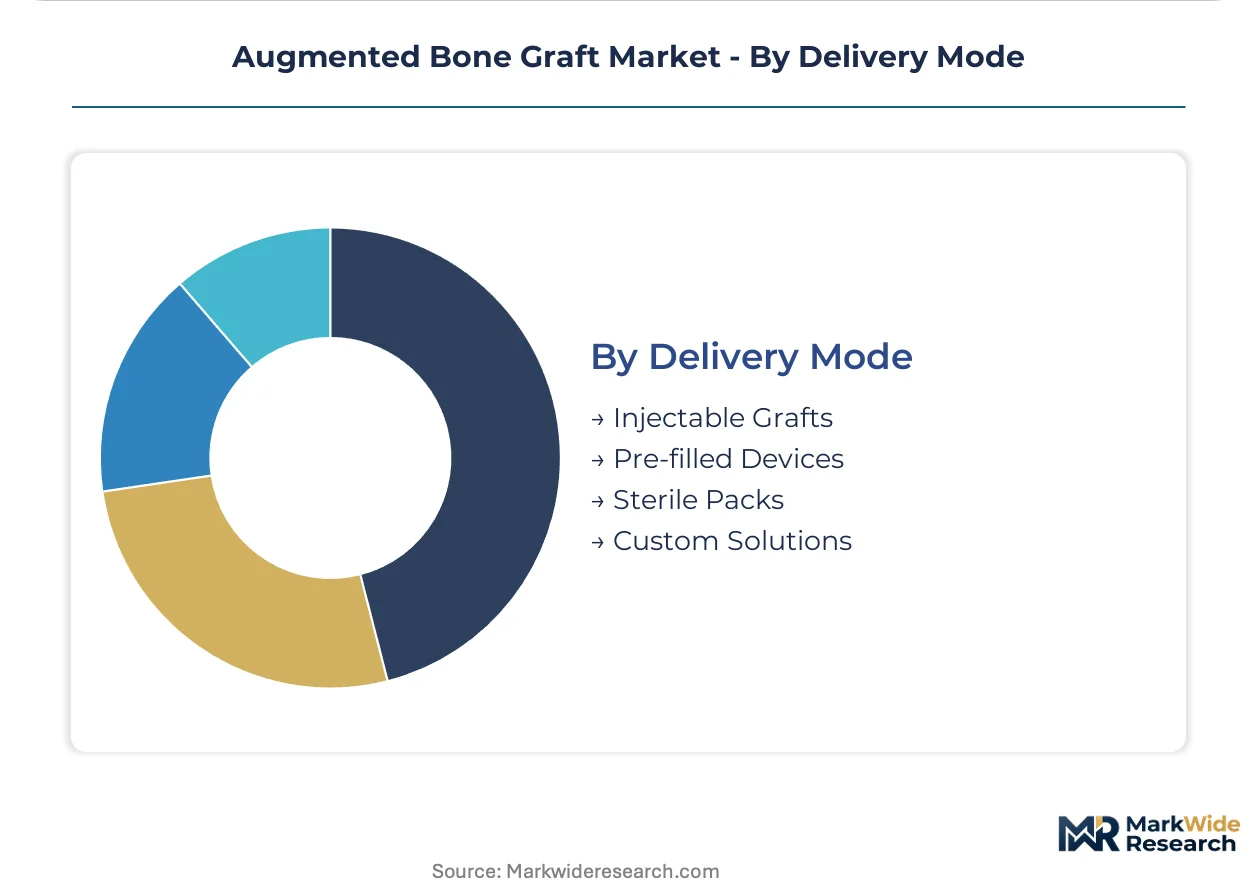
Delivery Mode:
Packaging and presentation formats increasingly differentiate competitive offerings as site-of-service logistics reshape handling requirements.
- Sterile Packs:Standardized graft quantities in peel-pouch configurations dominate high-volume hospital procurement, enabling lean inventory management through predictable consumption rates. United States health system distribution warehouses concentrate procurement here for spine fusion kits.
- Pre-filled Devices:Graft-loaded interbody cages and delivery systems streamline operating room workflow by reducing mixing steps. Medtronic's integrated hardware-biologics bundling strategy leverages this format across its spine portfolio.
- Injectable Grafts:Flowable formulations for minimally invasive delivery through cannula systems.
- Custom Solutions:Patient-specific geometries from CT-based surgical planning and additive manufacturing.
Sterile packs maintain volume leadership, with pre-filled devices gaining traction fastest as bundled implant-graft systems disassemble standalone procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EMA MDR compliance costs push production investment toward jurisdictions with streamlined biologics oversight. Manufacturers now site lyophilization and terminal sterilization facilities based on cost-of-compliance differentials rather than raw material proximity.
United States
Hospital outpatient departments in California and Texas integrated delivery networks now drive the dominant share of high-value spinal fusion volume. FDA's updated 510(k) guidance on combination product classification forces manufacturers to recalibrate submission strategies for composite grafts. The southeastern United States hosts the concentrated network of accredited tissue banks processing demineralized bone matrix.
Germany
Academic medical center spine departments in Bavaria and North Rhine-Westphalia are repositioning augmented grafts as primary material in multi-level fusions. EMA MDR has elevated evidence thresholds for allograft-derived products, advantaging synthetic ceramic manufacturers with cleaner regulatory pathways. Berlin-Brandenburg clusters host notified bodies prioritizing review capacity for machine-learning-enabled surgical planning submissions.
China
Domestic trauma centers in the Yangtze River Delta and Pearl River Delta are adopting engineered calcium phosphates for long-bone nonunions. NMPA biologics oversight frameworks are converging toward mutual recognition principles with TGA and Health Canada. Beijing-Tianjin-Hebei corridor manufacturers are expanding captive processing facilities to reduce dependency on imported allograft materials.
Japan
Metropolitan Tokyo and Osaka-Kobe spine surgeons are gaining confidence in synthetic substitutes with predictable resorption kinetics for single-level procedures. PMDA maintains aligned but distinct biologics oversight frameworks from US and EU regulators. Nagoya-area industrial clusters are developing additive manufacturing capabilities for patient-specific scaffold geometries.
Australia
New South Wales and Victoria health systems are standardizing graft formularies across previously autonomous orthopedic and neurosurgical service lines. TGA biologics frameworks are simplifying multi-country registration for manufacturers with established US or EU dossiers. Sydney and Melbourne academic medical centers are expanding motion-preserving cervical disc replacement programs, creating adjacent demand for salvage fusion graft materials.
Augmented Bone Graft Market Vendor Landscape
Portfolio diversification dominates the current landscape as integrated hardware-biologics bundling displaces standalone graft procurement. The vendor base concentrates around three strategic tiers: diversified orthopedic conglomerates with captive biologics divisions, specialized orthobiologics pure-plays, and contract manufacturers with GMP tissue processing capabilities. Horizontal integration through acquisition of tissue banks and lyophilization facilities represents the primary expansion vector. Vertical control over sterilization operations is emerging as a defensive necessity against supply variability.
Among diversified orthopedic conglomerates, Medtronic, Stryker Corporation, and Zimmer Biomet occupy positions defined by their hardware-implant heritage and captive processing infrastructure. Medtronic exemplifies the integrated bundling archetype through its spine hardware portfolio. Stryker Corporation represents manufacturing-scale defense through multi-state biologics facilities. Zimmer Biomet anchors competitive positioning via orthobiologics specialization adjacent to reconstructive joint franchises. These three entities collectively illustrate how hardware-graft integration is compressing standalone procurement channels.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Medtronic |
| Stryker Corporation |
| DePuy Synthes |
| NuVasive |
| Integra LifeSciences |
| Arthrex |
| RTI Surgical |
| Orthofix Medical |
| Others |
Supply Flow & Price Mechanics
Captive lyophilization and terminal sterilization infrastructure anchors both supply security and margin defense for manufacturers navigating EMA MDR compliance costs and FDA 510(k) pathway uncertainty. Hospital value-analysis committees in California and Texas integrated delivery networks now extract volume discounts that compress distributor margins, forcing graft suppliers to absorb cold-chain elimination gains into price concessions rather than profit retention.
Pricing Analysis
Distributor margins in the United States spine graft channel have compressed from traditional medical-device tiers toward commodity-like single-digit levels as GPO contracts consolidate procurement volume. Three-tier pricing structure across premium composite grafts, standard synthetic ceramics, and economy demineralized bone matrix segments reflects handling complexity and osteoinductive protein concentration rather than raw material cost. Cost compression in the standard tier intensifies because bioactive glass-ceramic manufacturers compete on predictable resorption kinetics. Ambulatory surgical centers exhibit highest price sensitivity due to constrained reimbursement under site-of-service differentials, while academic medical centers prioritize fusion outcome data over unit cost.
Supply Chain Analysis
Cold-chain elimination through ambient-stable lyophilization formats has reduced freight cost vulnerability for synthetic graft distribution to surgical centers previously dependent on refrigerated logistics. Allograft-derived materials draw from accredited tissue banks concentrated in the southeastern United States, with mineralized cortical bone sourcing anchored in domestic procurement networks. Demineralized bone matrix, synthetic calcium phosphate precursors, and bioactive glass feedstock create multi-input dependency. Single-source vulnerability concentrates in lyophilization capacity held by a handful of GMP-certified contract manufacturers. Distribution runs through health system distribution warehouses for sterile packs, with direct-to-hospital contracting displacing traditional distributor stocking for high-volume spine programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The augmented bone graft market operates as a regulatory compounder where EMA MDR evidence thresholds and FDA combination product guidance create accelerating compliance costs that favor scaled incumbents with captive processing infrastructure.
For Market Incumbents: Acquire lyophilization and terminal sterilization facilities to secure GMP tissue processing capacity against contract manufacturer bottlenecks. Consolidate tissue bank relationships in the southeastern United States to defend allograft supply positions against synthetic substitution. Channel control through direct hospital contracting represents the priority lever for margin defense as GPOs extract distributor concessions. For New Entrants and Emerging Players: Enter via 3D-printed patient-specific scaffolds for complex deformity reconstruction, a premium segment with limited incumbent formulation specialization. Target ambulatory surgical centers in Texas and California with shelf-stable synthetic graft formats that simplify nursing protocols. A software companion strategy integrating CT-based surgical planning with graft geometry customization offers the most penetrable go-to-market angle against hardware-bundled competitors. For Investors and Strategic Acquirers: Roll-up economics work for specialized orthobiologics pure-plays because hospital value-analysis committee standardization is compressing vendor counts and creating distressed assets with retained surgeon relationships. Five-to-ten year viability hinges on regulatory pathway clarity rather than technology differentiation alone. The signal to watch is FDA 510(k) clearance velocity for composite grafts with biologic signaling elements, as pathway friction determines which product formats achieve scalable commercial traction.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Lyophilization Facility Acquisition | Secures GMP tissue processing capacity against contract manufacturer concentration in southeastern United States. |
| FDA 510(k) Combination Product Submission | Clarifies regulatory pathway for composite grafts incorporating structural scaffolds and biologic signaling elements. |
| Hospital System Direct Contracting | Bypasses distributor margin extraction by California and Texas integrated delivery network value-analysis committees. |
| 3D-Printed Scaffold Development | Enables patient-specific geometries for complex deformity reconstruction with premium positioning. |
| Reimbursement Strategy for Outpatient Migration | Aligns graft format and packaging with site-of-service payment differentials driving spinal fusion volume shift. |
Methodological Framework
Bottom-up spine surgery procedure volume modeling reconciled against top-down synthetic ceramic and allograft production tracking forms the analytical core of this study. Primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS outpatient procedure data. Triangulation between demand-side consumption patterns and supply-side manufacturing capacity ensures cross-verified market sizing.
Input-output matrices map graft consumption rates to spinal fusion procedure volumes across synthetic, composite, demineralized bone matrix, and allograft product categories. Segmentation dimensions include formulation chemistry, surgical application, end-user facility type, and delivery mode packaging. CAGRs derive from procedure volume elasticity to demographic aging patterns and surgical site migration trends. Forecast inputs incorporate lyophilization capacity expansion timelines and regulatory clearance velocity for combination product submissions.
The model holds under continued outpatient migration and stable reimbursement differentials; deviation in FDA combination product pathway rulings or EMA MDR enforcement intensity would shift competitive positioning between allograft-reliant and synthetic-focused manufacturers. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Low Vision Aids Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Hemorrhage Control System Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Defibrillator Pads Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Buccal Cavity Devices Market