
 North America Sperm Separation Devices Market | 2026-2036
North America Sperm Separation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sperm Separation Devices Market Analytics
Equipment leasing and pay-per-use service models is fragmenting competitive dynamics in North America sperm separation devices. Hamilton Thorne leverages its installed base of imaging systems to cross-sell separation workflows. The Cooper Companies anchors its position through backward integration into fertility consumables and clinic networks. Cook Medical competes on the strength of its long-standing gynecological device distribution channels across hospital systems.
Sperm separation devices isolate motile, morphologically normal spermatozoa from seminal plasma using physical or chemical gradients, typically operating at room temperature with processing times under ninety minutes to preserve viability for immediate intrauterine insemination or cryopreservation. Microfluidic devices now lead product-type demand due to reduced oxidative stress on gametes compared with centrifugation, while gradient density technology sustains the largest technology share because of established clinical validation and lower capital requirements. Magnetic separation units represent the fastest-growing product category, driven by niche demand for DNA integrity screening in research laboratories.
FDA 510(k) clearance processes and CLIA certification standards govern commercial access and laboratory operational compliance for sperm separation devices in the United States, while Health Canada Medical Device Licensing applies north of the border. These frameworks elevate barriers for unproven technologies but also create structured reimbursement pathways through fertility benefit plans. Stakeholders must monitor evolving state-level insurance mandates for infertility coverage, as legislative expansions in Illinois and Massachusetts have already shifted clinic procurement volumes toward higher-throughput separation platforms.
Market Dynamics
Microfluidic technology is digitizing sperm separation workflows across fertility clinics, compressing processing times while preserving gamete viability through reduced oxidative stress compared with centrifugation methods.
Growth Catalysts
- State-level insurance mandates:Legislative expansions in Illinois and Massachusetts have shifted clinic procurement volumes toward higher-throughput separation platforms, creating structured demand pull.
- Academic medical hub clustering:Concentrated assisted reproductive technology centers near research institutions in California, Texas, and Ontario accelerate clinical validation cycles for new separation technologies.
- DNA integrity screening protocols:Research laboratories are expanding magnetic separation unit deployment for sperm DNA fragmentation analysis, opening adjacent demand channels beyond fertility clinics.
Market Restraints
- FDA 510(k) clearance timelines:Structured regulatory pathways elevate barriers for unproven microfluidic technologies, extending product development cycles by twelve to eighteen months.
- Gradient density consumable dependence:Established clinical validation of silica-based gradient media creates supplier lock-in effects, limiting rapid technology switching for mid-sized fertility practices.
- CLIA laboratory certification costs:Compliance infrastructure requirements for high-complexity testing designation strain capital budgets at independent reproductive laboratories.
Strategic Opportunities
- Pay-per-use service models:Equipment leasing arrangements are fragmenting competitive dynamics, enabling smaller fertility clinics to access advanced separation platforms without capital expenditure.
- Cross-border Health Canada licensing:Canadian fertility centers present underpenetrated demand for FDA-cleared devices with streamlined northbound regulatory recognition pathways.
- Cryopreservation workflow integration:Automated post-separation vitrification systems represent white space for device manufacturers bundling separation with long-term storage solutions.
Industry Challenges
- Embryologist training standardization:Variable microfluidic device operation protocols across fertility clinics create quality control inconsistencies requiring harmonized competency frameworks.
- Legacy centrifugation infrastructure retrofit:Capital-intensive laboratory reconfiguration for microfluidic adoption delays technology transitions at hospital-affiliated reproductive centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sperm Separation Devices Market |
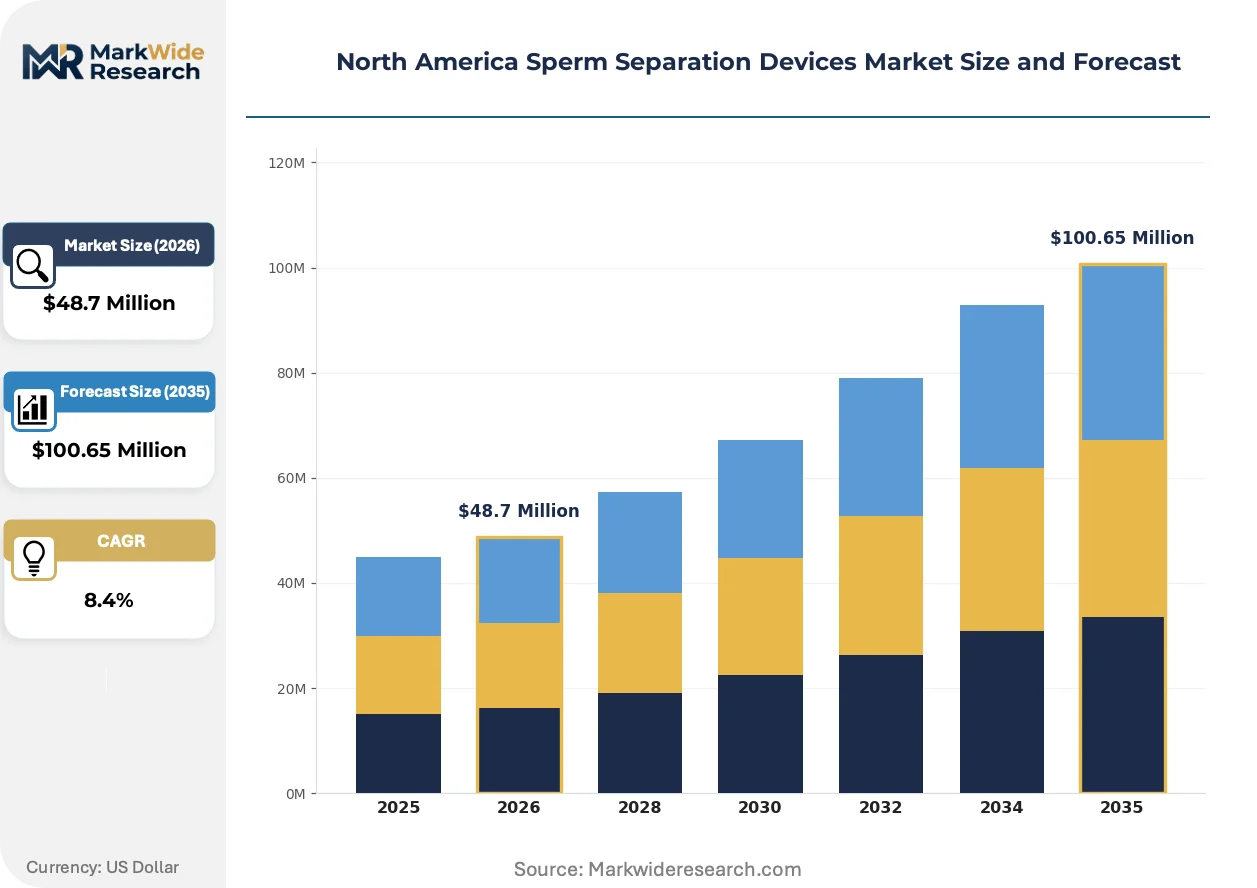
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Devices, Centrifuges, Filtration Systems, Magnetic Separation Units Technology: Gradient Density, Acoustic Separation, Optical Tweezers, Electrophoresis End User: Fertility Clinics, Hospitals, Research Laboratories, Sperm Banks Application: Assisted Reproductive Technology, Sperm Cryopreservation, Genetic Testing, Intrauterine Insemination |
| Companies Covered | Hamilton Thorne, The Cooper Companies, Memphasys, DxNow, Bonraybio, Nidacon International, Promega Corporation, Cook Medical, SAR Healthline, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sperm Separation Devices Market Evolving Landscape
Workflow automation and real-time quality monitoring are reshaping how fertility laboratories process semen samples, shifting competitive advantage toward integrated platform vendors.
Microfluidic chip-based separation technology is digitizing sperm selection through computer-vision-guided flow control and automated motility scoring. Fertility clinics in California and Texas are adopting these platforms at accelerated rates, displacing manual technician assessment steps. This digitization is compressing laboratory staffing requirements while standardizing selection outcomes across operator experience levels.
Health Canada Medical Device Licensing requirements are tightening post-market surveillance obligations for sperm separation devices, mandating annual safety reporting for Class II and III instruments. Manufacturers must now maintain Canadian-specific adverse event databases, increasing compliance overhead. Magnetic separation units face heightened scrutiny due to nanoparticle residue concerns, prompting reformulation of separation media.
Clinic procurement committees are consolidating vendor relationships around single-source platform contracts bundling imaging, separation, and cryopreservation modules. Independent fertility practices in Ontario are migrating from best-of-breed component purchasing to integrated system commitments, reducing supplier management burden. This concentration pattern is most visible in academic medical center networks where standardization protocols span multiple satellite clinics.
North America Sperm Separation Devices Market Segmentation
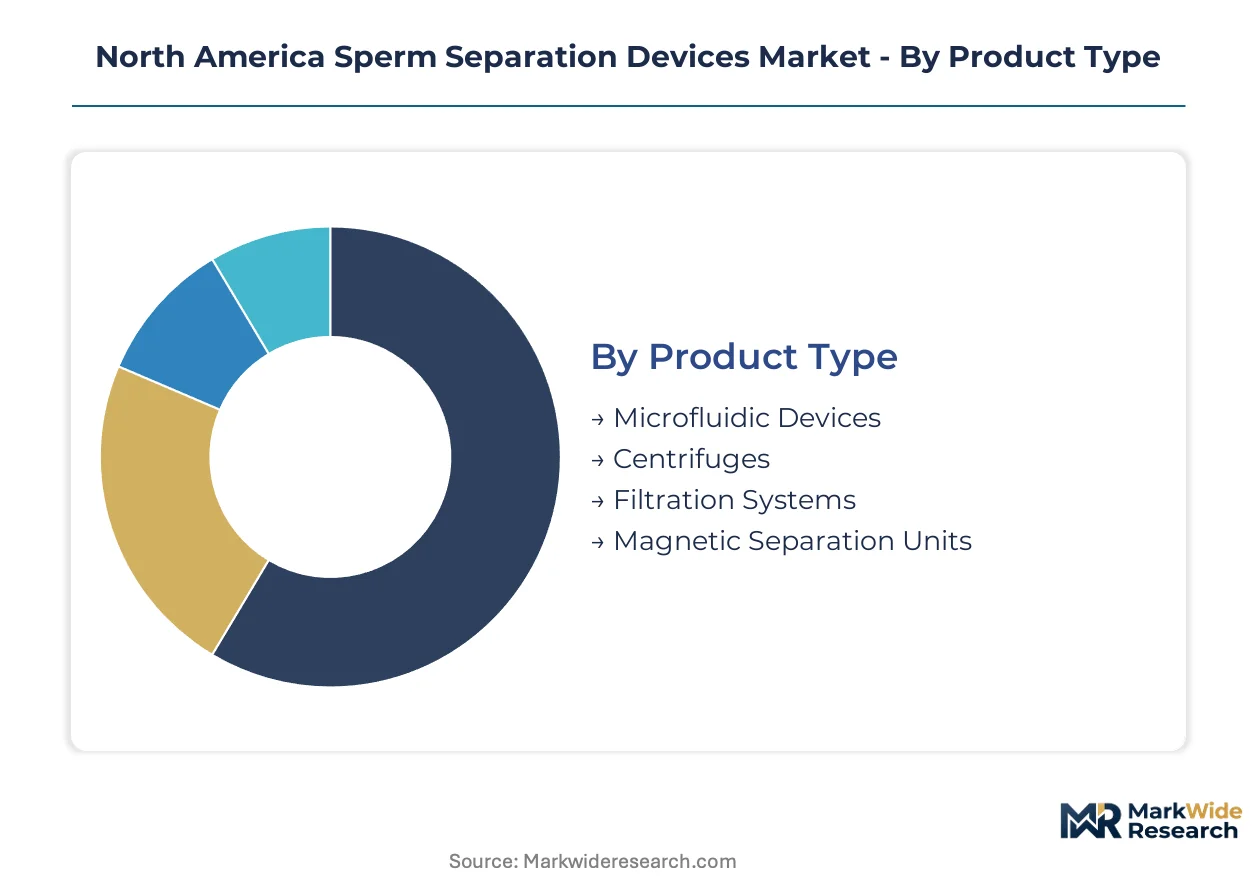
Sperm separation devices segment across four critical dimensions that determine procurement patterns and technology adoption cycles. Each category reflects distinct capital intensity, regulatory pathways, and end-user workflow requirements that shape manufacturer positioning.
Product Type:
Replacement cycles vary sharply across this category, with consumable-dependent platforms turning over annually while capital equipment persists for seven to ten years.
- Microfluidic Devices:Chip-based platforms employ laminar flow channels and computer-vision sorting to isolate motile spermatozoa without centrifugal stress. Fertility clinics in California and Texas are displacing manual assessment steps with these systems, compressing laboratory staffing requirements while standardizing selection outcomes.
- Centrifuges:Density gradient centrifugation remains the workhorse technology, utilizing silica-based media to separate morphologically normal cells from seminal plasma. Established clinical validation and lower capital requirements sustain dominance at hospital-affiliated reproductive centers in Ontario, though oxidative stress concerns limit adoption at research-focused facilities.
- Filtration Systems:Membrane-based separation employs calibrated pore sizes to retain motile gametes while eliminating debris and immotile cells.
- Magnetic Separation Units:Immunomagnetic bead platforms target surface antigen expression for DNA integrity screening protocols, gaining traction in research laboratories beyond fertility clinic demand.
Centrifuges dominate installed base. Microfluidic devices are where expansion concentrates.
Technology:
Cost tiers stratify sharply, with premium acoustic and optical platforms commanding five to ten times the per-procedure expense of standard gradient methods.
- Gradient Density:Silica colloid layering exploits differential sedimentation rates to concentrate viable spermatozoa at media interfaces. Mid-sized fertility practices across Illinois and Massachusetts exhibit supplier lock-in effects due to established validation protocols, limiting rapid technology switching despite oxidative stress trade-offs.
- Acoustic Separation:Standing wave manipulation exploits acoustic radiation force to trap cells based on size and density without physical contact. Academic medical centers in Texas are validating these platforms for reduced gamete damage, though capital requirements constrain penetration at independent laboratories.
- Optical Tweezers:Laser trap systems enable single-cell manipulation for research-grade DNA fragmentation analysis.
- Electrophoresis:Charge-based migration separates cells by surface electrophoretic mobility, finding niche application in sperm membrane integrity studies.
Gradient density methods anchor volume share. Acoustic separation is gaining share fastest among next-generation platforms.
End User:
Customer type determines procurement authority, with hospital systems favoring bundled vendor contracts while independent clinics prioritize flexible leasing terms.
- Fertility Clinics:Specialized reproductive medicine centers perform the majority of in vitro fertilization and intrauterine insemination procedures. Large assisted reproductive technology centers clustered near academic medical hubs in California, Texas, and Ontario are consolidating vendor relationships around single-source platform contracts.
- Hospitals:Hospital-affiliated reproductive centers leverage established gynecological device distribution channels and capital budgets for infrastructure retrofit. CLIA laboratory certification requirements for high-complexity testing designation strain procurement timelines at these facilities.
- Research Laboratories:Academic and commercial research settings deploy separation devices for DNA fragmentation analysis and cryopreservation protocol development.
- Sperm Banks:Cryopreservation-focused facilities prioritize high-throughput separation platforms for donor sample processing and long-term storage workflows.
Fertility clinics concentrate procedure volume. Research laboratories are where magnetic separation adoption is climbing the fastest.
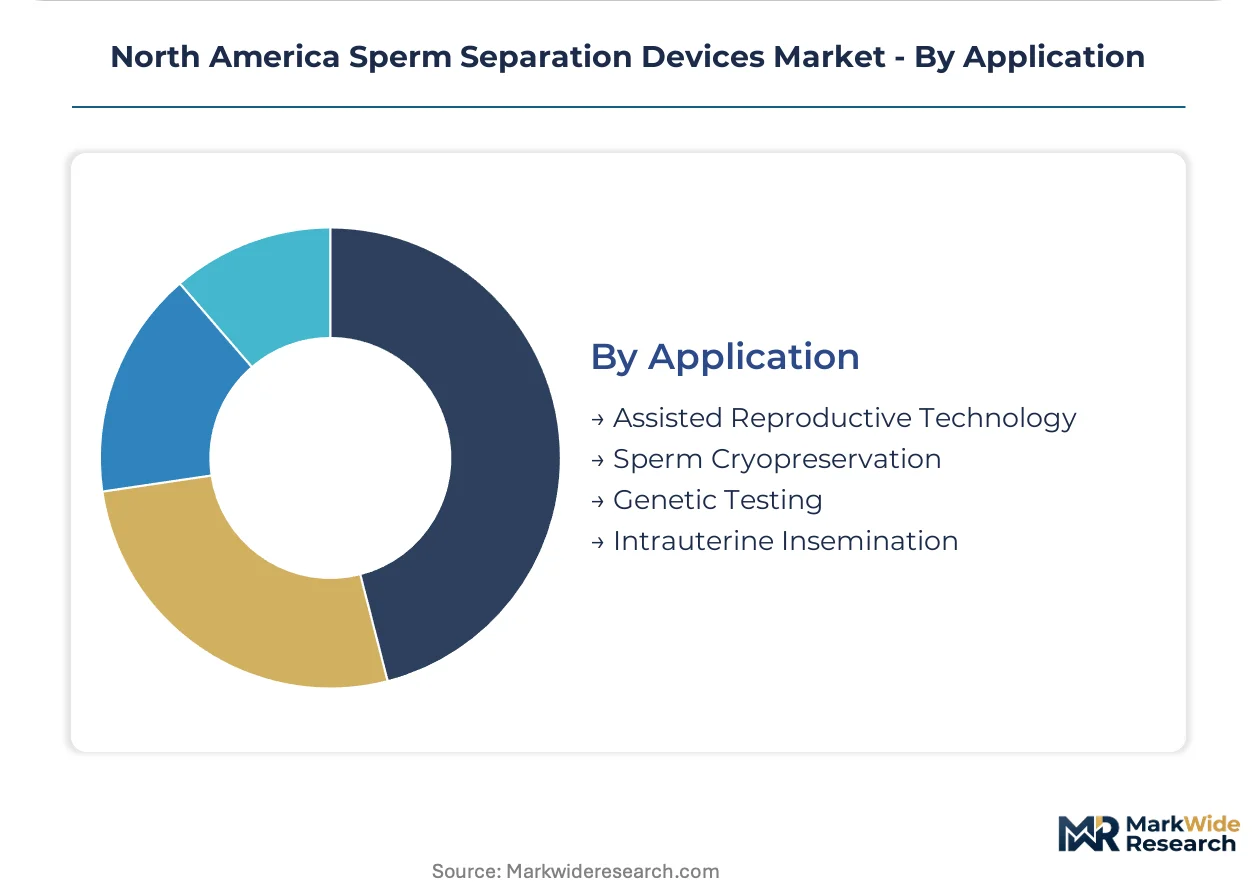
Application:
Maturity levels diverge, with intrauterine insemination representing established clinical practice while genetic testing applications remain protocol-development intensive.
- Assisted Reproductive Technology:In vitro fertilization and related procedures constitute the primary demand driver, requiring motile, morphologically normal spermatozoa for fertilization success. State-level insurance mandates in Illinois and Massachusetts have shifted clinic procurement volumes toward higher-throughput separation platforms, creating structured demand pull.
- Sperm Cryopreservation:Post-separation vitrification for long-term fertility preservation requires gamete viability maintenance through rapid freezing protocols. Automated post-separation vitrification systems represent white space for device manufacturers bundling separation with storage solutions.
- Genetic Testing:DNA integrity screening and chromosomal analysis applications leverage magnetic separation for sperm DNA fragmentation assessment.
- Intrauterine Insemination:Lower-complexity fertility treatment requires processed semen samples with concentrated motile cells, sustaining demand for rapid-turnaround gradient density methods.
Assisted reproductive technology commands revenue concentration. Genetic testing is where steepest expansion trajectory is emerging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level insurance mandates in Illinois and Massachusetts are redirecting clinic procurement toward higher-throughput platforms, while FDA 510(k) clearance pathways and CLIA certification requirements govern commercial access across the region.
United States
Fertility clinics in California, Texas, and Illinois concentrate the heaviest device demand near academic medical hubs. FDA 510(k) clearance processes and CLIA laboratory certification standards shape product development timelines and operational compliance. Large assisted reproductive technology centers in Los Angeles, Houston, and Chicago are consolidating vendor relationships around single-source platform contracts bundling imaging and separation workflows.
Canada
Health Canada Medical Device Licensing applies to commercial access north of the border, with annual safety reporting mandates for Class II and III instruments tightening post-market surveillance. Ontario fertility centers present underpenetrated demand for FDA-cleared devices with streamlined regulatory recognition pathways. Toronto academic medical networks are standardizing protocols across satellite clinics, driving integrated system procurement.
California
Microfluidic device adoption is accelerating fastest in this state as fertility clinics displace manual technician assessment with computer-vision-guided platforms. State-level regulatory alignment with federal FDA frameworks enables rapid technology validation cycles. San Francisco and Los Angeles metropolitan clusters anchor the largest concentration of research-focused fertility centers pursuing DNA integrity screening applications.
Texas
Academic medical centers in Houston and Dallas are validating acoustic separation platforms for reduced gamete damage, though capital requirements constrain penetration at independent laboratories. CLIA high-complexity testing designation requirements strain procurement timelines at hospital-affiliated reproductive centers. The state's large assisted reproductive technology infrastructure supports backward integration strategies among major device suppliers.
Illinois
Legislative expansions in infertility coverage insurance mandates have shifted Chicago-area clinic procurement volumes toward higher-throughput separation platforms. State policy creates structured demand pull distinct from neighboring jurisdictions. Fertility practices here exhibit supplier lock-in effects from established gradient density validation protocols, limiting rapid technology switching despite oxidative stress trade-offs.
North America Sperm Separation Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated vendor base where imaging system incumbents leverage installed bases for cross-selling separation workflows. The market structure tiers between premium integrated platform vendors and consumable-dependent specialists. Three archetypes dominate: imaging-system extenders, fertility consumable integrators, and gynecological device distributors. Competitive moves concentrate on backward integration into clinic networks and pay-per-use service model deployment.
Among North American-based suppliers, Hamilton Thorne and The Cooper Companies exemplify divergent strategic positioning, with the former representing imaging-system extension archetypes and the latter occupying fertility consumable integration roles. Cook Medical anchors the gynecological device distribution archetype through hospital system channel control. These three companies collectively illustrate how vendor relationships consolidate around platform contracts versus component purchasing strategies.
| Leading Market Players |
|---|
| Hamilton Thorne |
| The Cooper Companies |
| Memphasys |
| DxNow |
| Bonraybio |
| Nidacon International |
| Promega Corporation |
| Cook Medical |
| SAR Healthline |
| Others |
Value Network & Pricing Analysis
Los Angeles and San Diego metropolitan clusters concentrate microfluidic chip manufacturing capacity, with their scale dynamics translating directly into pricing leverage over fertility clinics in secondary markets. FDA 510(k) clearance timelines and CLIA certification requirements amplify this concentration effect, as downstream buyers face switching costs that insulate premium-tier suppliers from price erosion.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA-cleared microfluidic platforms commanding substantial premiums over Health Canada-only licensed alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects gradient density consumable dependence versus capital equipment leasing models. Cost compression in the economy tier is intensifying because pay-per-use service models fragment buyer commitment. Independent fertility practices in Ontario exhibit highest price sensitivity due to provincial reimbursement rate constraints, while academic medical center networks in Texas show lowest sensitivity given bundled platform procurement authority.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate supplier-financing arrangements, with equipment lessors absorbing working capital strain to secure clinic exclusivity. Manufacturing concentrates in the United States, Germany, and Japan for precision microfluidic components, while silica-based gradient media production draws from China and India. Polycarbonate substrates, photoresist materials, and immunomagnetic bead formulations constitute critical input dependencies. Single-source vulnerability in nanoparticle separation media creates exposure to Health Canada reformulation mandates. Distribution runs through gynecological device distributors and direct fertility clinic sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by deferred clinic capital expenditure during state-level insurance mandate negotiations. The recovery trajectory hinges on legislative clarity in Illinois and Massachusetts expanding coverage pools.
For Market Incumbents: Build regulatory clearance moats through parallel FDA 510(k) and Health Canada Medical Device Licensing submissions, compressing competitor entry windows by twelve to eighteen months. Deepen backward integration into fertility consumables to capture recurring revenue streams threatened by microfluidic chip disposables. Anchor hospital system channel control through CLIA laboratory certification partnership programs that raise switching costs for mid-sized practices. For New Entrants and Emerging Players: Canadian fertility centers present underpenetrated demand for FDA-cleared devices with streamlined northbound regulatory recognition pathways. Magnetic separation units for DNA integrity screening in research laboratories offer fastest penetration velocity given lower certification barriers. Cryopreservation workflow integration represents adjacent white space with bundled vitrification system partnerships. Pursue equipment leasing arrangements with independent Ontario clinics lacking capital expenditure authorization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among consumable-dependent gradient density platforms, though microfluidic chip disposables are accelerating fastest. Five-to-ten year viability favors vendors with installed imaging system bases enabling cross-selling workflows. Acquisition targets should demonstrate Health Canada licensing progress and Ontario clinic network penetration. Watch for state-level insurance mandate expansions beyond Illinois and Massachusetts as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Parallelism | Dual-track FDA and Health Canada filings compress competitor entry timelines by twelve to eighteen months. |
| CLIA Certification Partnership Program | Hospital-affiliated reproductive centers gain compliance infrastructure support, deepening vendor lock-in effects. |
| Microfluidic Chip Disposable Conversion | Fertility clinics in California and Texas shift from capital purchase to recurring consumable revenue models. |
| Acoustic Separation Platform Validation | Academic medical centers in Houston validate reduced gamete damage claims against centrifugation methods. |
| Cryopreservation Workflow Bundling | Automated post-separation vitrification systems address white space in long-term fertility preservation protocols. |
Research Methodology
Cross-validation between primary interviews with reproductive endocrinologists, embryology laboratory directors, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary sources including FDA 510(k) clearance databases, Health Canada Medical Device Licensing records, hospital procurement databases, and CMS fertility benefit plan filings. Bottom-up demand modeling from clinic procedure volumes triangulates with top-down equipment shipment data across the analysis window.
Calibration against historical adoption curves for microfluidic and gradient density platforms refines the analytical framework across product type, technology, end user, and application segmentation dimensions. CAGRs derive from logistic diffusion modeling of technology substitution rates, with inputs including CLIA laboratory certification expansion timelines and state-level insurance mandate legislative tracking.
The forecast holds incumbent behavior within observed patterns; aggressive moves by acoustic separation platform entrants or magnetic separation unit specialists would shift outcomes. Macroeconomic contraction affecting fertility benefit plan generosity, regulatory deviation in FDA 510(k) review timelines, or breakthrough microfluidic chip cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
North America Wheelchair Market
Medical Devices
Photopheresis Products Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Global Medical Composite Market
Medical Devices
Infertility Devices Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market