
 Global Personal Care Active Ingredients Market | 2026-2036
Global Personal Care Active Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Care Active Ingredients Market Outlook
Prestige skincare is expanding its share of active ingredient procurement as consumers trade up from mass-market alternatives. BASF SE leverages its biotechnology platforms to supply peptide complexes and ceramides to luxury cosmetics houses. Evonik Industries AG anchors its position through specialty surfactants engineered for sensitive-skin applications. Croda International Plc dominates lipid-based delivery systems that enhance bioavailability of vitamins and antioxidants in facial serums.
Personal care active ingredients comprise functional molecules—peptides, ceramides, botanical extracts, and synthetic actives—formulated at concentrations between 0.1% and 10% to deliver measurable dermatological benefits such as hydration, barrier repair, or sebum regulation. Humectants and emollients occupy the largest volume share within ingredient type segmentation, though preservative-free antimicrobial systems command premium pricing due to clean-label positioning. Skincare applications absorb the majority of value across the application dimension, while contract manufacturers represent the fastest-growing end-user channel as brands outsource formulation complexity to specialized partners.
REACH restrictions on traditional preservatives and the FDA's color additive regulations are forcing reformulation cycles across European and North American supply chains. ECHA's ongoing substance evaluations for endocrine-disrupting candidates threaten several legacy UV filters and antimicrobial actives. China's NMPA and GB standards for cosmetic safety assessments create divergent compliance pathways that fragment global product registration strategies. Stakeholders must monitor regulatory divergence between major economies when allocating R&D budgets and qualifying new raw material suppliers.
Market Dynamics
REACH substance evaluations and China's GB cosmetic safety standards are fragmenting formulation strategies as brands face divergent compliance thresholds across major economies.
Growth Catalysts
- Clean-label mandates:ECHA's endocrine-disruptor screening is accelerating replacement of legacy preservatives with bio-based antimicrobial systems in European formulations.
- Biotechnology platforms:Peptide synthesis via fermentation is reducing production costs for ceramide complexes used in barrier-repair skincare.
- China's domestic brand expansion:Local beauty houses are scaling captive R&D for proprietary active formulations, reducing import dependency.
Market Restraints
- Raw material concentration:Palm-derived emollients face supply volatility from Southeast Asian weather disruptions and land-use restrictions.
- Regulatory friction:Divergent NMPA and FDA approval timelines for novel UV filters delay global product launches by 18-36 months.
- Technical substitution:Mineral-based sunscreens are displacing organic chemical filters in pediatric and sensitive-skin segments, compressing addressable volumes for traditional actives.
Strategic Opportunities
- India's underpenetrated premium segment:CDSCO's streamlined cosmetic ingredient notifications are enabling faster entry for peptide and botanical active suppliers.
- Microbiome-targeted applications:Postbiotic lysates and prebiotic oligosaccharides are opening formulation white space beyond conventional moisturization claims.
- Direct-to-brand digital channels:Specialty ingredient marketplaces are disintermediating traditional distributors for mid-size cosmetics manufacturers.
Industry Challenges
- Formulation chemist scarcity:Shortage of specialists capable of integrating bio-based actives into stable emulsion systems is extending development timelines.
- Cross-border certification complexity:Divergent animal-testing bans between EU REACH and China's pre-market safety assessment requirements force parallel validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Care Active Ingredients Market |
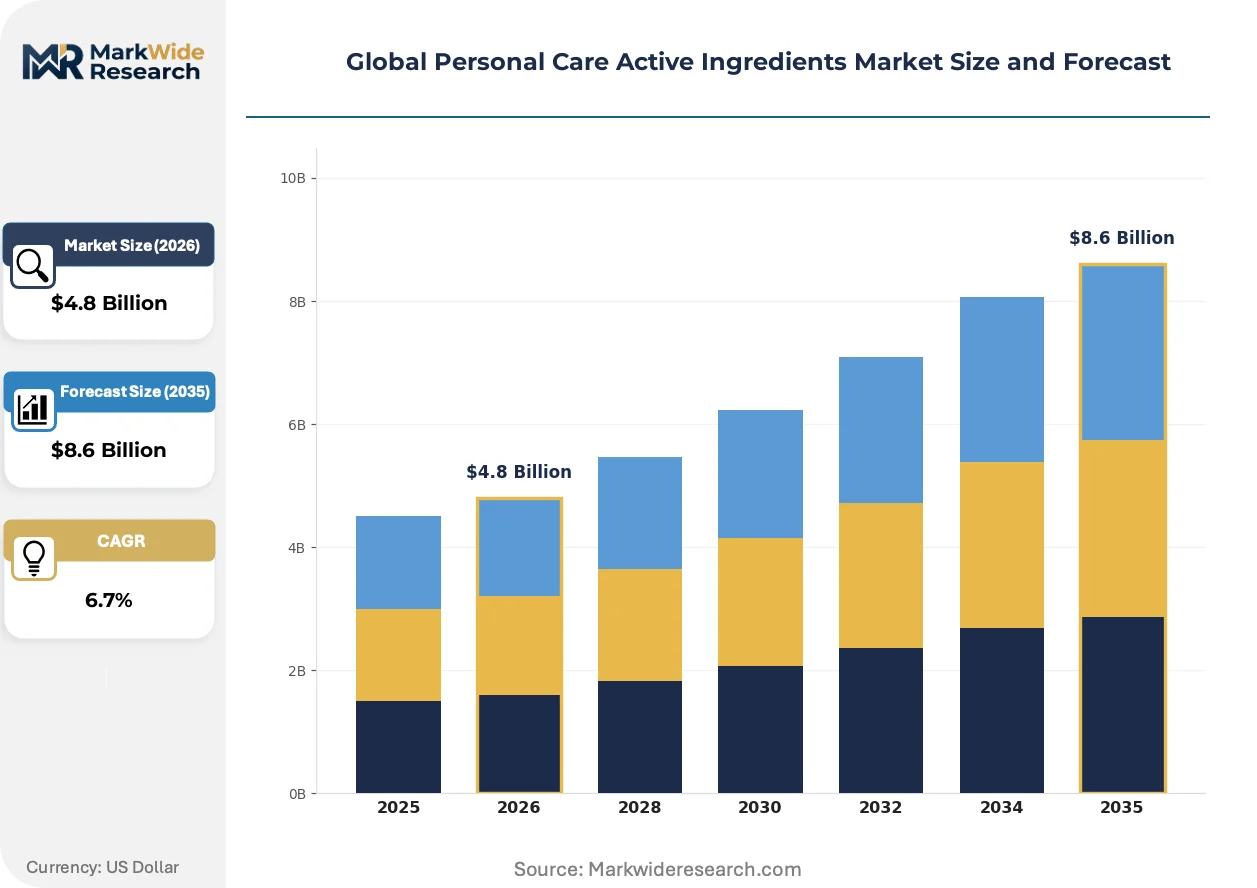
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Emollients, Humectants, Surfactants, Preservatives Application: Skincare, Haircare, Makeup, Fragrance Formulation: Emulsions, Powders, Gels, Sprays End User: Cosmetics Brands, Pharmaceuticals, Contract Manufacturers, Private Labels |
| Companies Covered | Croda International Plc, Dow, BASF SE, Eastman Chemical Co, Solvay SA, Evonik Industries AG, Koninklijke DSM NV, Wacker Chemie AG, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Care Active Ingredients Market Strategic Shifts
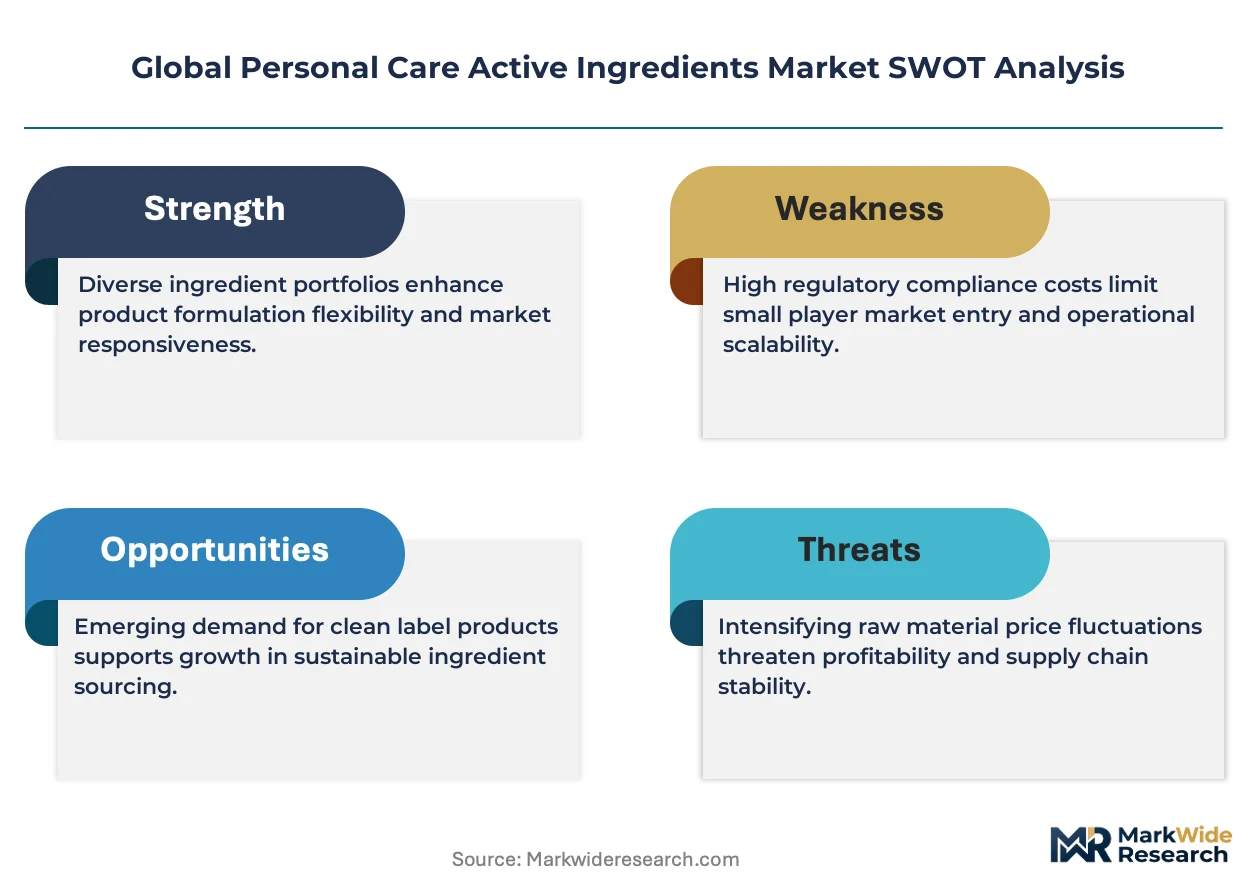
Biotechnology-derived actives are displacing petrochemical feedstocks as the primary innovation vector, while regulatory fragmentation forces parallel compliance investments across multiple jurisdictions.
Artificial intelligence is converging with high-throughput screening to accelerate peptide discovery for anti-aging applications. Specialty chemical suppliers are deploying machine-learning models to predict skin-penetration kinetics before bench synthesis. This convergence is compressing R&D cycles from 24 months to under 12 for validated lead compounds.
REACH authorization requirements for CMR substances are forcing systematic reformulation of hair-dye intermediates and preservative systems. The European Chemicals Agency's 2024-2026 evaluation roadmap targets additional UV filters and antimicrobial agents. Color cosmetics and sun care segments are absorbing the highest compliance costs through accelerated substitution programs.
Beauty brands are consolidating supplier relationships around full-service formulation partners capable of managing regulatory dossiers end-to-end. Contract manufacturers with integrated toxicology and stability-testing capabilities are capturing procurement volume previously fragmented across multiple vendors. This concentration is most pronounced in Germany and France, where mid-size brands lack in-house regulatory affairs capacity.
Global Personal Care Active Ingredients Market Segmentation
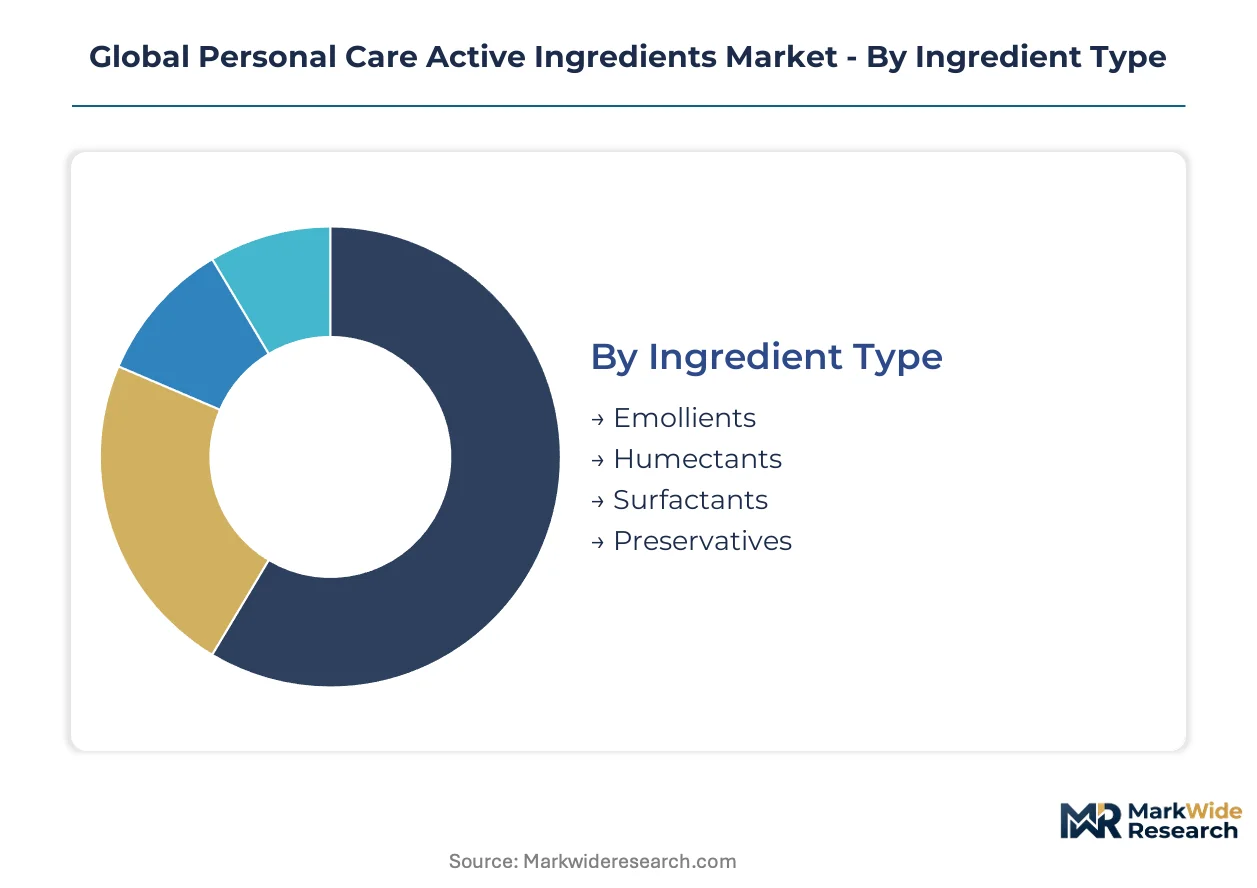
Active ingredient procurement strategies diverge sharply across formulation requirements and end-user sophistication. Segment boundaries determine margin capture, regulatory burden, and supplier relationship intensity.
Ingredient Type:
Capital intensity peaks in surfactant manufacturing, where continuous processing equipment and dedicated fermentation infrastructure lock in fixed costs.
- Emollients:Lipid-based film-formers including esters, fatty alcohols, and plant-derived oils that reduce transepidermal water loss. Demand concentrates in prestige facial moisturizers from French and German beauty houses seeking sensorial differentiation through exotic butter derivatives.
- Humectants:Hygroscopic molecules—glycerin, hyaluronic acid, sorbitol—that bind atmospheric moisture to stratum corneum. Procurement volumes from Chinese domestic brands are accelerating as captive biotech fermentation capacity comes online in Zhejiang and Jiangsu provinces.
- Surfactants:Amphiphilic compounds enabling emulsion stability and cleansing action; sulfate-free alternatives command premium positioning.
- Preservatives:Antimicrobial systems including phenoxyethanol, parabens, and bio-based alternatives; REACH restrictions are forcing systematic substitution cycles.
Most installed capacity flows through emollients. Expansion is steepest in surfactants as sulfate-free and sugar-based alternatives displace legacy petrochemical feedstocks.
Application:
Skincare absorbs the highest ingredient cost per finished unit, while haircare drives volume through rinse-off consumption patterns.
- Skincare:Facial serums, moisturizers, and treatment products requiring actives at 0.5-5% concentration for visible efficacy claims. Korean and Japanese beauty brands are concentrating procurement of peptide complexes and fermented extracts in Seoul and Tokyo innovation corridors.
- Haircare:Shampoos, conditioners, and scalp treatments where cationic surfactants and conditioning polymers dominate formulation costs. Brazilian and Indian consumers are expanding addressable volumes for anti-pollution and UV-protective hair actives.
- Makeup:Color cosmetics incorporating skin-benefit actives—niacinamide, vitamin E—at lower concentrations than dedicated skincare.
- Fragrance:Fine fragrance and functional perfumery with limited active ingredient loading beyond fixatives and carrier systems.
Skincare commands the highest formulation complexity premium. Haircare is gaining share fastest as scalp health positioning converges with facial skincare science.
Formulation:
Emulsion manufacturing requires the most sophisticated stability testing infrastructure, while powder processing offers route-to-market speed for indie brands.
- Emulsions:Oil-in-water and water-in-oil systems delivering controlled release of lipophilic and hydrophilic actives. Italian and Spanish contract manufacturers are specializing in biomimetic emulsion structures that replicate skin barrier lipid organization.
- Powders:Anhydrous formats including pressed pigments, dry shampoos, and active-laden finishing powders; lower regulatory burden accelerates formulation cycles.
- Gels:Hydrocolloid-thickened aqueous systems favored for acne treatments and cooling after-sun applications.
- Sprays:Aerosol and pump-dispersed formats requiring specialized propellant compatibility and particle size engineering for uniform skin deposition.
Emulsion capacity is most concentrated among established European suppliers. Gel formats are expanding most quickly through Southeast Asian manufacturing hubs serving tropical climate preferences.
End User:
Contract manufacturers are consolidating procurement volume as mid-size brands outsource regulatory dossier management and stability testing.
- Cosmetics Brands:Multinationals and indie houses with in-house formulation teams specifying actives directly; L'Oréal and Estée Lauder procurement offices in Singapore and New York coordinate global supplier qualification.
- Pharmaceuticals:Dermocosmetic divisions of drug manufacturers leveraging clinical validation infrastructure for cosmeceutical positioning; Galderma and LEO Pharma operations exemplify this hybrid model.
- Contract Manufacturers:Full-service formulation partners managing end-to-end active sourcing, compounding, and regulatory filing; Swiss and German specialists are capturing share from fragmented distributor networks.
- Private Labels:Retailer-owned beauty brands prioritizing cost-optimized standard actives over proprietary innovation; penetration is deepest in UK and US mass-market retail channels.
Contract manufacturers now process the largest active ingredient volumes. Private label demand is climbing fastest as grocery and pharmacy chains expand beauty shelf space.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as manufacturers relocate fermentation and synthesis capacity to jurisdictions with streamlined chemical notification pathways. Cost-of-compliance gaps between REACH-strict Europe and notification-friendly Asian markets are accelerating captive capacity investments outside the EU.
China
Domestic beauty brands are scaling proprietary peptide fermentation in Zhejiang and Jiangsu provinces, reducing import dependency on European ceramide suppliers. NMPA's 2021 cosmetic registration reform shortened novel ingredient approval timelines, though GB safety standards still diverge from EU REACH thresholds. Shanghai and Hangzhou innovation clusters now host integrated R&D facilities linking biotech fermentation to finished formulation.
United States
FDA oversight of color additives and sunscreen actives is tightening purity documentation requirements for imported cosmetic inputs. Prestige skincare brands headquartered in New York and Los Angeles are accelerating direct procurement of bio-based actives to meet clean-label consumer expectations. The Northeast corridor retains concentration of contract manufacturers with integrated toxicology testing capabilities.
Germany
ECHA's 2024-2026 substance evaluation roadmap is forcing systematic reformulation of preservative systems and UV filters across Rhine-Ruhr chemical manufacturing. BASF SE and Evonik Industries AG anchor specialty surfactant and peptide complex supply to luxury cosmetics houses. Frankfurt and Düsseldorf procurement offices coordinate pan-European supplier qualification for REACH-compliant active ingredient sourcing.
India
CDSCO's streamlined cosmetic ingredient notifications are enabling faster market entry for peptide and botanical active suppliers targeting underpenetrated premium segments. Domestic contract manufacturers in Maharashtra and Gujarat are expanding emulsion compounding capacity for multinational beauty brands. Mumbai specialty chemical clusters are capturing procurement volume previously routed through European distributors.
South Korea
K-beauty export growth is concentrating demand for fermented extract complexes and microbiome-targeted actives in Seoul and Incheon innovation corridors. MFDS cosmetic safety assessments align partially with EU standards, reducing parallel testing burdens for ingredients qualified under REACH. Domestic brands are vertically integrating into captive fermentation capacity for proprietary postbiotic lysate production.
Global Personal Care Active Ingredients Market Competitive Environment
Capacity expansion dominates the current landscape as specialty chemical suppliers build dedicated fermentation infrastructure to capture biotechnology-derived active demand. The vendor base organizes around three strategic tiers: integrated multinational chemical conglomerates with full-platform capabilities, mid-size specialists focused on lipid-based delivery systems or peptide synthesis, and regional contract manufacturers offering regulatory dossier management. M&A activity concentrates on microbiome-targeted technology acquisitions, while strategic partnerships between ingredient suppliers and finished goods brands accelerate co-development of proprietary actives.
Within the integrated multinational tier, BASF SE, Evonik Industries AG, and Croda International Plc exemplify divergent platform strategies. BASF SE represents the biotechnology-forward archetype with fermentation-derived peptide and ceramide capabilities. Evonik Industries AG occupies the specialty surfactant position engineered for sensitive-skin applications. Croda International Plc anchors the lipid-based delivery system segment with bioavailability-enhancing technologies for vitamins and antioxidants.
| Leading Market Players |
|---|
| Croda International Plc |
| Dow |
| BASF SE |
| Eastman Chemical Co |
| Solvay SA |
| Evonik Industries AG |
| Koninklijke DSM NV |
| Wacker Chemie AG |
| Symrise |
| Others |
Value Chain & Pricing Dynamics
Fermentation-derived ceramide feedstock costs cascade through three distinct pricing tiers before reaching finished formulation houses, with Zhejiang biotech clusters commanding premium positioning over Southeast Asian palm-derived alternatives subject to EUDR land-use compliance premiums.
Pricing Analysis
Distributor margins compress most acutely in the standard-grade surfactant tier, where bulk glycolipid procurement from German specialty houses faces direct competition from Indian contract manufacturers. Three-tier pricing structure across premium fermentation-derived peptides, standard petrochemical surfactants, and economy-grade commodity emollients reflects certification grade divergence and REACH dossier completeness. Pricing pressure stems from CDSCO's streamlined notification pathways enabling faster Indian market entry at 15-20% cost advantage. Mass-market private label brands exhibit highest price sensitivity, while prestige skincare houses absorb premium positioning through efficacy-driven procurement.
Supply Chain Analysis
Workforce availability for specialized fermentation technicians concentrates in Germany's Rhine-Ruhr corridor, China's Zhejiang-Jiangsu biotech belt, and South Korea's Seoul-Incheon innovation cluster, creating geographic supply concentration around these three production hubs. Raw material dependencies center on palm-derived fatty alcohols from Southeast Asia, fermentation feedstocks from domestic agricultural surplus, and peptide synthesis reagents from Swiss specialty chemical suppliers. Single-source vulnerability looms for REACH-compliant preservative alternatives facing ECHA's 2024-2026 substance evaluation roadmap. Distribution runs through full-service contract manufacturers with integrated regulatory dossier capabilities, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as consumer procurement shifts decisively toward bio-based actives with transparent supply chain documentation and verified dermatological efficacy claims.
For Market Incumbents: Lock in captive fermentation capacity through backward integration into Zhejiang and Jiangsu biotech corridors before CDSCO notification advantages erode cost premiums. BASF SE and Evonik Industries AG must accelerate peptide synthesis platform investments to defend against Chinese domestic brands scaling proprietary active R&D. Certification investment in ECHA-compliant preservative alternatives represents the critical lever for maintaining European market access.
For New Entrants and Emerging Players: Begin with microbiome-targeted postbiotic lysates in India's underpenetrated premium segment, where CDSCO's streamlined cosmetic ingredient notifications enable faster market entry than REACH-constrained European pathways. Scalp health applications in Brazilian and Indian haircare offer the most penetrable white space as consumers extend facial skincare science to hair treatment protocols. Direct-to-brand digital channels disintermediating traditional distributors provide the optimal go-to-market angle for mid-size cosmetics manufacturers.
For Investors and Strategic Acquirers: Consolidation pressure builds where contract manufacturers possess integrated toxicology and stability-testing capabilities that mid-size brands cannot replicate in-house. Long-term viability favors full-service formulation partners managing end-to-end regulatory dossiers across divergent NMPA, FDA, and REACH compliance pathways. Acquisition targets should prioritize Swiss and German specialists with captive fermentation infrastructure. The signal to watch is ECHA's substance evaluation roadmap acceleration forcing systematic reformulation cycles and supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captive ceramide and peptide production in Zhejiang reduces import dependency on European suppliers. |
| Regulatory Dossier End-to-End Management | Swiss contract manufacturers capture procurement volume from fragmented distributor networks. |
| Microbiome-Targeted Active Development | Postbiotic lysates open formulation white space beyond conventional moisturization claims. |
| Direct-to-Brand Digital Channel Expansion | Specialty ingredient marketplaces disintermediate traditional distributors for mid-size cosmetics manufacturers. |
| REACH-Compliant Preservative Substitution | ECHA's 2024-2026 evaluation roadmap forces systematic reformulation of legacy antimicrobial systems. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic formulation chemists, procurement leads at multinational beauty houses, regulatory affairs specialists navigating NMPA and REACH divergence, contract manufacturing operations heads, and biotech fermentation platform directors with secondary validation against customs trade data, ECHA substance evaluation databases, CDSCO cosmetic notification records, and SEC filings from listed specialty chemical suppliers. Bottom-up volume modeling triangulated against top-down value estimates across ingredient type, application, formulation, and end-user segments.
Comparable-period anchoring established baseline reference points from historical procurement patterns before projecting forward across the analysis window. Segmentation dimensions modeled included ingredient technology platform, end-use application complexity, regulatory compliance tier, and geographic production cluster. CAGRs derived from weighted average growth assumptions across these dimensions, with specific inputs capturing biotechnology platform adoption curves and REACH-driven reformulation cycle timing.
Several conditions sit outside the modeled scope, including unforeseen ECHA substance evaluation acceleration, NMPA regulatory pathway reversals, and palm oil supply disruptions from Southeast Asian climate events. Forecasts reflect stated assumptions about continued clean-label consumer preference evolution and biotech fermentation cost reduction trajectories. Material deviation in ECHA evaluation timelines or Chinese domestic brand R&D scaling warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Rice Bran Oil Market
Ingredients
Self-Rising Flour Market
Ingredients
Colombia Food Ingredients Market
Ingredients
Xylooligosaccharide Market
Ingredients
South America Vegetable Oil Market
Ingredients
Industrial Starch Market
Ingredients
RTD/High Strength Premixes Market
Ingredients
Casein Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Pea Fiber Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Psyllium Husk Powder Market
Ingredients
North America Dairy Protein Market
Ingredients
Europe Amino Acid Market
Ingredients
Mastic Gum Market
Ingredients
Fucoidan Extract Market