
 Dairy Ingredients Market | 2026-2036
Dairy Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Ingredients Market Intelligence
Market Context
New Zealand is narrowing its once-dominant whey protein export advantage as European cooperatives expand lactose refining capacity. Fonterra Co-operative Group leverages its farmer-owned structure to control raw milk sourcing across the Southern Hemisphere. FrieslandCampina anchors its position through backward integration into Dutch dairy farming collectives. Arla Foods competes on clean-label whey isolates for Scandinavian infant nutrition brands.
Technical Profile and Segment Dynamics
Dairy ingredients comprise proteins, fats, carbohydrates, and minerals extracted from fluid milk through separation, evaporation, drying, or membrane filtration, typically achieving protein concentrations from 34% in whey concentrates to over 90% in whey protein isolates. These inputs provide emulsification, gelation, foaming, and nutritional fortification across formulated foods. Milk powder retains the largest revenue footprint among product types due to its cost efficiency in emerging market supply chains, while whey protein commands premium positioning within sports nutrition applications. Infant nutrition channels generate the highest margin pools among end users, though food and beverage manufacturers move the greatest absolute tonnage through direct sales agreements.
Regulatory Environment
EU EFSA standards govern protein content claims and allergen labeling across European dairy ingredient shipments, while FDA Grade A Pasteurized Milk Ordinance dictates pathogen thresholds for US-sourced milk powders entering interstate commerce. Codex Alimentarius guidelines harmonize international trade specifications for whey protein and lactose derivatives. Stakeholders must monitor evolving front-of-pack labeling mandates in major import markets, as these rules reshape formulation decisions and supplier qualification criteria without warning.
Market Dynamics
EU F-Gas Regulation and the EU Green Deal are compressing processing margins across European dairy facilities while simultaneously accelerating capital deployment into energy-efficient membrane filtration systems.
Growth Catalysts
- Sports Nutrition Absorption:Athletic supplement brands now absorb larger whey protein volumes than a decade ago, pulling concentrate and isolate grades through dedicated supply contracts.
- India Urbanization:Packaged food consumption expands in Indian metropolitan corridors, driving local processors to scale milk powder output for domestic distribution networks.
- Clean-Label Infant Nutrition:Scandinavian infant formula brands demand whey isolates with minimal processing residues, creating specification premiums for certified suppliers.
Market Restraints
- Raw Milk Input Volatility:Fluid milk prices fluctuate with seasonal pasture conditions across Oceania and European cooperative territories, compressing ingredient processor margins without warning.
- Supply Concentration Risk:New Zealand's once-dominant whey protein export position narrows as European lactose refining capacity expands, yet Southern Hemisphere sourcing still anchors global spot markets.
- Regulatory Friction:FDA Grade A Pasteurized Milk Ordinance pathogen thresholds create compliance barriers for US-sourced milk powders entering interstate commerce, delaying shipment clearances.
Strategic Opportunities
- India Underpenetration:Domestic dairy ingredient processing remains below per-capita consumption potential in tier-two Indian cities, offering first-mover positioning for localized drying facilities.
- EU Regulatory Tailwind:EU Green Deal carbon accounting mandates favor processors with captive biogas generation from whey permeate, rewarding integrated operations with compliance cost advantages.
- Membrane-Conveyance Convergence:Advanced ceramic membranes combined with automated CIP systems enable continuous protein fractionation without batch downtime, reshaping plant economics.
Industry Challenges
- Membrane Technician Scarcity:Specialized operators capable of troubleshooting spiral-wound and ceramic membrane fouling remain concentrated in Dutch and Danish technical institutes, limiting facility expansion.
- Organic Certification Timelines:EU organic dairy ingredient accreditation requires 24-month conversion periods for supplier farms, locking processors out of premium channels during transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Ingredients Market |
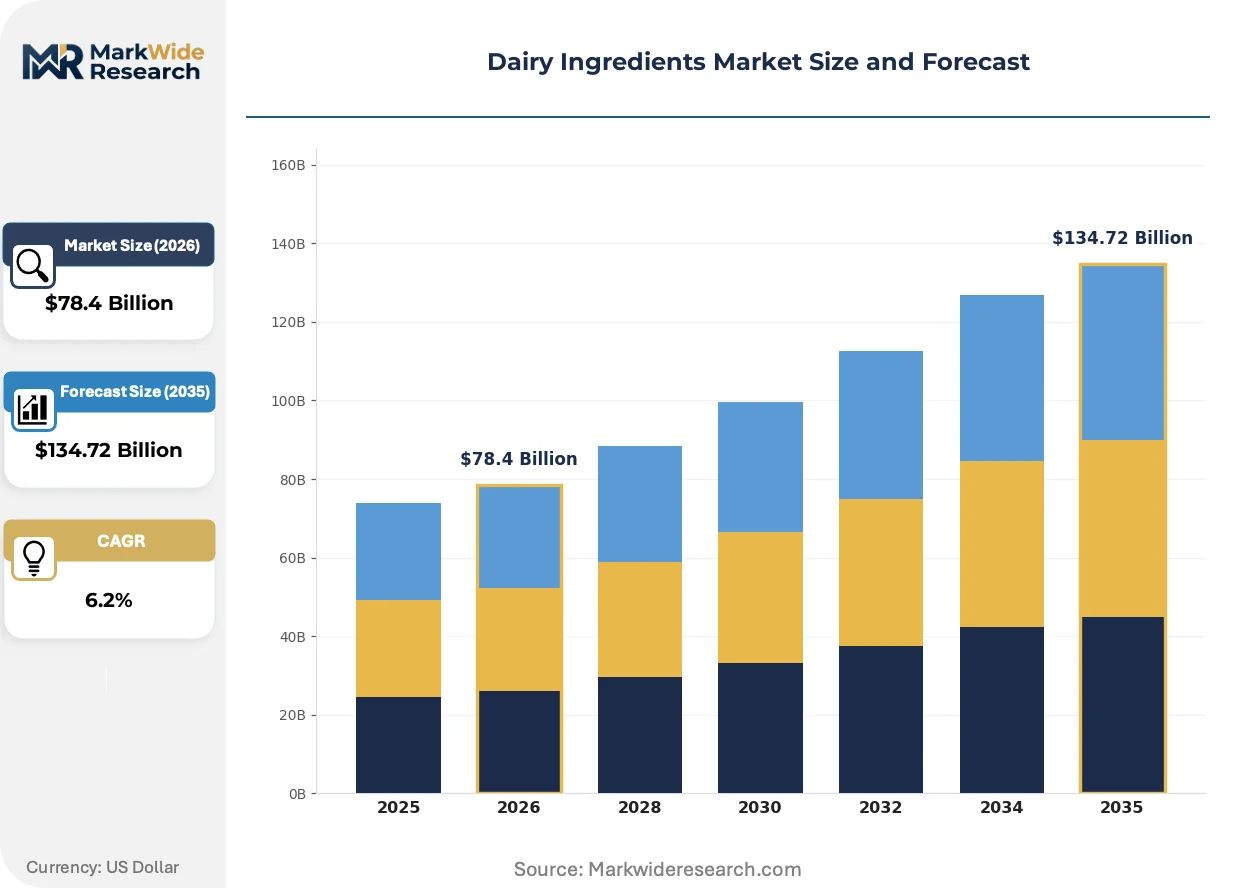
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Powder, Whey Protein, Casein, Butterfat, Lactose Application: Bakery Products, Infant Nutrition, Sports Nutrition, Confectionery, Beverages End User: Dairy Processors, Food & Beverage Manufacturers, Nutraceutical Companies, Animal Feed Producers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers, Specialty Stores |
| Companies Covered | Fonterra Co-operative Group, FrieslandCampina, Arla Foods, Glanbia PLC, Dairy Farmers of America, Groupe Lactalis, Saputo Inc, Sodiaal Group, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Ingredients Market Strategic Shifts & Innovations
Membrane filtration advances and regulatory carbon accounting are compressing traditional processing economics while enabling new protein fractionation capabilities across dairy ingredient supply chains.
Precision ceramic microfiltration systems operating at 50°C with pH-stabilized feed streams are rendering obsolete traditional heat-acid whey protein recovery methods. Infant nutrition manufacturers in Denmark and the Netherlands have adopted these systems at pilot scale since 2023. The technology is rendering obsolete batch processing economics by enabling continuous operation with 40% lower energy intensity per kilogram of isolate output.
EU F-Gas Regulation phasedown schedules are forcing refrigeration-dependent dairy dryers to retrofit with ammonia or CO2 cascade systems. Processing facilities in northern Germany and the Netherlands face 2027 compliance deadlines that compress capital planning cycles. Spray-drying operations with legacy HFC refrigerants confront equipment replacement costs that favor greenfield sites over brownfield retrofits.
Direct procurement contracts between ingredient processors and sports nutrition formulators are displacing traditional distributor-mediated spot purchasing. North American athletic supplement brands now negotiate 18-month protein concentrate agreements with fixed volume floors. This pattern concentrates most visibly in California and Texas formulation clusters where brands seek supply security over price arbitrage.
Dairy Ingredients Market Segmentation
Dairy ingredient procurement cycles vary dramatically across product categories, with perishable concentrates turning weekly while milk powder inventories stretch across quarters. Understanding velocity differentials between segments enables processors to align working capital deployment with margin capture opportunities.
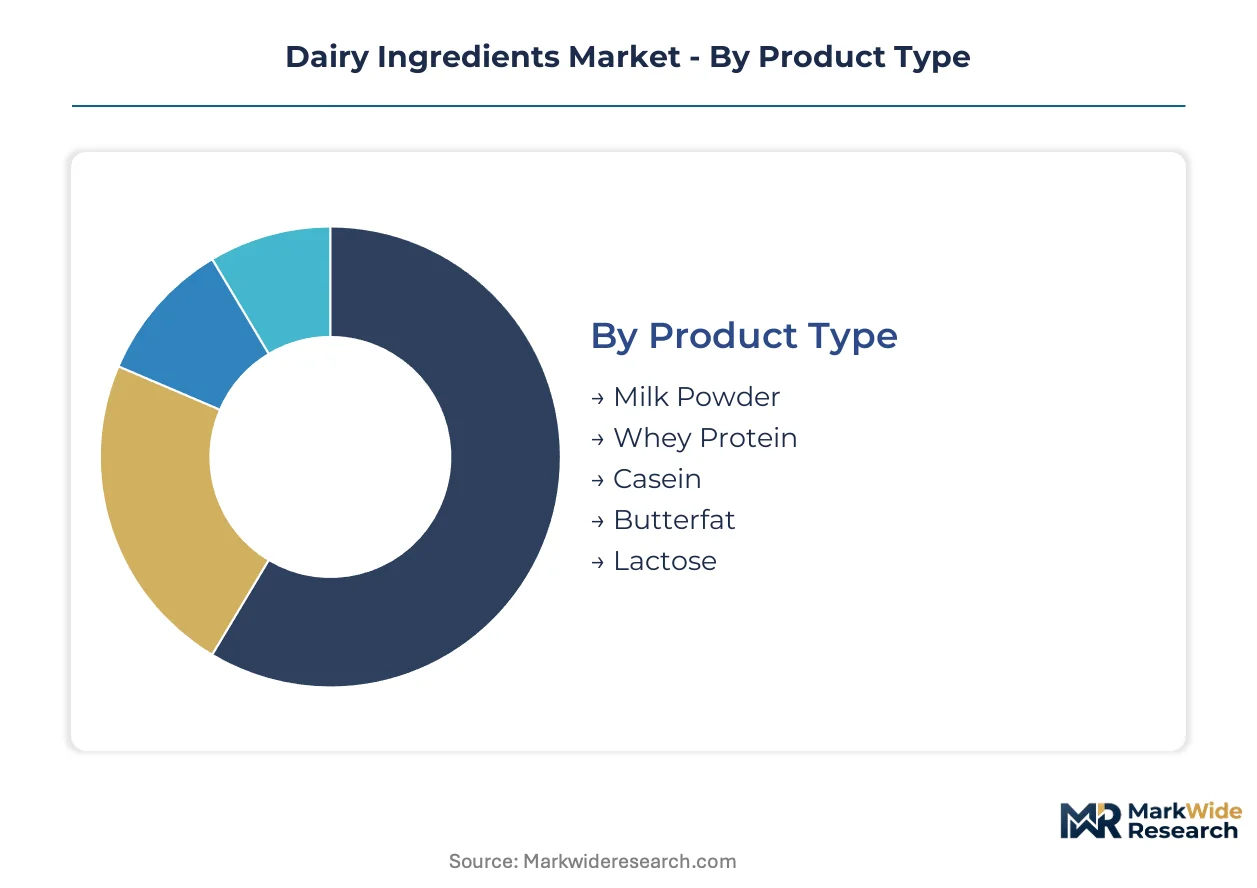
Product Type:
Whey protein isolates rotate through inventory fastest due to sports nutrition contract cadences, while milk powder sits longest in emerging market buffer stocks.
- Milk Powder:Full-fat and skim varieties retain moisture specifications below 4% through roller or spray-drying processes. Indian urban distributors now absorb the largest volume increases as packaged dairy penetration climbs in tier-two cities.
- Whey Protein:Concentrates at 34-80% protein and isolates exceeding 90% purity serve distinct formulation tiers. North American sports nutrition brands in California and Texas formulation clusters now negotiate 18-month supply agreements with fixed volume floors.
- Casein:Micellar and acid-precipitated variants provide slow-digesting protein matrices for medical nutrition applications.
- Butterfat:Anhydrous milk fat and butter oil concentrate deliver standardized lipid content for confectionery tempering.
- Lactose:Pharmaceutical-grade crystals and edible-grade powders filter into infant formula and tablet excipients respectively.
Milk powder dominates installed base. Whey protein is where expansion concentrates.
Application:
Infant nutrition commands the steepest specification premiums, while bakery applications move the greatest absolute tonnage through commodity-grade channels.
- Bakery Products:Milk powders and whey permeates strengthen dough hydration and crust browning at industrial scale. Brazilian and Mexican panaderia chains now specify medium-heat nonfat dry milk for consistent protein functionality.
- Infant Nutrition:Demineralized whey and alpha-lactalbumin fractions must meet EFSA protein content claims and allergen labeling standards. Scandinavian brands in Denmark and Sweden demand whey isolates with minimal processing residues, creating specification premiums for certified EU suppliers.
- Sports Nutrition:Ready-to-drink shakes and powder blends pull isolate and hydrolysate grades through dedicated supply contracts.
- Confectionery:Lactose and butterfat control crystallization kinetics in chocolate and caramel matrices.
- Beverages:UHT milk bases and protein-fortified drinks utilize milk protein concentrates for emulsion stability.
Bakery applications anchor volume throughput. Infant nutrition channels capture margin expansion.
End User:
Direct sales to food and beverage manufacturers compress distributor margins, while nutraceutical companies absorb premium isolates through specialized procurement teams.
- Dairy Processors:Integrated cooperatives in the Netherlands and New Zealand fractionate fluid milk into ingredient streams for captive use and third-party sale.
- Food & Beverage Manufacturers:CPG giants in Germany and France negotiate annual milk powder contracts with volume flexibility clauses.
- Nutraceutical Companies:Sports and medical nutrition formulators in Switzerland and California source whey isolates through direct technical partnerships.
- Animal Feed Producers:Whey permeate and lactose byproducts enter calf milk replacer and pet food formulations.
Food and beverage manufacturers dominate procurement volume. Nutraceutical companies concentrate premium specification demand.
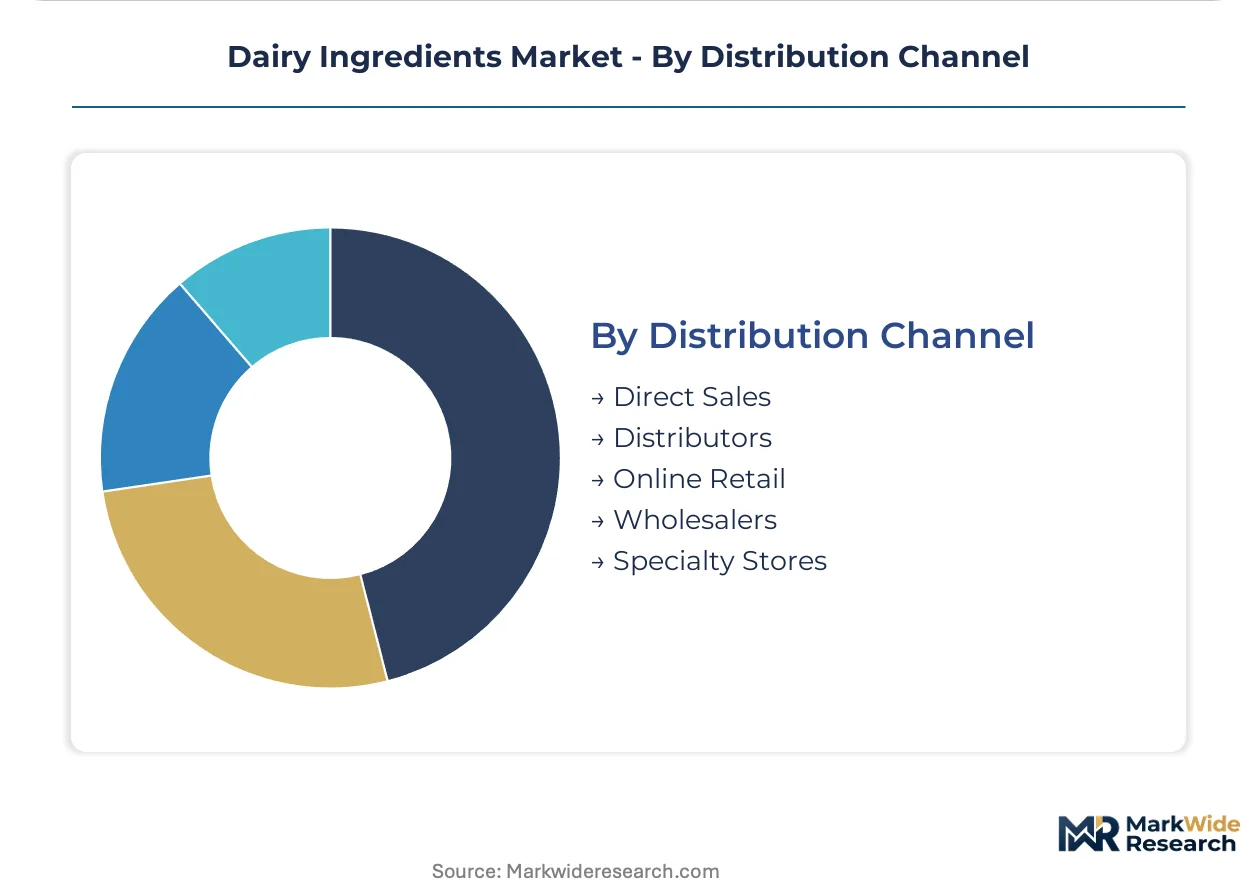
Distribution Channel:
Direct sales agreements displace spot purchasing most aggressively in North American protein markets, while Indian domestic networks still route heavily through layered wholesale structures.
- Direct Sales:Processor-to-manufacturer contracts lock in 12-24 month pricing with technical service attachments.
- Distributors:Regional warehouses in Germany and Poland buffer just-in-time deliveries for mid-sized bakery and confectionery accounts.
- Online Retail:Bulk ingredient platforms serve small-scale sports nutrition startups in Texas and Florida.
- Wholesalers:Traditional tiered networks dominate Indian tier-three city penetration for milk powder.
- Specialty Stores:Organic and clean-label ingredient boutiques in Copenhagen and Amsterdam supply craft chocolate makers.
Direct sales channels capture contract value. Distributor networks retain geographic coverage advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA protein content claims and allergen labeling standards govern European dairy ingredient shipments, while FDA Grade A Pasteurized Milk Ordinance pathogen thresholds dictate US-sourced milk powder clearances. Processing economics diverge sharply across geographies.
United States
North American sports nutrition brands in California and Texas formulation clusters negotiate 18-month whey protein concentrate agreements with fixed volume floors. FDA Grade A Pasteurized Milk Ordinance enforcement creates compliance barriers for interstate milk powder shipments. Dairy Farmers of America anchors procurement through cooperative structures across Midwest processing corridors.
Germany
EU F-Gas Regulation phasedown schedules force northern German spray-drying facilities to retrofit with ammonia cascade systems by 2027. EU Green Deal carbon accounting mandates favor processors with captive biogas generation from whey permeate. CPG giants in Bavaria and North Rhine-Westphalia negotiate annual milk powder contracts with volume flexibility clauses.
India
FSSAI standards govern packaged dairy penetration as urban consumption expands in tier-two metropolitan corridors. PLI scheme incentives support domestic processors scaling milk powder output for distribution networks. Gujarat and Maharashtra host concentrated drying facility investments targeting underpenetrated tier-three city markets.
Netherlands
REACH compliance and EFSA standards shape whey isolate specifications for Scandinavian infant nutrition brands. FrieslandCampina anchors backward integration into Dutch dairy farming collectives. Randstad ceramic membrane filtration clusters enable continuous protein fractionation with 40% lower energy intensity per kilogram of isolate output.
New Zealand
Fonterra Co-operative Group leverages farmer-owned structures to control raw milk sourcing across Southern Hemisphere territories. Seasonal pasture conditions create fluid milk price volatility that compresses processor margins without warning. Canterbury and Waikato processing clusters face narrowing whey protein export advantages as European lactose refining capacity expands.
Dairy Ingredients Market Key Industry Players
Farmer-owned cooperatives and publicly traded ingredient specialists split the market between captive raw milk control and flexible procurement strategies. Processing scale concentrates among tier-one operators with integrated membrane filtration capabilities. Two archetypes dominate: vertically integrated cooperatives securing upstream milk supply, and technology-focused specialists commanding premium isolate specifications. Competitive moves center on membrane filtration capacity expansion and direct procurement contract displacement of distributor-mediated spot purchasing.
Within the cooperative archetype, Fonterra Co-operative Group exemplifies farmer-owned raw milk control across Southern Hemisphere sourcing territories. FrieslandCampina occupies a position anchoring Dutch dairy farming collective integration. Among publicly traded specialists, Glanbia PLC represents the technology-focused tier targeting sports nutrition contract channels. Arla Foods sits within the clean-label premium segment serving Scandinavian infant nutrition specification requirements. These three anchors illustrate the strategic divergence between upstream supply security and downstream formulation partnership models.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| FrieslandCampina |
| Arla Foods |
| Glanbia PLC |
| Dairy Farmers of America |
| Groupe Lactalis |
| Saputo Inc |
| Sodiaal Group |
| Kerry Group |
| Others |
Cost & Logistics Intelligence
New Zealand's Fonterra Co-operative Group anchors global whey protein spot markets through farmer-owned raw milk control, concentrating upstream supply power that flows downstream into premium infant nutrition and sports nutrition margin pools.
Pricing Analysis
Oceania-to-Europe price spreads for whey protein isolates compress when European lactose refining capacity expands, yet widen during Southern Hemisphere drought seasons. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified infant nutrition grades from commodity bakery concentrates and animal feed permeates. Pricing pressure stems from EU F-Gas Regulation compliance costs that retrofit legacy spray-dryers with ammonia cascade systems. Food and beverage manufacturers exhibit highest price sensitivity through annual contract renegotiations, while nutraceutical companies absorb specification premiums for clean-label isolates.
Supply Chain Analysis
Fluid milk feedstock draws from New Zealand, the Netherlands, and India as primary sourcing territories, with seasonal pasture volatility creating margin compression without warning. Raw material dependencies center on membrane filtration ceramics, HFC refrigerant alternatives, and pharmaceutical-grade lactose crystals. Single-source vulnerability concentrates in Dutch and Danish technical institutes supplying membrane technician expertise. Distribution runs through direct processor-to-manufacturer contracts displacing traditional spot purchasing, particularly in North American sports nutrition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized operators capable of troubleshooting ceramic membrane fouling remain concentrated in limited technical institutes, creating a structural bottleneck that constrains facility expansion and rewards early capability investments.
For Market Incumbents: Insulate margin pools by deploying captive biogas generation from whey permeate to satisfy EU Green Deal carbon accounting mandates, while acquiring membrane filtration engineering talent ahead of competitor expansion. Regulatory friction from FDA Grade A Pasteurized Milk Ordinance pathogen thresholds favors processors with pre-qualified interstate clearance infrastructure. For New Entrants and Emerging Players: Build out localized drying capacity in tier-two Indian cities where FSSAI-compliant packaged dairy penetration lags per-capita consumption potential, leveraging PLI scheme incentives to undercut established import-dependent distributors. Direct technical partnerships with Scandinavian infant nutrition brands offer specification premium capture unavailable through commodity channels. For Investors and Strategic Acquirers: Capital is best deployed toward technology-focused specialists with integrated membrane filtration capabilities and established sports nutrition contract channels, as these archetypes command durable pricing power across the analysis window. Watch for EU F-Gas Regulation 2027 compliance deadlines triggering distressed asset availability in northern German processing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Continuous protein fractionation with 40% lower energy intensity reshapes plant economics at Randstad clusters. |
| Backward Integration into Dairy Farming Collectives | FrieslandCampina's Dutch cooperative model secures raw milk supply certainty against seasonal volatility. |
| Direct Procurement Contract Displacement | Eighteen-month fixed-volume agreements with California sports nutrition brands reduce spot market exposure. |
| EU Green Deal Compliance Infrastructure | Captive biogas generation from whey permeate creates regulatory cost advantages for integrated processors. |
| Specialized Technical Talent Acquisition | Membrane technician scarcity in Dutch and Danish institutes limits competitor facility expansion timelines. |
Research Approach
Desk research of customs trade databases, SEC 10-K filings, and EFSA regulatory guidance preceded structured interviews with dairy processing plant managers, sports nutrition procurement leads, membrane filtration engineering directors, and Indian distribution channel partners. Primary fieldwork across New Zealand cooperative territories, Dutch Randstad processing clusters, and Gujarat drying facilities combined with secondary validation from Fonterra milk price announcements and EU F-Gas Regulation implementation timelines. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Assumptions held fixed include EU Green Deal carbon accounting enforcement timelines and FDA Grade A Pasteurized Milk Ordinance pathogen threshold maintenance, while fluid milk price volatility and membrane technology adoption curves were varied across sensitivity bands. Segmentation dimensions spanned product type, application, end user, and distribution channel, with regional regulatory cluster effects modeled separately. CAGRs derived from volume trajectory analysis incorporating sports nutrition contract cadences and Indian urbanization patterns.
Stress conditions across Oceania drought frequency, EU refrigeration retrofit cost inflation, and membrane technician training pipeline capacity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology adoption S-curves. Cross-checking against Fonterra Global Dairy Trade auction price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
African Brewing Enzymes Market
Ingredients
Australia Soy Protein Market
Ingredients
Soy Peptones Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Astragalus Root Extract Market
Ingredients
Non-GMO Soya Market
Ingredients
Lime Seed Oils Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Savory Ingredients Market
Ingredients
Mustard Oil Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Tuberose Extract Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Europe Pea Starch Market
Ingredients
Psyllium Products Market