
 Plant Protein Ingredients Market | 2026-2036
Plant Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Protein Ingredients Market Analysis
Buyer concentration in the plant protein ingredients space is decoupling from legacy food conglomerates toward specialized sports nutrition and alt-meat startups. Cargill leverages its oilseed crushing infrastructure to secure cost-advantaged soy protein isolate supply chains across North American processing corridors. Kerry Group anchors its position through flavor-mask technology that neutralizes off-notes in pea and rice protein formulations, a capability that commands premium placement in beverage applications. Roquette Frères dominates European pea protein extraction with wet-fractionation assets that achieve higher protein purity rates than conventional dry-process competitors.
Plant protein ingredients comprise extracted, concentrated, or isolated protein fractions derived from oilseeds, legumes, and cereal grains, typically achieving protein content ranging from 50% in concentrates to 90% in isolates through aqueous or alkaline extraction followed by isoelectric precipitation. These ingredients function as structural binders, emulsifiers, and nutritional fortifiers in formulated foods, pet diets, and cosmetic bases. Soy protein retains the largest volume footprint among product types due to decades of infrastructure amortization and established agronomy, though pea protein is capturing the fastest growth trajectory as formulators seek allergen-friendly alternatives with favorable amino acid profiles. Within application segments, food and beverages holds the deepest margin pool because branded finished goods command pricing power that raw ingredient suppliers cannot access directly.
FDA GRAS notifications and USDA organic certification govern market access in the United States, while EFSA novel food authorizations and EU Green Deal protein diversification mandates shape European product development timelines and subsidy eligibility. REACH compliance for processing aids and CSRD sustainability disclosure requirements are adding compliance layers that favor suppliers with verified carbon footprint data and deforestation-free supply chains. Stakeholders must monitor how evolving allergen labeling thresholds and precision-fermentation regulatory classifications will redraw competitive boundaries between extracted and biomanufactured protein sources.
Market Dynamics
The EU Green Deal's protein diversification mandates are redirecting agricultural subsidies toward legume cultivation, forcing ingredient suppliers to reconfigure sourcing networks and processing capacity allocation.
Growth Catalysts
- Precision fermentation scale-up:Berlin and Hamburg food-tech clusters are expanding extraction capacity for pea and fava protein, drawing venture capital into domestic processing infrastructure.
- EU subsidy reallocation:The Common Agricultural Policy now ties direct payments to protein crop rotation, incentivizing farmers to shift hectarage from cereals to legumes.
- Sports nutrition procurement surge:Functional beverage and supplement brands now contract larger volumes than legacy food processors, creating dedicated supply lines with premium specifications.
Market Restraints
- Input cost volatility:Yellow pea prices fluctuate with Canadian prairie weather patterns, compressing margins for European processors dependent on North American raw material imports.
- Supply concentration risk:Wet-fractionation assets achieving protein purity above 85% remain concentrated among three European operators, creating bottleneck vulnerability.
- Technical limitation:Off-note masking in pea and rice protein formulations requires proprietary flavor systems that add cost layers incompatible with economy-tier positioning.
Strategic Opportunities
- Underpenetrated pet nutrition:Germany's premium pet food manufacturers are reformulating with fava protein to meet novel protein claims, opening a channel with higher tolerance for ingredient premiums.
- CSRD disclosure tailwind:Corporate Sustainability Reporting Directive requirements favor suppliers with verified Scope 3 carbon data, rewarding early investments in farm-level traceability systems.
- Cosmetic base convergence:Hydrolyzed rice protein is crossing from food into hair care formulations, enabled by shared emulsification chemistry with existing personal care ingredient portfolios.
Industry Challenges
- Isoelectric precipitation expertise gap:Wet-fractionation plant operators require specialized protein chemistry training that existing food engineering programs inadequately supply.
- EFSA novel food timeline compression:Accelerated application backlogs are extending authorization windows for emerging protein sources, delaying commercial launch schedules.
- Legacy equipment retrofit costs:Oilseed crushing infrastructure requires capital-intensive modification to handle smaller-seeded legumes with different hull composition and oil content profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Protein Ingredients Market |
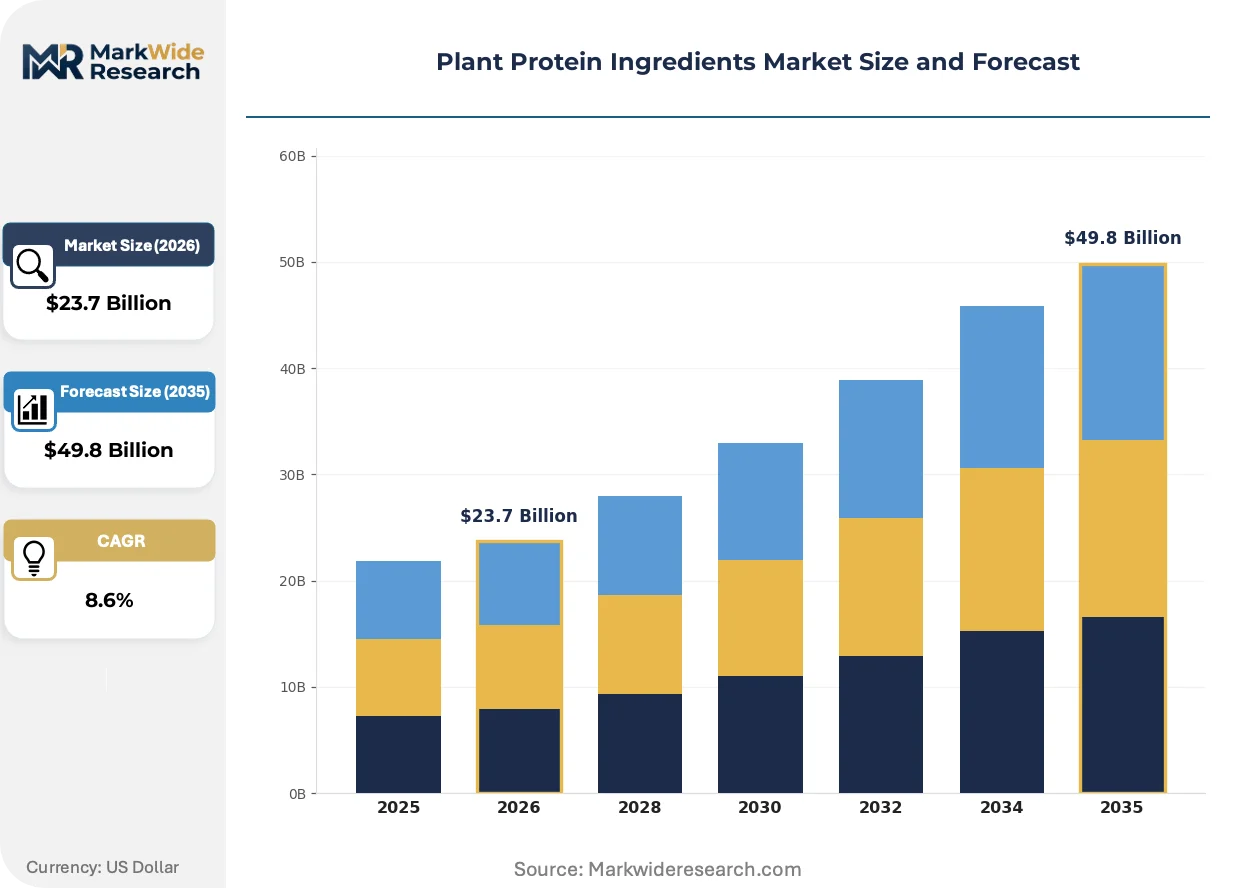
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein, Pea Protein, Rice Protein, Wheat Protein Application: Food & Beverages, Animal Feed, Nutraceuticals, Personal Care Form: Powder, Isolate, Concentrate, Textured End User: Vegetarians, Vegans, Health-Conscious Consumers, Athletes |
| Companies Covered | Cargill, Archer Daniels Midland Company, Kerry Group, Glanbia PLC, Roquette Frères, International Flavors & Fragrances, Ingredion, Axiom Foods, Prinova Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Protein Ingredients Market Emerging Trajectories
Formulation science and bioprocessing advances are compressing the performance gap between plant and animal proteins, enabling structural applications previously restricted to dairy and egg fractions.
Precision fermentation is electrifying protein ingredient manufacturing by enabling microbial production of specific amino acid sequences without agricultural cultivation. Sports nutrition brands are adopting these ingredients for rapid formulation iteration cycles. The technology is compressing development timelines from growing seasons to bioreactor batch cycles, threatening traditional extraction-based suppliers with obsolescence in premium segments.
CSRD sustainability disclosure mandates are forcing ingredient suppliers to deploy blockchain-enabled farm-to-facility traceability systems. ESG audit requirements now extend to deforestation-free supply chain verification for soy derivatives. German food processors are responding by consolidating procurement around suppliers with ISO 14064-certified carbon accounting, excluding smaller operators lacking compliance infrastructure.
Buyer concentration among alt-meat startups is fragmenting procurement patterns away from long-term supply agreements. These emerging manufacturers favor spot purchasing with flexible volume commitments to manage formulation experimentation risk. Hamburg's food-tech incubator networks are facilitating direct supplier-startup matching, bypassing traditional ingredient distribution channels and compressing price discovery transparency.
Plant Protein Ingredients Market Segmentation
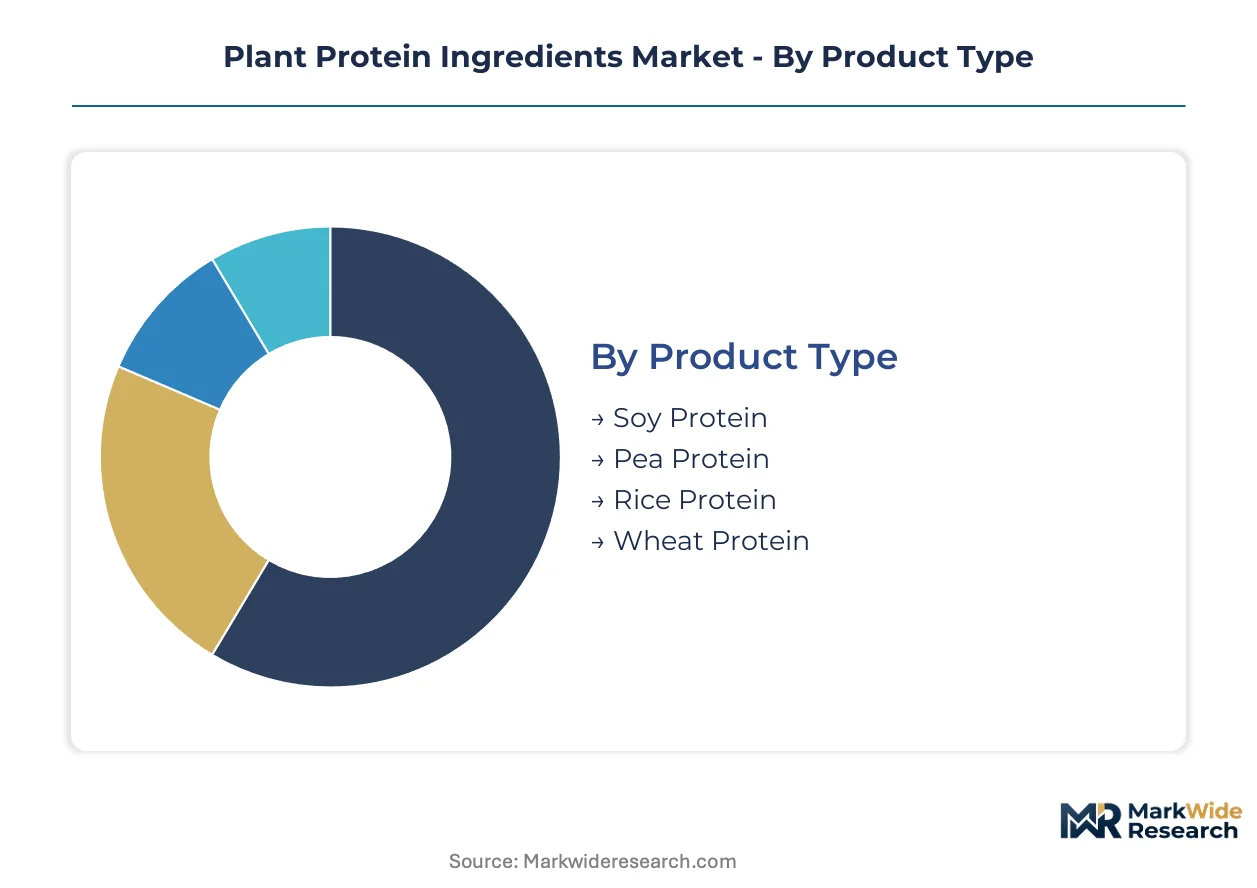
Plant protein ingredient procurement varies sharply across certification requirements, with EFSA novel food authorizations governing emerging sources while GRAS status accelerates soy and wheat protein deployment. Formulation specifications diverge between sports nutrition brands demanding isolate-grade purity and pet food processors tolerating concentrate-tier specifications.
Product Type:
EFSA novel food classifications apply differentially across this category, with pea and rice protein facing extended authorization timelines while soy and wheat protein benefit from decades of established regulatory precedent.
- Soy Protein:Isolates achieve protein content exceeding 90% through alkaline extraction followed by isoelectric precipitation, with defatted flakes serving as the standard feedstock. Demand concentrates in North American sports nutrition manufacturing corridors, where established crushing infrastructure delivers cost-advantaged supply chains that newer legume proteins cannot replicate.
- Pea Protein:Wet-fractionation processing yields isolates with superior amino acid completeness compared to dry-milled alternatives, though off-note masking requires proprietary flavor systems. Berlin and Hamburg food-tech clusters are scaling extraction capacity for this segment, drawn by EU Green Deal protein diversification subsidies that favor domestic legume cultivation over imported soy.
- Rice Protein:Hypoallergenic positioning supports premium placement in pediatric and senior nutrition formulations.
- Wheat Protein:Vital wheat gluten retains dominance in European bakery applications despite celiac-labeling constraints.
Soy protein sits at the top of the volume ranking, with pea protein climbing the fastest.
Application:
Margin structures diverge dramatically across this category, with branded finished goods in food and beverages capturing value that raw ingredient suppliers cannot access directly.
- Food & Beverages:Alt-meat startups and precision-fermentation facilities in Germany are driving formulation innovation, with extruded texturized proteins replacing structural functions previously served by egg and dairy fractions. Hamburg's food-tech incubators facilitate direct supplier matching for these emerging manufacturers, bypassing traditional distribution channels.
- Animal Feed:Premium pet food manufacturers in Germany are reformulating with fava and pea protein to meet novel protein claims, accepting ingredient premiums that economy-tier livestock feed operations reject.
- Nutraceuticals:Sports nutrition brands now contract larger volumes than legacy food processors, creating dedicated supply lines with premium specifications for isolate-grade materials.
- Personal Care:Hydrolyzed rice protein is crossing from food into hair care formulations, enabled by shared emulsification chemistry with existing personal care ingredient portfolios.
Food and beverages commands the deepest margin pool, with nutraceuticals gaining share fastest among procurement-intensive segments.
Form:
Processing intensity and capital requirements stratify competitive positioning across this category, with wet-fractionation assets for isolate production remaining concentrated among a limited set of European operators.
- Powder:Spray-dried concentrates serve economy-tier positioning in bulk sports nutrition applications where solubility requirements are less stringent.
- Isolate:Protein purity above 85% requires specialized wet-fractionation infrastructure that achieves superior amino acid profiles and reduced off-notes compared to dry-process alternatives.
- Concentrate:Protein content ranging from 50% to 70% offers cost-efficient fortification for processed foods where complete substitution of animal protein is not required.
- Textured:Extruded formats replicate meat-like fibrous structures through thermoplastic processing, with Berlin-based alt-meat startups driving demand for customized particle size distributions.
Isolate commands premium positioning, with textured formats expanding most quickly on alt-meat formulation demand.
End User:
Procurement patterns fragment across this category, with athlete-focused brands demanding certificate-of-analysis documentation that health-conscious consumer segments rarely require.
- Vegetarians:Flexitarian positioning drives partial substitution demand rather than complete protein replacement, favoring concentrate-tier economics.
- Vegans:Strict exclusion requirements support premium pricing for certified allergen-free isolates with full supply chain traceability documentation.
- Health-Conscious Consumers:Clean-label preferences favor minimally processed concentrates over chemically extracted isolates, despite inferior protein density.
- Athletes:Leucine content and digestibility scoring determine procurement decisions, with sports nutrition brands conducting amino acid profiling that exceeds standard food-grade specifications.
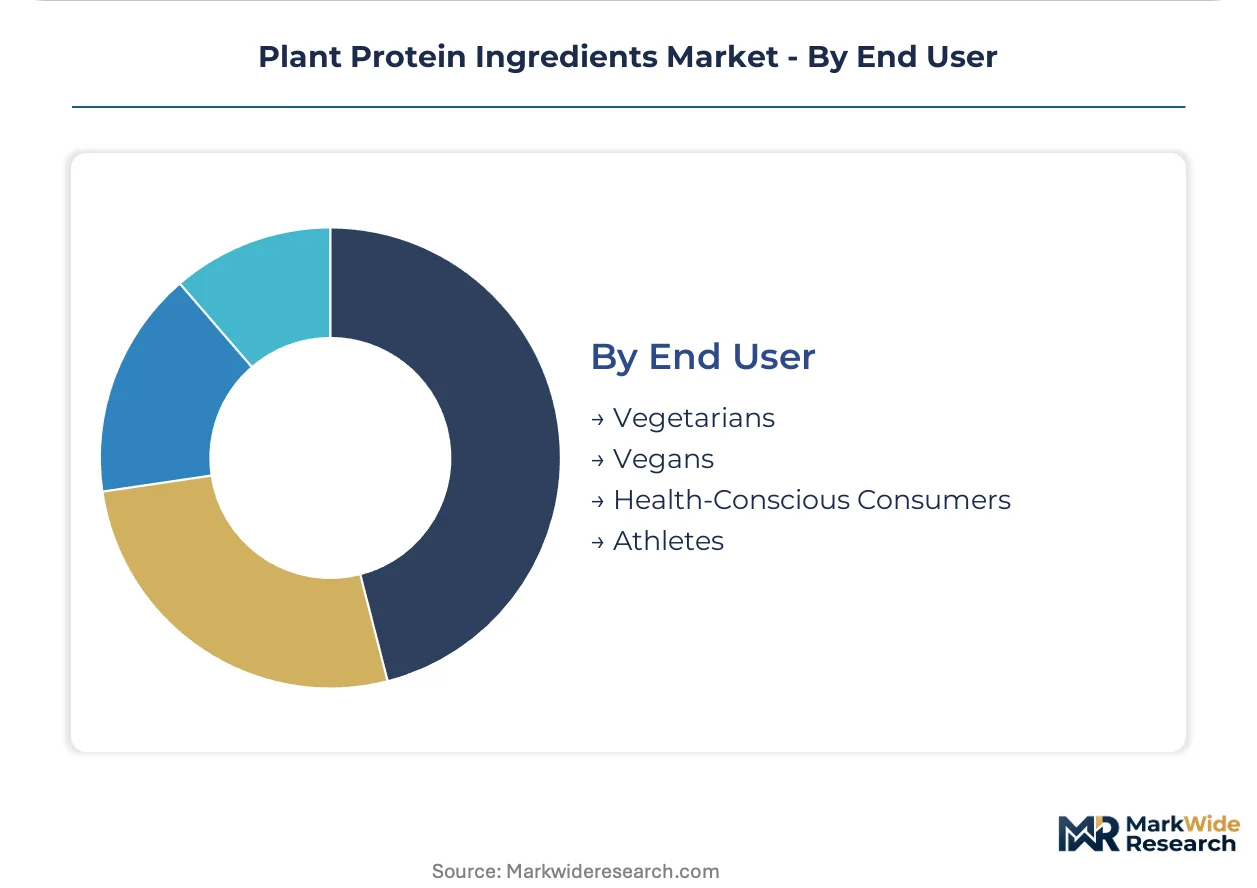
Athletes drive the most demanding specification requirements, with vegan end users representing the steepest expansion trajectory on ethical positioning and allergen avoidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's food-tech clusters attract precision-fermentation investment while the United States retains crushing infrastructure advantages for soy protein economics. Canada supplies yellow pea raw material that European processors depend on. France maintains bakery applications dominance through vital wheat gluten demand. China scales domestic extraction capacity for rice protein export.
United States
Sports nutrition manufacturers in North American processing corridors contract isolate-grade volumes exceeding legacy food processor procurement. FDA GRAS status for soy and wheat protein accelerates formulation deployment versus novel food timelines. Crushing infrastructure in the Midwest delivers cost-advantaged soy protein isolate supply chains.
Germany
Alt-meat startups and precision-fermentation facilities in Berlin and Hamburg drive formulation innovation for extruded texturized proteins. EU Green Deal protein diversification mandates redirect agricultural subsidies toward domestic legume cultivation. Food-tech incubators in Hamburg facilitate direct supplier-startup matching, bypassing traditional distribution channels.
Canada
Yellow pea cultivation on the Canadian prairies supplies raw material for European wet-fractionation processors dependent on North American imports. Prairie weather patterns introduce input cost volatility that compresses margins for downstream operators. Protein crop rotation incentives under the Common Agricultural Policy tie European subsidy eligibility to supply chain diversification.
France
Vital wheat gluten retains dominance in European bakery applications despite celiac-labeling constraints on finished goods. EFSA novel food authorizations for emerging protein sources face accelerated application backlogs that extend commercial launch windows. Roquette Frères anchors European pea protein extraction with wet-fractionation assets achieving superior purity rates.
China
Domestic extraction capacity for rice protein scales to serve hypoallergenic positioning in pediatric and senior nutrition export markets. SAMR regulatory frameworks govern food ingredient safety assessments for plant protein derivatives. Processing infrastructure in coastal provinces targets international cosmetic and personal care ingredient channels.
Plant Protein Ingredients Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure consolidates around oilseed processors with amortized crushing infrastructure, flavor technology houses commanding premium placement, and wet-fractionation operators with scarce protein chemistry expertise. Strategic archetypes include agricultural conglomerates leveraging upstream crop handling, ingredient technology platforms masking off-notes, and regional extraction specialists with purity advantages. Dominant competitive moves encompass capacity expansion in precision-fermentation corridors and strategic partnerships between flavor houses and alt-meat formulators.
Within the agricultural conglomerate tier, Cargill and Archer Daniels Midland Company represent scale-driven positions anchored in North American oilseed processing corridors. Kerry Group and Glanbia PLC exemplify technology-forward specialists where flavor-mask capabilities and nutritional premix integration command premium specifications. Roquette Frères occupies a focused European extraction position tied to wet-fractionation purity advantages.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Kerry Group |
| Glanbia PLC |
| Roquette Frères |
| International Flavors & Fragrances |
| Ingredion |
| Axiom Foods |
| Prinova Group |
| Others |
Supply Flow & Price Mechanics
Isolate-concentrate bifurcation splits procurement economics between wet-fractionation purity premiums and dry-milled commodity positioning, with EU Green Deal subsidy eligibility now conditioning supply chain configuration decisions across German processing corridors. This tier divergence concentrates margin capture among three European wet-fractionation operators while forcing commodity-tier suppliers into spot-market volatility exposure.
Pricing Analysis
Capacity additions in Berlin and Hamburg are reshaping price floors for pea protein isolates as precision-fermentation facilities absorb venture capital flows. Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade textured formats governs contract negotiations, with certification grade and volume scale as primary differentiation drivers. Cost compression in concentrate-tier supply is intensifying because Canadian prairie weather volatility feeds raw material uncertainty. Sports nutrition brands show least price sensitivity on isolate specifications, while economy-tier food processors reject premium positioning entirely.
Supply Chain Analysis
Yellow pea supply rests on Canadian prairie cultivation, German wet-fractionation processing infrastructure, and Chinese rice protein extraction capacity as geographic anchors. Raw material dependencies span North American legume cultivation, European flavor-mask technology inputs, and Asian hydrolysis enzyme supplies. Single-source vulnerability concentrates in wet-fractionation assets achieving protein purity above 85%, where specialized protein chemistry expertise creates replacement friction. Distribution runs through direct supplier-startup matching in Hamburg food-tech incubators alongside traditional ingredient distribution channels serving legacy food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's protein diversification mandates compound regulatory tailwinds into structural demand expansion, with Common Agricultural Policy subsidy reallocation driving hectarage shifts that reshape upstream supply availability.
For Market Incumbents: Deepen wet-fractionation capacity utilization rates through long-term offtake agreements with alt-meat startups, insulating against precision-fermentation substitution threats. Secure deforestation-free supply chain verification under CSRD disclosure requirements to exclude smaller competitors lacking ISO 14064-certified carbon accounting infrastructure. Anchor position through backward integration into domestic legume cultivation under EU subsidy programs. For New Entrants and Emerging Players: Direct-to-pet-food-manufacturer channels in Germany offer white-space penetration with higher ingredient premium tolerance than livestock feed economics allow. Target cosmetic base applications for hydrolyzed rice protein where personal care ingredient portfolios enable cross-category leverage. Exploit EFSA novel food authorization backlogs by pursuing GRAS-equivalent pathways for faster commercial deployment. For Investors and Strategic Acquirers: Consolidation pressure builds where wet-fractionation expertise scarcity concentrates value capture among operators with isoelectric precipitation capabilities. Five-to-ten-year viability favors acquisition targets with verified Scope 3 carbon data and farm-level blockchain traceability systems already deployed. Monitor precision-fermentation regulatory classification decisions as inflection signals for extracted versus biomanufactured protein source competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Legume Cultivation | EU Green Deal subsidies reward domestic protein crop rotation with direct payment eligibility. |
| Flavor-Mask Technology Partnership | Kerry Group's off-note neutralization capabilities command premium placement in beverage applications. |
| Precision-Fermentation Capacity Buildout | Berlin food-tech clusters compress development timelines from growing seasons to bioreactor batch cycles. |
| CSRD Compliance Infrastructure Investment | ISO 14064-certified carbon accounting excludes smaller operators from German processor procurement pools. |
| Novel Protein Source Authorization | EFSA approval timelines determine commercial launch windows for emerging fava and rice protein derivatives. |
Methodological Framework
Bottom-up formulation modeling reconciled against top-down crushing infrastructure tracking forms the analytical core, combining primary interviews with plant protein extraction operators, sports nutrition procurement directors, and pet food formulation scientists against secondary validation from EFSA novel food registers, USDA organic certification databases, and EU Common Agricultural Policy implementation reports. This triangulation anchors volume estimates in actual processing capacity utilization and subsidy-driven hectarage shifts.
Input-output matrices across isolate, concentrate, and textured form dimensions model protein content tiers, application segments, and end-user specification requirements throughout the forecast period. CAGRs derive from capacity expansion pipelines in German precision-fermentation corridors and Canadian prairie cultivation trends. Industry-specific forecast inputs include wet-fractionation asset deployment schedules and EFSA authorization backlog resolution patterns.
The model assumes a particular technology adoption path; alternative pathways for precision-fermentation scale-up would alter the outlook if microbial protein production achieves cost parity with extracted isolates faster than baseline assumptions. Forecasts reflect assumptions regarding EU subsidy continuity and EFSA staffing capacity for novel food reviews. Material deviation in Canadian prairie weather patterns or precision-fermentation regulatory classification decisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fish Gelatin Market
Ingredients
Salt Content Reduction Ingredients Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Vegetable Powder Market
Ingredients
United States Soy Protein Market
Ingredients
Soluble Fibers Market
Ingredients
Oyster Peptide Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Salt Market
Ingredients
Lime Seed Oils Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Grape Skin Extract Market
Ingredients
United States Wheat Protein Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Bulk Food Ingredients Market