
 Global Distillers Corn Oil Market | 2026-2036
Global Distillers Corn Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Distillers Corn Oil Market Analysis
End-use consumption is shifting as fuel companies expand renewable diesel capacity faster than traditional food applications. POET LLC leverages its integrated ethanol platform to capture distillers corn oil at scale across multiple biorefineries. Green Plains Inc. anchors its margin profile through oil separation technology investments at dry mill facilities. Valero Energy Corporation competes by routing captive distillers corn oil into its renewable diesel operations at Diamond Green Diesel.
Distillers corn oil is a co-product of dry mill ethanol production extracted from the stillage stream after fermentation, typically containing 85-92% triglycerides with elevated free fatty acid content relative to commodity corn oil. Its primary commercial purpose centers on serving as a lower-cost feedstock for biodiesel and renewable diesel hydrotreating while also supplying oleochemical applications. The refined corn oil segment dominates food-grade applications where processors demand low moisture and low impurity specifications for frying and ingredient formulations. Crude corn oil captures expanding share in biofuel production where pretreatment systems tolerate higher free fatty acid levels and mechanical extraction avoids refining costs. Industrial grade oil occupies a narrower channel serving lubricant and surfactant manufacturers with less stringent color and odor requirements.
The US EPA Renewable Fuel Standard and California Air Resources Board Low Carbon Fuel Standard collectively shape demand trajectories by assigning favorable carbon intensity scores to distillers corn oil pathways. FDA food contact substance regulations and REACH chemical registration requirements in Europe govern product specifications for cross-border trade in food and technical grades. Stakeholders must monitor renewable diesel capacity announcements against distillers corn oil supply growth to assess feedstock balance and pricing dynamics.
Market Dynamics
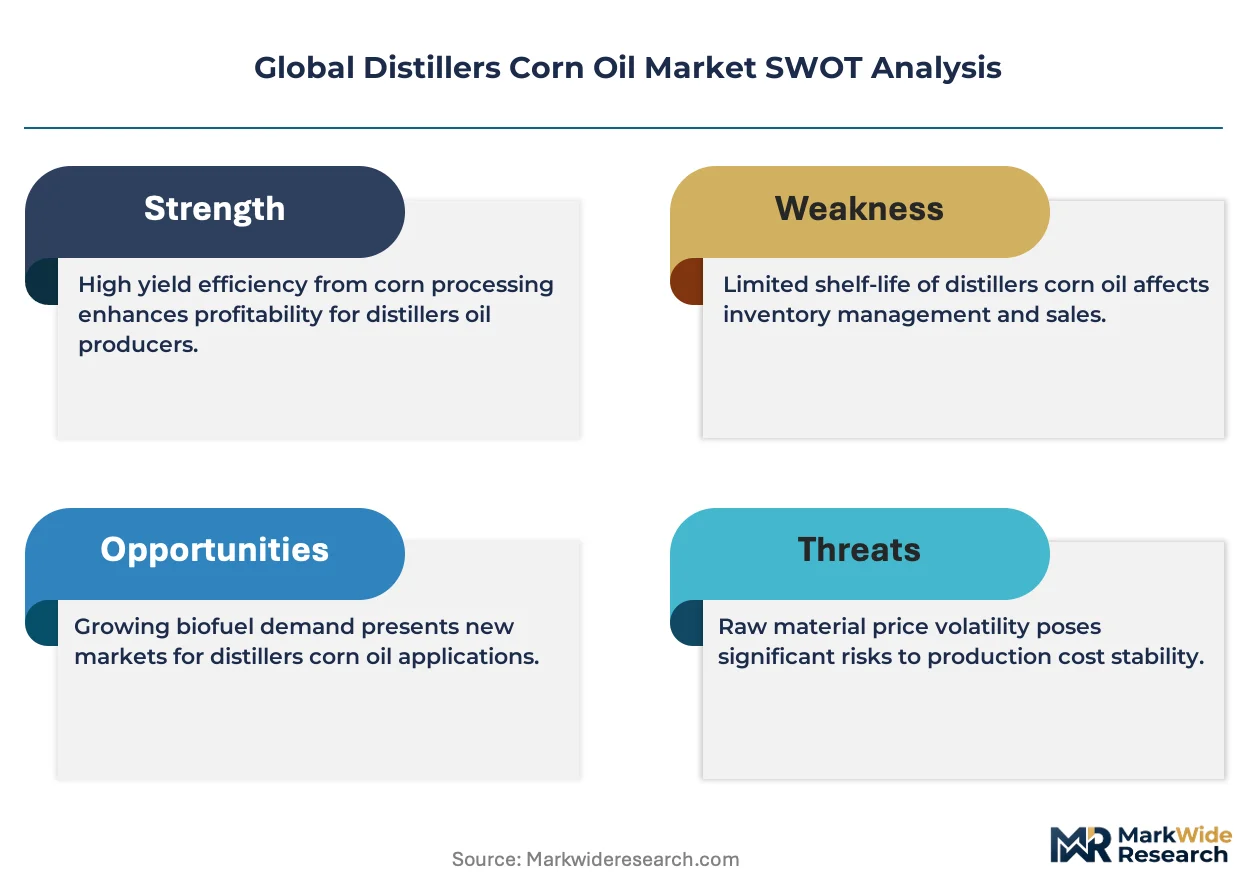
The renewable diesel buildout is compressing the traditional food-versus-fuel arbitrage for distillers corn oil, as biofuel producers now absorb volumes previously routed to oleochemical and feed markets.
Growth Catalysts
- US EPA Renewable Fuel Standard:Mandated blending volumes sustain offtake for alternative feedstocks, with distillers corn oil qualifying under advanced biofuel pathways.
- California Low Carbon Fuel Standard:Favorable carbon intensity scoring for corn oil-derived renewable diesel pulls Midwest supply toward West Coast refining clusters.
- Hydrotreater technology:Pretreatment advances now tolerate elevated free fatty acid levels in crude distillers corn oil, eliminating refining costs for biofuel producers.
Market Restraints
- Crude oil price volatility:Soybean oil and waste grease compete as biodiesel feedstocks, with price spreads dicting switching economics for blenders.
- Midwest supply concentration:Iowa, Illinois, and Nebraska ethanol clusters generate over 80% of North American distillers corn oil, creating geographic dependency risk.
- REACH registration friction:European chemical registration requirements for technical-grade imports impose compliance timelines that delay market entry.
Strategic Opportunities
- India biofuel blending:The country's 20% ethanol blending target by 2025 creates import demand for feedstock oils as domestic corn oil recovery scales.
- Sustainable aviation fuel:Emerging hydrotreated esters and fatty acids pathways for aviation represent a volume sink with premium pricing potential.
- Integrated extraction systems:Converting dry mill stillage through membrane separation plus mechanical pressing yields higher oil recovery rates than legacy centrifuge methods.
Industry Challenges
- Skilled technician shortage:Operating membrane separation and acid esterification pretreatment systems requires specialized training that ethanol plant workforces often lack.
- Certification timeline compression:Securing FDA food contact substance notifications and REACH registrations simultaneously strains regulatory affairs capacity.
- Supply chain reconfiguration:Redirecting tanker railcars from food processors to renewable diesel terminals demands new logistics partnerships and storage infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Distillers Corn Oil Market |
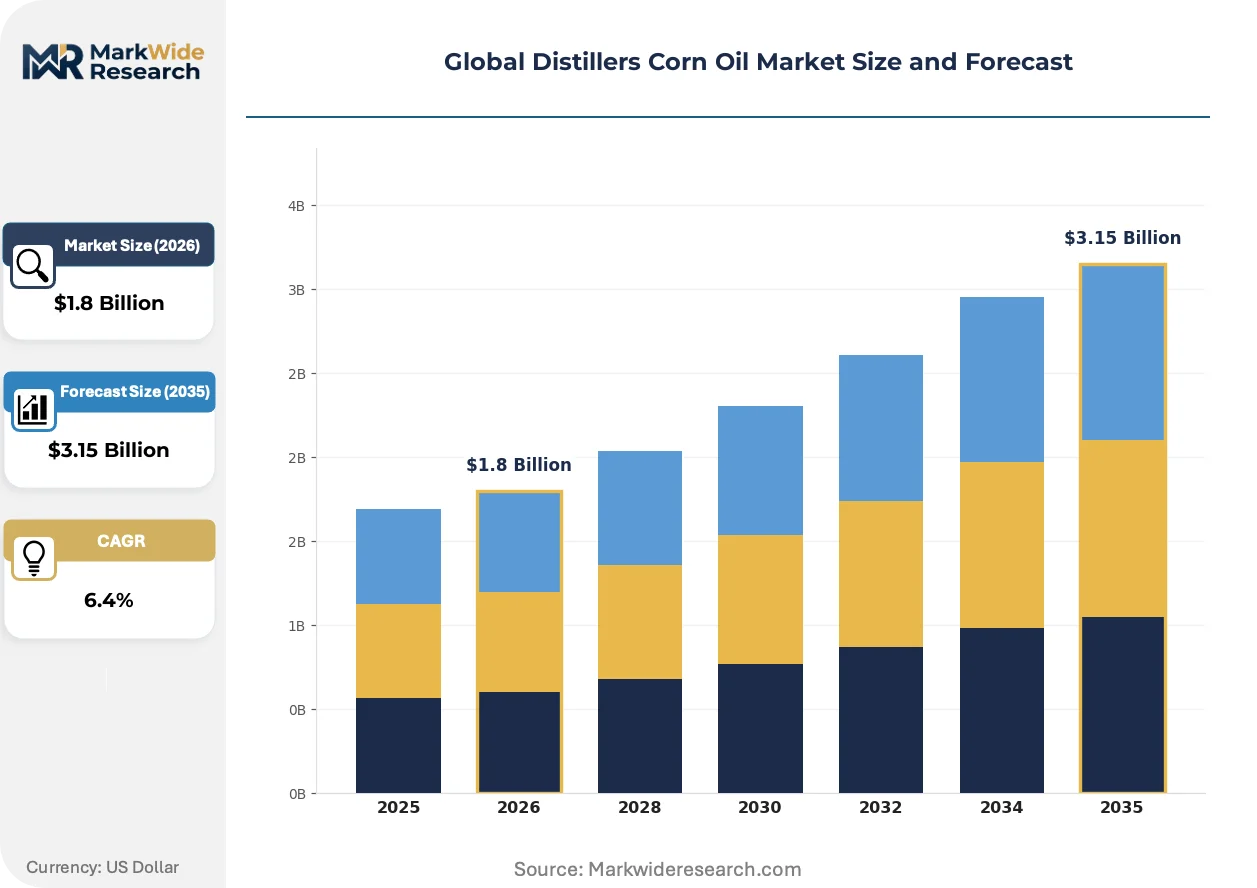
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Corn Oil, Crude Corn Oil, Food Grade Oil, Industrial Grade Oil Application: Food Industry, Biofuel Production, Cosmetics, Animal Feed End User: Food Manufacturers, Fuel Companies, Cosmetic Brands, Livestock Feed Suppliers Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Green Plains Inc., POET LLC, Valero Energy Corporation, Cargill, Incorporated, Flint Hills Resources, LLC, The Andersons, Inc., CHS Inc., Cardinal Ethanol LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Distillers Corn Oil Market Emerging Trajectories
Technology convergence between ethanol biorefining and renewable diesel hydrotreating is dissolving traditional boundaries between agricultural processing and petroleum refining.
Membrane filtration systems are integrating into dry mill stillage processing lines, enabling continuous oil recovery without batch centrifuge downtime. POET and Green Plains have retrofitted multiple facilities with ceramic membrane skids that extract oil upstream of distillation solids drying. This technology is integrating oil separation into the core ethanol production workflow rather than treating it as a downstream coproduct step.
The EU Green Deal's Fit for 55 package tightens carbon intensity benchmarks for transport fuels imported into European ports. Fuel suppliers must demonstrate lifecycle emissions below declining thresholds, with crop-based feedstocks facing stricter scrutiny than waste streams. Distillers corn oil shipments to Rotterdam and Hamburg now require detailed sustainability certification that US-origin supply chains are racing to document.
Biofuel procurement contracts are compressing from annual volumes toward quarterly price-indexed agreements with volume flex provisions. Renewable diesel producers at Diamond Green Diesel and Neste's Singapore facility now negotiate feedstock supply with price collars tied to soybean oil futures plus a basis differential. This shift transfers price risk upstream to ethanol plant operators while securing offtake certainty for hydrotreater runs.
Global Distillers Corn Oil Market Segmentation
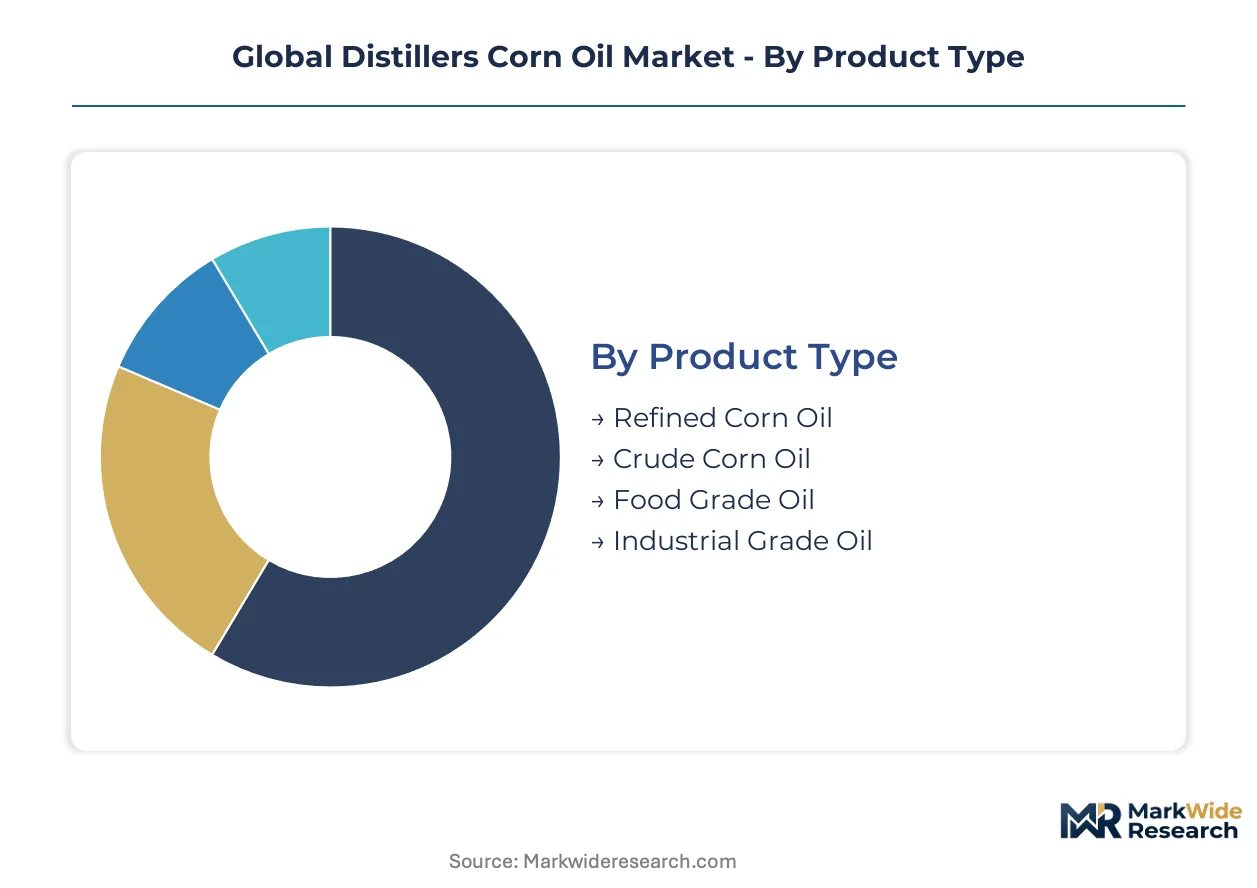
Product specifications and end-use requirements fragment the distillers corn oil market into distinct commercial channels. Each segment carries unique certification burdens and margin profiles that determine competitive positioning across food, fuel, and industrial applications.
Product Type:
FDA food contact substance notifications govern refined and food-grade specifications, while crude and industrial grades face lighter regulatory loads but demand different supply chain configurations.
- Refined Corn Oil:Achieves moisture content below 0.1% and free fatty acid levels under 0.05% through alkali refining and bleaching. Snack food manufacturers in the United States specify this grade for extended fry life in continuous frying systems. FDA compliance documentation adds 60-90 days to procurement cycles for new suppliers.
- Crude Corn Oil:Retains 85-92% triglycerides with 5-15% free fatty acids and elevated phospholipid content after mechanical extraction. Renewable diesel producers at Diamond Green Diesel and Neste's Singapore facility now accept this grade directly, bypassing refining costs that eroded margins in earlier procurement cycles.
- Food Grade Oil:Meets Codex Alimentarius standards for color, odor, and oxidative stability required by bakery and margarine compounders. European imports require EFSA novel food assessments if processing methods deviate from traditional wet milling.
- Industrial Grade Oil:Tolerates higher color units and peroxide values for lubricant base stocks and surfactant feedstocks. REACH registration in Europe mandates full substance characterization that few US ethanol plant operators have completed.
Leading the category by volume: Crude Corn Oil. Growing fastest: Food Grade Oil.
Application:
Carbon intensity scoring systems redirect volume flows between food and fuel channels faster than traditional demand cycles.
- Food Industry:Encompasses frying, baking, and ingredient formulations where oxidative stability determines shelf life. Major US snack producers specify corn oil for neutral flavor profiles that do not mask seasoning blends.
- Biofuel Production:Hydrotreated renewable diesel pathways now absorb crude distillers corn oil at scale, with California LCFS credits offsetting feedstock premiums versus soybean oil. US EPA RFS compliance generates offtake certainty through mandated blending volumes.
- Cosmetics:Requires low-odor, low-color refined grades for emollient formulations. Indie beauty brands in Korea and Japan source small batches through specialized importers with established cosmetic ingredient dossiers.
- Animal Feed:Distillers corn oil replaces tallow and choice white grease in dairy ration energy supplements. Midwest feed mills blend 3-5% inclusion rates to boost metabolizable energy without disrupting rumen function.
Dominant by volume: Biofuel Production. Steepest expansion trajectory: Cosmetics.
End User:
Procurement sophistication varies sharply across customer types, with fuel companies driving contract innovation toward price-indexed agreements.
- Food Manufacturers:Multinational processors like Frito-Lay and Kellogg negotiate annual contracts with fixed pricing and quality penalties. Their technical service teams audit ethanol plant extraction systems before supplier qualification.
- Fuel Companies:Valero, Marathon, and independent renewable diesel developers now dominate crude oil offtake. Quarterly price collars tied to soybean oil futures plus basis differentials transfer commodity risk upstream to ethanol producers.
- Cosmetic Brands:Clean beauty positioning drives demand for non-GMO and organic certified corn oil variants. Supply chains must document identity preservation from ethanol plant to cosmetic contract manufacturer.
- Livestock Feed Suppliers:Regional feed mills in Iowa, Illinois, and Nebraska purchase tanker loads through established grain elevator networks. Price sensitivity limits premium payments for refined grades unless fat supplementation is critical.
Largest volume concentration: Fuel Companies. Fastest contract sophistication gains: Cosmetic Brands.
Distribution Channel:
Logistics infrastructure shapes channel economics, with bulk liquid handling favoring direct and wholesale routes over retail fragmentation.
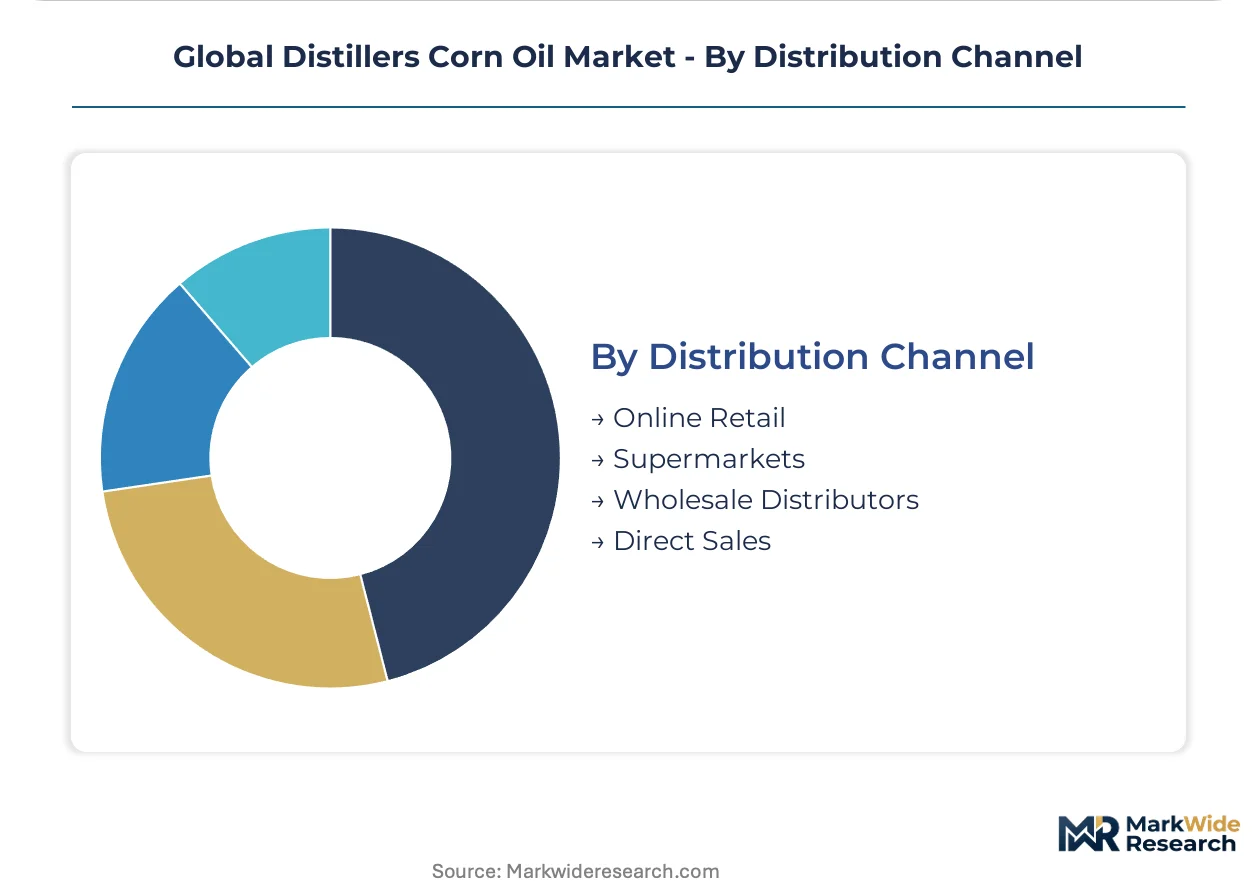
- Online Retail:Serves artisan food producers and small cosmetic formulators seeking 55-gallon drum quantities. Amazon Business and specialty chemical marketplaces list food-grade and organic certified variants with 5-7 day fulfillment.
- Supermarkets:Bottled refined corn oil competes with commodity vegetable oil blends in 48-ounce retail formats. Private label programs at Kroger and Albertsons source through co-packers with established FDA food facility registrations.
- Wholesale Distributors:Univar Solutions and Brenntag move industrial and technical grades through established chemical distribution networks. Their tank terminal access enables bulk transfer to manufacturing plants without drum handling costs.
- Direct Sales:Ethanol plant operators like POET and Green Plains negotiate direct offtake agreements with renewable diesel producers. Dedicated railcar fleets and storage terminal partnerships lock in volume commitments across multi-year contracts.
Highest volume flow: Direct Sales. Channel expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Renewable Fuel Standard tax incentives and California's Low Carbon Fuel Standard credits have concentrated biofuel feedstock demand in specific geographic corridors rather than dispersing it evenly.
United States
Iowa and Illinois ethanol clusters generate over 80% of North American distillers corn oil supply. The EPA's Renewable Fuel Standard mandates advanced biofuel blending volumes that sustain offtake certainty. Diamond Green Diesel's renewable diesel facility in Louisiana draws crude corn oil via dedicated railcar fleets from Midwest biorefineries.
Brazil
Sugar-ethanol complexes in São Paulo state are retrofitting corn ethanol units to capture distillers corn oil for domestic biodiesel blending. The country's RenovaBio program assigns carbon intensity scores that favor corn oil pathways over soybean oil. Mato Grosso grain processors are investing in dry mill oil separation technology to supply the Southeast industrial corridor.
Germany
Hamburg and Rotterdam ports handle increasing US-origin distillers corn oil shipments for EU renewable diesel hydrotreaters. The EU Green Deal's Fit for 55 package tightens transport fuel carbon intensity benchmarks. REACH registration requirements for technical-grade imports impose compliance timelines that delay market entry for new suppliers.
India
The government's 20% ethanol blending target by 2025 creates import demand for feedstock oils as domestic corn oil recovery scales. FSSAI food safety standards govern refined grade imports for snack food manufacturers. Gujarat and Maharashtra ethanol plants are piloting membrane separation systems to boost oil recovery rates.
Canada
Ontario and Saskatchewan ethanol facilities supply crude corn oil to domestic biodiesel producers and US renewable diesel terminals. Environment and Climate Change Canada's Clean Fuel Regulations assign carbon intensity scores that pull Prairie supply toward West Coast refining clusters. Sarnia's chemical processing hub is evaluating distillers corn oil as a oleochemical feedstock alternative.
Global Distillers Corn Oil Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated ethanol operators commanding crude supply while refined grade distributors serve food manufacturers. The market structure concentrates around three archetypes: captive ethanol producers with in-house oil extraction, independent commodity traders arbitraging grade spreads, and renewable diesel operators securing long-term offtake. Dominant competitive moves include backward integration into stillage processing technology and multi-year supply contracts with price collars tied to soybean oil futures.
Among integrated ethanol operators, POET LLC and Green Plains Inc. anchor the captive supply archetype by controlling extraction infrastructure across multiple biorefinery locations. Valero Energy Corporation occupies a distinct position routing distillers corn oil into renewable diesel operations through its Diamond Green Diesel joint venture. These three entities exemplify how petroleum refining and agricultural processing boundaries are dissolving through technology convergence.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Green Plains Inc. |
| POET LLC |
| Valero Energy Corporation |
| Cargill, Incorporated |
| Flint Hills Resources, LLC |
| The Andersons, Inc. |
| CHS Inc. |
| Cardinal Ethanol LLC |
| Others |
Supply Flow & Price Mechanics
Soybean oil futures on the Chicago Board of Trade cascade through distillers corn oil procurement contracts, compressing margins for ethanol plant operators who lack long-term offtake agreements with renewable diesel producers. The benchmark's volatility feeds directly into pricing tiers, with crude grade discounts widening when soybean oil spikes and food-grade premiums holding firmer due to FDA certification stickiness.
Pricing Analysis
Short lead-time spot purchases command premiums of 8-12% above quarterly contract rates as renewable diesel producers rush to cover hydrotreater runs. Three-tier pricing structure across premium refined, standard food-grade, and economy crude levels segments buyers by certification burden and volume commitment. Cost compression in crude tiers is intensifying because biofuel producers now negotiate price collars tied to soybean oil futures. Fuel companies exhibit lowest price sensitivity due to California LCFS credit arbitrage, while regional feed mills remain most price-elastic.
Supply Chain Analysis
Skilled membrane separation technicians in Iowa, Illinois, and Nebraska ethanol clusters constrain expansion timelines for oil recovery retrofits. Geographic supply concentration in the US Midwest draws from corn belt harvests, dry mill fermentation capacity, and rail terminal access. Single-source vulnerability runs through Union Pacific and BNSF rail corridors that move 90% of crude corn oil to Gulf Coast renewable diesel facilities. Distribution runs through dedicated tanker railcar fleets and liquid bulk terminals rather than packaged goods channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH registration timelines and FDA food contact substance notifications erect barrier-to-entry moats. The EPA's Renewable Fuel Standard and California's LCFS collectively sustain demand visibility for players who navigate dual regulatory frameworks.
For Market Incumbents: Acquire membrane separation technology assets to lock in oil recovery rates above legacy centrifuge methods. Defensive consolidation should prioritize backward integration into stillage processing equipment manufacturing to secure technician training pipelines. The emerging threat of skilled operator shortages at ethanol plants demands captive workforce development programs.
For New Entrants and Emerging Players: Capture cosmetic-grade refined oil segments in Korea and Japan where clean beauty positioning commands premium pricing. White-space targets include sustainable aviation fuel offtake agreements and India biofuel import demand. A go-to-market angle centered on non-GMO identity preservation documentation unlocks indie beauty brand procurement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ethanol plant operators with idle oil separation capacity in Nebraska and Iowa. Long-term viability over the coming decade hinges on renewable diesel capacity buildout sustaining crude grade absorption. The signal to watch is Diamond Green Diesel and Neste expansion announcements against Midwest supply growth rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Separation Retrofit | POET and Green Plains deployments prove ceramic membrane skids outperform centrifuge batch processing. |
| Long-term Supply Agreement | Multi-year offtake contracts with price collars transfer commodity risk to ethanol producers. |
| REACH Registration Completion | Technical-grade EU market entry requires ECHA substance characterization that few US operators possess. |
| Renewable Diesel Capacity Buildout | Diamond Green Diesel's Louisiana facility absorbs Midwest crude corn oil via dedicated railcar fleets. |
| Identity Preservation Certification | Non-GMO and organic documentation unlocks cosmetic brand procurement in Korean and Japanese markets. |
Methodological Framework
USDA crop production reports, EPA Renewable Fuel Standard compliance data, and EIA biofuel processing statistics formed the secondary backbone of this analysis. Primary interviews with ethanol plant operations managers, renewable diesel procurement leads, and FDA regulatory affairs specialists combined with bottom-up facility capacity modeling and top-down trade flow triangulation. Secondary validation drew from customs records, railcar movement filings, and California Air Resources Board LCFS credit transaction databases.
Historical trendline analysis of ethanol plant oil recovery rates and renewable diesel feedstock consumption patterns anchored the projection framework. Segmentation modeling spanned product grade tiers, end-use applications, and regional regulatory clusters across the analysis window. CAGRs derived from capacity expansion announcements, hydrotreater technology deployment curves, and carbon intensity scoring evolution. Forecast inputs included EPA mandated blending volume trajectories and EU Green Deal transport fuel benchmarks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to renewable diesel capacity buildout delays and EU sustainability certification timeline shifts. Forecasts reflect documented assumptions around membrane separation adoption rates and California LCFS credit pricing stability. Material deviation in EPA RFS mandate stringency or EU Fit for 55 package implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
France Protein Market
Ingredients
Spain Fermentation Ingredients Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Halal Ingredients Market
Ingredients
Fresh Yeast Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Phytosterols Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Casein Hydrolysate Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Egg White Powder Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Stock Cubes Market
Ingredients
Europe Plant Protein Ingredients Market