
 Europe Sodium Reduction Ingredient Market | 2026-2036
Europe Sodium Reduction Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sodium Reduction Ingredient Market Foresight
Food manufacturers is collapsing the historical buyer mix once split evenly with restaurants and retailers, as private-label reformulation and clean-label commitments concentrate procurement power in industrial kitchens. Cargill Incorporated leverages its European salt substitute blending capacity to serve pan-continental bakery chains. Kerry Group anchors its position through savory taste modulation systems that mask potassium chloride off-notes. dsm-firmenich competes on fermentation-derived flavor enhancers that deliver umami impact without sodium load.
Europe sodium reduction ingredients comprise functional food additives and processing aids designed to replicate or amplify salty taste perception while lowering actual sodium chloride content, typically employing potassium salts, yeast extracts, amino acids, or mineral blends at application doses between 0.5% and 3.0% by weight. These ingredients serve primarily to help food processors maintain consumer sensory acceptance under reformulated recipes with reduced salt. Salt substitutes dominate current volume flows due to mature potassium chloride supply chains and established efficacy in meat and dairy matrices. Flavor enhancers represent the fastest-expanding margin pool, as fermented ingredients and nucleotide-based systems command premium positioning in organic and free-from product lines where clean-label claims restrict mineral salt use.
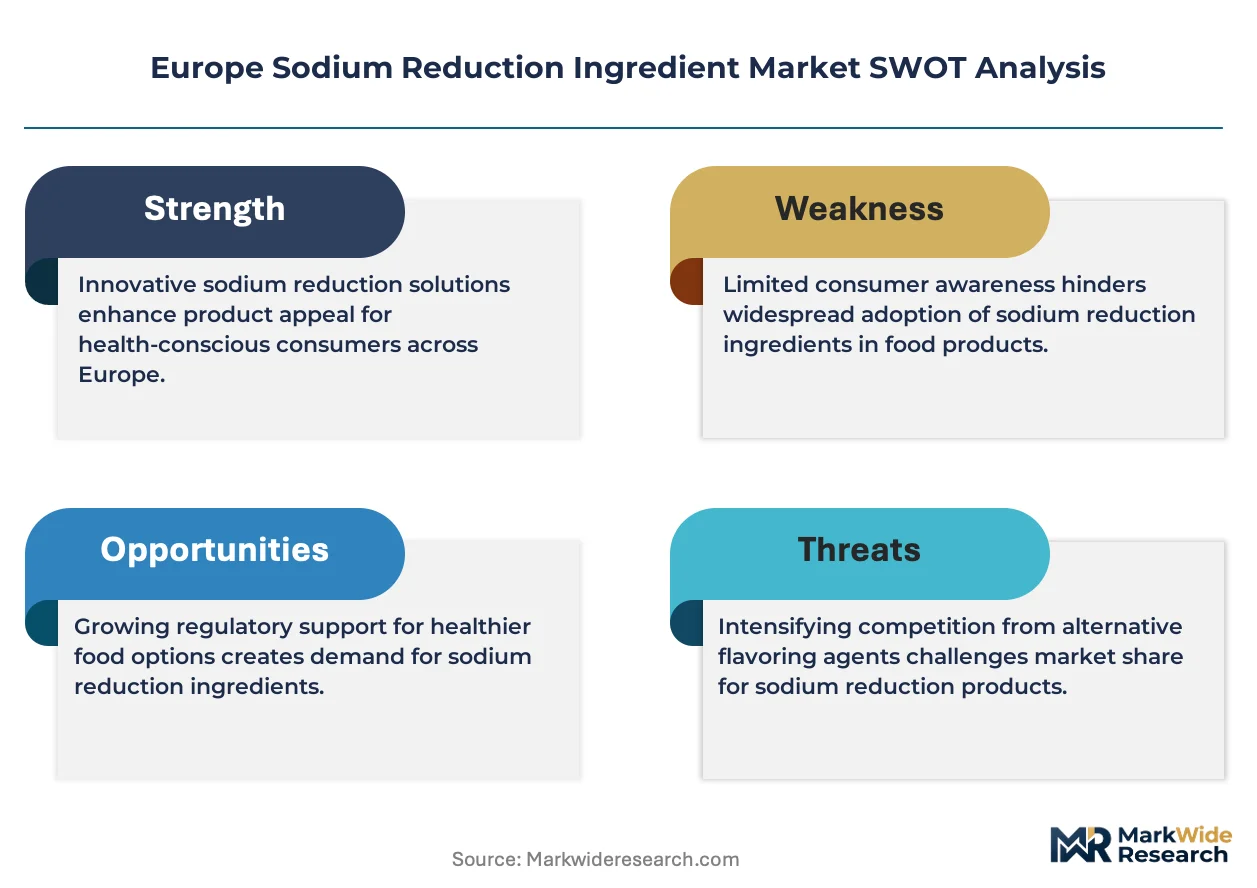
EFSA sodium intake benchmarks, EU Green Deal nutritional targets, and national health agency mandates in France and the UK collectively reshape product standards by penalizing high-salt formulations through front-of-pack warning schemes and public procurement criteria. REACH compliance adds a secondary gating factor for novel mineral complexes and biotech-derived taste modulators entering European ingredient channels. Stakeholders must monitor the interplay between tightening WHO sodium guidelines and evolving EFSA safety opinions on high-level potassium fortification, as this regulatory tension will determine which technical platforms secure long-term formulation slots.
Market Dynamics
EFSA's updated sodium intake benchmarks and the EU Green Deal nutritional targets are compressing formulation windows for processed food manufacturers, forcing rapid substitution of sodium chloride with functional mineral salts and fermentation-derived taste modulators across European industrial kitchens.
Growth Catalysts
- EU Front-of-Pack Labelling Mandate:The 2024 EFSA-guided disclosure rules penalize high-salt formulations through warning schemes, compelling reformulation investments in ready meals and cured meats.
- German Sodium Targets:Binding national reduction goals aligned with WHO recommendations drive procurement of potassium-based substitutes in industrial bakeries and meat processing facilities.
- Clean-Label Consumer Pull:Free-from and organic product lines accelerate demand for yeast extract and amino acid systems that bypass mineral salt declarations.
Market Restraints
- Potassium Chloride Supply Concentration:Mature supply chains for mineral salt substitutes concentrate in German and Dutch chemical processing hubs, creating geographic vulnerability.
- REACH Registration Burden:Novel mineral complexes and biotech-derived taste modulators face extended safety dossier requirements, delaying market entry by 18-36 months.
- Off-Note Technical Limitations:Potassium chloride's metallic aftertaste persists above 30% sodium replacement rates in delicate dairy matrices, constraining application range.
Strategic Opportunities
- Polish and Romanian Industrial Baking:Underpenetrated markets in Eastern European bakery chains present first-mover advantages for savory taste modulation systems.
- Fermentation-Enhancer Convergence:Combining nucleotide-based systems with traditional yeast extracts unlocks premium positioning in organic meat alternatives.
- UK Public Procurement Criteria:Post-Brexit NHS and school food contracts now mandate sodium thresholds, creating mandated demand pull for technical ingredient suppliers.
Industry Challenges
- Flavor Chemist Talent Scarcity:European universities produce insufficient specialists in savory taste modulation and salt-receptor biochemistry, inflating R&D labor costs.
- Legacy Equipment Retrofit Requirements:Existing salt dosing infrastructure in meat processing plants requires capital-intensive modification to handle hygroscopic potassium blends.
- EFSA-WHO Guideline Divergence:Tightening WHO sodium recommendations outpace EFSA potassium safety opinions, creating regulatory uncertainty for high-level fortification formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sodium Reduction Ingredient Market |
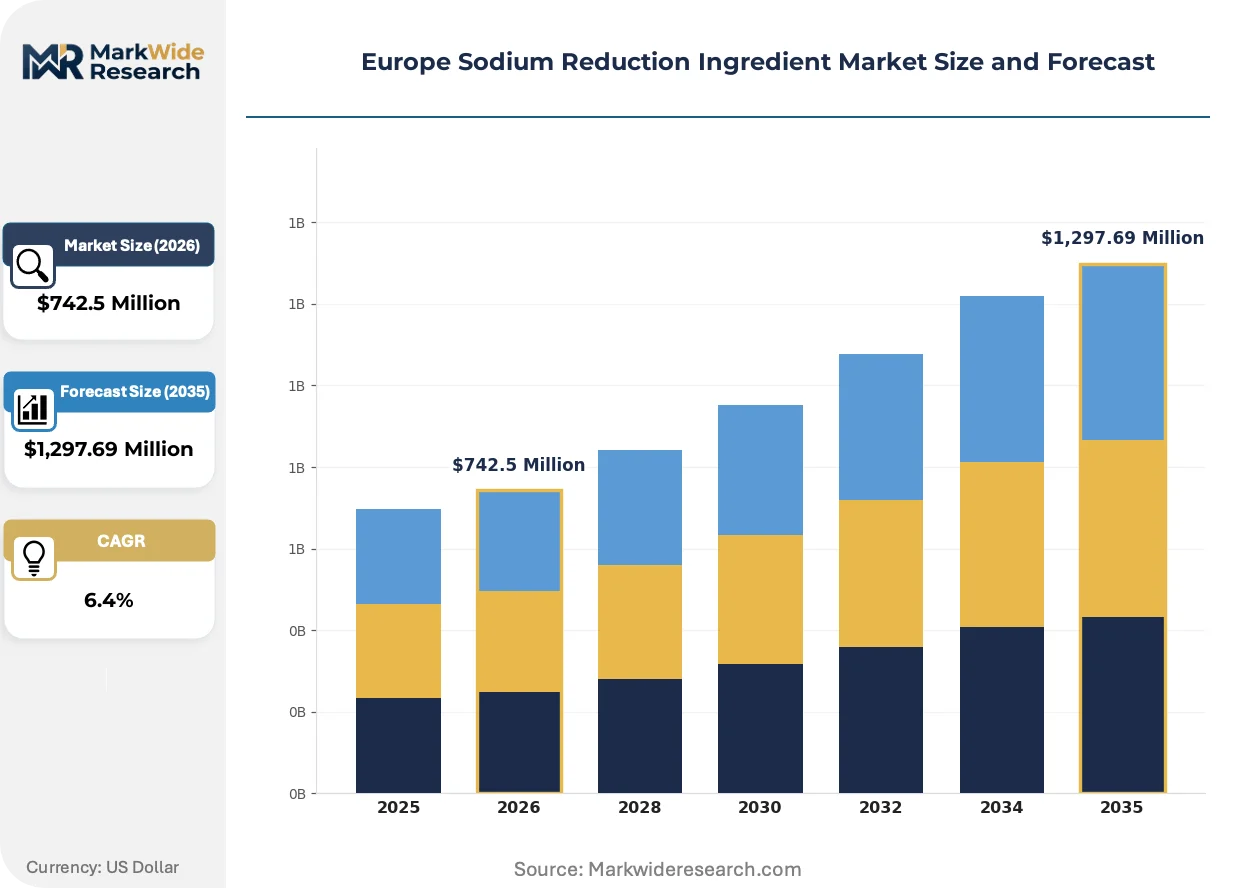
| Market Size in 2026 | $742.5 Million |
| Market Size in 2035 | $1,297.69 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Fermented Ingredients, Sodium-Reducing Agents Application: Processed Foods, Snacks, Sauces, Dairy Products End User: Food Manufacturers, Restaurants, Retailers, Health Food Brands Delivery Mode: Direct Sales, Online Distribution, Retail Stores, Wholesale |
| Companies Covered | Cargill Incorporated, Kerry Group, Tate & Lyle, dsm-firmenich, Bunge Limited, Royal DSM NV, Novozymes A/S, Salt of the Earth Ltd, Corbion, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sodium Reduction Ingredient Market Shifts & Advancements
Fermentation-derived taste technologies and mineral salt processing advances are fragmenting the traditional dominance of simple potassium chloride substitution, while regulatory disclosure mandates accelerate technical ingredient adoption timelines.
Umami-enhancing yeast extract systems are fragmenting the sodium reduction ingredient landscape by enabling deeper salt cuts without metallic off-notes. Industrial meat processors in Germany and the Netherlands adopt these systems at accelerated rates for cured sausage applications. The technology is fragmenting volume concentration away from commodity potassium salts toward differentiated fermentation platforms.
REACH registration requirements for novel mineral complexes are tightening disclosure standards for biotech-derived taste modulators entering European channels. The regulation forces ingredient suppliers to front-load toxicology and environmental fate data, compressing R&D-to-commercialization cycles. Savory flavor enhancers face the steepest compliance burden, driving consolidation among smaller biotech ingredient developers.
Direct technical service relationships between ingredient suppliers and industrial bakery chains are displacing traditional distributor-mediated procurement in sodium reduction categories. Large pan-continental bakery groups now mandate on-site formulation support as a contract precondition. This pattern concentrates most visibly in France and Spain, where private-label bread reformulation programs demand rapid recipe iteration cycles.
Europe Sodium Reduction Ingredient Market Segmentation
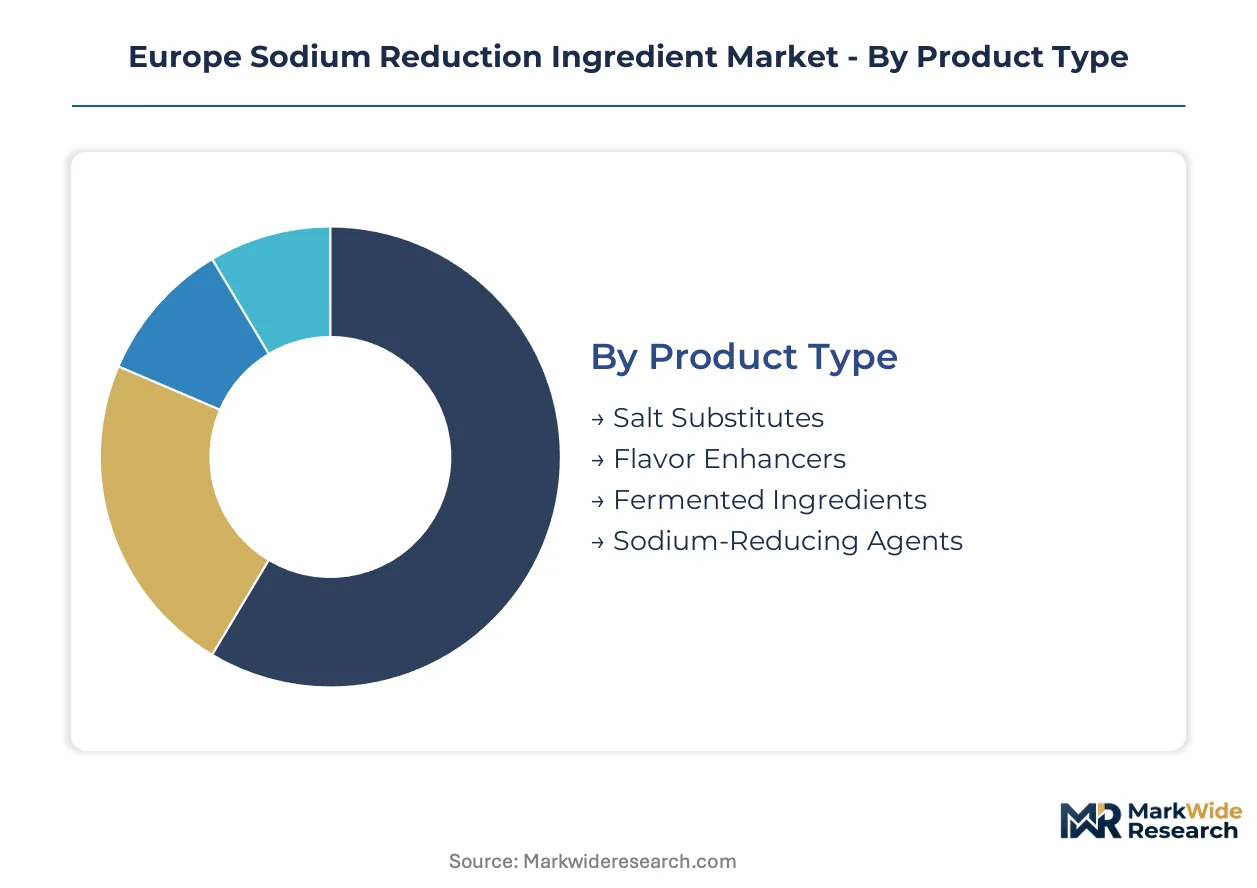
Channel dynamics in the Europe Sodium Reduction Ingredient Market concentrate procurement power through divergent pathways. Industrial food manufacturers negotiate bulk technical service contracts while health food brands prioritize direct supplier relationships for clean-label certification.
Product Type:
Salt substitutes flow predominantly through industrial distributors serving meat and bakery processors, while fermentation-derived systems reach organic brands via specialized ingredient brokers.
- Salt Substitutes:Potassium chloride and mineral salt blends constitute the technical backbone of industrial reformulation programs. German meat processors and Dutch dairy facilities absorb the highest volumes as binding national sodium targets compress formulation windows.
- Flavor Enhancers:Nucleotide-based systems and amino acid complexes deliver umami impact without sodium load. Demand concentrates in French and Spanish industrial bakeries where clean-label bread programs require rapid recipe iteration cycles.
- Fermented Ingredients:Yeast extracts and autolyzed proteins command premium positioning through organic certification channels.
- Sodium-Reducing Agents:Processing aids and functional mineral complexes face extended REACH registration timelines before commercialization.
Salt Substitutes dominate installed base. Fermented Ingredients is where expansion concentrates.
Application:
Processed foods absorb the majority of technical ingredient flows due to reformulation mandates under EFSA-guided front-of-pack labelling rules.
- Processed Foods:Ready meals and cured meats drive procurement of potassium-based substitutes as EU disclosure rules penalize high-salt formulations. Industrial kitchens in Germany and the Netherlands accelerate substitution rates to meet WHO-aligned national targets.
- Snacks:Extruded and fried products employ taste modulation systems to mask sodium reduction in seasoned coatings. Polish and Romanian snack manufacturers represent underpenetrated demand pockets for savory enhancer suppliers.
- Sauces:Condiment reformulation relies on fermented flavor systems to maintain consumer acceptance.
- Dairy Products:Delicate matrices constrain potassium chloride use above 30% replacement rates due to persistent metallic off-notes.
Processed Foods captures the deepest volume penetration. Snacks is climbing the fastest as Eastern European production scales.
End User:
Procurement patterns diverge sharply between industrial scale and specialty positioning, with food manufacturers consolidating supplier relationships around technical service capabilities.
- Food Manufacturers:Pan-continental bakery chains and meat processors mandate on-site formulation support as contract preconditions. Direct technical service relationships are displacing traditional distributor mediation in sodium reduction categories.
- Restaurants:Chain operators face limited penetration due to minimal reformulation control at kitchen level.
- Retailers:Private-label programs concentrate procurement power in industrial kitchens rather than retail buying offices.
- Health Food Brands:Organic and free-from lines drive demand for yeast extract systems that bypass mineral salt declarations.
Food Manufacturers anchor volume flows. Health Food Brands is gaining share fastest through premium positioning.
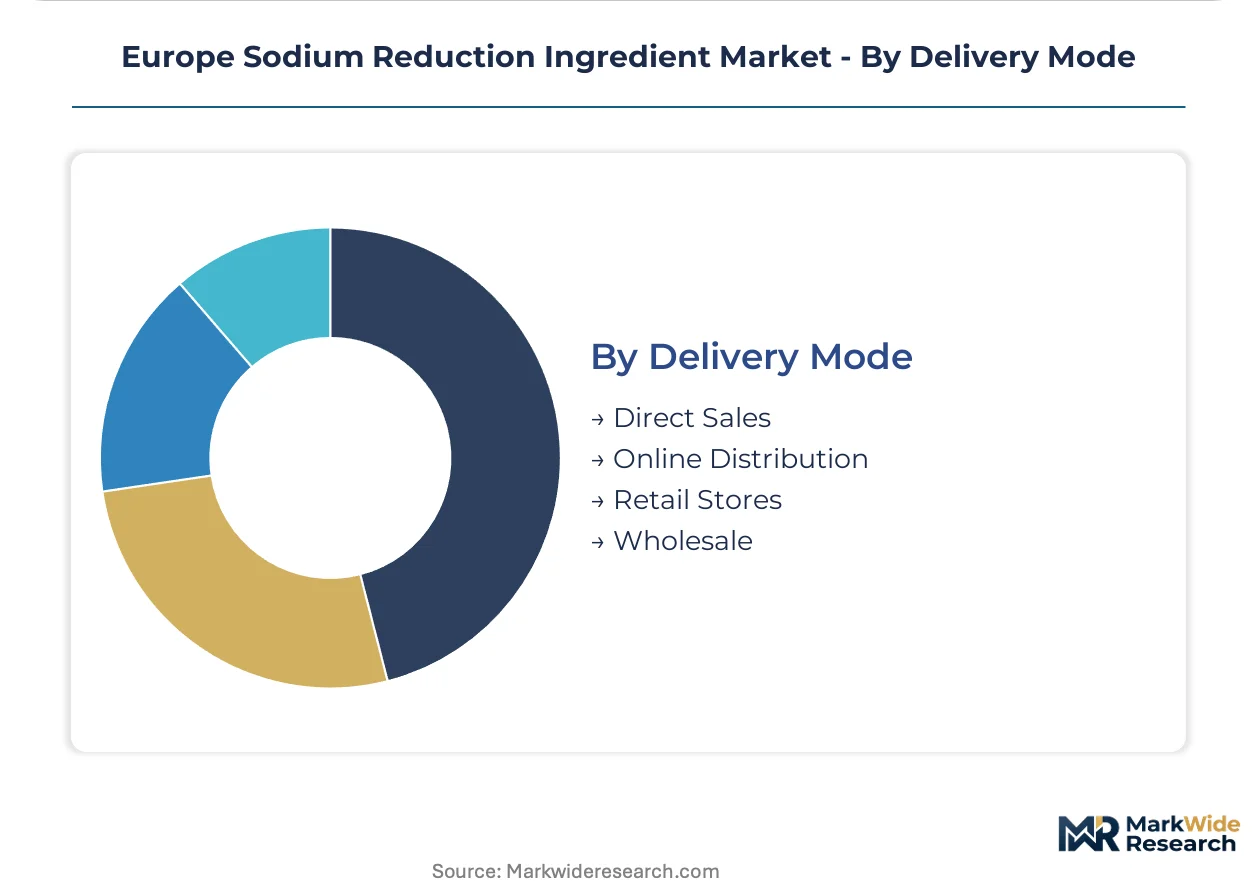
Delivery Mode:
Supply chain configuration varies by customer scale, with large industrial accounts demanding integrated technical service while smaller buyers accept standard distribution terms.
- Direct Sales:Large food manufacturers negotiate integrated technical service contracts including on-site formulation support. French and Spanish private-label bakery groups require rapid recipe iteration cycles as standard contract terms.
- Online Distribution:Specialty ingredient platforms serve health food brands and smaller organic processors with lower minimum order quantities.
- Retail Stores:Limited relevance for industrial-grade sodium reduction ingredients.
- Wholesale:Traditional distributors retain position in mid-tier meat processing accounts without dedicated technical staff.
Direct Sales commands the highest value concentration. Online Distribution is expanding most quickly among emerging health food brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight network underwrites Europe's sodium reduction ingredient trade, connecting German chemical processing hubs to French and Dutch food manufacturing clusters with dedicated bulk mineral salt logistics.
Germany
Industrial bakeries in Lower Saxony and meat processors in Bavaria absorb the highest regional volumes of potassium chloride substitutes. The Federal Ministry of Food and Agriculture enforces binding sodium reduction targets aligned with WHO recommendations. Hamburg's port infrastructure handles inbound mineral salt raw materials for redistribution across Central European reformulation programs.
France
Private-label bread reformulation drives concentrated demand for yeast extract systems in Paris Basin industrial bakeries. ANSM and DGCCRF coordinate enforcement of EU Front-of-Pack Nutrition Labelling rules through retail inspection protocols. The Auvergne-Rhône-Alpes corridor hosts fermentation-derived taste modulator production facilities serving pan-continental savory applications.
Netherlands
Dutch dairy facilities and snack manufacturers procure mineral salt blends through Rotterdam's chemical distribution terminals. The Dutch Food and Consumer Product Safety Authority implements EFSA-guided sodium disclosure mandates ahead of EU baseline deadlines. Wageningen University's food science cluster generates specialist flavor chemist talent for regional ingredient developers.
United Kingdom
Post-Brexit NHS and school food procurement contracts now mandate sodium thresholds, creating mandated demand pull for technical ingredient suppliers. The Food Standards Agency operates independent salt reduction programs parallel to EU frameworks. Midlands-based meat processing plants retrofit legacy salt dosing infrastructure to accommodate hygroscopic potassium blends.
Poland
Emerging industrial baking chains in the Łódź and Poznań regions represent underpenetrated demand pockets for savory taste modulation systems. The Chief Sanitary Inspectorate aligns national food composition standards with tightening EU nutritional targets. Polish snack manufacturers scale extruded product lines requiring seasoned coating reformulation without sodium load penalties.
Europe Sodium Reduction Ingredient Market Competitive Landscape
Listed leaders compete with private specialists across fermentation technology and mineral processing capabilities, creating a tiered structure where scale-driven commodity suppliers face differentiated biotech challengers. The vendor base clusters around three strategic archetypes: diversified agribusiness conglomerates with integrated salt substitute blending, fermentation-focused ingredient specialists, and regional mineral salt processors. Consolidation pressure intensifies through strategic partnerships between taste modulation technology developers and established distribution networks, while geographic expansion into Eastern European production zones accelerates competitive positioning.
Among diversified agribusiness conglomerates, Cargill Incorporated anchors the commodity salt substitute segment through European blending capacity serving pan-continental bakery chains. Kerry Group exemplifies the fermentation-specialist archetype with savory taste modulation systems that address potassium chloride off-notes. Tate & Lyle occupies a position within the functional ingredient tier, representing the convergence of sweetener expertise into broader reformulation solution portfolios. These three entities collectively illustrate the competitive spectrum from bulk mineral processing to premium biotech-derived systems.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kerry Group |
| Tate & Lyle |
| dsm-firmenich |
| Bunge Limited |
| Royal DSM NV |
| Novozymes A/S |
| Salt of the Earth Ltd |
| Corbion |
| Others |
Supply & Pricing Matrix
Potassium chloride's displacement of sodium chloride in German meat processing and Dutch dairy facilities simultaneously redraws procurement geography toward Rhine-Alpine chemical hubs and compresses margin structures for reformulation service providers. EFSA-mandated front-of-pack disclosure rules accelerate volume commitments from pan-continental bakery chains, amplifying buyer negotiating leverage against mineral salt blenders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the European sodium reduction ingredient trade. Premium fermented systems command valuation multiples due to organic certification and clean-label positioning, while commodity potassium chloride flows through annual offtake contracts indexed to agricultural mineral benchmarks. Price differentiation rests on REACH registration status and technical service bundling. Cost compression in standard mineral salt tiers is intensifying because German chemical processors face energy input volatility. Mid-tier meat processors exhibit highest price sensitivity, whereas private-label bakery groups prioritize formulation speed over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for mineral salt raw materials sourced from Chilean and Israeli extraction operations. Supply concentrates in German chemical processing clusters, Dutch distribution terminals, and French fermentation facilities. The trade draws from potassium chloride ore, yeast biomass, and nucleotide precursors as core inputs. Single-source vulnerability pervades the potassium salt segment where three German blenders control bulk formulation capacity. Distribution runs through technical service-integrated direct sales for large accounts, with specialized brokers serving organic certification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's 2024 front-of-pack labelling mandate constitutes a regulatory inflection that transforms sodium reduction from voluntary reformulation into compulsory technical procurement, compressing adoption timelines and expanding addressable demand across European industrial kitchens.
For Market Incumbents: Fortify German and Dutch production footprints through captive potassium chloride processing capacity to offset supply concentration risk from Chilean ore dependencies. Deepen technical service staffing in French and Spanish bakery clusters where rapid recipe iteration demands strain existing support networks. Invest in REACH registration pipelines for novel mineral complexes before EFSA-WHO guideline divergence hardens into restrictive safety opinions.
For New Entrants and Emerging Players: Lead with fermentation-derived taste modulation systems targeting Polish and Romanian industrial baking chains where savory enhancer penetration remains underdeveloped. Prioritize organic certification pathways to access health food brand procurement channels that bypass mineral salt price competition. Establish direct technical service relationships as contract preconditions, displacing traditional distributor mediation in sodium reduction categories.
For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-focused ingredient specialists with established EFSA safety dossiers and scalable yeast extract production platforms. Long-term viability hinges on regulatory clearance velocity rather than manufacturing scale alone. Monitor EFSA potassium safety opinion updates as the critical signal for which technical platforms secure permanent formulation slots in high-fortification applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potassium Chloride Processing | Captive mineral supply insulates German blenders from Chilean ore price volatility and logistics disruption. |
| Fermentation Capacity Expansion | Yeast extract scale-up in Auvergne-Rhône-Alpes serves pan-continental organic meat alternative reformulation demand. |
| REACH Registration Acceleration | Front-loaded toxicology dossiers compress biotech-derived taste modulator commercialization timelines against regulatory gates. |
| Technical Service Footprint Expansion | On-site formulation support in Polish bakery clusters captures first-mover positioning in underpenetrated Eastern European production zones. |
| Strategic Partnership with Pan-Continental Retailers | Private-label program integration concentrates procurement power and locks out distributor-mediated competitors. |
Research Methodology
Desk research of EFSA guidance documents, EU Green Deal nutritional target publications, and national health agency mandates preceded structured interviews with flavor chemists at ingredient developers, procurement directors at pan-continental bakery chains, regulatory affairs leads at fermentation technology firms, and plant managers at German meat processing facilities. Secondary validation drew from REACH registration databases, WHO sodium intake guidelines, and customs trade flows for potassium chloride imports. Bottom-up volume estimates triangulated against top-down market sizing from reformulation program expenditure tracking.
Variance decomposition across product type, application matrix, end-user procurement pattern, and delivery mode configuration shaped the analytical framework. Modeled segmentation spanned salt substitutes, flavor enhancers, fermented ingredients, and sodium-reducing agents by processed foods, snacks, sauces, and dairy applications. CAGRs derived from elasticity-adjusted penetration curves tied to binding national sodium targets and EFSA disclosure mandate compliance deadlines. Forecast inputs incorporated industrial kitchen reformulation cycle timing and clean-label certification adoption trajectories.
Forecasts assume regulatory continuity in EFSA sodium benchmarks and REACH registration requirements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Fats and Oil Market
Ingredients
Homecare Ingredients Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
Corn Starch Market
Ingredients
Edible Oils and Fats Market
Ingredients
Europe Gelatin Market
Ingredients
Valerian Root Oil Market
Ingredients
Europe Soy Protein Market
Ingredients
Colombia Food Ingredients Market
Ingredients
China Beer Adjuncts Market
Ingredients
Resistant Starch Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Fruit Powder Market
Ingredients
Protein Ingredients Market