
 Buckwheat–Mediterranean Grain Blend Ingredients Market | 2026-2036
Buckwheat–Mediterranean Grain Blend Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Buckwheat–Mediterranean Grain Blend Ingredients Market Insights
Multi-source grain procurement is recalibrating how ingredient suppliers manage supply security and quality consistency. Bob's Red Mill Natural Foods leverages its vertically integrated milling infrastructure to control traceability from farm to package. Wilmar International anchors its position through bulk sourcing networks spanning Eastern European buckwheat belts. Birkett Mills specializes in heritage grain processing, competing on identity-preserved varieties that command premium positioning among health food manufacturers.
Buckwheat–Mediterranean grain blend ingredients comprise formulated mixtures where buckwheat flour serves as the base component combined with chickpea flour, barley, oat groats, rye flakes, or sorghum, typically milled to particle sizes between 80 and 200 microns for uniform hydration in commercial baking and extrusion processes. These blends function primarily as gluten-free structuring agents and protein-fortified bases in bakery goods, pasta alternatives, and nutritional supplements where wheat replacement demands both functional performance and clean-label appeal. The gluten-free products application commands the deepest margin pools as certification requirements and consumer willingness-to-pay for allergen-safe formulations outpace conventional bakery segments. Multigrain mix compositions are gaining fastest among blend categories as formulators seek complexity in amino acid profiles and sensory differentiation beyond single-ingredient substitutes.
EFSA governs novel food approvals and allergen labeling thresholds that determine which blend formulations qualify for health claims across European markets, while the EU Green Deal's deforestation-free supply chain regulations are reshaping import documentation requirements for non-EU grain sources. REACH compliance for processing aids and packaging migrants adds a secondary compliance layer that smaller millers struggle to navigate without dedicated regulatory staff. Stakeholders must monitor how evolving carbon border adjustments and organic equivalence agreements between the EU and major buckwheat-exporting nations redefine cost structures for cross-border ingredient flows.
Market Dynamics
Clean-label certification mandates and EU Green Deal deforestation regulations are forcing ingredient suppliers to restructure sourcing networks and documentation systems for buckwheat and Mediterranean grain inputs.
Growth Catalysts
- EU Green Deal supply chain rules:Deforestation-free import requirements create competitive moats for European millers with established traceability infrastructure.
- Gluten-free bakery expansion:Specialty bakeries in Germany and France are scaling production of allergen-safe bread alternatives using multigrain blends as structuring bases.
- Chickpea flour protein fortification:Formulators are combining buckwheat with legume flours to achieve complete amino acid profiles in pasta alternatives and nutritional supplements.
Market Restraints
- Buckwheat supply concentration:Eastern European growing regions dominate raw material availability, exposing processors to weather-driven yield volatility and geopolitical logistics friction.
- REACH compliance costs:Smaller millers lack dedicated regulatory staff to navigate processing aid and packaging migrant documentation requirements for EU market access.
- Quinoa and te substitution:Alternative gluten-free grains with stronger consumer recognition are capturing shelf space in North American and Asian retail channels.
Strategic Opportunities
- Organic certification hubs in Bavaria:Regional clustering of specialty millers around inspection infrastructure enables premium positioning for identity-preserved heritage varieties.
- Extrusion technology convergence:Twin-screw extrusion combined with micronized milling is opening textured protein applications in plant-based meat analogues.
- Direct-to-manufacturer e-procurement:Digital platforms are bypassing traditional ingredient distributors, allowing smaller blenders to access bakery and supplement formulators directly.
Industry Challenges
- Particle size standardization:Achieving consistent 80-200 micron distributions across variable raw material lots requires capital-intensive optical sorting and air classification equipment.
- Organic equivalence negotiation delays:Pending mutual recognition agreements between the EU and major buckwheat-exporting nations are creating documentation bottlenecks for certified organic shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buckwheat–Mediterranean Grain Blend Ingredients Market |
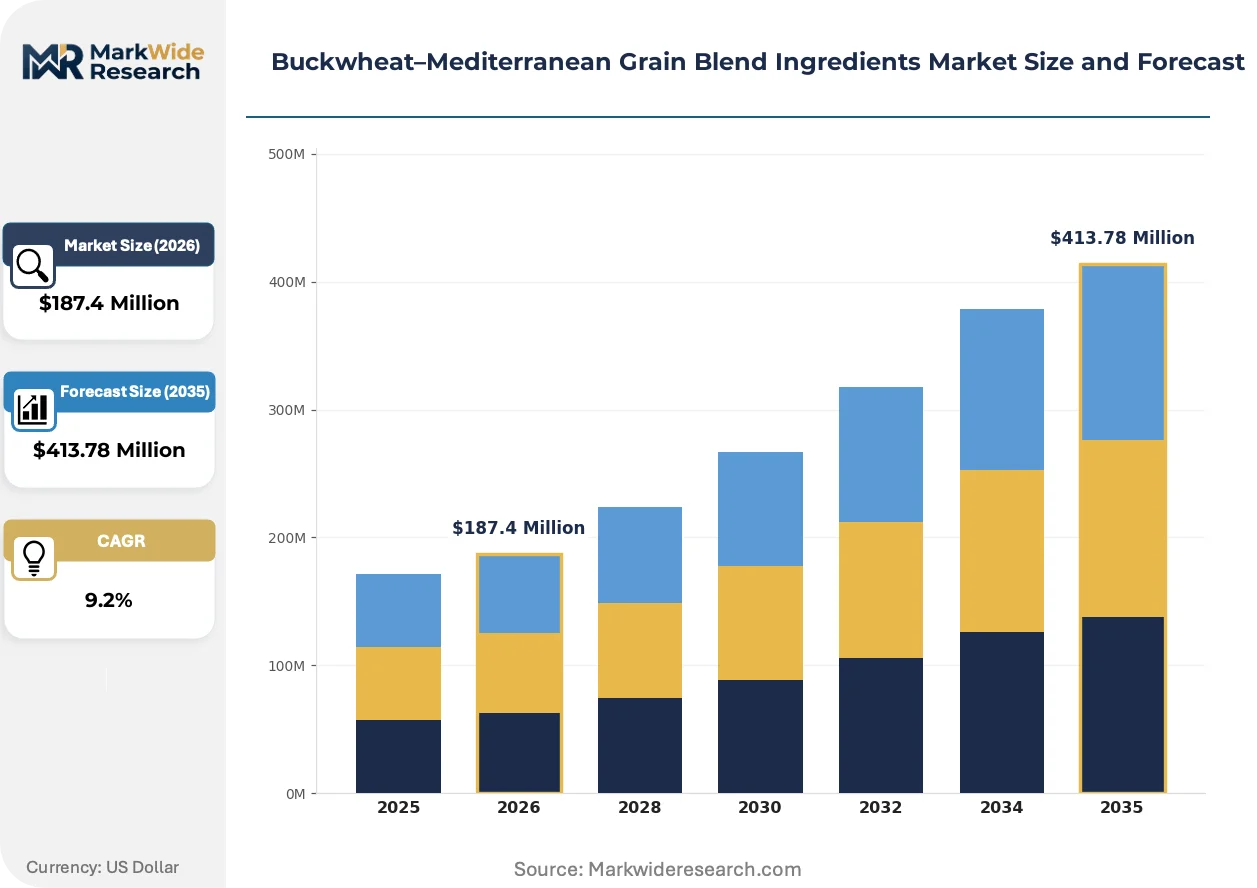
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $413.78 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buckwheat Flour, Chickpea Flour, Barley, Oat Groats, Rye Flakes, Sorghum Blend Composition: 100% Buckwheat, Mixed Legumes, Multigrain Mix, Seed & Nut Integration, Pulse-Enriched, Ancient Cereals Application: Breakfast Cereals, Snack Foods, Gluten-Free Products, Bakery Goods, Pasta Alternatives, Nutritional Supplements End User: Health Food Manufacturers, Gluten-Free Product Firms, Functional Food Developers, Vegan Food Producers, Specialty Retailers, Meal Kit Providers |
| Companies Covered | Archer Daniels Midland, Bob’s Red Mill Natural Foods, Birkett Mills, Doves Farm Foods, Homestead Organics, Wilmar International, Nature’s Path Foods, Galinta Group, Hain Celestial Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buckwheat–Mediterranean Grain Blend Ingredients Market Trends and Innovations
Digital traceability systems and precision milling technologies are compressing quality assurance timelines while regulatory pressure on supply chain transparency intensifies documentation requirements across European markets.
Near-infrared spectroscopy coupled with blockchain ledgering is automating real-time compositional verification and origin tracking for imported buckwheat lots. Large-scale bakery manufacturers in Germany are deploying these systems at receiving docks to reduce laboratory testing bottlenecks. This convergence is automating supplier qualification processes and compressing procurement cycles from weeks to days.
EFSA novel food approval pathways are tightening allergen threshold definitions for multigrain blends containing potential cross-contact sources. The regulatory consequence is forcing reformulators to segregate production lines and validate cleaning protocols with greater stringency. Gluten-free certification bodies in France and Italy are responding by introducing enhanced audit frequencies for facilities processing multiple grain categories.
Ingredient buyers are consolidating supplier relationships around vertically integrated millers capable of delivering farm-to-package documentation. Mid-sized bakery innovators in the Netherlands are displacing multi-vendor sourcing models with single-source contracts that bundle traceability, certification, and technical support. This concentration pattern is most visible in organic and gluten-free segments where liability exposure drives preference for audited supply chains.
Buckwheat–Mediterranean Grain Blend Ingredients Market Segmentation
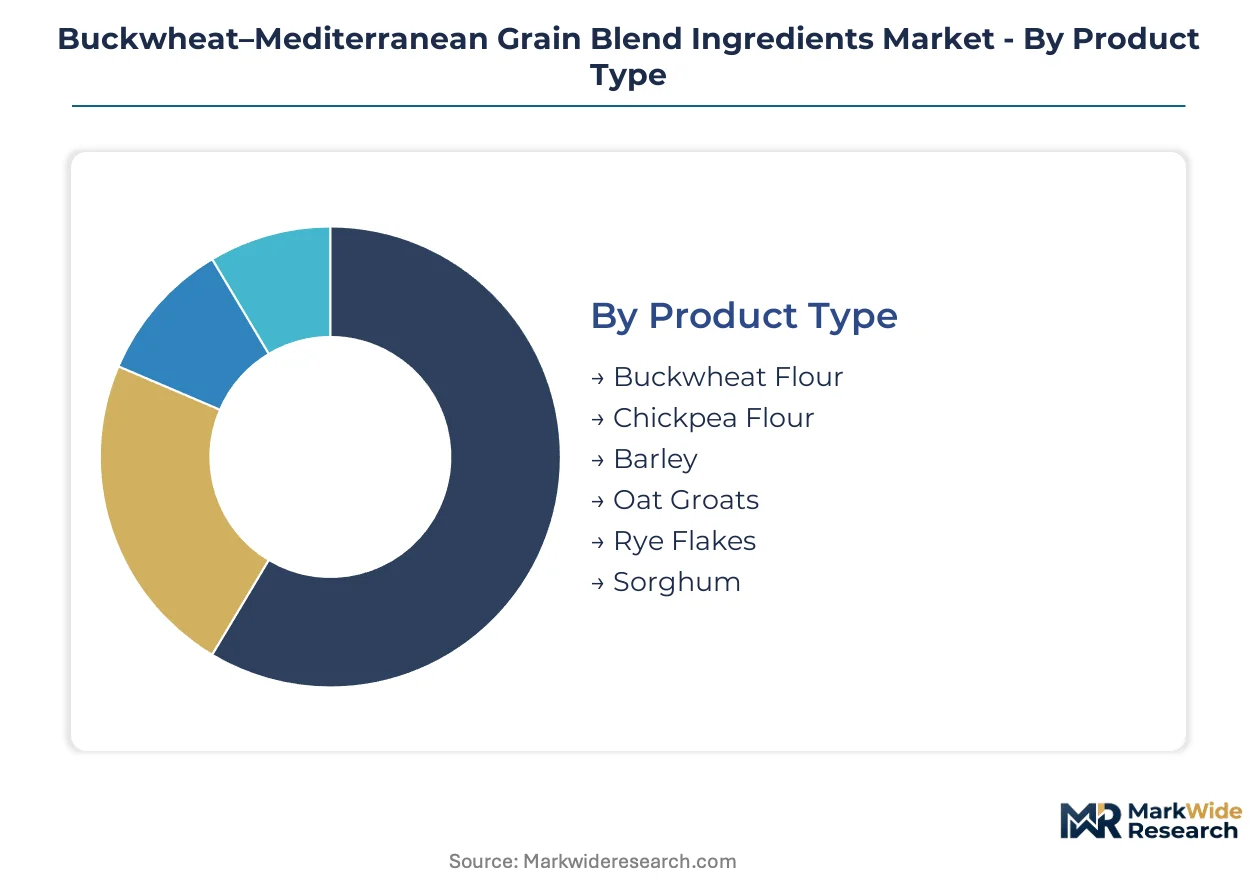
Segmentation in the Buckwheat–Mediterranean Grain Blend Ingredients Market reveals how procurement priorities diverge between mass-market cost efficiency and premium positioning through certification complexity. Buyers select blend categories based on end-use technical requirements, regulatory exposure, and consumer-facing label claims rather than commodity pricing alone.
Product Type:
Cost sensitivity and functional performance separate buyers across this category, with premium positioning demanding identity-preserved sourcing and mass applications tolerating broader origin pools.
- Buckwheat Flour:Milled to 80-200 micron particle specifications, this base ingredient provides the structural backbone for gluten-free formulations. German specialty millers cluster procurement around Bavarian organic certification hubs to secure EFSA-compliant allergen documentation for export-ready blends.
- Chickpea Flour:Legume-derived protein fortification enables complete amino acid profiles in pasta alternatives and nutritional supplements. Formulators in France combine this with buckwheat to meet clean-label demands while navigating REACH compliance for processing aids.
- Barley:Malted and unmalted varieties serve conventional bakery applications where gluten content is permissible.
- Oat Groats:Steel-cut and rolled formats provide textural differentiation in breakfast cereals and snack foods.
- Rye Flakes:Eastern European sourcing dominates, exposing buyers to EU Green Deal deforestation-free documentation requirements.
- Sorghum:Drought-resistant crop appeals to sustainability-positioned brands seeking supply security narratives.
Volume sits with Buckwheat Flour; growth tilts toward Chickpea Flour.
Blend Composition:
Technical complexity and margin structure differentiate procurement patterns, with simpler blends serving cost-driven manufacturers and engineered compositions capturing health-positioned premiums.
- Multigrain Mix:Complex amino acid profiles and sensory differentiation drive fastest adoption among formulators seeking competitive separation from single-ingredient substitutes. Dutch bakery innovators consolidate supplier relationships around vertically integrated millers capable of delivering farm-to-package documentation for these compositions.
- 100% Buckwheat:Pure formulations serve allergen-severe consumer segments where cross-contamination liability demands segregated production lines. Italian gluten-free certification bodies impose enhanced audit frequencies for facilities processing these dedicated blends.
- Mixed Legumes:Chickpea-lentil combinations target protein density in plant-based meat analogues.
- Seed & Nut Integration:Omega-3 positioning appeals to functional food developers in nutritional supplements.
- Pulse-Enriched:Extrusion-compatible formulations serve textured protein applications.
- Ancient Cereals:Heritage variety premiums command positioning among health food manufacturers in Germany.
Volume concentrates in 100% Buckwheat; steepest expansion trajectory belongs to Multigrain Mix.
Application:
Regulatory certification burden and consumer willingness-to-pay create tiered demand, with allergen-safe segments commanding documentation investments that mass-market categories cannot justify.
- Gluten-Free Products:Certification requirements and liability exposure drive preference for audited supply chains with complete traceability infrastructure. EFSA novel food approval pathways and tightening allergen threshold definitions force reformulators to validate cleaning protocols with greater stringency than conventional segments.
- Nutritional Supplements:Protein-fortified bases combining buckwheat with legume flours achieve complete amino acid profiles for sports nutrition and clinical applications. French and Italian manufacturers deploy near-infrared spectroscopy with blockchain ledgering to automate real-time compositional verification.
- Breakfast Cereals:Extruded and flaked formats prioritize cost-efficient bulk sourcing from Eastern European belts.
- Snack Foods:Puffed and baked applications emphasize texture consistency over nutritional claim complexity.
- Bakery Goods:Bread alternatives in Germany scale production using multigrain blends as structuring bases.
- Pasta Alternatives:Chickpea-buckwheat combinations target clean-label positioning in retail and foodservice.
Volume concentrates in Bakery Goods; expansion accelerates fastest in Gluten-Free Products.
End User:
Supply chain sophistication and technical service requirements separate buyers, with large manufacturers demanding bundled traceability and smaller innovators accepting higher per-unit costs for flexibility.
- Gluten-Free Product Firms:Allergen-safe formulation expertise and certification documentation dominate procurement criteria. These buyers consolidate around single-source contracts that bundle technical support with liability protection, displacing multi-vendor sourcing models visible in conventional segments.
- Health Food Manufacturers:Heritage variety premiums and organic certification drive supplier selection toward identity-preserved processors like Birkett Mills. Bavarian regional clustering enables premium positioning through inspection infrastructure proximity.
- Functional Food Developers:Clinical and sports nutrition applications demand precise compositional specifications.
- Vegan Food Producers:Plant-based meat analogue applications leverage extrusion technology convergence.
- Specialty Retailers:Private-label sourcing prioritizes packaging claim compliance over technical formulation support.
- Meal Kit Providers:Direct-to-manufacturer e-procurement platforms bypass traditional distributors for smaller volume access.
Volume concentrates in Health Food Manufacturers; Gluten-Free Product Firms gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern European buckwheat belts anchor raw material availability for processors serving Western European formulators. Procurement networks concentrate around Black Sea growing regions and Baltic milling corridors, with logistics friction and EU Green Deal documentation requirements reshaping cross-border ingredient flows.
Germany
Specialty millers in Bavaria cluster around organic certification hubs to secure EFSA-compliant allergen documentation for export-ready blends. The EU Green Deal's deforestation-free supply chain regulations force importers to restructure documentation systems for non-EU grain sources. Munich and Nuremberg host bakery innovators scaling gluten-free bread production using multigrain blends as structuring bases.
France
Chickpea-buckwheat combinations target clean-label positioning in retail pasta alternatives and nutritional supplements. EFSA novel food approval pathways tighten allergen threshold definitions, forcing reformulators to validate cleaning protocols with enhanced stringency. Lyon and Paris basin manufacturers deploy near-infrared spectroscopy with blockchain ledgering to automate real-time compositional verification at receiving docks.
Netherlands
Mid-sized bakery innovators consolidate supplier relationships around vertically integrated millers capable of delivering farm-to-package documentation. REACH compliance for processing aids and packaging migrants adds regulatory complexity that smaller millers navigate with difficulty. Rotterdam and Amsterdam corridors concentrate extrusion technology convergence for textured protein applications in plant-based meat analogues.
Italy
Gluten-free certification bodies impose enhanced audit frequencies for facilities processing dedicated 100% buckwheat blends for allergen-severe consumer segments. EFSA governs health claim qualifications that determine which formulations achieve premium positioning. Emilia-Romagna and Lombardy host heritage grain processors competing on identity-preserved varieties among health food manufacturers.
Poland
Domestic buckwheat cultivation supplies regional millers with raw material proximity advantages over Western European competitors. Pending organic equivalence negotiations between the EU and major buckwheat-exporting nations create documentation bottlenecks for certified organic shipments. Warsaw and Krakow processing corridors leverage Eastern European growing region access to manage supply security for export markets.
Buckwheat–Mediterranean Grain Blend Ingredients Market Competitive Landscape
Global majors compete with regional champions across traceability infrastructure and certification bundling. The supplier base organizes around vertically integrated millers with farm-to-package documentation capabilities, mid-sized heritage processors competing on identity-preserved varieties, and bulk sourcing networks anchored in Eastern European growing belts. Three archetypes dominate: integrated traceability providers, heritage variety specialists, and volume-driven commodity processors. Competitive moves concentrate on single-source contract consolidation and optical sorting equipment deployment for particle size standardization.
Among integrated North American millers, Bob's Red Mill Natural Foods and Birkett Mills occupy positions exemplifying the traceability-provider and heritage-specialist archetypes respectively. Wilmar International represents the bulk-sourcing network model anchored in Eastern European supply corridors. These three entities illustrate how procurement sophistication, certification complexity, and raw material proximity define competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Bob's Red Mill Natural Foods |
| Birkett Mills |
| Doves Farm Foods |
| Homestead Organics |
| Wilmar International |
| Nature's Path Foods |
| Galinta Group |
| Hain Celestial Group |
| Others |
Pricing and Supply Chain Analysis
Backward integration into Eastern European buckwheat cultivation anchors supply security for German and French millers while compressing procurement cycles and supporting premium positioning through farm-to-package traceability. This integration choice concentrates pricing power among vertically integrated processors capable of bundling certification documentation with technical service, leaving smaller blenders exposed to spot-market volatility and REACH compliance cost pass-throughs.
Pricing Analysis
Service bundling separates contract structures in this market, with comprehensive offerings including EFSA-compliant allergen documentation and blockchain traceability commanding substantial premiums over unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and volume scale, with organic and gluten-free certified blends capturing the highest margins. Pricing pressure stems from EU Green Deal deforestation-free documentation requirements that inflate procurement costs for non-EU grain sources. Mid-sized bakery innovators in the Netherlands exhibit greatest price sensitivity, while gluten-free product firms prioritize liability protection over unit cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Eastern European buckwheat belts in Poland, Ukraine, and Russia, where weather-driven yield volatility and geopolitical logistics friction concentrate exposure for Western European processors. Raw material procurement draws from buckwheat groats, chickpea legumes, and heritage cereal varieties, with optical sorting equipment requirements creating capital barriers to quality consistency. Tariff exposure intensifies as pending organic equivalence negotiations between the EU and major exporting nations generate documentation bottlenecks for certified shipments. Distribution runs through vertically integrated millers with direct-to-manufacturer e-procurement platforms increasingly displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy coupled with blockchain ledgering is displacing legacy laboratory testing protocols, compressing quality assurance timelines from weeks to days while automating supplier qualification processes.
For Market Incumbents: Acquire optical sorting and air classification equipment to standardize 80-200 micron particle distributions across variable raw material lots. Consolidate supplier relationships around single-source contracts bundling traceability, certification, and technical support to defend against emerging digital-platform competitors. Invest in segregated production lines with enhanced cleaning protocol validation to meet tightening EFSA novel food approval pathways. For New Entrants and Emerging Players: Technology-first extrusion capability convergence opens textured protein applications in plant-based meat analogues as a penetrable white-space target. Focus initial market entry on Bavarian organic certification hubs where regional clustering of specialty millers enables premium positioning for identity-preserved heritage varieties. Deploy direct-to-manufacturer e-procurement platforms to bypass traditional ingredient distributors and access smaller volume bakery and supplement formulators directly. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated North American millers seeking European traceability infrastructure and EFSA-compliant documentation capabilities. Long-term viability across the projection horizon favors vertically integrated processors with captive supply from Eastern European growing belts and in-house milling capacity. Monitor organic equivalence negotiation outcomes between the EU and major buckwheat-exporting nations as the critical inflection signal for cross-border cost structure redefinition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive supply from Polish and Ukrainian buckwheat belts reduces tariff exposure and documentation friction. |
| Blockchain Traceability Deployment | Real-time compositional verification at Rotterdam and Amsterdam receiving docks compresses procurement cycles. |
| Extrusion Technology Convergence | Twin-screw systems combined with micronized milling enable textured protein applications for plant-based meat analogues. |
| Organic Certification Hub Clustering | Proximity to Bavarian inspection infrastructure supports premium positioning for heritage variety processors. |
| Direct E-Procurement Platform Launch | Digital channels bypass traditional distributors to connect smaller blenders with Dutch bakery innovators directly. |
Research Methodology
Trade databases, EFSA regulatory filings, and EU Green Deal implementation documents formed the secondary backbone for supply chain mapping and compliance trajectory assessment. Primary interviews with specialty miller procurement directors, gluten-free product firm formulation scientists, and REACH regulatory consultants combined with this secondary validation. Bottom-up and top-down triangulation cross-checked volume estimates against customs records and downstream consumption patterns.
Bottom-up modeling aggregated segment-level demand across product type, blend composition, application, and end user dimensions, while top-down approaches validated aggregate market scale against macroeconomic indicators. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and technology adoption curves across the analysis window. Industry-specific forecast inputs included EU organic equivalence negotiation timelines and extrusion technology penetration rates in plant-based meat applications.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to EFSA allergen thresholds and unforeseen geopolitical disruptions to Eastern European grain flows. Forecasts reflect documented assumptions about certification body audit frequency evolution and carbon border adjustment implementation pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Virgin Coconut Oil Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Gymnema Extract Market
Ingredients
Rice Bran Oil Market
Ingredients
Casein Hydrolysate Market
Ingredients
Marine Ingredients Market
Ingredients
Functional Flours Market
Ingredients
Pet Food Ingredients Market
Ingredients
African Brewing Enzymes Market
Ingredients
Commercial Amino Acids Market
Ingredients
Meat Extract Market
Ingredients
France Soy Protein Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Oyster Shell Powder Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market