
 Pea Protein Ingredients Industry Status and Prospects Professional Market | 2026-2036
Pea Protein Ingredients Industry Status and Prospects Professional Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Protein Ingredients Industry Status and Prospects Professional Market Analytics
REACH is expanding the cost-of-entry calculus for pea protein suppliers seeking European market access, as registration requirements for novel food ingredients intensify documentation burdens. Roquette Frères leverages its decades of pulse processing expertise to dominate supply contracts with multinational food manufacturers. Cosucra sustains competitive positioning through backward integration into Belgian pea farming cooperatives. Ingredion competes by diversifying its portfolio across both concentrate and isolate grades for distinct application tiers.
Pea protein ingredients encompass fractionated proteins extracted from yellow and green field peas through dry milling, air classification, and wet extraction processes yielding protein contents ranging from 55% in concentrates to 90% in isolates, serving primarily as functional emulsifiers and nutritional fortifiers across formulated foods. Isolates command premium positioning in meat alternatives and dairy alternatives where solubility and neutral flavor profiles justify higher ingredient costs, while concentrates retain volume leadership in bakery and animal feed applications where cost efficiency outweighs purity requirements. Textured pea protein is gaining fastest in protein supplements as brands seek clean-label positioning distinct from whey and soy sources.
The FDA governs GRAS self-affirmation pathways for pea protein in the United States, while EFSA evaluates novel food dossiers for expanded use claims across the European Union, and Health Canada maintains distinct approval tracks for plant protein ingredient notifications. These frameworks shape reformulation timelines, label claim permissibility, and cross-border shipment eligibility for finished goods containing pea-derived inputs. Stakeholders must monitor evolving protein content thresholds in organic certification standards and anticipate how carbon footprint labeling requirements will alter sourcing decisions between European and North American suppliers.
Market Dynamics
Extrusion technology advancement is compressing texture development timelines for meat analogues while REACH documentation requirements are extending supplier onboarding cycles in Europe.
Growth Catalysts
- EU Green Deal protein strategy:Agricultural subsidy redirection toward domestic pulse cultivation is reducing import dependence and stimulating regional processing capacity expansion.
- Clean-label positioning:Sports nutrition brands are accelerating formulation switches from whey and soy to pea-derived isolates for allergen-free protein supplements.
- Germany:Food technologists in this market have pioneered fibrous extrusion processes that elevate sensory performance of plant-based meat alternatives.
Market Restraints
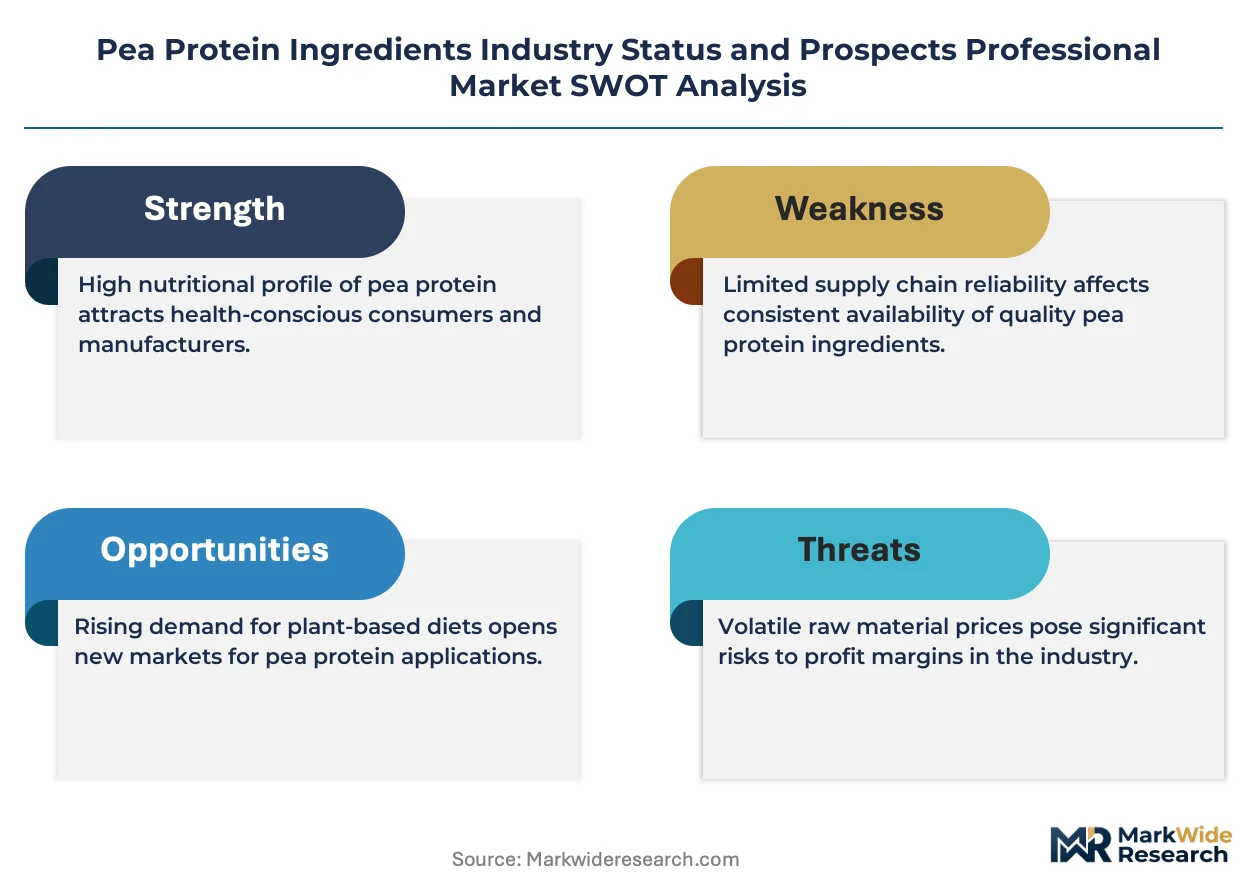
- Yellow pea supply concentration:North American growing regions dominate raw material sourcing, exposing processors to climate volatility and trade friction.
- REACH registration burdens:ECHA documentation requirements for novel protein fractions are elevating cost-of-entry for suppliers seeking European market access.
- Flavor masking costs:Beany off-notes in standard isolates necessitate additional processing steps or expensive masking systems that compress margins.
Strategic Opportunities
- Textured pea protein:This emerging format category is capturing share in protein supplements as brands differentiate from commodity isolates.
- EFSA novel food pathways:Expanded use claim approvals are opening formulation possibilities in dairy alternatives and infant nutrition segments.
- Carbon footprint labeling:Upcoming requirements will favor European-sourced peas over transatlantic shipments, rewarding regional backward integration.
Industry Challenges
- Extrusion engineering talent:Scarcity of food technologists skilled in high-moisture extrusion is constraining textured protein production scale-up.
- Organic certification timelines:Protein content threshold disputes in organic standards are delaying product launches and reformulation cycles.
- Cross-border shipment eligibility:Divergent GRAS self-affirmation versus novel food dossier requirements are complicating finished goods distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Protein Ingredients Industry Status and Prospects Professional Market |
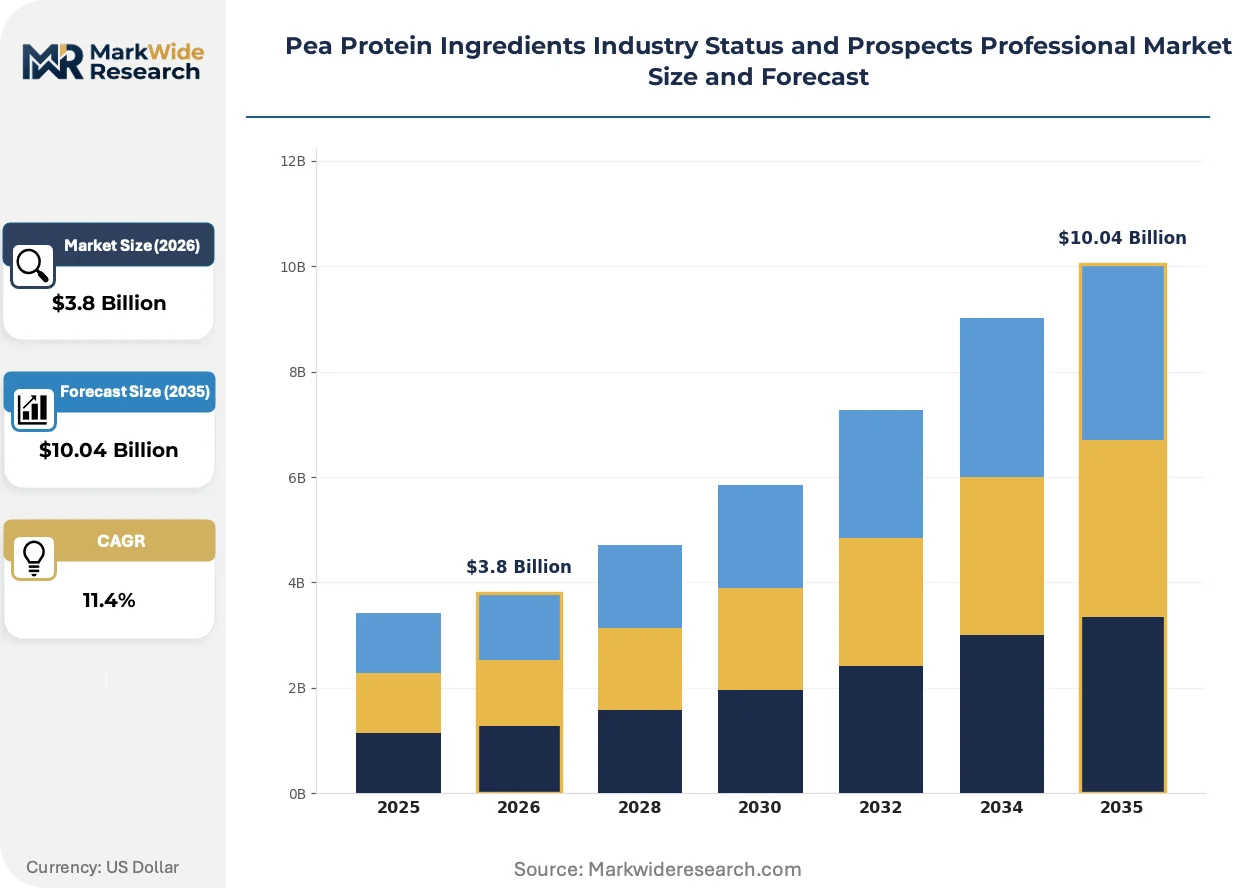
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Isolates, Flour, Textured End User: Food & Beverage, Nutraceuticals, Cosmetics, Animal Feed Application: Meat Alternatives, Bakery, Dairy Alternatives, Protein Supplements Distribution Channel: Online Retail, Supermarkets, Health Stores, Distributors |
| Companies Covered | Archer Daniels Midland, Kerry Group, Ingredion, Roquette Frères, Cosucra, GlobePeas, Pur peas, Axiom Foods, NutriPea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Protein Ingredients Industry Status and Prospects Professional Market Evolving Landscape
Processing technology is advancing faster than formulation science, creating capability gaps between equipment suppliers and food manufacturers seeking precise texture control.
High-moisture extrusion is converging with air classification systems to produce layered fibrous structures that replicate muscle tissue architecture. Plant-based meat manufacturers in Germany and the Netherlands are adopting these integrated lines at pilot scale. The technology is converging with traditional meat processing workflows, enabling shared equipment utilization and reducing capital barriers for protein diversification.
REACH is tightening purity documentation requirements for protein isolates entering European food applications. ECHA has expanded substance data set obligations for imported pulse fractions, forcing suppliers to retrofit supply chain traceability systems. Concentrate-grade suppliers targeting bakery fortification are most affected, as they lack the margin structure to absorb compliance investments.
Direct procurement relationships between food manufacturers and farming cooperatives are displacing commodity broker intermediaries. Large meat analogue producers are signing multi-year offtake agreements with Belgian and French pulse growers, securing volume and traceability. This pattern is most visible in Germany, where sustainability reporting requirements under CSRD are mandating supplier emission disclosures that brokers cannot provide.
Pea Protein Ingredients Industry Status and Prospects Professional Market Segmentation
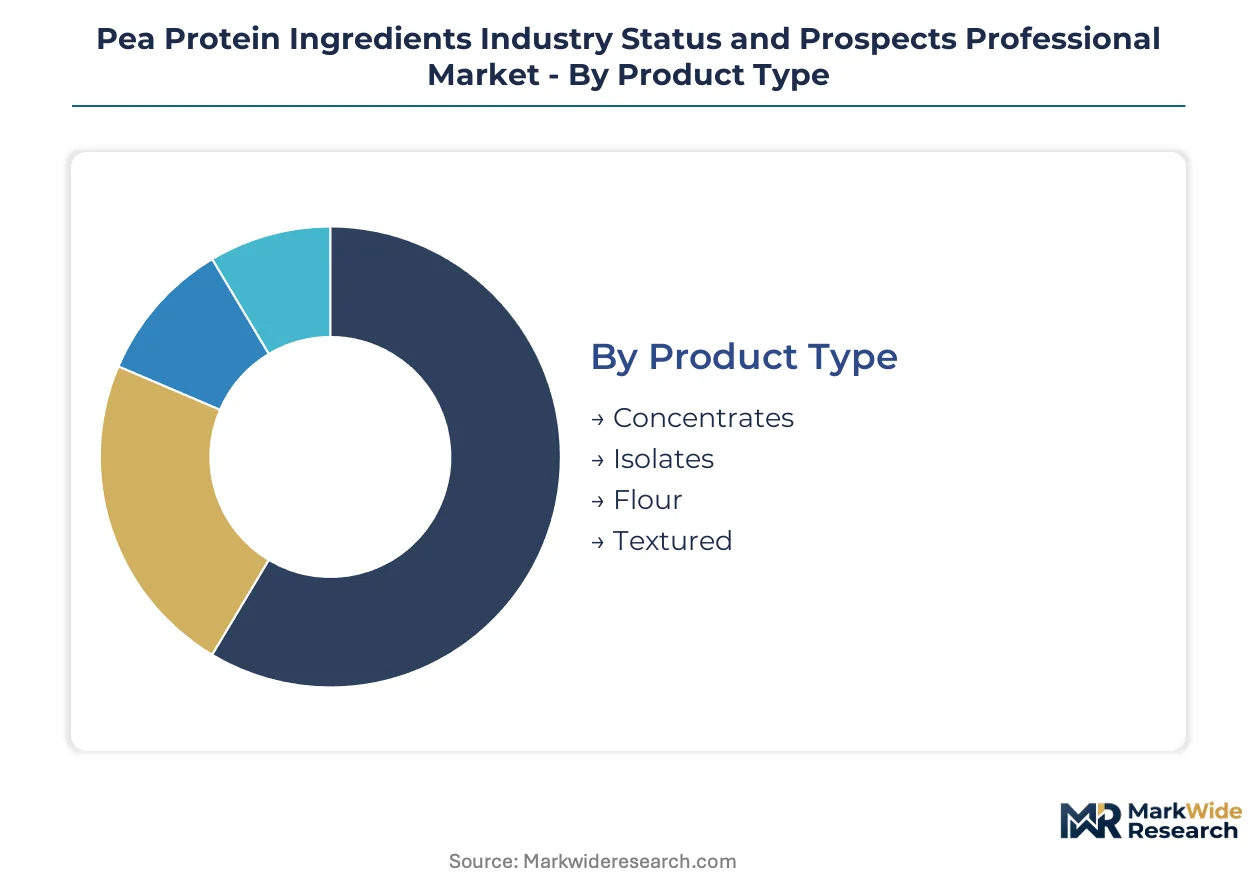
Pea protein ingredient procurement patterns diverge sharply across product grades and end-use specifications. Manufacturers optimize formulation costs by matching protein concentration tiers to functional requirements in target applications.
Product Type:
Capital intensity escalates dramatically from dry-milled flour through wet-extracted isolates, with fractionation equipment representing the dominant upfront investment barrier.
- Concentrates:These 55-80% protein fractions undergo air classification without full wet extraction, preserving native starch and fiber matrices. Bakery fortification in Germany absorbs the largest concentrate volumes, though margin compression from organic certification disputes is forcing suppliers toward contract manufacturing arrangements.
- Isolates:Achieving 85-90% protein purity demands alkali solubilization followed by isoelectric precipitation, requiring stainless steel processing trains and wastewater treatment infrastructure. Meat analogue producers in the Netherlands are locking in multi-year isolate supply agreements to secure texture-critical solubility specifications.
- Flour:Whole-milled pea powder at 20-25% protein content serves cost-sensitive animal feed compounders and emerging-market bakery applications where functional performance requirements remain minimal.
- Textured:Extruded fibrous structures from concentrate or isolate feedstocks command specialized twin-screw extrusion capital outlays that smaller processors avoid.
Most installed capacity flows through concentrates. Expansion is steepest in textured formats.
End User:
Customer technical sophistication determines specification stringency and thereby supplier qualification timelines.
- Food & Beverage:Formulation teams at multinational meat and dairy analogue manufacturers enforce the tightest protein dispersibility and flavor masking standards, driving isolate adoption despite 40-60% price premiums over concentrates.
- Nutraceuticals:Sports nutrition brands seeking allergen-free positioning are switching whey and soy formulations to pea isolates, with German contract manufacturers leading clean-label capsule and powder development.
- Cosmetics:Pea-derived peptides for topical applications represent a nascent value pool with limited current volume but expanding EFSA novel food-adjacent interest.
- Animal Feed:Pet food manufacturers in France and Belgium are substituting pea flour for soy meal in premium positioning strategies, leveraging domestic pulse cultivation subsidies.
Food and beverage commands the dominant procurement volume. Nutraceuticals are climbing the fastest.
Application:
Functional performance requirements in finished goods dictate protein grade selection and thereby ingredient supplier tier.
- Meat Alternatives:High-moisture extrusion of isolates into fibrous structures replicating muscle tissue architecture demands the most advanced texturization capability, with German food technologists pioneering process integration that European processors are licensing.
- Bakery:Concentrates at 5-15% inclusion rates improve dough hydration and crumb structure without the solubility demands justifying isolate costs, though organic certification protein threshold disputes are delaying launches.
- Dairy Alternatives:Barista-grade foam stability and neutral flavor profiles in oat-pea blended milks require isolate grades with extensive flavor masking investment.
- Protein Supplements:Ready-to-mix powder brands are differentiating through textured pea protein formats that signal processing innovation beyond commodity isolates.
Meat alternatives absorb the steepest technology investment. Protein supplements are expanding most quickly.
Distribution Channel:
Channel selection reflects customer scale and traceability documentation requirements rather than product differentiation.
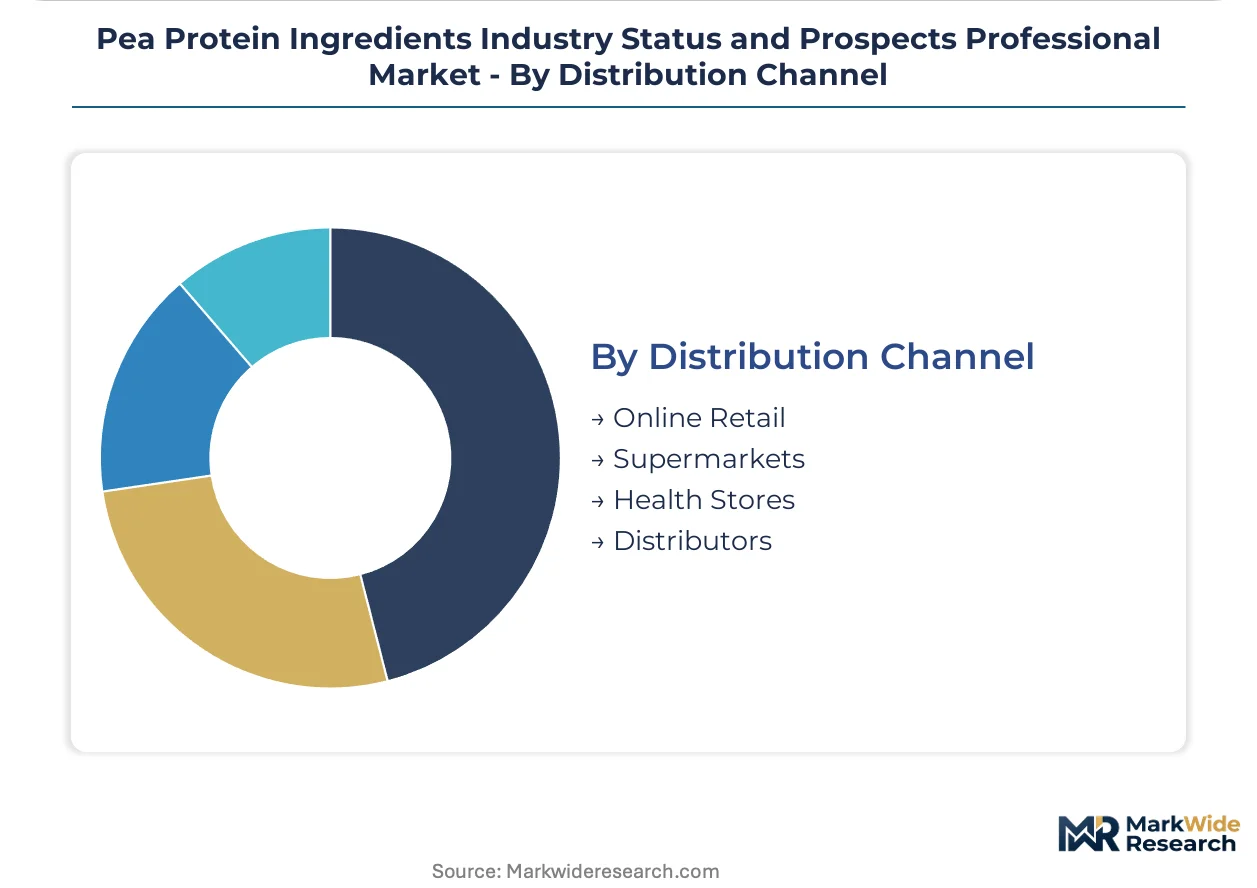
- Online Retail:Direct-to-consumer sports nutrition brands in Germany are bypassing traditional distribution to capture margin and control sustainability narrative, though REACH documentation complexity favors established suppliers with compliance infrastructure.
- Supermarkets:Private-label plant-based meat and dairy analogue procurement flows through centralized buying desks demanding multi-year volume commitments that only integrated processors can satisfy.
- Health Stores:Specialty retailers stock premium-priced organic-certified concentrates targeting allergen-conscious consumers, with Belgian cooperative-sourced products gaining shelf space.
- Distributors:Ingredient brokers are losing share to direct manufacturer-grower relationships as CSRD emission disclosure mandates require supply chain visibility they cannot provide.
Supermarkets channel the largest volume. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists in Germany anchor the European extrusion engineering workforce, while North American yellow pea cultivation clusters around the northern Great Plains and Canadian prairie provinces.
Germany
Meat analogue manufacturers in Cologne and Hamburg drive isolate procurement volumes. EFSA novel food dossier requirements shape reformulation timelines for dairy alternatives. High-moisture extrusion specialists in Lower Saxony license fibrous texturization processes to Dutch and Belgian processors.
United States
Yellow pea supply concentrates in North Dakota and Montana, with wet-milling capacity expanding in Minnesota. FDA GRAS self-affirmation pathways accelerate ingredient approvals relative to European novel food tracks. Twin-screw extrusion equipment suppliers in Wisconsin serve domestic meat alternative startups.
France
Pet food manufacturers in Brittany substitute pea flour for soy meal under EU Green Deal protein strategy subsidies. ANSM consults on novel ingredient safety for human applications. Roquette Frères operates pulse processing headquarters in Lestrem, supplying multinational food manufacturers.
Canada
Prairie provinces of Saskatchewan and Manitoba dominate organic yellow pea exports to European isolators. Health Canada maintains distinct approval tracks for plant protein ingredient notifications. Winnipeg-based processors supply concentrates to US bakery fortification markets.
Belgium
Cosucra sources from Walloon farming cooperatives under backward integration models. REACH documentation requirements for imported fractions favor domestic traceability systems. Brussels food technologists collaborate with Dutch extrusion engineers on barista-grade foam stability formulations.
Pea Protein Ingredients Industry Status and Prospects Professional Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Roquette Frères and Ingredion anchor the integrated processor tier with multi-continent milling networks. Mid-scale European cooperatives occupy regional sourcing positions. Emerging textured protein specialists license German extrusion engineering. Capacity expansion and strategic partnerships dominate competitive moves, with direct procurement relationships displacing commodity brokers.
Among diversified agribusiness conglomerates, Archer Daniels Midland and Kerry Group exemplify portfolio breadth spanning multiple protein sources beyond pea isolates. Roquette Frères occupies a position within the pulse processing specialist archetype, leveraging decades of fractionation expertise. These three entities represent contrasting strategic postures: conglomerate diversification versus ingredient focus versus cooperative integration models.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Kerry Group |
| Ingredion |
| Roquette Frères |
| Cosucra |
| GlobePeas |
| Pur peas |
| Axiom Foods |
| NutriPea |
| Others |
Value Network & Pricing Analysis
High-moisture extrusion technology diffusion is compressing texture development timelines while simultaneously concentrating capital requirements among processors capable of integrated wet-extraction and texturization operations. This dual effect rewards established European players with existing fractionation infrastructure while elevating barriers for commodity concentrate suppliers lacking extrusion engineering partnerships.
Pricing Analysis
Unbundled isolate-grade protein commands substantial premiums over bundled concentrate offerings with attached technical support and formulation services. Three-tier pricing structure across premium isolate, standard concentrate, and economy flour segments reflects protein purity gradients and certification burdens. Pricing pressure stems from REACH documentation requirements elevating compliance costs for imported fractions. Animal feed compounders exhibit highest price sensitivity, while meat analogue manufacturers absorb premiums for solubility-critical isolates.
Supply Chain Analysis
Transatlantic freight cost volatility is reshaping procurement geography as European processors seek domestic pulse sourcing under CSRD emission disclosure mandates. Raw material supply draws from Canadian prairie provinces, North Dakota, and emerging French-Belgian cultivation clusters. Wet-milling capacity hinges on alkali and isoelectric precipitation chemical inputs. Single-source vulnerability concentrates in North American yellow pea growing regions exposed to climate volatility. Distribution runs through direct manufacturer-grower relationships displacing commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea protein ingredient procurement functions as a geographic-arbitrage play between North American raw material abundance and European regulatory premium capture, with REACH compliance costs widening the effective cost differential between transatlantic and regional sourcing.
For Market Incumbents: Deepen backward integration into Belgian and French farming cooperatives to secure traceability documentation required under CSRD emission disclosure rules. Expand high-moisture extrusion capacity in Lower Saxony to license fibrous texturization processes before engineering talent scarcity constrains scale-up. Counter emerging textured protein specialists by locking multi-year isolate supply agreements with Dutch meat analogue manufacturers.
For New Entrants and Emerging Players: Sports nutrition contract manufacturers in Germany present the most penetrable channel partner type for clean-label isolate positioning against whey and soy incumbents. Target online retail distribution to capture margin and control sustainability narrative bypassing supermarket buying desk concentration. Exploit EFSA novel food pathway expertise gaps among established processors to differentiate through expanded use claim approvals in dairy alternatives.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European cooperatives lacking extrusion engineering partnerships but possessing established organic certification and regional sourcing relationships. Long-term viability centers on carbon footprint labeling requirements favoring backward-integrated processors over import-dependent competitors. Watch for EFSA novel food dossier approval velocity as inflection indicator for formulation expansion into infant nutrition segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | CSRD emission disclosure mandates reward traceability systems that commodity brokers cannot provide. |
| High-Moisture Extrusion Capacity Expansion | German engineering licenses enable fibrous texture replication that elevates meat analogue sensory performance. |
| EFSA Novel Food Dossier Investment | Expanded use claim approvals open formulation possibilities in dairy alternatives and infant nutrition segments. |
| Direct Manufacturer-Grower Procurement | Multi-year offtake agreements secure volume and traceability while displacing intermediary margins. |
| Textured Protein Format Development | Specialized twin-screw extrusion output differentiates brands from commodity isolate competition in supplements. |
Research Methodology
Direct dialogue with food technologists, procurement directors at multinational meat analogue manufacturers, regulatory affairs specialists navigating EFSA novel food pathways, and farming cooperative managers grounded qualitative findings. Secondary validation drew from ECHA substance data sets, EU Green Deal protein strategy documentation, FDA GRAS self-affirmation filings, and customs trade records. Bottom-up volume modeling across isolate, concentrate, flour, and textured grades triangulated against top-down protein ingredient market sizing.
Bottom-up demand modeling segmented by product type, end user, application, and distribution channel informed value projections across the analysis window. CAGRs derived from protein content tier adoption curves, extrusion technology diffusion rates, and regulatory approval timeline assumptions. Forecast inputs incorporated EU agricultural subsidy redirection patterns, organic certification threshold disputes, and carbon footprint labeling implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate volatility in North American growing regions, REACH documentation requirement expansions, and extrusion engineering talent scarcity. Forecasts reflect documented assumptions about technology adoption and regulatory implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sea Salt Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Rice Bran Oil Market
Ingredients
Pea Peptones Market
Ingredients
Food Amino Acids Market
Ingredients
Vegetable Concentrates Market
Ingredients
Sunflower Meal Market
Ingredients
North America Phytosterols Market
Ingredients
Liquid Feed Market
Ingredients
African Brewing Enzymes Market
Ingredients
Europe Phytosterols Market
Ingredients
Savory Ingredients Market
Ingredients
Specialty Starch Market
Ingredients
Amylase Market