
 Smart Warehouse System Market | 2026-2036
Smart Warehouse System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Warehouse System Market Analytics
Skilled automation technician shortages across developed economies is redrawing competitive boundaries for warehouse technology providers. Dematic leverages its deep vertical integration in automated storage and retrieval to sustain project margins in North America. Daifuku anchors its position through manufacturing scale in conveyor and sortation systems for high-throughput distribution centers. Manhattan Associates differentiates via software-centric architectures that integrate warehouse execution with broader supply chain orchestration.
A smart warehouse system integrates hardware and software layers to automate material handling, inventory tracking, and order fulfillment operations, typically incorporating real-time sensor networks with sub-second latency and robotic actuators operating at throughput rates exceeding 1,000 picks per hour. Its primary commercial purpose is to minimize labor dependency while maximizing inventory accuracy and order cycle velocity. Warehouse Management Systems command the largest installed base and margin pool due to their position as the data orchestration layer connecting upstream ERP to downstream automation. Automated Guided Vehicles represent the fastest-expanding technology segment as lithium-ion powertrains and AI-based navigation slash deployment timelines. Robotics specialization in piece-picking and palletizing is maturing fastest in ambient-temperature e-commerce environments where SKU variability remains constrained.
The EU Machinery Directive and CE marking requirements shape product design standards for robotic systems deployed across European distribution networks, while OSHA workplace safety regulations in the United States mandate protective protocols around human-robot collaboration zones that directly influence system architecture decisions. China's GB standards and MIIT guidelines for industrial internet platforms are accelerating domestic certification requirements for connected warehouse equipment. Stakeholders must monitor how divergent safety certification timelines across these jurisdictions affect cross-border deployment strategies and total cost of ownership calculations for multi-national fulfillment networks.
Market Dynamics
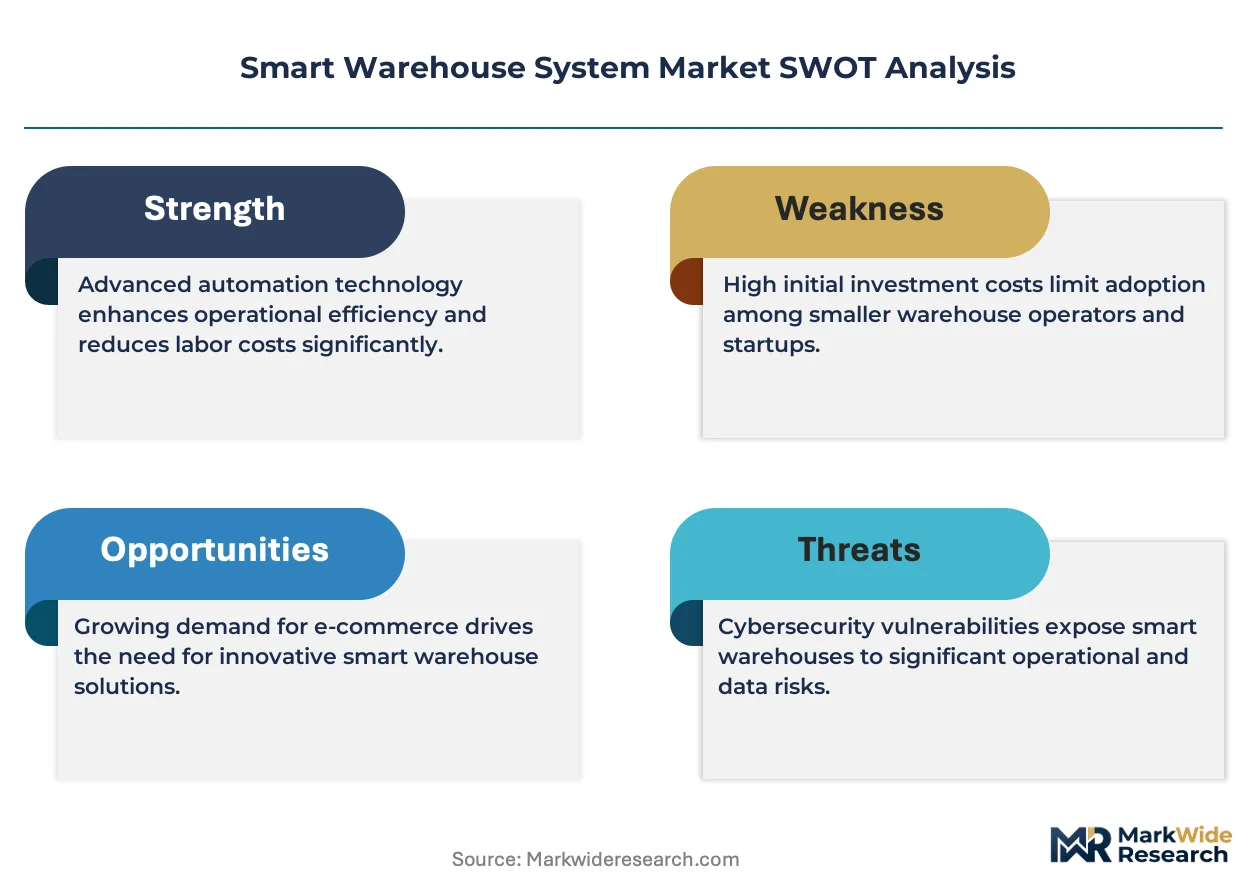
Labor scarcity across developed economies is compressing deployment timelines for autonomous material handling systems as e-commerce fulfillment networks race to automate before peak season capacity constraints.
Growth Catalysts
- OSHA collaborative robot safety protocols:Clarified human-robot interaction standards in the United States are accelerating AMR deployment timelines in distribution centers previously stalled by liability uncertainty.
- Pharmaceutical cold chain expansion:Temperature-controlled biologics distribution is driving demand for automated storage and retrieval systems with environmental monitoring capabilities.
- Lithium-ion powertrain maturation:Energy density improvements and faster charging cycles are eliminating the operational downtime that constrained earlier generation AGV fleets.
Market Restraints
- Steel and rare earth input volatility:Permanent magnet costs for robotic actuators fluctuate with Chinese export quota policies, compressing hardware margins unpredictably.
- CE marking timeline fragmentation:Divergent national implementation schedules for the EU Machinery Directive across member states delay cross-border equipment standardization.
- Conveyor system substitution:Modular AMR fleets are displacing fixed infrastructure investments in greenfield facilities, stranding incumbent sortation equipment suppliers.
Strategic Opportunities
- India warehouse automation:The PLI scheme for logistics infrastructure is creating first-mover advantages for system integrators establishing local assembly capacity.
- 5G private network convergence:Ultra-reliable low-latency communication is enabling real-time coordination between autonomous vehicles and warehouse execution software.
- Reverse logistics automation:Returns processing complexity in apparel and electronics is driving demand for robotic depalletizing and inspection systems.
Industry Challenges
- Automation technician scarcity:Mechatronics maintenance skills lag installed base growth in Germany and the United States, extending mean time to repair.
- WMS-ERP integration complexity:Legacy enterprise resource planning architectures require custom middleware development, inflating project risk and timeline overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Warehouse System Market |
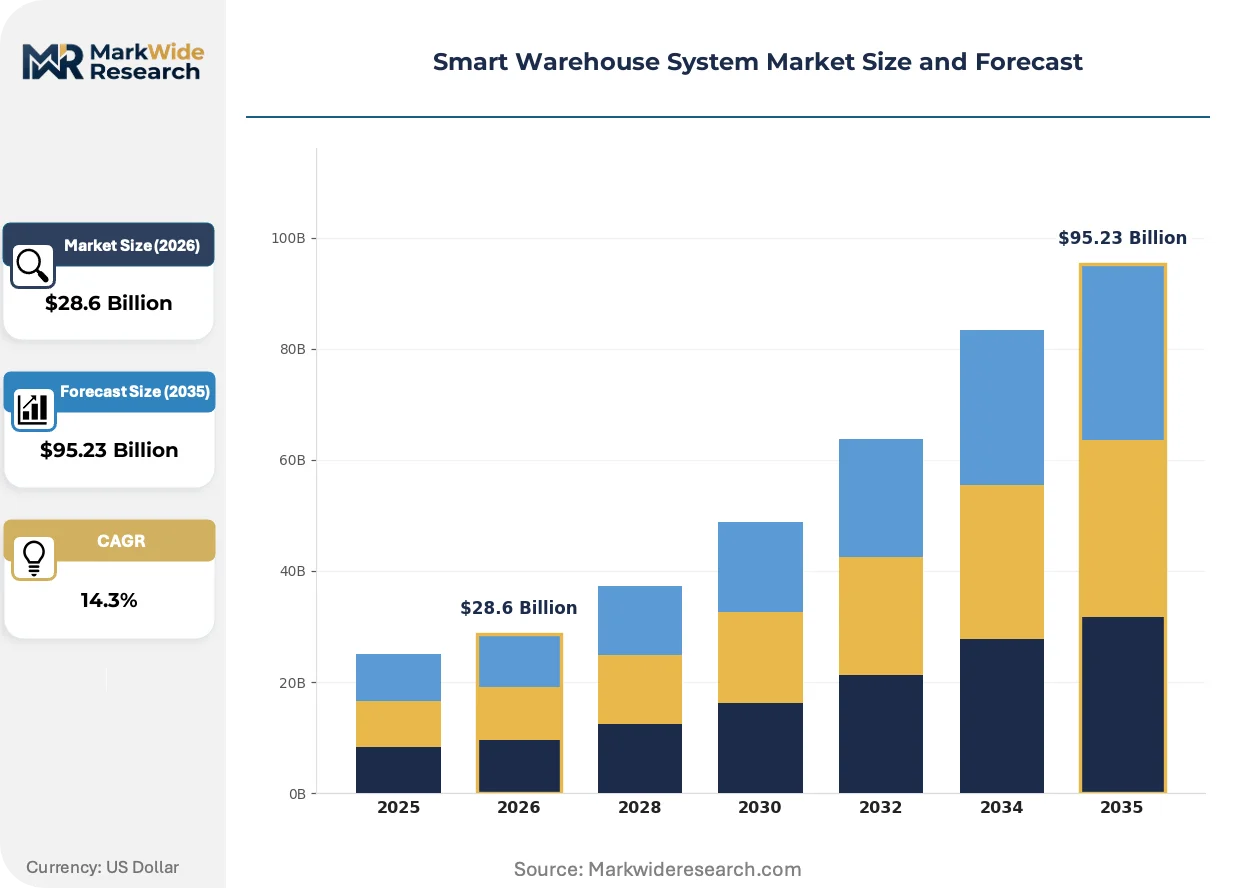
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $95.23 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Guided Vehicles, Robotics, IoT Sensors, Warehouse Management Systems Application: Inventory Management, Order Fulfillment, Shipping Optimization, Asset Tracking End User: E-commerce, Third-party Logistics, Retail, Manufacturing Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Dematic, SSI Schaefer, Daifuku, Körber, Blue Yonder, Manhattan Associates, Honeywell Intelligrated, SAP SE, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Warehouse System Market Evolving Landscape
Warehouse automation architecture is shifting from monolithic systems toward modular, software-defined orchestration layers that decouple hardware procurement from operational logic.
Computer vision-based piece-picking is decomposing the traditional zone-picking labor model in e-commerce fulfillment. Direct-to-consumer retailers are deploying robotic arms with suction and gripper arrays at throughput rates matching human pickers. This capability is decomposing the capital intensity barrier that previously restricted full automation to pallet-scale operations.
REACH substance restrictions and RoHS compliance deadlines are forcing redesigns of sensor housings and cable assemblies in robotic systems destined for European distribution networks. Manufacturers are substituting halogen-free flame retardants and lead-free solder formulations to maintain market access. German automotive parts distributors are advancing certification timelines by twelve to eighteen months to secure preferred supplier status.
Third-party logistics providers are unbundling automation-as-a-service from traditional facility management contracts, transferring capex risk to technology vendors. Retailers with seasonal demand volatility are favoring opex-based robotic fleet subscriptions over owned infrastructure. This model is gaining strongest traction in the United States among mid-market apparel and consumer electronics fulfillment operations.
Smart Warehouse System Market Segmentation
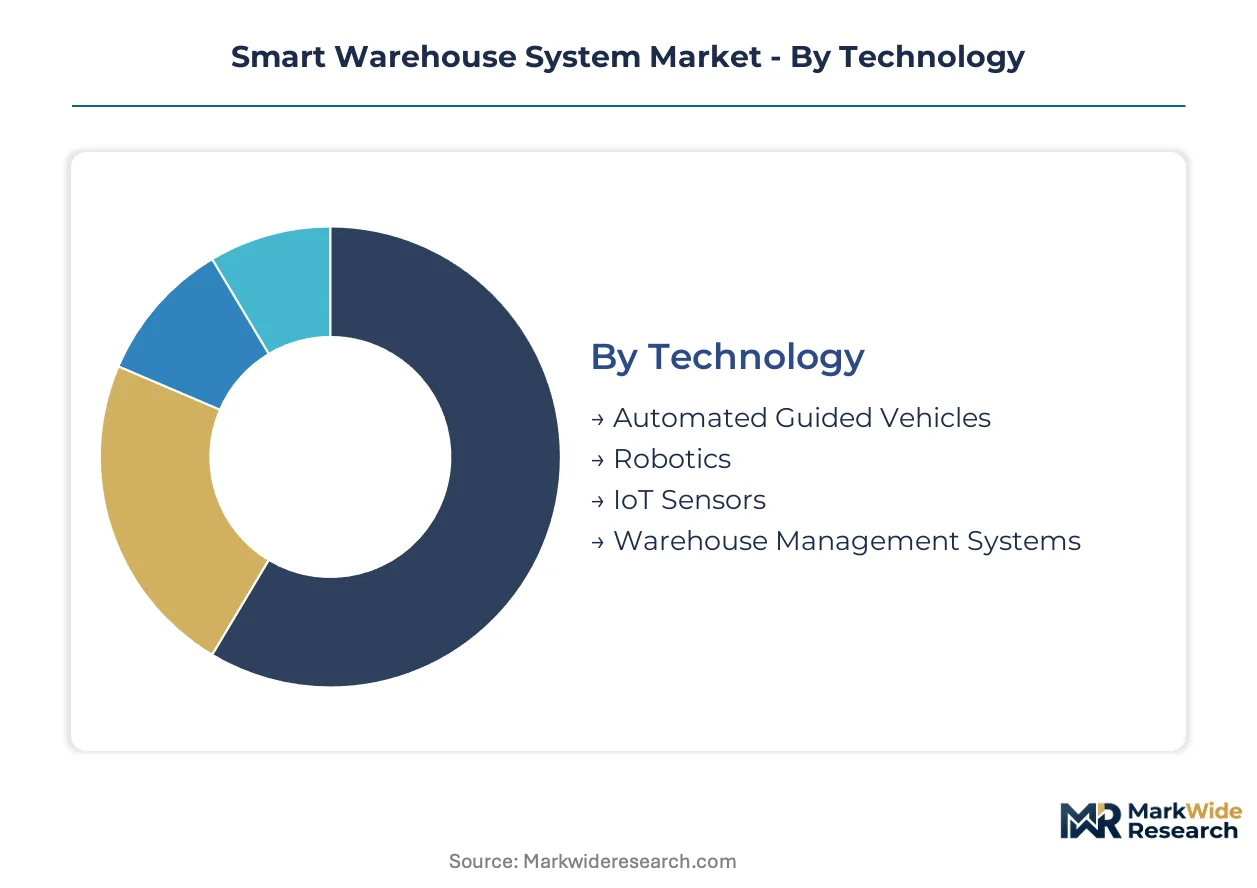
Smart warehouse system procurement varies sharply by operational scale and regulatory exposure. Technology choices determine compliance pathways, while service models shift capital structures between balance sheet and operating expenditure.
Technology:
OSHA collaborative robot protocols and EU Machinery Directive CE marking timelines differentiate deployment feasibility across hardware categories.
- Warehouse Management Systems:Software architectures orchestrate data flows between ERP layers and automation hardware with sub-second latency requirements. Pharmaceutical distributors in Germany prioritize WMS with embedded environmental monitoring to satisfy EMA cold chain documentation rules.
- Automated Guided Vehicles:Lithium-ion powertrains and AI-based navigation compress deployment timelines from months to weeks. E-commerce fulfillment centers in the United States are expanding AGV fleets ahead of peak season capacity constraints.
- Robotics:Piece-picking arms with computer vision operate at throughput rates matching human pickers in ambient-temperature environments.
- IoT Sensors:Real-time location systems with UWB and RFID track inventory at pallet and item level.
Warehouse Management Systems handle the majority of throughput; Automated Guided Vehicles are gaining share fastest.
Application:
Cost tier differentiation separates high-velocity operations from compliance-heavy workflows.
- Order Fulfillment:Direct-to-consumer picking workflows integrate robotic arms with conveyor sortation to achieve rates exceeding 1,000 picks per hour. Apparel retailers in the United States favor modular automation-as-a-service models to match seasonal demand volatility.
- Inventory Management:Automated storage and retrieval systems with environmental monitoring serve temperature-controlled biologics distribution. Pharmaceutical manufacturers in Germany retrofit legacy facilities to meet EMA serialization requirements.
- Shipping Optimization:Dynamic cartonization algorithms reduce dimensional weight charges in parcel networks.
- Asset Tracking:RTLS deployments monitor returnable transport item utilization across distributed fulfillment networks.
Order Fulfillment commands the largest installed base; Inventory Management is climbing fastest on regulatory pressure.
End User:
Customer type determines capex appetite and integration complexity tolerance.
- E-commerce:Direct-to-consumer retailers deploy modular robotic fleets with subscription-based financing to avoid owned infrastructure. Peak season capacity constraints drive compressed deployment timelines ahead of holiday volume.
- Third-party Logistics:Multi-tenant facilities require WMS architectures that segregate client data while sharing automation hardware. 3PLs in the United States unbundle automation-as-a-service from traditional facility management contracts.
- Retail:Brick-and-mortar networks retrofit regional distribution centers with AGV fleets for store replenishment.
- Manufacturing:Automotive parts distributors in Germany advance certification timelines to secure preferred supplier status under REACH and RoHS deadlines.
E-commerce accounts for the dominant share of new deployments; Third-party Logistics is expanding most quickly on opex-model adoption.
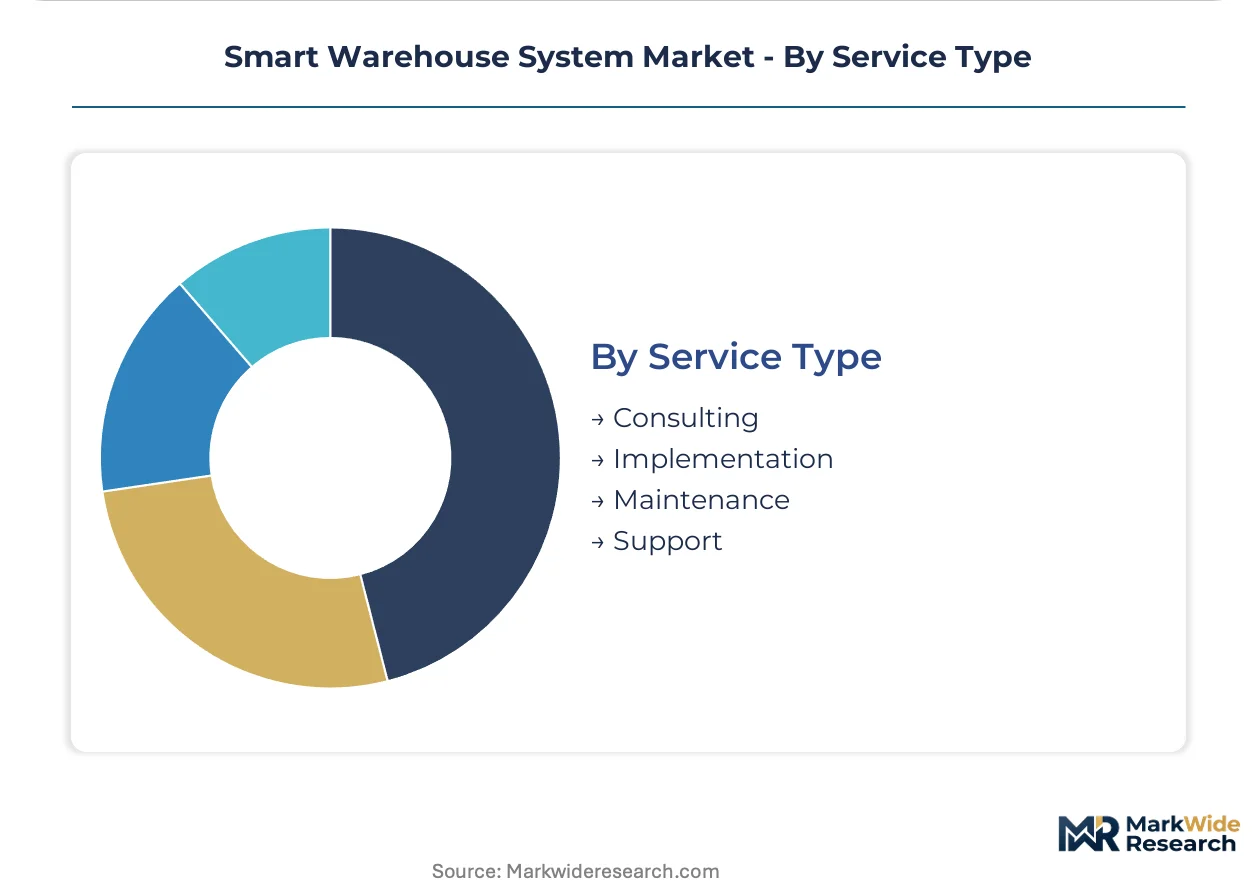
Service Type:
Margin concentration follows technical complexity and recurrence predictability.
- Implementation:System integration projects encompass mechanical installation, software configuration, and commissioning. Custom middleware development for WMS-ERP integration inflates timeline risk and project overruns.
- Maintenance:Mechatronics technician scarcity in Germany and the United States extends mean time to repair. Predictive maintenance contracts with spare parts provisioning command premium pricing.
- Consulting:Warehouse design and automation roadmapping engagements precede capital commitment decisions.
- Support:Help desk and software update services provide recurring revenue streams with high renewal rates.
Maintenance generates the steadiest recurring revenue; Implementation captures the largest project value per engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies, with the United States prioritizing e-commerce velocity while Germany emphasizes pharmaceutical compliance and China scales domestic automation platforms under MIIT guidelines.
United States
E-commerce fulfillment networks dominate procurement, with lithium-ion AGV fleets expanding ahead of peak season capacity constraints. OSHA collaborative robot safety protocols clarified human-robot interaction standards, accelerating AMR deployment timelines previously stalled by liability uncertainty. The Midwest distribution corridor spanning Ohio and Illinois anchors retrofit activity for automotive and consumer electronics warehouses.
Germany
Automotive and pharmaceutical manufacturers drive demand for automated storage and retrieval systems with environmental monitoring capabilities. REACH substance restrictions and RoHS compliance deadlines force redesigns of sensor housings and cable assemblies, advancing certification timelines by twelve to eighteen months. The Baden-Württemberg automotive cluster and Bavarian pharmaceutical corridor concentrate retrofit investment in legacy facilities.
China
Domestic e-commerce platforms scale warehouse automation under GB standards and MIIT guidelines for industrial internet platforms. Dual carbon goals accelerate lithium-ion powertrain adoption in AGV fleets, displacing lead-acid alternatives. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate system integrator activity for export-oriented fulfillment networks.
India
The PLI scheme for logistics infrastructure creates first-mover advantages for system integrators establishing local assembly capacity. BIS certification requirements for connected warehouse equipment shape procurement specifications for domestic fulfillment networks. The Maharashtra and Gujarat industrial corridors attract automation deployment for pharmaceutical and automotive parts distribution.
Japan
Precision manufacturing and semiconductor supply chains drive demand for high-accuracy inventory tracking systems. METI industrial automation guidelines influence procurement standards for human-robot collaboration zones. The Chubu region around Nagoya and the Kanto manufacturing belt concentrate deployment of robotic piece-picking systems for electronics fulfillment.
Smart Warehouse System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with software-centric providers and hardware manufacturers competing on divergent margin structures. The upper tier commands project value through captive control over critical subsystems, while specialists carve position through narrow technical excellence in navigation algorithms or gripper mechanics. Two archetypes dominate: vertically integrated system houses with in-house production of conveyors and storage racks, and software-native platforms that orchestrate heterogeneous hardware fleets. Competitive moves center on strategic partnerships between automation hardware vendors and cloud infrastructure providers, plus geographic expansion through local assembly joint ventures in high-growth markets.
Among integrated system houses, Dematic and Daifuku exemplify the hardware-centric archetype with deep backward integration into automated storage and retrieval manufacturing. Manhattan Associates occupies a position within the software-native tier, anchoring warehouse execution through data orchestration layers that connect upstream ERP systems to downstream automation. SSI Schaefer represents the European specialist model, sitting within the mid-tier segment with concentrated strength in conveyor and sortation engineering for high-throughput distribution environments.
| Leading Market Players |
|---|
| Dematic |
| SSI Schaefer |
| Daifuku |
| Körber |
| Blue Yonder |
| Manhattan Associates |
| Honeywell Intelligrated |
| SAP SE |
| Oracle Corporation |
| Others |
Value Network & Pricing Analysis
Project-based system integration contracts lock in multi-year supply commitments for German automotive and pharmaceutical buyers, anchoring price visibility against rare earth magnet volatility while transferring commissioning risk to integrators. This structure concentrates procurement leverage among vertically integrated system houses with captive component supply.
Pricing Analysis
Project-based contracts dominate smart warehouse system procurement, with pricing stratifying across premium CE-certified, standard OSHA-compliant, and economy non-certified tiers. Price differentiation rests on certification grade and software integration depth, with pharmaceutical cold chain deployments commanding premiums for environmental monitoring capabilities. Cost compression in economy-tier hardware is intensifying because Chinese rare earth export quotas destabilize permanent magnet costs. Third-party logistics providers exhibit highest price sensitivity due to opex-model fleet subscriptions, while pharmaceutical manufacturers prioritize compliance over unit economics.
Supply Chain Analysis
Strategic stockpiling of lithium-ion battery cells and rare earth magnets supersedes just-in-time preferences as Chinese export policies inject procurement uncertainty. Hardware manufacturing concentrates in China, Germany, and Japan, with robotic actuators and sensor assemblies drawing from Taiwanese semiconductor foundries and South Korean battery cell suppliers. Single-source vulnerability in permanent magnet supply chains threatens production continuity for AGV motor assemblies. Distribution runs through regional system integrator networks with localized commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart warehouse system markets reward defensive moats built on regulatory entrenchment, where CE marking and OSHA certification timelines create sticky customer relationships that resist displacement.
For Market Incumbents: Compound certification advantages by accelerating REACH and RoHS compliance roadmaps ahead of competitor timelines, securing preferred supplier status with German automotive distributors. Deepen backward integration into lithium-ion powertrain assembly to offset rare earth cost volatility threatening hardware margins. Lock in multi-year automation-as-a-service contracts with US-based third-party logistics providers before modular AMR fleets mature.
For New Entrants and Emerging Players: CE marking fast-track programs for collaborative robot systems open immediate access to German pharmaceutical and automotive retrofit opportunities stalled by incumbent certification backlogs. White-space concentration exists in Indian warehouse automation under PLI scheme incentives, where local assembly joint ventures circumvent BIS certification delays. Target reverse logistics automation for apparel returns processing, where robotic depalletizing demand outpaces specialist supply.
For Investors and Strategic Acquirers: Software-native orchestration platforms with proven ERP integration capabilities represent the highest-conviction acquisition archetype as WMS-ERP middleware complexity inflates project risk for hardware-centric competitors. Long-term viability favors vendors with recurring maintenance revenue streams over pure implementation plays. Watch 5G private network deployment velocity as inflection signal for real-time coordination software adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Joint Venture | PLI scheme compliance in India secures first-mover positioning against delayed BIS certification timelines. |
| Software-Native Platform Integration | WMS-ERP middleware capabilities reduce project overrun risk in pharmaceutical cold chain deployments. |
| CE Marking Acceleration Program | Twelve-month certification advance secures preferred supplier status with German automotive distributors. |
| Automation-as-a-Service Launch | Opex-based fleet subscriptions capture mid-market US apparel retailers with seasonal demand volatility. |
| Predictive Maintenance Contract Expansion | Mechatronics technician scarcity in Germany commands premium pricing for spare parts provisioning. |
Research Methodology
The analysis maps warehouse management systems, automated guided vehicles, robotics, and IoT sensor networks, each validated through automation engineers, warehouse operations directors, system integrator project managers, and pharmaceutical supply chain executives. Primary interview findings triangulate against customs trade data, OSHA regulatory filings, EU Machinery Directive implementation schedules, and SEC disclosures from publicly traded automation vendors. Bottom-up installation base estimates reconcile with top-down market sizing across hardware and software revenue pools.
Consistency checks validate projection outputs against lithium-ion powertrain adoption curves, e-commerce fulfillment center buildout announcements, and pharmaceutical cold chain capacity expansion plans. Segmentation models incorporate technology type, application workflow, end-user industry, and service delivery model across the projection horizon. CAGRs derive from installed base growth rates, replacement cycles, and greenfield automation penetration patterns in automotive and pharmaceutical verticals.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth, stable rare earth supply, or clarified OSHA collaborative robot protocols would require recalibration. Forecasts reflect assumptions on technician labor availability, certification timeline convergence, and 5G private network deployment velocity. Revision becomes warranted when lithium-ion cell supply constraints or EU Machinery Directive implementation delays cross thresholds that compress deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Machine Control System Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Multi-Axis Motion Controller Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Smart Manufacturing Market
Industrial Automation
Smart Industries Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Port Equipment Automation Market