
 United Kingdom Factory Automation and Industrial Control Systems Market | 2026-2036
United Kingdom Factory Automation and Industrial Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Factory Automation and Industrial Control Systems Market Analytics
Carbon-fiber-reinforced polymers are expanding their presence in robotic arm construction, displacing conventional aluminum alloys in high-payload automation cells. Siemens AG leverages deep R&D investment to anchor its position in motion-control systems for precision assembly. ABB Ltd. competes through specialized collaborative robot platforms targeting small-batch pharmaceutical operations. Honeywell International Inc. dominates distributed control system deployments across UK petrochemical facilities.
Factory automation and industrial control systems encompass programmable logic controllers, sensors, actuators, and supervisory software that orchestrate manufacturing processes with millisecond-level precision and sub-micron repeatability. These systems execute closed-loop feedback control to optimize throughput, minimize defect rates, and enforce safety interlocks across continuous and discrete production environments. Industrial robots represent the fastest-expanding product category as UK automotive and electronics producers retool for electric-vehicle component manufacturing and semiconductor packaging. Process automation applications command the deepest margin pools due to long replacement cycles and stringent validation requirements in pharmaceutical and food-processing installations.
The Health and Safety Executive enforces machinery safety standards through PUWER and LOLER regulations, compelling control system upgrades with integrated functional-safety architectures. BSI certification requirements for electromagnetic compatibility and cybersecurity resilience shape procurement specifications across UK industrial buyers. The Environment Agency's emissions monitoring mandates drive adoption of intelligent sensor networks with real-time data logging capabilities. Stakeholders must weigh capital deployment timing against evolving carbon-border adjustment mechanisms and the UK's accelerating grid decarbonization trajectory.
Market Dynamics
The UK's Net Zero Strategy and Industrial Decarbonisation Plan are forcing a wholesale replacement of legacy control architectures with energy-efficient, electrified automation stacks across England's manufacturing heartland.
Growth Catalysts
- Automotive retooling:Electric-vehicle component manufacturing is pulling robotic assembly lines into UK Midlands plants at unprecedented velocity.
- BSI cybersecurity mandates:Electromagnetic compatibility and resilience certification requirements are compelling control system upgrades across industrial buyers.
- Pharmaceutical validation:Stringent process automation requirements in drug manufacturing are deepening deployment of closed-loop sensor networks.
Market Restraints
- Semiconductor supply concentration:PLC and motion-controller chip sourcing remains concentrated in East Asian foundries, exposing UK integrators to input volatility.
- PUWER compliance costs:Machinery safety standards enforced by the Health and Safety Executive impose capital-intensive functional-safety architecture retrofits.
- Legacy protocol fragmentation:Proprietary fieldbus systems from 1990s deployments create interoperability barriers to unified control platforms.
Strategic Opportunities
- Scottish offshore wind:Turbine manufacturing clusters in Aberdeen and Glasgow present untapped demand for heavy-payload robotic handling systems.
- Carbon-border adjustment preparation:Emissions monitoring mandates from the Environment Agency are accelerating intelligent sensor network adoption with real-time data logging.
- Edge-AI convergence:On-device inference chips merging with traditional PLCs are opening predictive maintenance service models for small-batch producers.
Industry Challenges
- Controls engineering talent scarcity:Functional safety programming and IEC 61508 certification expertise remains concentrated among aging specialists in the West Midlands.
- Integration complexity:Brownfield sites in Birmingham and Coventry require phased migration paths that extend project timelines and strain systems integrator capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Factory Automation and Industrial Control Systems Market |
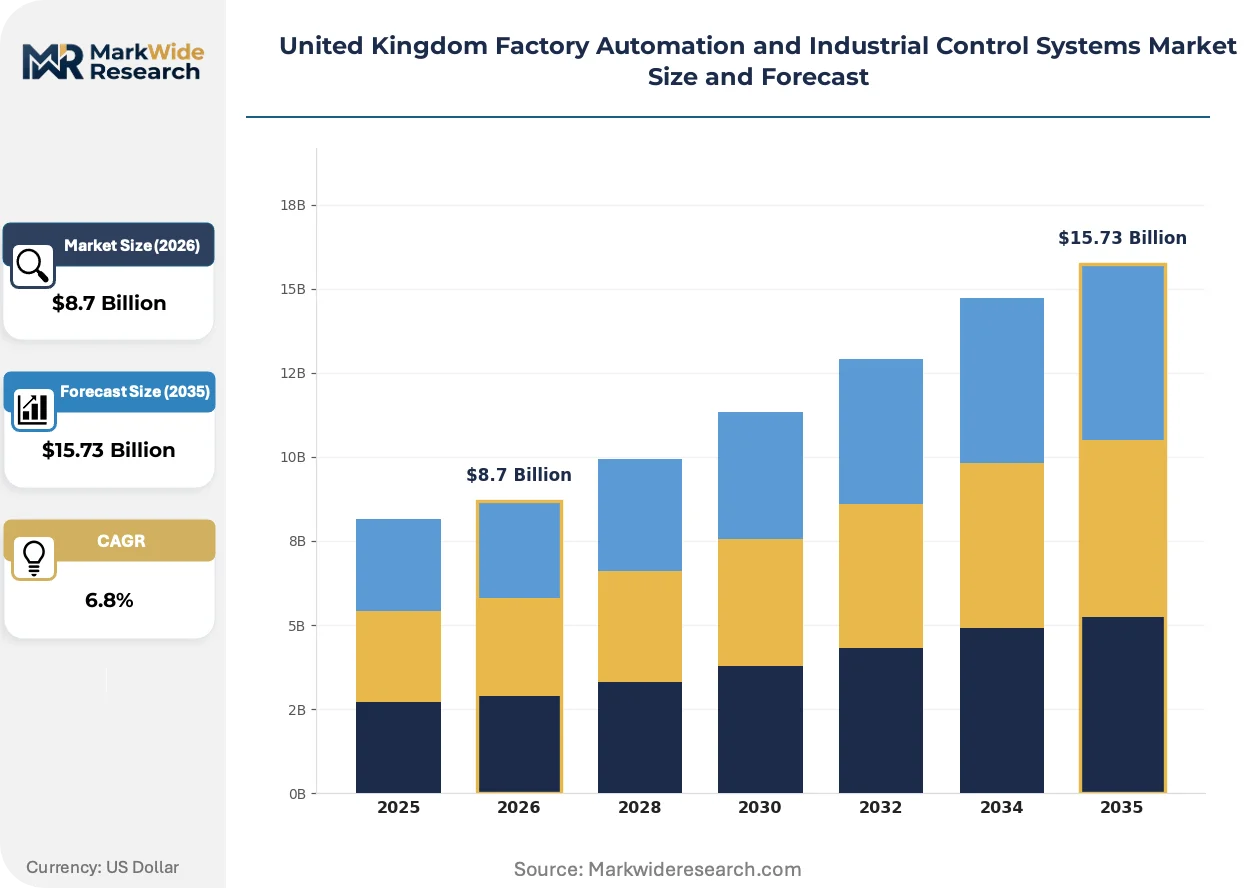
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Sensors, Industrial Robots, Human-Machine Interfaces Technology: IoT, AI, Machine Learning, Robotics Application: Manufacturing, Packaging, Quality Control, Process Automation End User: Automotive, Electronics, Food & Beverage, Pharmaceuticals |
| Companies Covered | Rockwell Automation, Inc., Honeywell International Inc., Siemens AG, Omron Corporation, Mitsubishi Electric Corporation, ABB Ltd., Emerson Electric Co., Yokogawa Electric Corporation, Schneider Electric SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Factory Automation and Industrial Control Systems Market Evolving Landscape
Control hardware architectures are fragmenting into interoperable subsystems as UK manufacturers demand flexibility without full platform replacement. This decomposition is reshaping vendor competitive dynamics across the Midlands corridor.
Software-defined safety controllers are modularizing traditional hardwired relay logic into reprogrammable, certified function blocks. Automotive Tier-1 suppliers in Derbyshire are piloting these systems for mixed-model EV battery assembly. This shift is modularizing safety system procurement from capital expenditure into subscription-based operational models.
The Environment Agency's emissions monitoring mandates are tightening data-logging requirements for industrial permit holders. Real-time sensor networks must now feed directly to regulatory portals with tamper-evident audit trails. Food-processing installations in Yorkshire are deploying blockchain-anchored data pipelines to satisfy these verification protocols.
Small-batch pharmaceutical manufacturers are unbundling after-sales service contracts from hardware procurement. These buyers now source maintenance expertise through specialist integrator networks rather than original equipment vendor agreements. This pattern is most pronounced in Cambridge-Oxford life sciences clusters where equipment diversity exceeds any single vendor's service coverage.
United Kingdom Factory Automation and Industrial Control Systems Market Segmentation
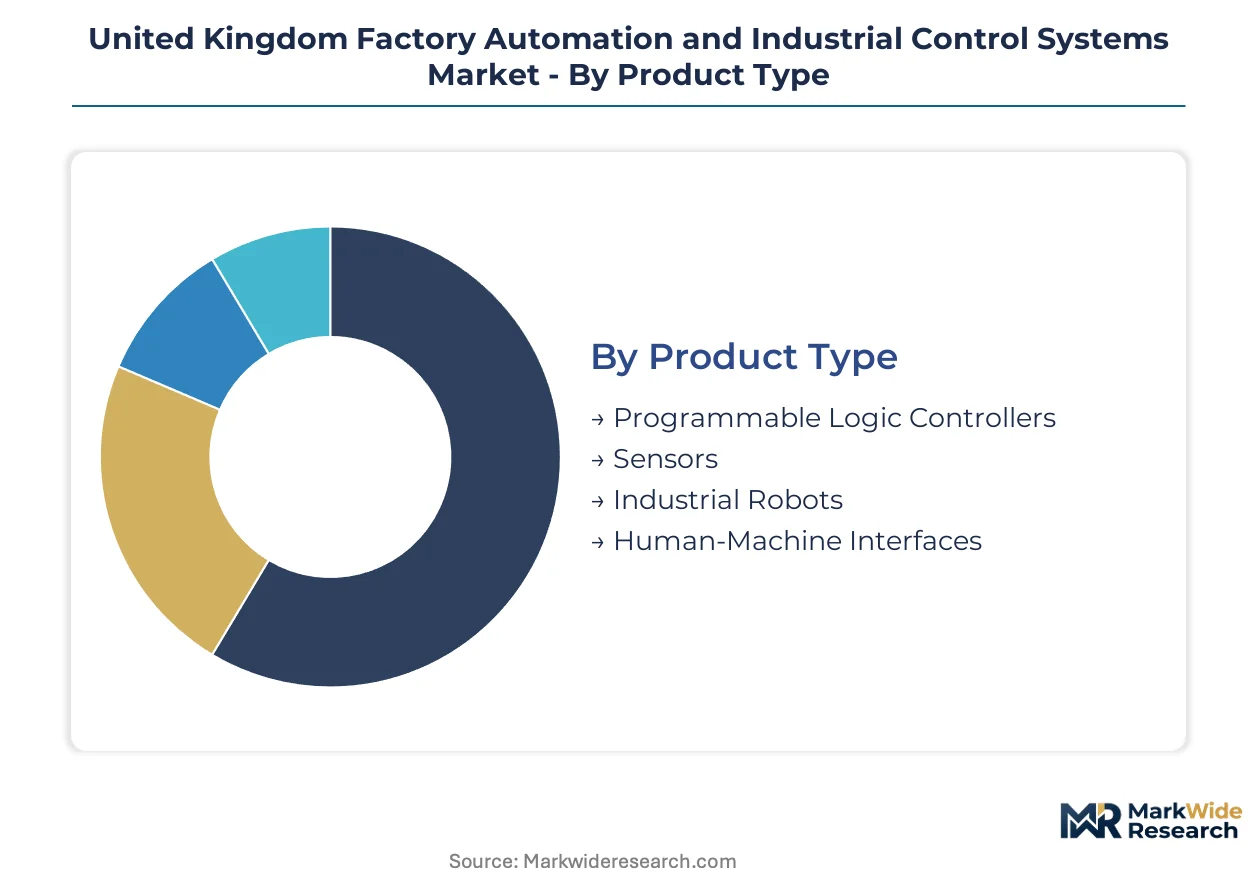
Segmentation reveals how automation investment concentrates across hardware layers, digital intelligence stacks, and vertical use cases. The UK's industrial base exhibits pronounced skew toward automotive electrification and pharmaceutical validation requirements, reshaping vendor priorities across the Midlands corridor.
Product Type:
Hardware specification tiers separate mission-critical motion control from peripheral sensing layers, with capital allocation shifting toward integrated mechatronic platforms.
- Programmable Logic Controllers:Ruggedized processors execute ladder logic and structured text with deterministic cycle times below 10 milliseconds. Automotive battery assembly lines in Derby and Coventry demand these units for synchronized multi-axis motion control under PUWER-mandated safety architectures.
- Industrial Robots:Six-axis articulated arms and SCARA configurations handle payloads from 3 kg to 1,000 kg with repeatability below 0.05 mm. Electric-vehicle retooling across Birmingham manufacturing clusters is accelerating deployment of carbon-fiber-reinforced polymer arm constructions for high-speed welding and battery module handling.
- Sensors:Photoelectric, inductive, and vision-based detection devices feed real-time process data to supervisory systems. Food-processing installations in Yorkshire deploy these for inline quality verification under Environment Agency emissions-logging mandates.
- Human-Machine Interfaces:Touch-panel and augmented-reality displays enable operator override and diagnostic access. Small-batch pharmaceutical producers in the Cambridge-Oxford corridor favor these for rapid recipe changeover in validated environments.
Industrial robots lead on scale; programmable logic controllers lead on momentum.
Technology:
Intelligence layers stack from connectivity infrastructure through predictive algorithms, with procurement patterns reflecting maturity gradients in industrial AI deployment.
- IoT:Edge gateways and protocol translators bridge operational technology networks to enterprise systems. Midlands automotive Tier-1 suppliers deploy these for over-the-air firmware updates across distributed press lines.
- AI:Machine-vision classification and anomaly detection algorithms reduce defect escape rates. Semiconductor packaging facilities in South Wales integrate these for die-placement verification.
- Machine Learning:Predictive models trained on historical failure patterns optimize maintenance scheduling. Petrochemical complexes on the Humber estuary apply these for pump vibration analysis under Honeywell DCS architectures.
- Robotics:Collaborative force-limiting systems and mobile autonomous platforms expand automation into previously manual workflows. Scottish offshore wind turbine manufacturing in Aberdeen tests heavy-payload variants for nacelle assembly.
IoT leads on scale; machine learning leads on momentum.
Application:
Process stage segmentation tracks where control system value concentrates, from discrete piece handling through continuous chemical transformation.
- Manufacturing:Discrete assembly, machining, and fabrication workflows dominate capital deployment. EV powertrain production in the West Midlands consumes the majority of UK robotic system shipments.
- Process Automation:Continuous flow control in chemical, pharmaceutical, and food processing commands premium margins. Stringent batch validation requirements deepen supplier relationships and extend replacement cycles.
- Packaging:End-of-line case packing, palletizing, and labeling systems integrate vision guidance for variable-format handling. E-commerce fulfillment growth drives refresh demand in East Midlands logistics hubs.
- Quality Control:Inline metrology and statistical process monitoring enforce specification compliance. Medical device manufacturers in the Southeast deploy coordinate measuring machines with automated probe changers.
Manufacturing leads on scale; process automation leads on momentum.
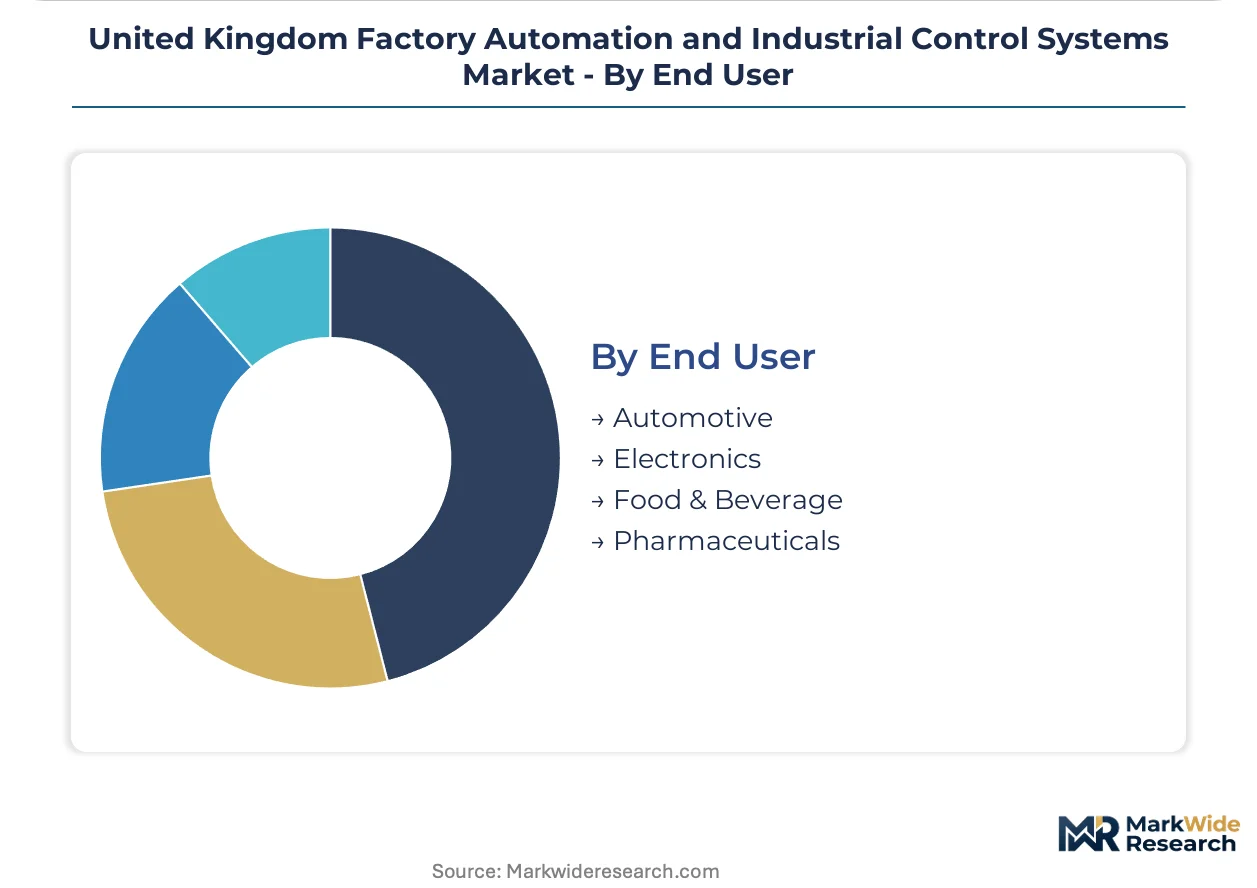
End User:
Vertical demand concentration reflects sector-specific regulatory pressures and capital availability across UK industrial geography.
- Automotive:OEM and Tier-1 electrification programs drive the largest absolute investment volumes. Battery gigafactory commitments in the Midlands and Northeast reshape supplier capacity planning.
- Pharmaceuticals:Sterile manufacturing and active ingredient synthesis require validated control architectures with full audit trails. MHRA inspection standards enforce upgrade cycles that sustain premium pricing.
- Electronics:Semiconductor packaging and printed circuit board assembly demand micron-level placement precision. Welsh fabrication facilities import specialized motion-control expertise.
- Food & Beverage:Hygienic design standards and allergen segregation protocols shape equipment specifications. Yorkshire dairy processors lead adoption of blockchain-anchored traceability systems.
Automotive leads on scale; pharmaceuticals leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midlands manufacturing corridor spanning Birmingham, Coventry, and Derby concentrates the majority of UK factory automation deployment. England's industrial heartland hosts battery gigafactory commitments and automotive Tier-1 retooling programs. Scotland and Wales present emerging demand vectors in offshore wind and semiconductor packaging respectively.
Midlands
Electric-vehicle powertrain production and battery module assembly drive robotic system procurement across Derbyshire and Coventry manufacturing clusters. The Health and Safety Executive enforces PUWER machinery safety standards that mandate functional-safety architecture upgrades. Birmingham automotive plants deploy carbon-fiber-reinforced polymer robotic arms for high-speed welding operations.
Southeast
Cambridge-Oxford life sciences clusters generate demand for validated process automation in small-batch pharmaceutical manufacturing. MHRA inspection standards enforce control system upgrade cycles with full audit trail requirements. Medical device manufacturers in the Southeast deploy coordinate measuring machines with automated probe changers for inline metrology.
Yorkshire and the Humber
Food-processing installations accelerate adoption of blockchain-anchored traceability systems under Environment Agency emissions-logging mandates. The Environment Agency's tamper-evident data pipeline requirements shape intelligent sensor network procurement. Dairy processors in Yorkshire lead deployment of hygienic design automation for allergen segregation protocols.
Scotland
Offshore wind turbine manufacturing in Aberdeen and Glasgow creates demand for heavy-payload robotic handling systems in nacelle assembly operations. The Scottish Government's renewable energy targets accelerate capital allocation toward electrified automation stacks. Aberdeen manufacturing clusters test collaborative robot platforms for wind tower component fabrication.
Wales
Semiconductor packaging facilities in South Wales import specialized motion-control expertise for micron-level die-placement verification. BSI electromagnetic compatibility certification requirements shape control system specifications for Welsh electronics producers. Welsh fabrication clusters integrate machine-vision classification systems for defect reduction in printed circuit board assembly.
United Kingdom Factory Automation and Industrial Control Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors position for EV battery manufacturing contracts and pharmaceutical validation requirements. The vendor base clusters around three tiers: diversified industrial conglomerates with full-stack portfolios, specialized motion-control specialists, and regional systems integrators with sector-specific expertise. Two strategic archetypes prevail—vertically integrated platform providers and niche collaborative robot developers. M&A activity and technology licensing agreements represent the primary competitive vectors as incumbents acquire edge-AI capabilities and predictive maintenance software assets.
Among diversified industrial conglomerates, Siemens AG and ABB Ltd. exemplify platform-scale positioning across motion-control and collaborative automation segments. Honeywell International Inc. occupies a distinct position in process automation deployments, particularly within petrochemical and pharmaceutical validation environments. These three anchors demonstrate how vendor archetypes map to sector-specific procurement patterns—Siemens toward precision assembly, ABB toward small-batch flexibility, and Honeywell toward continuous process control with stringent regulatory compliance requirements.
| Leading Market Players |
|---|
| Rockwell Automation, Inc. |
| Honeywell International Inc. |
| Siemens AG |
| Omron Corporation |
| Mitsubishi Electric Corporation |
| ABB Ltd. |
| Emerson Electric Co. |
| Yokogawa Electric Corporation |
| Schneider Electric SE |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up systems integrators across the West Midlands have consolidated fragmented service capabilities, tightening pricing discipline on project-based automation deployments while squeezing margin pools for standalone hardware vendors.
Pricing Analysis
Input-cost pass-through from semiconductor component shortages runs through motion-controller and PLC tier pricing, with East Asian foundry concentration amplifying volatility. Three-tier pricing structure across premium-certified, standard-compliant, and economy-unvalidated levels separates pharmaceutical-grade installations from general manufacturing. Cost compression in the economy tier is intensifying because Tier 2 automotive suppliers demand stripped-down control architectures for EV retooling. Small-batch pharmaceutical producers exhibit lowest price sensitivity due to MHRA validation requirements, while food-processing buyers in Yorkshire negotiate hardest on upfront capital.
Supply Chain Analysis
Motion-controller chip supply rests on Taiwanese and South Korean foundry capacity, with industrial sensor production concentrated in Germany and Japan. Carbon-fiber-reinforced polymers for robotic arm construction draw from Japanese specialty chemical producers, while rare-earth magnet sourcing for servo motors hinges on Chinese processing dominance. Single-source vulnerability in PLC processor fabrication exposes UK integrators to allocation risk during demand surges. Distribution runs through authorized distributor networks anchored by RS Components and specialist integrator channels serving the Midlands corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with electrification mandates and carbon-border preparation pulling procurement toward premium energy-efficient architectures.
For Market Incumbents: Deploy functional-safety certification as a retention moat against emerging Polish and Czech systems integrators bidding on Midlands automotive contracts. Deepen backward integration into edge-AI chip design to capture predictive maintenance service revenues from pharmaceutical small-batch producers. Channel control through exclusive distributor agreements in the Cambridge-Oxford corridor defends margin pools from hardware commoditization. For New Entrants and Emerging Players: Enter via Scottish offshore wind turbine manufacturing, where nacelle assembly automation remains underpenetrated by established Midlands-focused vendors. Target Aberdeen and Glasgow clusters with heavy-payload collaborative robot platforms certified for North Sea environmental conditions. A go-to-market angle through renewable energy EPC contractors bypasses incumbent distributor lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among regional systems integrators with sector-specific expertise in pharmaceutical validation, as financial buyers overlook replacement-cycle predictability. Long-term viability framing centers on decade-long service contract visibility from MHRA-mandated upgrade cycles. The signal to watch is Environment Agency emissions-logging mandate expansion beyond food processing into chemicals and metals.| Strategic Initiative | Industry Significance |
|---|---|
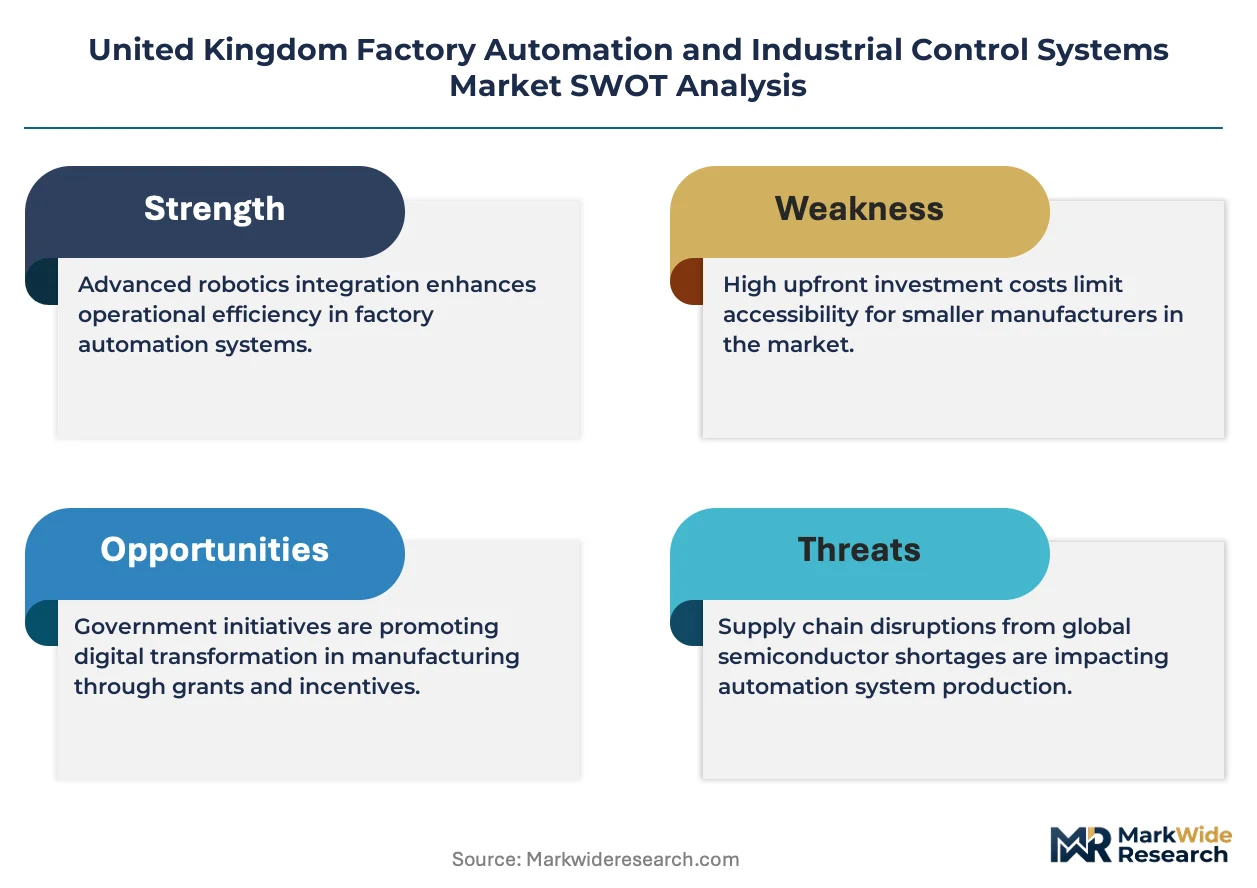
| Edge-AI Chip Integration | Merges predictive maintenance capabilities into traditional PLC architectures for pharmaceutical small-batch producers. |
| Functional-Safety Certification Investment | PUWER compliance creates barrier against low-cost Eastern European integrators in Midlands automotive. |
| Scottish Offshore Wind Partnership | Positions heavy-payload systems for Aberdeen nacelle assembly under government renewable targets. |
| Blockchain-Anchored Data Pipeline | Satisfies Environment Agency tamper-evident audit requirements for Yorkshire food-processing installations. |
| Collaborative Robot Platform Launch | Targets small-batch flexibility gaps in Cambridge-Oxford life sciences clusters beyond ABB coverage. |
Research Methodology
Coverage spans England's Midlands corridor, Southeast life sciences clusters, and Scottish offshore wind manufacturing, with primary inputs from each. The analysis combines interviews with plant engineers at automotive Tier 1 suppliers, procurement leads at pharmaceutical manufacturers, and aftermarket service heads at systems integrators. Secondary validation draws from Health and Safety Executive enforcement notices, Environment Agency emissions permit databases, and BSI certification registries. Bottom-up project pipeline tracking triangulates against top-down capital expenditure surveys across the analysis window.
Granularity-level modeling extends to product type, technology stack, application stage, and end-user vertical, with regional production cluster as an additional dimension. CAGRs derive from segment-level volume forecasts reconciled to aggregate market sizing. Industry-specific inputs include EV battery gigafactory commitment timelines and MHRA inspection frequency data for pharmaceutical validation cycles.
Inputs from Health and Safety Executive and Environment Agency regulatory filings were available through the study window; gaps in private capital expenditure plans at early-stage battery manufacturers introduce uncertainty bands around automotive segment projections. Forecasts reflect assumptions on semiconductor supply normalization and grid decarbonization trajectory. A small set of triggers—carbon-border adjustment mechanism finalization, Scottish renewable subsidy renewal, and PUWER enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Rotary Actuators Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Global SCADA Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Europe ICS Market