
 Model Based Manufacturing Technologies Market | 2026-2036
Model Based Manufacturing Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Model Based Manufacturing Technologies Market Outlook
Modular platform bundling is pivoting buyer choice away from standalone CAD licenses toward integrated simulation-to-production suites. Siemens leverages its digital thread architecture to anchor factory automation workflows across European and North American installations. PTC competes through its IoT-integrated PLM stack, while Dassault Systèmes differentiates via physics-based virtual twin environments that span design through service life.
Model Based Manufacturing Technologies comprise software and hardware systems that generate, validate, and execute production instructions directly from digital product models rather than paper-based drawings or manual programming, typically incorporating real-time sensor feedback loops and parametric design rules to synchronize engineering intent with shop-floor execution. Their primary purpose is eliminating translation errors between design and manufacturing while enabling continuous process optimization. Simulation and automation segments lead current revenue contribution, reflecting heavy investment in virtual commissioning and robotic workcell programming. Cloud-based deployment is expanding fastest as OEMs seek elastic compute for generative design workloads, though on-premise installations retain margin pools in defense and regulated medical device manufacturing where data sovereignty requirements predominate.
ISO 23247 digital twin framework, FDA 21 CFR Part 820 quality system regulation, and EU AI Act conformity assessment shape product validation requirements and market access conditions for model-based systems in regulated industries. The FDA's emerging guidance on predetermined change control plans for AI-enabled manufacturing software is creating new compliance architecture demands. Stakeholders must monitor how regulatory convergence between medical device and automotive software standards reshapes platform certification costs and competitive moats.
Market Dynamics
Digital twin validation protocols are compressing prototyping cycles across aerospace and automotive supply chains, forcing vendors to rearchitect software delivery around continuous compliance certification rather than discrete version releases.
Growth Catalysts
- EU AI Act conformity assessment:Mandated algorithmic transparency for production systems is accelerating investment in explainable simulation frameworks among medical device and automotive OEMs.
- Generative design workloads:Cloud-native elastic compute is expanding access to topology optimization tools previously restricted to aerospace primes with captive supercomputing infrastructure.
- Germany's industrial automation corridor:Co-development partnerships between automotive OEMs and machinery builders are creating reference architectures that propagate model-based workflows across Tier-2 and Tier-3 supplier networks.
Market Restraints
- Specialized simulation engineer scarcity:Talent pools for multiphysics modeling and parametric design rule authoring remain concentrated in Munich, Stuttgart, and Wolfsburg, constraining deployment velocity elsewhere.
- On-premise infrastructure lock-in:Defense and medical device manufacturers face data sovereignty requirements that prevent cloud migration, fragmenting vendor R&D investment across dual deployment stacks.
- Legacy CAD translation friction:Proprietary file formats from incumbent design platforms create interoperability barriers that inflate integration costs for mid-tier manufacturers.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Production-linked incentives for automotive and electronics sectors are attracting model-based technology vendors to establish local validation centers.
- Robotic workcell virtual commissioning:Convergence of real-time sensor feedback with physics-based simulation is opening service revenue streams in predictive maintenance and remote diagnostics.
- FDA predetermined change control plans:Emerging guidance on AI-enabled manufacturing software is creating first-mover advantages for platforms with built-in audit trail architectures.
Industry Challenges
- Multiphysics simulation expertise gaps:Shop-floor technicians lack training to interpret digital twin outputs, creating implementation bottlenecks that stall ROI realization.
- Cross-functional workflow redesign:Organizational silos between design engineering and production planning teams resist the collaborative restructuring that model-based systems require.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Model Based Manufacturing Technologies Market |
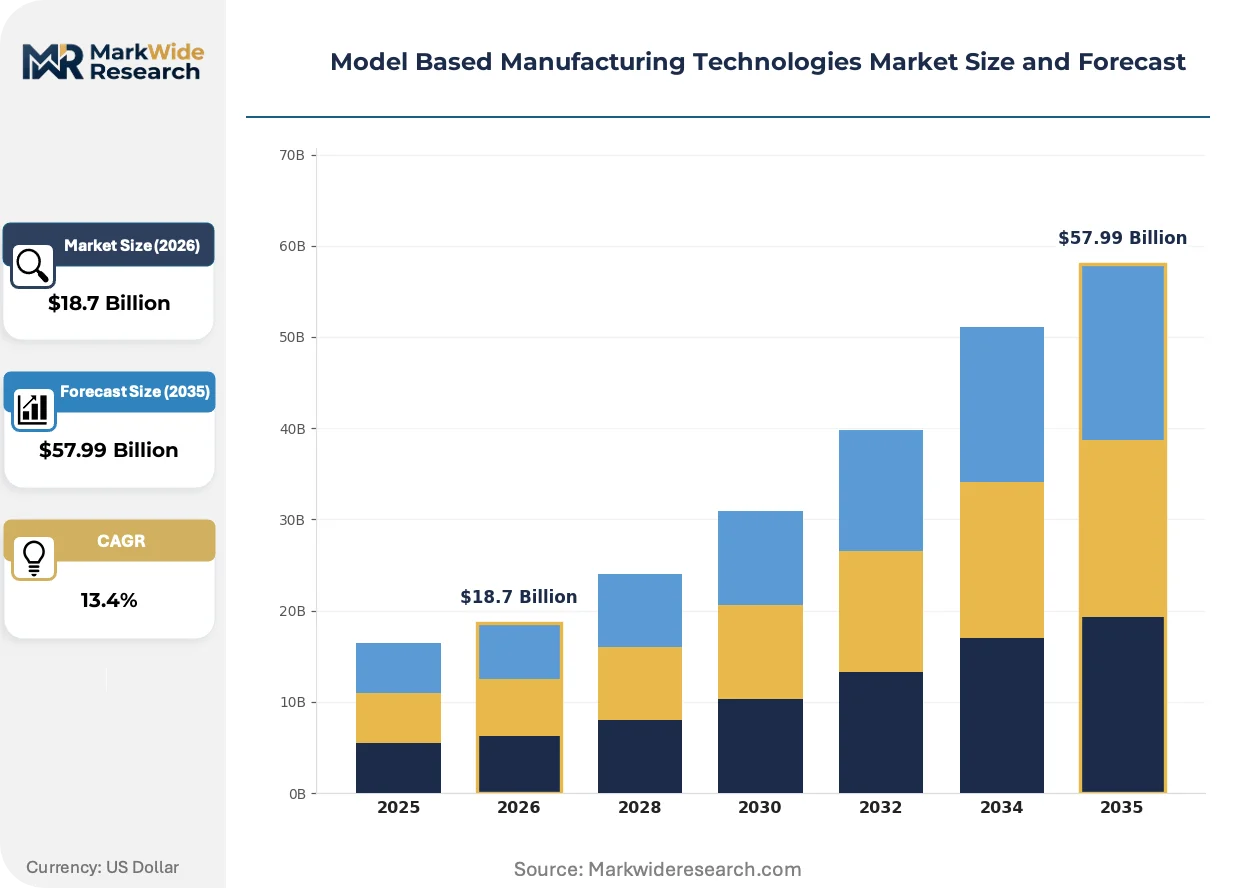
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Simulation, Visualization, Automation, Data Analytics End User: Aerospace, Automotive, Electronics, Consumer Goods Application: Product Design, Process Optimization, Quality Control, Supply Chain Management Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Siemens, PTC, Dassault Systèmes, SAP, Autodesk, Oracle, HCL Technologies, Rockwell Automation, Ansys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Model Based Manufacturing Technologies Market Strategic Shifts
Physics-based virtual environments are migrating from design validation into operational decision support, embedding simulation engines directly within manufacturing execution systems to enable real-time process adjustments.
Cloud-native generative design platforms are expanding into mid-market automotive and industrial machinery segments, compressing the traditional 18-month product development cycle into quarterly iteration sprints for chassis and powertrain components.
REACH substance restrictions and EU AI Act risk classification frameworks are forcing simulation vendors to embed materials compliance checking and algorithmic bias detection directly within model validation pipelines, with medical device manufacturers in Ireland and the Netherlands piloting integrated audit-ready workflows.
Subscription-based platform access is displacing perpetual licensing among machinery builders in Northern Italy and Southwest Germany, with vendors bundling simulation-to-production suites into outcome-aligned contracts that tie fees to measured throughput improvements rather than seat counts.
Model Based Manufacturing Technologies Market Segmentation
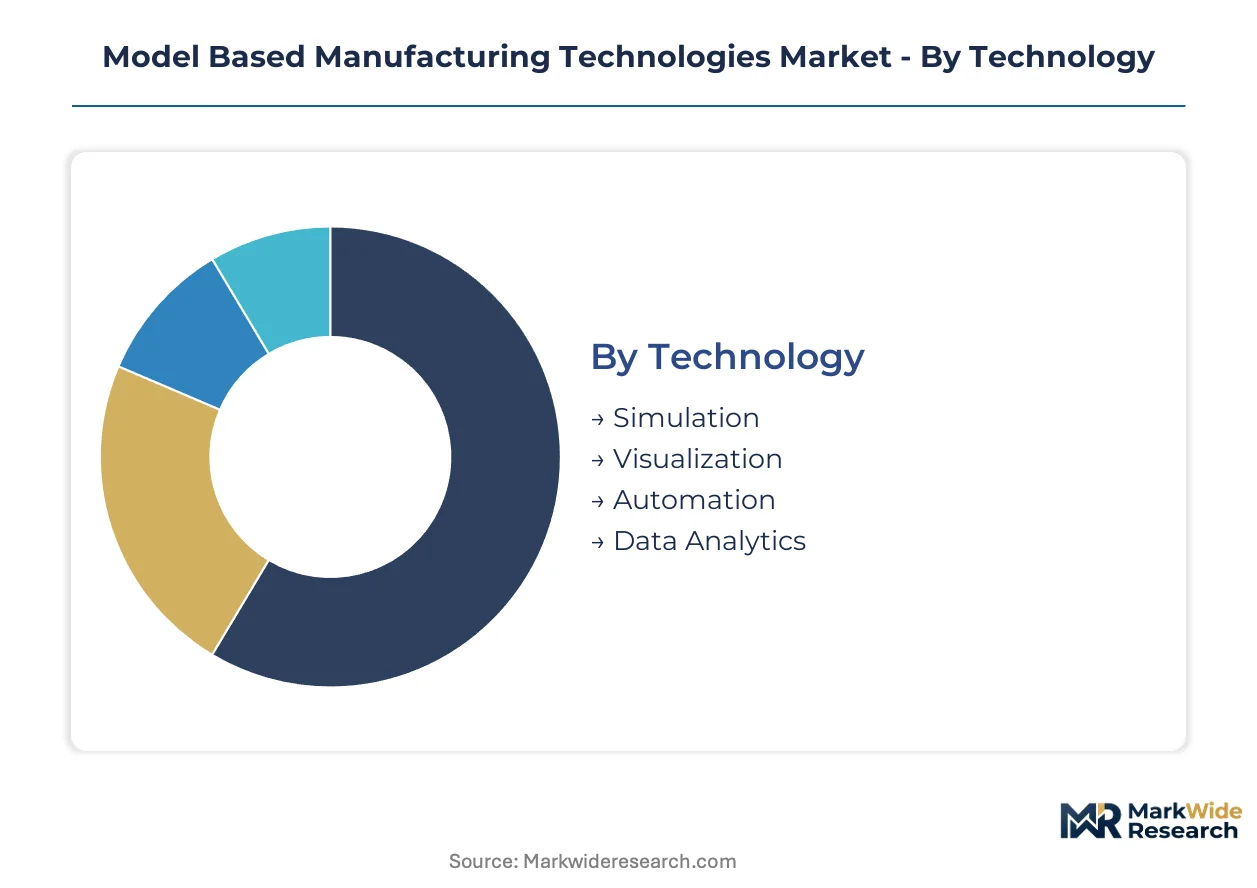
Technology choices in model-based manufacturing determine capital deployment patterns and compliance architectures. Segment boundaries increasingly blur as integrated platforms subsume discrete tool categories.
Technology:
Capital intensity peaks in multiphysics simulation infrastructure, where aerospace primes and automotive OEMs co-invest with vendors.
- Simulation:Multiphysics modeling engines validate structural, thermal, and fluid dynamics behaviors before physical prototyping. German automotive OEMs in Stuttgart and Wolfsburg anchor demand, driven by EU AI Act mandates for explainable algorithmic outputs in safety-critical components.
- Automation:Robotic workcell programming and virtual commissioning tools synchronize digital models with shop-floor execution. Ireland-based medical device manufacturers pilot these systems under FDA predetermined change control plans to compress validation timelines.
- Visualization:Immersive rendering environments accelerate design review cycles.
- Data Analytics:Real-time inference engines process sensor streams for predictive quality.
Most installed capacity flows through Simulation. Expansion is steepest in Automation.
End User:
Application complexity and regulatory burden vary sharply across buyer categories, reshaping vendor sales motion and support staffing.
- Aerospace:Digital twin validation for airframe and propulsion systems demands FAA-compliant traceability architectures. Boeing and Airbus tier-one suppliers in Toulouse and Hamburg drive cloud-native elastic compute adoption for generative design workloads.
- Automotive:Powertrain and chassis development cycles compress through physics-based virtual commissioning. Munich machinery builders co-develop reference architectures with OEMs that propagate to Tier-2 networks across Bavaria and Baden-Württemberg.
- Electronics:Miniaturization pressures force semiconductor packaging simulation at nanometer scales.
- Consumer Goods:Rapid SKU turnover favors modular, subscription-accessible platforms.
Automotive commands the largest deployment base. Aerospace posts the steepest expansion trajectory.
Application:
Functional use cases stratify by decision velocity, from months-long design cycles to millisecond-level process adjustments.
- Product Design:Parametric modeling and topology optimization embed manufacturing constraints at concept stage. Netherlands medical device firms integrate REACH substance checking directly within validation pipelines to preempt regulatory rejection.
- Process Optimization:Real-time simulation engines embedded in manufacturing execution systems enable adaptive parameter adjustment. Northern Italian machinery builders adopt subscription-based outcome-aligned contracts tied to throughput improvements.
- Quality Control:In-line metrology feedback loops close deviation detection to correction.
- Supply Chain Management:Digital thread visibility extends model fidelity to supplier tiers.
Process Optimization absorbs the majority of new investment. Product Design is climbing the fastest.
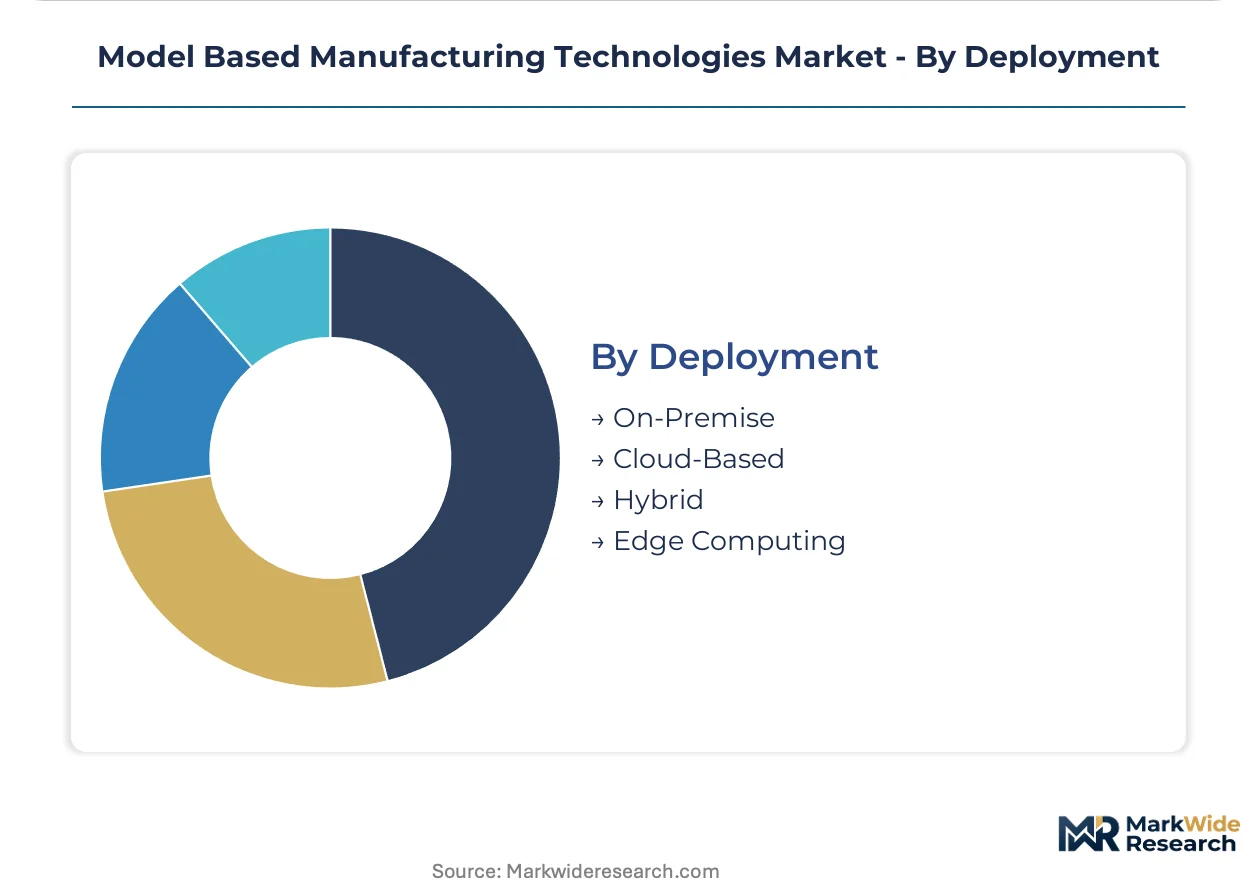
Deployment:
Data sovereignty requirements and latency sensitivity fragment infrastructure choices across regulated and performance-driven use cases.
- On-Premise:Captive compute clusters satisfy defense and medical device data residency mandates. FDA 21 CFR Part 820 quality system requirements prevent cloud migration for implantable device manufacturers in Massachusetts and Minnesota.
- Cloud-Based:Elastic provisioning supports generative design burst workloads previously restricted to aerospace primes with supercomputing access. India's PLI scheme beneficiaries in Tamil Nadu and Karnataka adopt these platforms without legacy infrastructure drag.
- Hybrid:Sensitive design data remains local while compute-intensive simulation offloads to cloud.
- Edge Computing:Sub-10ms latency requirements drive shop-floor inference deployment.
Hybrid architectures carry the heaviest current deployment load. Cloud-Based options are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Model-based manufacturing technologies trace their industrial lineage to post-war German automotive engineering, where parametric design methods first bridged drafting offices with shop-floor machining centers. Stuttgart's Mercedes-Benz and Wolfsburg's Volkswagen pioneered early digital prototyping workflows that now propagate globally through supplier networks and software licensing.
Germany
Automotive OEMs in Stuttgart, Munich, and Wolfsburg anchor European demand for multiphysics simulation suites. EU AI Act conformity assessments for algorithmic transparency in safety-critical components tighten vendor qualification requirements. The industrial automation corridor spanning Bavaria and Baden-Württemberg hosts co-development partnerships between machinery builders and tier-one suppliers that export reference architectures across Central Europe.
United States
Aerospace primes in Seattle and defense contractors across Massachusetts and Minnesota drive digital twin validation for airframe and propulsion systems. FDA 21 CFR Part 820 quality system regulations prevent cloud migration for implantable device manufacturers, preserving on-premise infrastructure margins. Boeing's tier-one supplier network in Wichita and Charleston accelerates elastic compute adoption for generative design workloads.
China
Electric vehicle manufacturers in Shanghai and Shenzhen compress powertrain development cycles through physics-based virtual commissioning. MIIT standards for intelligent manufacturing systems mandate model-based interoperability across state-owned enterprise supply chains. The Yangtze River Delta cluster around Suzhou and Hangzhou concentrates robotics workcell programming demand from automotive and electronics contract manufacturers.
India
Production-linked incentive beneficiaries in Tamil Nadu and Karnataka adopt cloud-native platforms without legacy infrastructure drag. BIS certification requirements for industrial automation equipment shape vendor localization strategies. Automotive OEMs in Pune and Chennai establish model-based validation centers to serve export markets under EU and Middle Eastern regulatory frameworks.
Japan
Precision machinery builders in Nagoya and Osaka integrate real-time sensor feedback with parametric design rules for tool and die manufacturing. METI's Society 5.0 roadmap funds digital thread implementations across SME supplier tiers. The Kanto region around Tokyo hosts convergence between semiconductor packaging simulation and automotive electronics miniaturization demands.
Model Based Manufacturing Technologies Market Competitive Environment
Premium-margin players sit above commodity-margin players across deployment architecture sophistication, with integrated digital thread suites commanding pricing multiples over standalone CAD or simulation modules. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive automation hardware, pure-play software platforms with IoT-integrated PLM stacks, and specialized multiphysics simulation houses. Dominant competitive moves include strategic partnerships between machinery OEMs and cloud infrastructure providers, plus portfolio diversification into outcome-aligned subscription contracts.
Within the diversified industrial tier, Siemens and Rockwell Automation represent archetypes of factory automation anchoring, while PTC exemplifies the IoT-integrated PLM specialist position. Dassault Systèmes occupies a distinctive niche in physics-based virtual twin environments that span design through service life. These three named entities collectively illustrate how vendor positioning stratifies between hardware-coupled workflow control and software-centric digital thread orchestration.
| Leading Market Players |
|---|
| Siemens |
| PTC |
| Dassault Systèmes |
| SAP |
| Autodesk |
| Oracle |
| HCL Technologies |
| Rockwell Automation |
| Ansys |
| Others |
Value Chain & Pricing Dynamics
EU AI Act algorithmic transparency mandates gate qualified supply access for simulation-to-production suites, with vendors embedding explainable model architectures commanding premium-tier pricing while non-compliant platforms face exclusion from automotive and medical device procurement pipelines in Stuttgart and Wolfsburg.
Pricing Analysis
Subscription-based outcome-aligned contracts dominate model-based manufacturing technology pricing, with Northern Italian machinery builders and Southwest German automotive suppliers adopting fees tied to measured throughput improvements rather than perpetual seat licenses. Price differentiation hinges on EU AI Act conformity certification tier and cloud-native elastic compute provisioning scale, with defense and medical device manufacturers absorbing on-premise infrastructure premiums due to FDA 21 CFR Part 820 data residency requirements. Cost compression runs through mid-market machinery segments as India's PLI scheme beneficiaries in Tamil Nadu and Karnataka access cloud platforms without legacy migration overhead. Tier-2 automotive suppliers exhibit highest price sensitivity, while aerospace primes in Toulouse and Hamburg prioritize traceability architectures over unit cost.
Supply Chain Analysis
Multiphysics simulation engineer scarcity in Munich, Stuttgart, and Wolfsburg constrains deployment velocity for model-based manufacturing systems across European automotive supply chains. Software development concentrates in Germany, the United States, and France, with hardware integration anchored in Japanese precision machinery clusters around Nagoya and Osaka. Raw material dependencies span high-performance computing silicon, industrial sensor arrays, and specialized visualization hardware. Single-source vulnerability persists in cloud infrastructure provisioning for generative design workloads. Distribution runs through direct vendor-OEM co-development partnerships in Germany's industrial automation corridor, with reference architectures propagating to Tier-2 and Tier-3 networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Model Based Manufacturing Technologies Market functions as a geographic-arbitrage play where India's PLI scheme production-linked incentives attract vendor validation center investment at roughly half the operational cost structure of equivalent EU facilities.
For Market Incumbents: Hedge against pure-play cloud-native entrants by embedding edge-computing inference engines within existing factory automation footprints, while securing backward integration into industrial sensor supply through partnerships with Japanese precision component manufacturers. Certification investment in FDA predetermined change control plan architectures creates switching costs among Massachusetts and Minnesota medical device manufacturers.
For New Entrants and Emerging Players: Enter via India's Tamil Nadu and Karnataka automotive corridors, where PLI scheme beneficiaries lack legacy CAD infrastructure and seek cloud-native simulation-to-production suites without migration friction. Target robotic workcell virtual commissioning for mid-tier electronics contract manufacturers in the Yangtze River Delta, positioning through outcome-based pricing tied to commissioning cycle reduction.
For Investors and Strategic Acquirers: Roll-up economics work for specialized multiphysics simulation houses because EU AI Act conformity assessment requirements are consolidating buyer preference around integrated audit-trail platforms rather than point-solution tools. Long-term viability centers on five-to-ten year digital thread architecture dominance. Acquisition target archetype: regional automation integrators with captive relationships to German automotive OEMs. The signal to watch is FDA guidance finalization on AI-enabled manufacturing software validation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Siemens leverages digital thread architecture to anchor factory automation workflows across European installations. |
| Regulatory Certification Investment | PTC's IoT-integrated PLM stack captures FDA predetermined change control plan demand from Ireland-based medical device manufacturers. |
| Geographic Expansion | Dassault Systèmes extends physics-based virtual twin environments through co-development partnerships in Germany's Baden-Württemberg corridor. |
| Acquisition of Specialist Firm | Consolidation of regional multiphysics simulation houses accelerates EU AI Act conformity assessment capability aggregation. |
| Strategic Partnership | Cloud infrastructure alliances with machinery OEMs in Northern Italy enable subscription-based outcome-aligned contract scaling. |
Study Parameters
Multiple input streams — structured interviews with digital twin platform engineers, manufacturing execution system integration specialists, and regulatory affairs directors at medical device and automotive OEMs — were reconciled against secondary validation from FDA 21 CFR Part 820 guidance documents, EU AI Act conformity assessment frameworks, SEC filings of publicly traded industrial software vendors, and production-linked incentive scheme disclosures from India's Ministry of Commerce. Bottom-up segment sizing across simulation, automation, visualization, and data analytics technology categories was triangulated with top-down market envelope checks derived from disclosed vendor licensing revenues and OEM digital transformation capex allocations.
Historical growth trajectories in aerospace digital twin adoption and automotive virtual commissioning deployment were cross-referenced against panel input from procurement directors at Boeing tier-one suppliers and Munich machinery builders to inform projection assumptions across the analysis window. Segmentation dimensions modeled encompass technology type, end-user industry, functional application, and deployment architecture, with additional stratification by regulatory compliance tier given FDA and EU AI Act divergence. CAGRs were derived from elasticity-adjusted adoption curves incorporating cloud-native generative design workload expansion and on-premise infrastructure persistence in defense and regulated medical device manufacturing.
Inputs from vendor financial disclosures, OEM digital transformation budget filings, and regulatory guidance documents were available through the study window; gaps in privately held mid-tier automation integrator revenue data introduce uncertainty bands around segment share estimates. Forecasts assume continued convergence between medical device and automotive software validation standards, with material deviation in FDA final guidance timing or EU AI Act enforcement intensity warranting pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
United States SCADA Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
Motion Control Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Intralogistics Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Programmable Automation Controller (PAC) Market